
 Canada Glass Bottles and Containers Market | 2026-2036
Canada Glass Bottles and Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Glass Bottles and Containers Market Outlook
Canada's single-use plastic bans is expanding the addressable market for glass packaging by eliminating competing substrates in food and beverage applications. Owens-Illinois Inc leverages its North American furnace network to sustain bulk supply contracts with major Canadian brewers. TricorBraun Canada differentiates through customized mold capabilities for craft distilleries and pharmaceutical clients. Pegasus Glass anchors its position in specialty pharmaceutical vials where borosilicate durability commands premium placement.
Canada glass bottles and containers comprise silica-soda-lime formulations formed through blow molding, pressing, or casting processes, typically achieving wall thicknesses of 3-8 mm and thermal shock resistance up to 42°C for standard flint glass. These vessels serve primarily as inert, impermeable barriers for oxygen-sensitive liquids and sterile formulations across food, beverage, and pharmaceutical supply chains. Blow molding dominates volume production for beverage bottles where throughput economics favor high-speed IS machine operations, while pressing commands structural jar applications in food packaging where heavier bases resist vacuum deformation. The below 250 ml capacity tier leads pharmaceutical vial demand driven by biologic injection volumes, though above 1 L formats are accelerating fastest in craft beverage bulk retail and food service condiment segments.
Health Canada governs pharmaceutical glass through its Therapeutic Products Directorate, while the Canadian Food Inspection Agency enforces food contact material safety under Division 23 of the Food and Drug Regulations; both frameworks elevate quality thresholds that favor established domestic suppliers over import alternatives. Environment and Climate Change Canada's plastic pollution regulations directly expand glass substitution opportunities by scheduled elimination of checkout bags, cutlery, and stir sticks, with extended producer responsibility frameworks in British Columbia and Ontario adding waste-diversion compliance costs to plastic competitors. Stakeholders must monitor provincial deposit-return expansion proposals and carbon border adjustment developments that could reshape cost competitiveness between domestic furnace production and imported container flows.
Market Dynamics
Health Canada's single-use plastic prohibitions are systematically eliminating competing substrates across food and beverage packaging, forcing a structural substrate shift toward glass that domestic furnace capacity must absorb or forfeit to import flows.
Growth Catalysts
- Deposit-Return Expansion:Ontario's proposed expansion of its deposit-return system to wine and spirits bottles would increase collection rates and closed-loop glass supply, directly benefiting domestic remelt economics.
- Carbon Border Adjustment Mechanism:Canada's developing carbon border framework will penalize imported container glass from jurisdictions with weaker emissions standards, tilting procurement toward domestic furnace production.
- Craft Beverage Premiumization:Small-batch distilleries and wineries across British Columbia and Quebec are specifying heavier base weights and custom mold designs that command price premiums over commodity formats.
Market Restraints
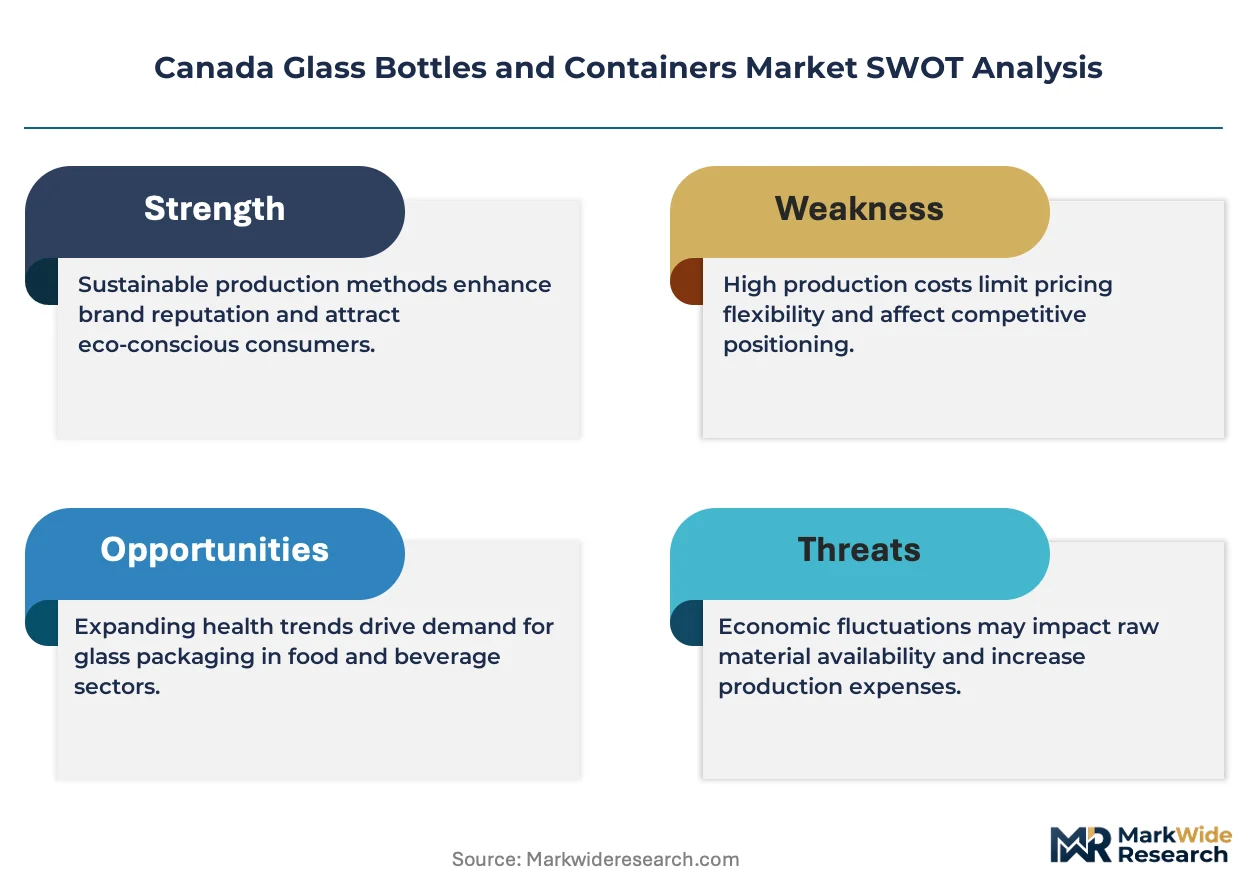
- Natural Gas Price Volatility:Furnace operations in Ontario and Quebec remain exposed to North American natural gas price swings that directly determine melting cost structures and margin stability.
- Import Concentration Risk:Lower-value commodity bottles for food service and industrial chemicals flow increasingly from US and Mexican furnace networks, constraining domestic volume growth in standardized formats.
- Weight Penalty in Distribution:Glass density imposes freight cost disadvantages against aluminum and PET alternatives in long-haul distribution to Western Canadian markets from Ontario production bases.
Strategic Opportunities
- Atlantic Canada Underpenetration:Nova Scotia and New Brunswick lack domestic furnace presence, creating white space for regional distribution partnerships or mini-furnace investments serving maritime beverage producers.
- Extended Producer Responsibility:British Columbia's advanced EPR framework rewards packaging with higher recycled content, positioning post-consumer cullet-fed production for preferential procurement.
- Pharmaceutical Serialization Convergence:Integration of track-and-trace serialization with anti-counterfeit glass marking creates differentiated vial offerings for biologic drug manufacturers.
Industry Challenges
- Furnace Rebuild Capital Intensity:Major furnace rebuilds require 18-24 month planning cycles and capital commitments exceeding $50 million, freezing strategic flexibility during demand uncertainty.
- Color-Sorting Contamination Control:Maintaining flint glass clarity requires rigorous separation of amber and green cullet streams, demanding investment in optical sorting infrastructure that smaller recyclers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Glass Bottles and Containers Market |
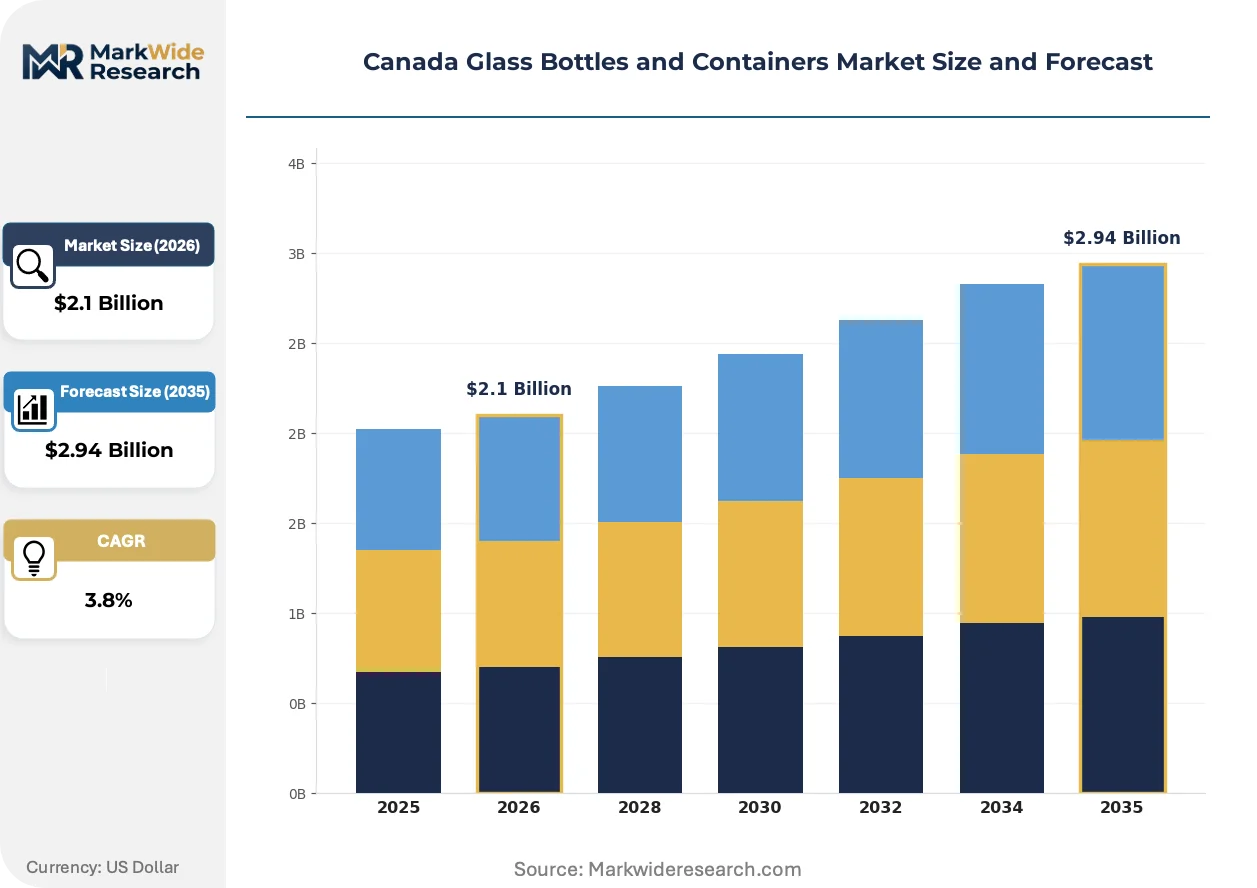
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blow Molding, Pressing, Casting, Injection Molding End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Capacity: Below 250 ml, 250 ml to 500 ml, 500 ml to 1 L, Above 1 L Packaging Type: Jars, Bottles, Vials, Containers |
| Companies Covered | TricorBraun Canada, Pegasus Glass, Owens-Illinois Inc, Stoney Creek Glass, United Bottles & Packaging, Richards Packaging Inc, Consolidated Bottle, Ampak Inc, Vitro Canada, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Glass Bottles and Containers Market Strategic Shifts
Active technological and regulatory forces are compressing production cycles while elevating quality thresholds across Canadian glass manufacturing, with implications for furnace economics and buyer-supplier relationships.
Lightweighting technology is rewriting competitive positioning in beverage packaging. Advanced thin-wall forming techniques now achieve 15-20% weight reduction in standard wine and spirits bottles without sacrificing vertical load strength. Molson Coors and Labatt are specifying these formats for domestic premium lines to offset freight cost penalties. The structural consequence is a compression in per-unit glass consumption that furnace operators must offset through volume gains or premium mix shifts.
Health Canada's Therapeutic Products Directorate is tightening pharmacopeial glass standards for parenteral packaging. The 2024 guidance on glass delamination risk assessment now requires documented surface chemistry testing for all new vial submissions. Parenteral drug manufacturers are responding by consolidating supplier bases to domestic borosilicate specialists with established regulatory dossiers. The compliance burden is accelerating qualification timelines and freezing out newer import entrants lacking Canadian regulatory history.
Consolidation in Canadian food retail is concentrating procurement power among Loblaw, Sobeys, and Metro. These chains are unbundling packaging specification from product manufacturing, creating direct relationships with container suppliers for private-label lines. The shift is most visible in Ontario's tomato processing and condiment sectors, where retailers now mandate specific lightweight jar formats across co-packer networks. Supplier qualification cycles have compressed from 24 months to 12 months, rewarding mold-flexible producers with faster turnaround capabilities.
Canada Glass Bottles and Containers Market Segmentation
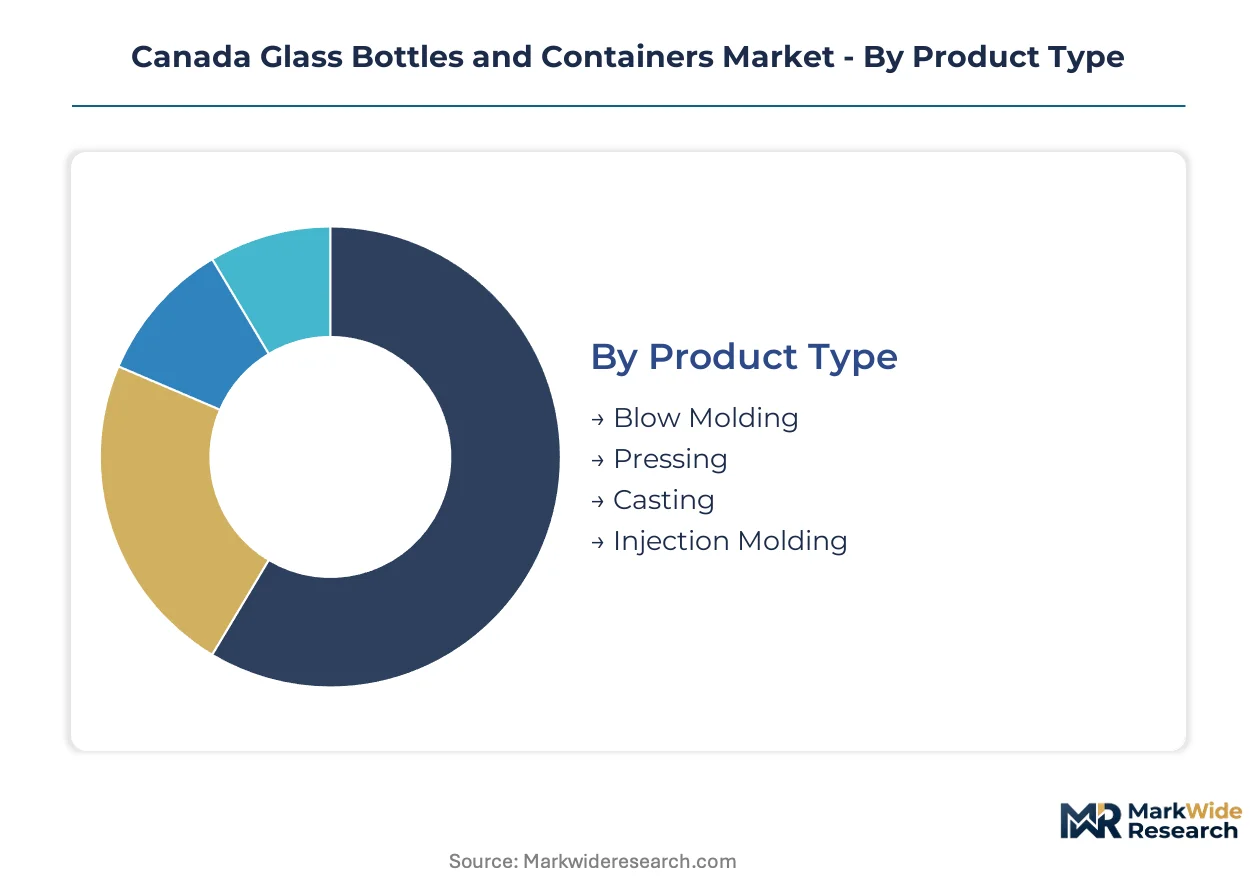
Glass container specifications diverge sharply between commodity beverage formats and precision pharmaceutical barriers. Understanding these segment boundaries clarifies where furnace investments concentrate versus where mold flexibility commands premium positioning.
Product Type:
Customization intensity varies from standardized high-speed forming to specialized low-volume casting across Canadian furnace networks.
- Blow Molding:IS machine operations dominate beverage bottle production with throughput exceeding 600 units per minute for standardized wine and spirits formats. Molson Coors and Labatt procurement concentrates here, though lightweighting specifications now demand thinner wall control than legacy equipment delivers.
- Pressing:Heavier base weights and structural rigidity define food jar applications where vacuum deformation resistance matters. Ontario's tomato processing corridor around Leamington drives demand for wide-mouth formats with reinforced shoulders.
- Casting:Low-volume specialty production serves decorative spirits presentations and limited-edition pharmaceutical packaging where mold complexity justifies slower cycle economics.
- Injection Molding:Precision thread forming and neck finish control position this method for pharmaceutical closures and child-resistant packaging where dimensional tolerance is tightest.
Most installed capacity flows through Blow Molding. Expansion is steepest in Pressing as food service condiment specifications multiply.
End User:
Regulatory burden intensity separates pharmaceutical compliance costs from beverage commodity economics.
- Food & Beverage:Health Canada's plastic prohibitions are redirecting condiment and sauce volumes toward glass substitution. Deposit-return expansion proposals in Ontario would amplify closed-loop supply security for domestic brewers.
- Pharmaceuticals:Therapeutic Products Directorate pharmacopeial standards on glass delamination risk are consolidating supplier bases to borosilicate specialists with established Canadian regulatory dossiers. Parenteral packaging now demands documented surface chemistry testing.
- Personal Care:Premium fragrance and skincare brands specify heavier base weights and custom mold designs that differentiate shelf presence in Shoppers Drug Mart and Sephora channels.
- Household Products:Industrial chemical resistance requirements favor amber glass for solvent-based cleaners where UV protection extends product stability.
Procurement volume concentrates in Food & Beverage. Margin expansion is most rapid in Pharmaceuticals as qualification timelines lengthen.
Capacity:
Volume scale determines whether dedicated high-speed lines or flexible batch production delivers optimal unit economics.
- Below 250 ml:Pharmaceutical vial demand for biologic injection volumes dominates this tier. Borosilicate durability specifications command premium placement over soda-lime alternatives.
- 250 ml to 500 ml:Standard spirits and wine formats occupy this middle ground where lightweighting technology is compressing per-unit glass consumption fastest.
- 500 ml to 1 L:Craft beverage bulk retail positioning and food service condiment segments are gaining share here as producers seek differentiation through larger format presentations.
- Above 1 L:Food service and institutional packaging applications concentrate in Ontario and Quebec where restaurant supply chains favor refillable formats.
Production throughput peaks in 250 ml to 500 ml. Steepest expansion trajectory belongs to Above 1 L as craft beverage bulk formats proliferate.
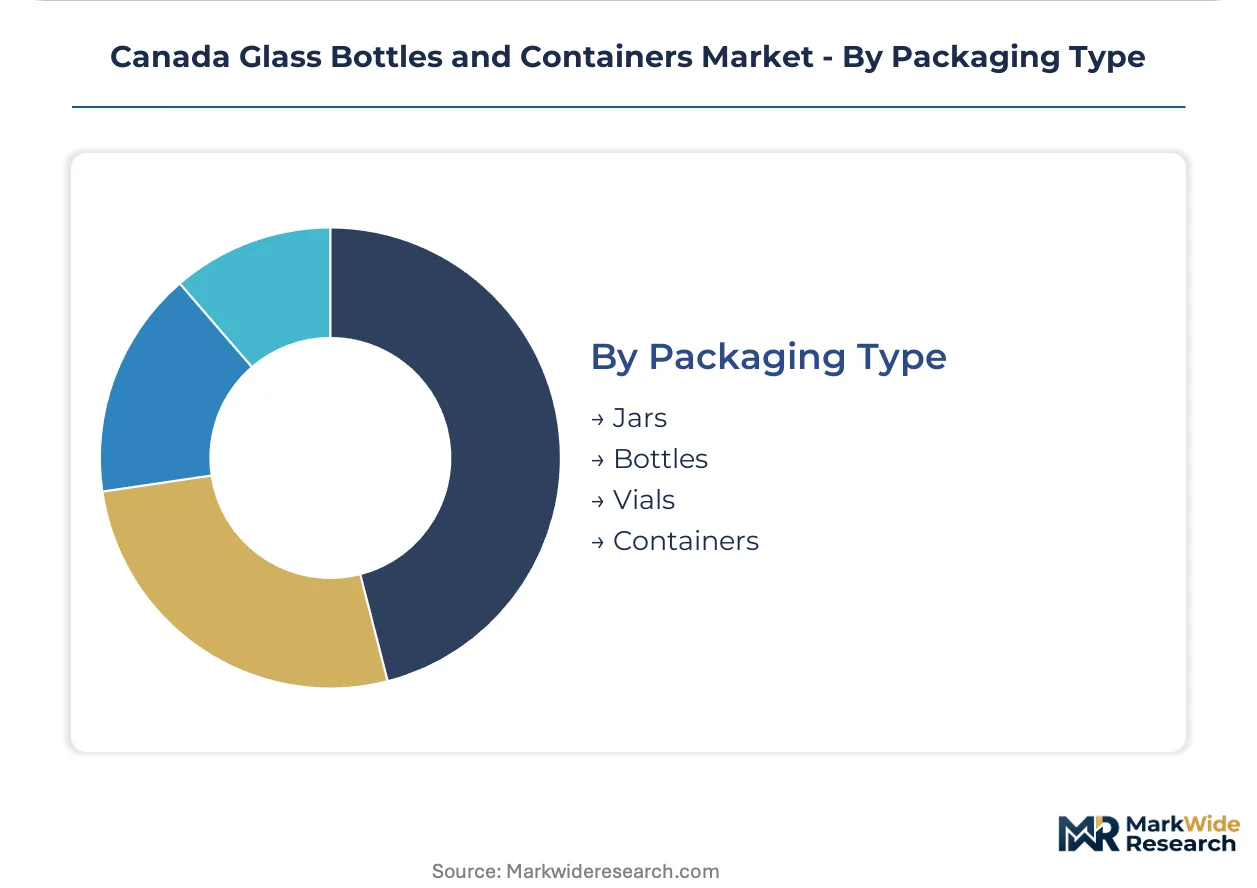
Packaging Type:
Structural function dictates whether vertical load strength or hermetic sealing capability drives specification priority.
- Bottles:Beverage containment dominates volume with neck finish standardization enabling high-speed capping line compatibility across Canadian bottling facilities.
- Jars:Wide-mouth food packaging requires heavier bases resisting vacuum deformation during thermal processing. Loblaw and Sobeys private-label specifications are consolidating format diversity.
- Vials:Parenteral drug packaging demands precise dimensional control for automated filling lines and documented surface chemistry for regulatory submission.
- Containers:Industrial and household chemical resistance specifications favor amber and cobalt formulations where UV opacity protects product integrity.
Manufacturing asset concentration favors Bottles. Fastest capacity additions target Vials as biologic drug volumes climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled furnace technicians and mold specialists concentrate in Ontario's Golden Horseshoe, anchoring Canada's glass container production workforce. Quebec's Saint-Gobain-trained engineering talent and British Columbia's craft beverage packaging designers round out the specialized labor pool.
Ontario
Toronto-Hamilton corridor hosts Owens-Illinois Inc's furnace operations and TricorBraun Canada's distribution headquarters serving Molson Coors and Labatt. Health Canada's plastic prohibition enforcement accelerates substrate conversion in Leamington's tomato processing cluster. The region's deposit-return expansion proposal would capture wine and spirits bottles currently outside the loop.
Quebec
Craft distilleries in Montreal and Quebec City specify heavier base weights and custom mold designs for premium spirits presentation. Environment and Climate Change Canada's extended producer responsibility framework adds compliance costs favoring domestic cullet-fed production. Borosilicate specialists near Montreal supply pharmaceutical vial manufacturers with documented regulatory dossiers.
British Columbia
Okanagan Valley wineries and Vancouver craft breweries drive demand for lightweighted bottles offsetting freight penalties to Eastern markets. The province's advanced EPR framework rewards higher recycled content procurement. Regional distribution partnerships serve maritime markets lacking domestic furnace presence.
Alberta
Calgary-based food service distributors specify above-1 L condiment formats for restaurant supply chains. Natural gas price volatility directly impacts melting economics for any prospective mini-furnace investment. The province's chemical resistance specifications favor amber glass for industrial solvent packaging.
Atlantic Canada
Nova Scotia and New Brunswick beverage producers rely entirely on Ontario and Quebec supply flows incurring weight-based freight penalties. Provincial deposit-return systems lack glass collection infrastructure present in Central Canada. White space exists for regional distribution partnerships or scaled mini-furnace investments.
Canada Glass Bottles and Containers Market Competitive Environment
The competitive structure tilts toward integrated furnace operators with North American network leverage. Domestic capacity concentrates among three archetypes: multinational furnace networks with bulk supply contracts, specialized mold-flexible distributors serving craft segments, and borosilicate specialists commanding pharmaceutical premiums. Capacity expansion and lightweighting technology licensing represent the dominant competitive vectors as procurement cycles compress.
Among furnace-integrated operators, Owens-Illinois Inc exemplifies the scale-driven archetype leveraging cross-border production networks. TricorBraun Canada occupies the mold-flexibility tier targeting craft distilleries and pharmaceutical qualification timelines. Pegasus Glass anchors the specialty pharmaceutical segment where borosilicate durability and regulatory dossier depth create qualification barriers.
| Leading Market Players |
|---|
| TricorBraun Canada |
| Pegasus Glass |
| Owens-Illinois Inc |
| Stoney Creek Glass |
| United Bottles & Packaging |
| Richards Packaging Inc |
| Consolidated Bottle |
| Ampak Inc |
| Vitro Canada |
| Others |
Value Chain & Pricing Dynamics
Ontario's deposit-return expansion proposal for wine and spirits bottles is forcing furnace operators to recalibrate collection economics and cullet quality premiums, compressing margins on commodity formats while rewarding closed-loop supply investments with pricing power in premium tiers.
Pricing Analysis
Bundled mold-design-and-logistics contracts dominate procurement for major brewers, while unbundled spot purchasing serves craft distilleries seeking custom specifications. Three-tier pricing structure across premium borosilicate pharmaceutical vials, standard flint beverage bottles, and economy amber food jars reflects certification grade and volume scale differentiation. Pricing pressure stems from lightweighting specifications that reduce per-unit glass consumption by 15-20 percent. Major beverage producers exhibit lowest price sensitivity due to long-term furnace contracts, while food service distributors face acute cost compression.
Supply Chain Analysis
Skilled furnace technicians and IS machine operators concentrate in Ontario's Golden Horseshoe and Quebec's Saint-Gobain legacy corridor, creating workforce scarcity that constrains capacity expansion elsewhere. Silica sand deposits in Quebec and natural gas supply from Alberta anchor raw material dependencies. Single-source vulnerability runs through Owens-Illinois Inc's cross-border furnace network for standardized beverage formats. Distribution runs through Toronto-Hamilton consolidation hubs serving Atlantic Canada, with Western Canadian markets incurring weight-based freight penalties from Ontario production bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by Health Canada's pharmacopeial glass delamination standards consolidating procurement toward domestic borosilicate specialists with established regulatory dossiers.
For Market Incumbents: To counter import flows from US and Mexican furnace networks, deepen backward integration into post-consumer cullet collection through Ontario deposit-return expansion participation, and accelerate lightweighting technology licensing to offset per-unit consumption compression. For New Entrants and Emerging Players: Capture Atlantic Canada's furnace absence through regional distribution partnerships serving Nova Scotia and New Brunswick beverage producers, or pursue mini-furnace investments targeting maritime craft distillery custom mold demand with faster qualification cycles than incumbent networks permit. For Investors and Strategic Acquirers: Asymmetric upside sits with borosilicate specialists commanding pharmaceutical premium placement as Health Canada's Therapeutic Products Directorate tightens surface chemistry documentation requirements. Five-to-ten year viability favors mold-flexible mid-cap distributors over commodity furnace operators. Watch carbon border adjustment mechanism implementation timing as inflection indicator for domestic cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting Technology Licensing | Molson Coors and Labatt specifications reward thinner-wall control capabilities with volume retention. |
| Backward Integration into Cullet Collection | Ontario deposit-return expansion creates captive supply security for closed-loop remelt economics. |
| Pharmaceutical Regulatory Dossier Investment | Therapeutic Products Directorate compliance barriers freeze out import competitors lacking Canadian history. |
| Mini-Furnace Regional Deployment | Atlantic Canada underpenetration offers white space for scaled investments serving maritime producers. |
| Custom Mold Capability Expansion | Craft distilleries in British Columbia and Quebec specify heavier base weights commanding price premiums. |
Study Parameters
Multiple input streams — primary interviews with furnace operations managers, pharmaceutical packaging procurement leads, and craft distillery supply chain directors; secondary validation through Environment and Climate Change Canada regulatory filings, Ontario deposit-return system data, and Canadian Food Inspection Agency enforcement records; plus customs trade flow analysis — were reconciled through bottom-up production capacity modeling and top-down demand segmentation triangulation.
Data-stream reconciliation across the projection horizon applied capacity-utilization curves, natural gas price sensitivity matrices, and substitution elasticity estimates between glass and competing substrates. Segmentation dimensions modeled encompass forming technology, end-use regulatory burden, capacity tier, and packaging structural function. CAGRs were derived from production volume trajectories and value-per-unit shifts across premium and commodity tiers, incorporating Health Canada plastic prohibition phase-in schedules and carbon border adjustment mechanism development signals.
Regulatory enforcement timing, natural gas price volatility, and deposit-return system expansion adoption are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about furnace rebuild cycles, cullet quality maintenance, and lightweighting technology diffusion rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Italy Container Glass Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Dosing Bottles Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
France Container Glass Market
Glass Packaging
Egypt Container Glass Market
Glass Packaging
Panama Container Glass Market
Glass Packaging
Asia - Pacific Glass Bottles and Containers Market
Glass Packaging
India Container Glass Market
Glass Packaging
Uruguay Container Glass Market
Glass Packaging
North America Pharmaceutical Glass Packaging Market
Glass Packaging
United Kingdom (UK) Glass Bottles and Containers Market
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
Mason Jars Market