
 Japan Asset Management Market | 2026-2036
Japan Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Asset Management Market Outlook
Retail distribution channels is fragmenting as digital robo-advisors and online brokerage platforms erode traditional bank-sold fund dominance. Jafco leverages its private equity heritage to anchor alternative asset access for domestic investors. SBI Holdings competes through fintech-integrated wealth platforms that extend beyond conventional fund distribution. WealthNavi differentiates via fully automated portfolio construction that occupies the mass-affluent digital segment.
Asset management encompasses the professional oversight of investment portfolios across equities, fixed income, real estate, and commodities, employing active management, passive investing, or hybrid strategies to optimize risk-adjusted returns for institutional and retail clients. The practice relies on quantitative models, fundamental research, and regulatory compliance frameworks to allocate capital toward specified financial objectives. Passive investing and index funds now lead flow generation as fee compression reshapes margin pools across the industry. Alternative strategies and real estate allocations represent the fastest-growing structural segments as pension funds and high net worth individuals seek yield beyond traditional fixed income.
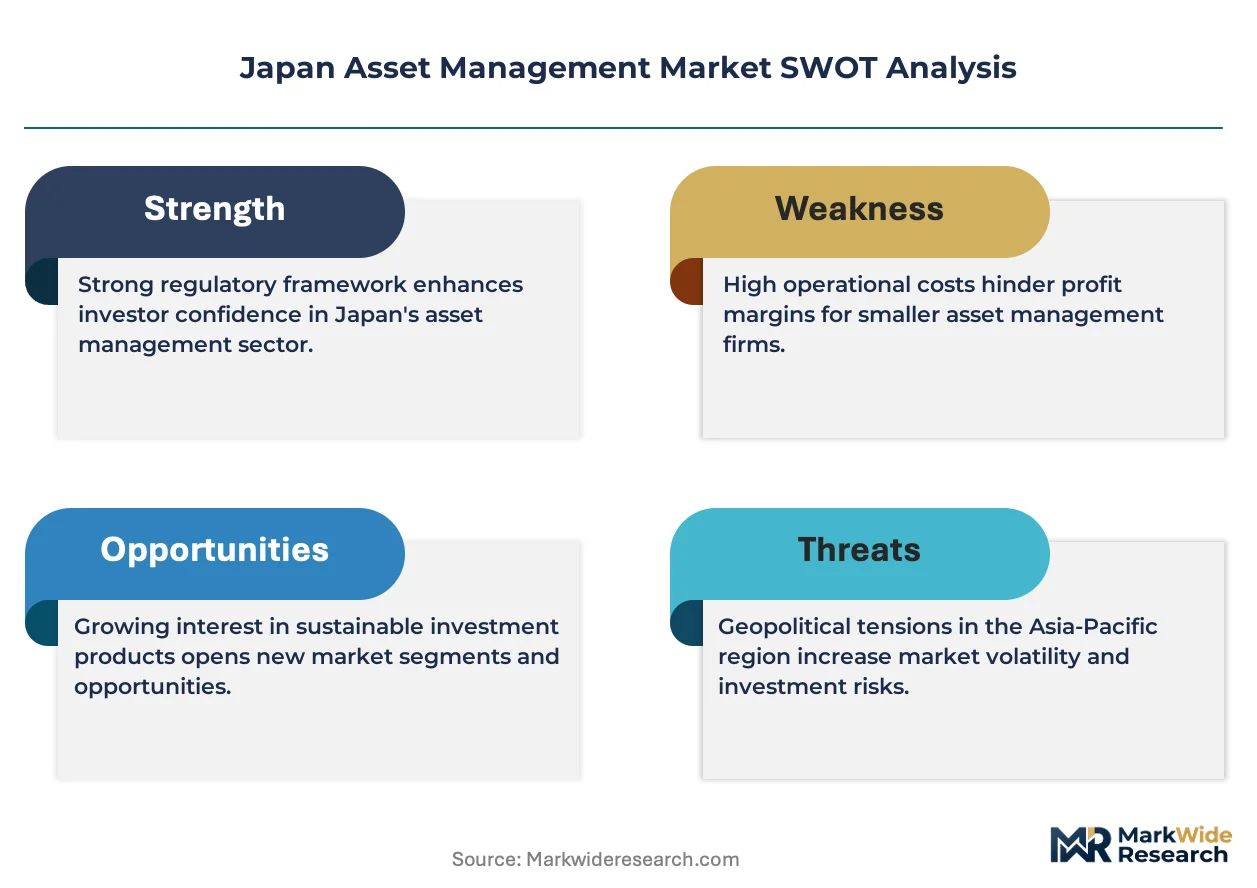
METI guidelines on sustainable finance and the FSA's stewardship code shape product design and disclosure standards for domestic fund managers. JIS standards for financial service quality and the FSA's fund registration requirements govern market access and operational compliance. Stakeholders must monitor how evolving ESG disclosure mandates and digital asset custody rules reshape competitive requirements for licensing and client onboarding.
Market Dynamics
Fee compression across passive vehicles is forcing Japanese asset managers to restructure revenue models while METI's sustainable finance mandates redirect product development priorities toward ESG-integrated portfolios.
Growth Catalysts
- Pension fund reallocation:Japan's Government Pension Investment Fund and corporate pension schemes are expanding alternative asset allocations beyond traditional fixed income, creating structural demand for private equity and real estate strategies.
- METI sustainable finance framework:The Ministry of Economy, Trade and Industry's disclosure guidelines and green bond standards are accelerating ESG product launches across domestic fund houses.
- Tokyo metropolitan wealth concentration:High net worth household density in the capital region sustains premium advisory service demand and supports fee-based wealth management expansion.
Market Restraints
- Domestic equity market stagnation:Prolonged low returns on Japanese equities constrain active management fee justification and compress manager performance fees.
- Banking channel dominance:Mega-bank trust banking subsidiaries control retail fund distribution, creating entry barriers for independent asset managers and fintech platforms.
- Negative interest rate legacy:Sustained monetary easing has eliminated yield on money market funds and compressed fixed income strategy margins.
Strategic Opportunities
- Regional bank partnership channels:Second-tier regional banks lack in-house asset management capabilities, opening white-label and sub-advisory arrangements for specialized managers.
- Defined contribution pension expansion:Japan's iDeCo and corporate DC plan growth creates demand for target-date funds and lifecycle investment products.
- Digital robo-advisor penetration:Automated portfolio platforms can capture mass-affluent segments underserved by traditional bank wealth divisions.
Industry Challenges
- Quantitative analyst talent scarcity:Domestic universities produce insufficient graduates with combined programming and financial engineering skills to support systematic strategy growth.
- Legacy IT system integration:Established asset managers face high switching costs when migrating from on-premise portfolio management systems to cloud-native platforms.
- Stewardship Code compliance burden:FSA engagement monitoring requirements demand expanded governance resources for equity managers holding Japanese corporate shares.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Asset Management Market |
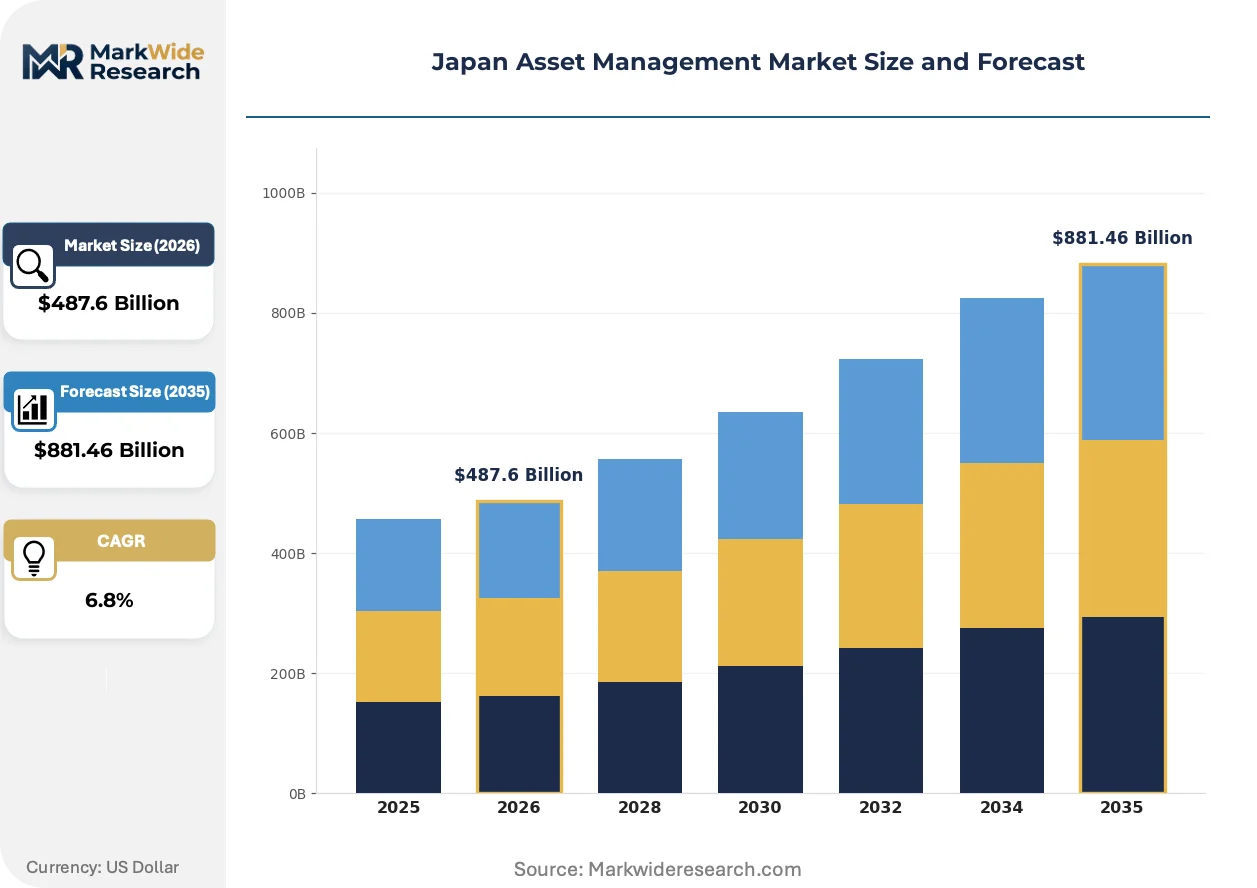
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Active Management, Passive Investing, Index Funds, Alternatives Asset Class: Equities, Fixed Income, Real Estate, Commodities Client Type: Institutional Investors, Retail Investors, High Net Worth Individuals, Pension Funds Service Type: Wealth Management, Fund Management, Advisory Services, Risk Management |
| Companies Covered | Jafco, SPARX Group, SBI Holdings, CREAL, Ichiyoshi Securities, Tokai Tokyo Financial Holdings, WealthNavi, Miyakoshi Holdings, Ichigo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Asset Management Market Strategic Shifts
Digital infrastructure is restructuring how investment products reach Japanese retail investors, while regulatory mandates and demographic pressures reshape portfolio construction methodologies.
Artificial intelligence-driven risk analytics is collapsing traditional portfolio construction timelines by automating scenario stress-testing and correlation analysis. Domestic quantitative teams at major trust banks are deploying machine learning models for factor-based equity selection. This compression is enabling faster product iteration cycles and reducing time-to-market for new fund launches.
METI's 2023 sustainable finance taxonomy and the FSA's enhanced stewardship disclosure requirements are mandating granular ESG data collection across equity holdings. Asset managers must now integrate carbon footprint tracking and engagement documentation into standard reporting workflows. Small-cap domestic equity specialists face disproportionate compliance costs relative to their AUM base.
Retail investors are bypassing bank branch advisors through direct-to-consumer digital platforms offering fractional share access and thematic ETF baskets. Online brokerages in Osaka and Fukuoka are capturing younger demographic cohorts with mobile-first interfaces. This channel rotation is most pronounced among investors under 40 seeking cryptocurrency and overseas equity exposure.
Japan Asset Management Market Segmentation
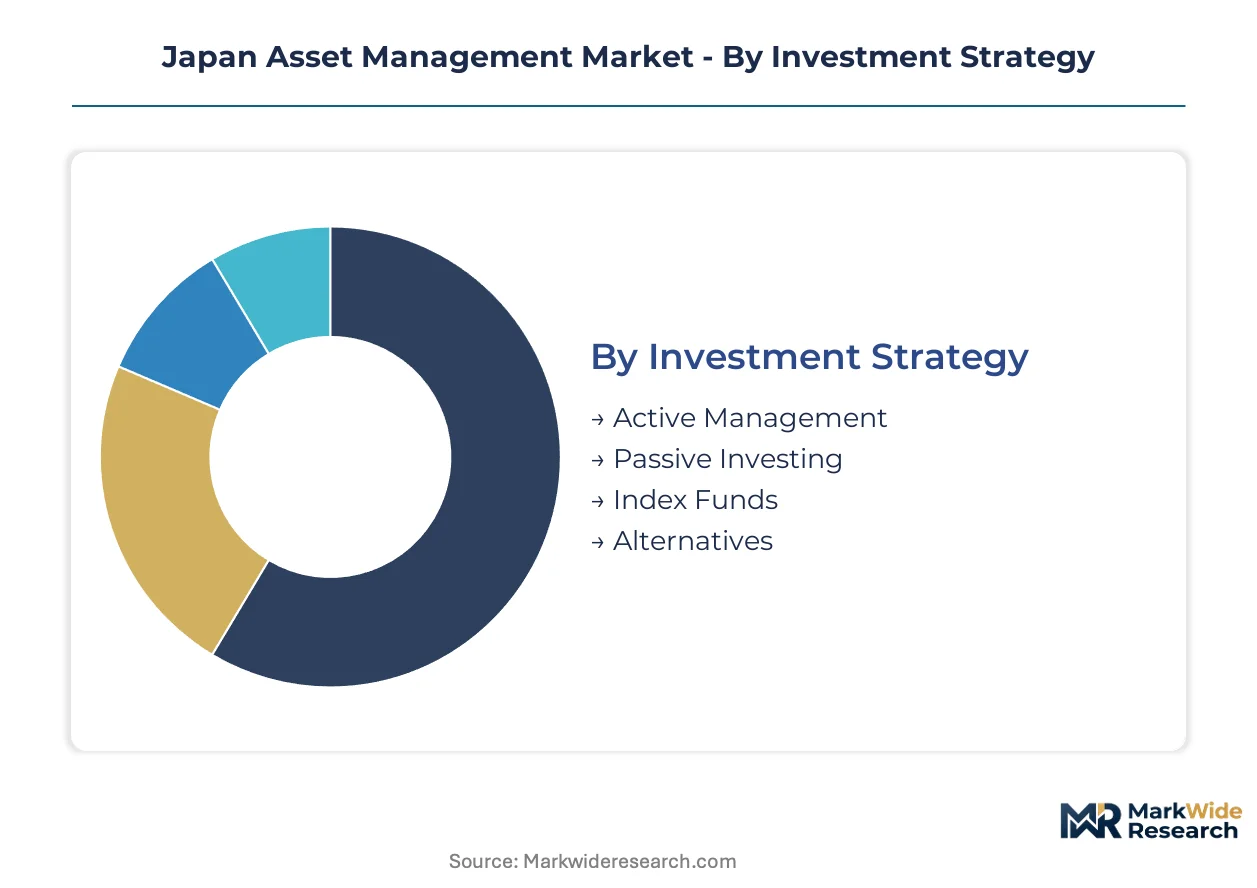
Segmentation reveals how fee compression, regulatory mandates, and demographic shifts differentially impact revenue pools across strategy types and client categories in Japan. Understanding these divisions exposes where margin erosion concentrates and where structural demand expansion offers shelter.
Investment Strategy:
After-sales service intensity varies sharply across strategy types, with alternatives requiring ongoing portfolio monitoring and bespoke reporting that passive vehicles simply do not demand.
- Active Management:Portfolio managers deploy fundamental research and quantitative models to outperform benchmarks through security selection and tactical allocation. Tokyo-based institutional mandates concentrate here as corporate pension funds seek alpha generation to close liability gaps. Fee pressure from passive migration is compressing margins fastest in this segment.
- Passive Investing:Rules-based replication of market indices at minimal cost through ETFs and index-tracking mutual funds. Mass-affluent retail demand through Osaka and Fukuoka digital platforms is accelerating flow capture. METI disclosure requirements add compliance overhead that scales poorly against razor-thin fee structures.
- Index Funds:Pooled vehicles offering precise benchmark exposure with minimal tracking error. The Government Pension Investment Fund deploys substantial allocations here for core equity and fixed income exposure.
- Alternatives:Private equity, hedge fund, and real asset strategies operating outside traditional long-only frameworks. Jafco and domestic PE houses anchor distribution to high net worth segments seeking yield beyond negative-rate fixed income.
By volume, passive investing leads. By growth pace, alternatives are climbing the fastest.
Asset Class:
Cost tier differentiation separates institutional-grade mandates from retail-accessible products, with minimum investment thresholds and fee structures stratifying access.
- Equities:Domestic and international stock allocations across market capitalizations and sectors. FSA Stewardship Code engagement requirements impose governance documentation burdens that favor large-cap specialists with compliance scale.
- Fixed Income:Government bonds, corporate credit, and structured products delivering yield and duration management. Negative interest rate legacy has eliminated money market viability and compressed margins across duration strategies.
- Real Estate:Direct property, REITs, and real estate debt strategies offering inflation linkage and income generation. Tokyo metropolitan wealth concentration sustains premium allocation demand from family offices.
- Commodities:Physical and futures-based exposure to energy, metals, and agricultural products. Institutional hedging demand from trading houses and manufacturers anchors this segment.
Fixed income dominates current AUM by volume, yet real estate is gaining share fastest as yield-seeking capital rotates from negative-rate debt.
Client Type:
Application requirements diverge materially across client categories, with institutional mandates demanding custom reporting and fiduciary governance that retail channels cannot economically support.
- Institutional Investors:Corporate pension schemes, insurance companies, and endowments with fiduciary oversight and liability-driven investment frameworks. METI sustainable finance mandates are redirecting procurement toward ESG-integrated managers.
- Retail Investors:Individual savers accessing products through bank branches, online brokerages, and digital platforms. Younger cohorts in metropolitan corridors are bypassing traditional distribution for mobile-first interfaces.
- High Net Worth Individuals:Affluent households with investable assets exceeding threshold minimums for bespoke advisory and alternative access. Tokyo concentration supports premium fee-based wealth management expansion.
- Pension Funds:The Government Pension Investment Fund and corporate schemes with defined benefit obligations driving liability-matched allocation. Alternative asset expansion is creating structural demand for illiquid strategies.
Pension funds lead by committed capital volume, while retail investors are expanding most quickly through iDeCo and defined contribution penetration.
Service Type:
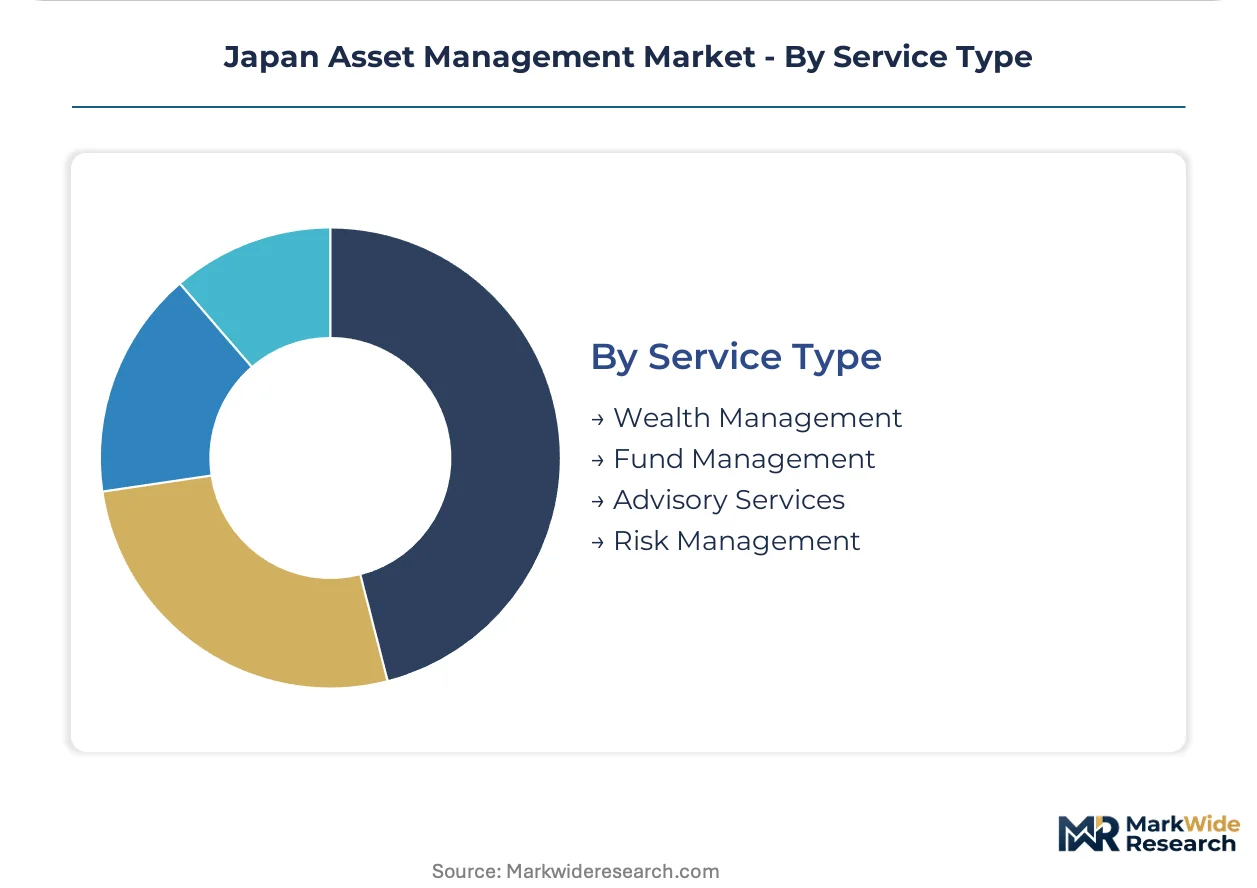
Customer type determines service packaging, with mass-market digital delivery at one extreme and white-glove family office governance at the other.
- Wealth Management:Holistic financial planning integrating investment, tax, and estate considerations for affluent households. Regional bank partnership demand is opening white-label opportunities for specialized managers.
- Fund Management:Pooled vehicle construction and administration across strategy types and asset classes. Fee compression is forcing revenue model restructuring toward performance-linked structures.
- Advisory Services:Consultative investment guidance without discretionary portfolio authority. Digital robo-advisors are automating this function for mass-affluent segments.
- Risk Management:Portfolio hedging, derivatives overlay, and liability-driven investment frameworks. Corporate pension derisking mandates are expanding institutional procurement here.
Fund management dominates by revenue volume presently, though wealth management is on the steepest expansion trajectory as advisory fees replace transaction-based compensation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tokyo-Osaka Shinkansen corridor underwrites Japan's asset management concentration, compressing travel time between the two largest wealth pools to under three hours and enabling same-day client servicing across both metropolitan anchors.
Kanto/Tokyo
The Government Pension Investment Fund and corporate headquarters density drive institutional mandate concentration. METI's sustainable finance taxonomy implementation is redirecting procurement toward ESG-integrated managers. Marunouchi and Nihonbashi financial districts host trust banking subsidiaries that control retail distribution channels.
Kansai/Osaka
Regional bank holding companies and trading house treasury operations generate substantial institutional asset servicing demand. FSA fund registration requirements govern market access for foreign managers establishing Osaka satellite offices. Umeda district is emerging as a secondary fintech platform hub targeting mass-affluent digital investors.
Chubu/Nagoya
Automotive and industrial corporate pension schemes anchor defined contribution plan administration. JIS standards for financial service quality shape operational compliance for managers serving manufacturing sector clients. Sakae district concentrates private banking operations for affluent household segments.
Kyushu
Fukuoka's startup visa program and digital nomad incentives are attracting fintech platform registration. FSA digital asset custody rules are reshaping licensing requirements for emerging wealth technology ventures. Tenjin district is developing as a regional hub for online brokerage platform operations.
Hokkaido
Agricultural cooperative financial institutions generate demand for conservative fixed income and alternative asset strategies. The FSA's stewardship code engagement monitoring requirements apply to equity managers serving regional institutional clients. Sapporo's limited manager density creates white-label partnership opportunities for specialized Tokyo-based firms.
Japan Asset Management Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in niche strategy construction. The vendor base stratifies across trust banking conglomerates, independent alternative asset houses, and digital-native fintech platforms. Three archetypes dominate: mega-bank asset management subsidiaries with distribution lock-in, boutique private equity specialists with illiquid strategy expertise, and automated robo-advisors with mass-market scalability. Competitive moves concentrate on regional bank partnership formations and digital infrastructure buildouts.
Among Japan-based independent specialists, Jafco, SPARX Group, and WealthNavi occupy distinct positioning archetypes. Jafco represents the legacy private equity house with alternative asset heritage. SPARX Group exemplifies the activist-oriented equity specialist with institutional mandate concentration. WealthNavi anchors the fully automated digital segment targeting mass-affluent investors underserved by traditional bank wealth divisions. Each sits within a non-overlapping competitive space defined by client type, service intensity, and distribution methodology.
| Leading Market Players |
|---|
| Jafco |
| SPARX Group |
| SBI Holdings |
| CREAL |
| Ichiyoshi Securities |
| Tokai Tokyo Financial Holdings |
| WealthNavi |
| Miyakoshi Holdings |
| Ichigo |
| Others |
Value Chain & Pricing Dynamics
Marunouchi's trust banking cluster concentrates discretionary mandate capacity, translating custody scale into pricing leverage over independent asset managers competing for institutional flows. Fee compression across passive vehicles feeds back into distributor consolidation as mega-bank subsidiaries absorb margin pressure through cross-subsidized wealth operations.
Pricing Analysis
Volume-discount tiering structures separate institutional mandates from retail-accessible products, with minimum commitment thresholds stratifying advisory fees. Pricing stratifies across premium bespoke mandates, standard pooled vehicles, and economy digital robo-advisory tiers. Cost compression in passive index tracking is intensifying because METI disclosure requirements add fixed compliance overhead that erodes razor-thin management fees. Corporate pension schemes exhibit lowest price sensitivity given fiduciary governance requirements, while mass-affluent digital investors demonstrate highest elasticity to basis-point reductions.
Supply Chain Analysis
Extended payment terms from regional bank distributors strain working capital for specialized fund managers lacking balance-sheet depth. Portfolio management technology draws from US cloud infrastructure, Japanese domestic data center capacity, and Singapore-based disaster recovery nodes. Custody and fund administration rest on Tokyo-based trust banking subsidiaries and Osaka satellite operations. Single-source vulnerability concentrates in core banking system providers serving the mega-bank trust subsidiaries. Distribution runs through branch advisor networks, online brokerage platforms, and direct-to-consumer mobile applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's asset management sector sits at a platform-economics inflection where open-architecture API interoperability between robo-advisors and regional bank cores is dissolving traditional distribution moats.
For Market Incumbents: Build data-asset moats through proprietary ESG scoring engines that METI disclosure mandates now require. Integrate carbon footprint analytics in-house to avoid licensing costs from third-party providers. Regional bank partnership exclusivity offers channel control against SBI Holdings' fintech-integrated wealth platforms. Stewardship Code compliance automation represents the critical R&D investment area. For New Entrants and Emerging Players: Mid-market corporate DC plan administration in Nagoya and Fukuoka represents the most penetrable entry point given incumbent neglect of second-tier manufacturing pension schemes. White-label target-date fund construction for regional banks lacking in-house lifecycle product capability offers immediate revenue traction. Direct API integration with online brokerage back-ends enables bypass of branch advisor gatekeepers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because fee compression will eliminate sub-scale active managers while alternatives expertise commands scarcity premiums. Acquisition targets cluster around quantitative systematic specialists with carbon analytics capabilities and regional bank distribution relationships. The signal to watch is iDeCo participant growth rates as a proxy for defined contribution market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Bank Partnership Formation | White-label fund distribution through second-tier institutions bypasses mega-bank trust subsidiary lock-in. |
| ESG Data Infrastructure Investment | Proprietary carbon footprint tracking satisfies METI taxonomy requirements without third-party licensing. |
| Robo-Advisor Platform Integration | API connectivity with online brokerage back-ends captures mass-affluent investors outside branch networks. |
| Alternative Asset Capability Buildout | Private equity and real estate expertise addresses pension fund yield-seeking beyond negative-rate fixed income. |
| DC Plan Product Development | Target-date and lifecycle construction serves iDeCo and corporate defined contribution expansion mandates. |
Study Parameters
Cross-validation between FSA fund registration databases and METI sustainable finance disclosure filings anchors the qualitative findings on product development priorities. Primary interviews with trust bank portfolio managers, regional bank wealth division heads, DC plan administrators, and fintech platform CTOs combined with secondary validation from FSA regulatory circulars, JIS standards documentation, and pension fund procurement disclosures. Bottom-up AUM aggregation and top-down macro allocation trend analysis complete the triangulation.
Calibration against historical flow data and institutional mandate procurement patterns shapes the projection framework across the analysis window. Segmentation dimensions include investment strategy type, asset class exposure, client category, and service delivery model. CAGRs derive from trend extrapolation adjusted for regulatory inflection points and demographic transition effects. Forecast inputs incorporate pension fund alternative allocation targets and digital platform penetration rates.
Macroeconomic conditions sit as an overlay; deviation in Bank of Japan policy trajectory, yen volatility, or regional equity market performance would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation timelines and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
US Asset Management Market
Asset Management
India Asset Management Market
Asset Management
Equity Management Tool Market
Asset Management
Global Asset Performance Management Market
Asset Management
Fund Management Fee Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
Global Investment Management Software Market
Asset Management
Fixed Income Asset Management Market
Asset Management
Canada Asset Management Market
Asset Management
Asset Optimization Solutions Market
Asset Management
Global AI in Asset Management Market
Asset Management
Mutual Fund Assets Market
Asset Management
LAMEA Equity Management Software Market
Asset Management
APAC Mutual Fund Market
Asset Management
Global Remote Asset Management Market
Asset Management
Hardware Asset Management Market