
 Equity Management Tool Market | 2026-2036
Equity Management Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Equity Management Tool Market Insights
Platform bundling is pivoting how buyers evaluate equity management tools, with all-in-one suites displacing point solutions for cap table administration. Carta leverages its vertical integration across valuation services and compliance tracking to sustain pricing power. Pulley anchors its position among early-stage startups through modular onboarding that scales with headcount growth.
An equity management tool is a software platform that automates cap table administration, equity plan governance, and stakeholder reporting through centralized databases with audit-trail functionality, typically deployed via cloud infrastructure with API connectivity to HRIS and payroll systems. Its primary commercial purpose is to reduce legal risk in equity compensation while providing real-time visibility to investors, employees, and regulators. Cloud-based deployment leads the market due to lower implementation friction for startups lacking dedicated IT infrastructure, while compliance tracking commands premium margins as regulatory complexity intensifies across jurisdictions. Grant administration represents the fastest-growing solution segment as companies expand equity participation to broader employee pools beyond executive ranks.
The SEC shapes product standards through disclosure requirements for private company equity compensation, while the IRS governs tax-qualified plan documentation and 409A valuation compliance. GDPR and emerging state privacy laws in California and New York constrain how platforms store and transfer participant personal data across borders. Stakeholders must monitor whether evolving SEC rules for private market transparency will force platform providers to rebuild reporting architectures or create openings for specialized compliance vendors.
Market Dynamics
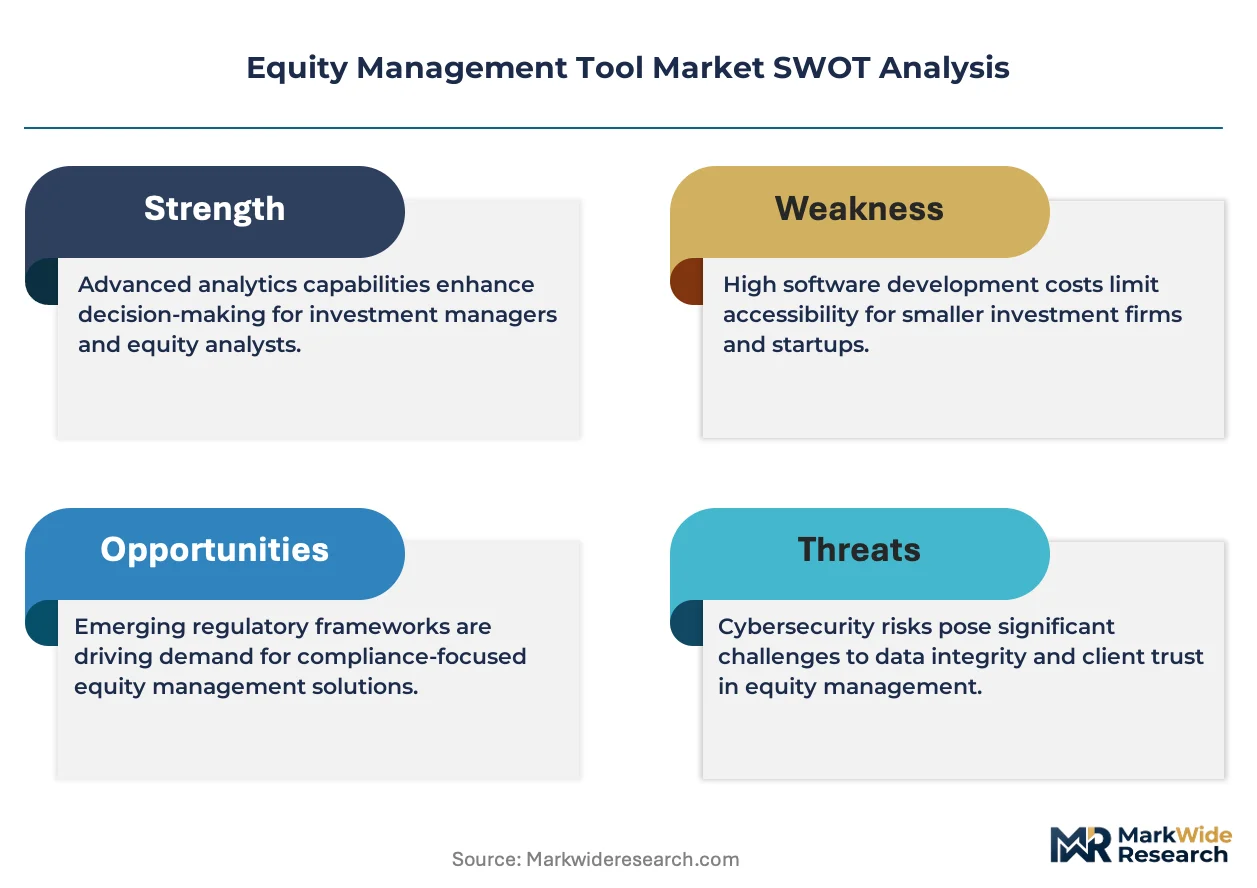
Cloud-native architecture is restructuring competitive boundaries in equity management tools, collapsing the traditional gap between cap table administration and real-time compliance automation that previously required separate vendor relationships.
Growth Catalysts
- SEC Private Market Transparency Rules:The SEC's enhanced disclosure mandates for private company equity compensation are compelling venture-backed firms to adopt automated reporting platforms that generate audit-ready documentation.
- Startup Cluster Density:Concentrated startup ecosystems in the United States, particularly Silicon Valley and New York corridors, create network effects where platform adoption by lead investors cascades to portfolio companies.
- API-First Integration:Cloud-based platforms with native HRIS and payroll connectivity are eliminating manual data reconciliation, reducing implementation friction for companies without dedicated IT infrastructure.
Market Restraints
- 409A Valuation Cost Concentration:Third-party valuation services required for tax compliance create ongoing cost burdens that scale with grant frequency and company complexity.
- Data Sovereignty Fragmentation:GDPR in Europe and emerging state privacy laws in California and New York impose conflicting storage and transfer requirements that complicate cross-border participant management.
- Legacy System Entrenchment:Established private companies with decades of equity history face migration complexity when transitioning from spreadsheet-based cap tables to automated platforms.
Strategic Opportunities
- Mid-Market Expansion:Private companies with 200-2,000 employees remain underserved by solutions designed for either early-stage startups or public issuers, creating a whitespace for tailored platform configurations.
- International Equity Plans:Cross-border equity compensation for remote workforces is driving demand for multi-jurisdictional tax withholding automation and localized grant documentation.
- Real-Time Stakeholder Dashboards:Investor and employee self-service portals are displacing quarterly PDF reports, creating subscription revenue opportunities through premium visibility tiers.
Industry Challenges
- Specialized Compliance Talent Scarcity:Platforms require personnel fluent in both software engineering and equity plan taxation across multiple jurisdictions, a combination rarely found in single candidates.
- Multi-System Integration Complexity:Synchronizing equity data across HRIS, payroll, accounting, and cap table platforms demands sustained engineering resources to maintain API stability and data integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equity Management Tool Market |
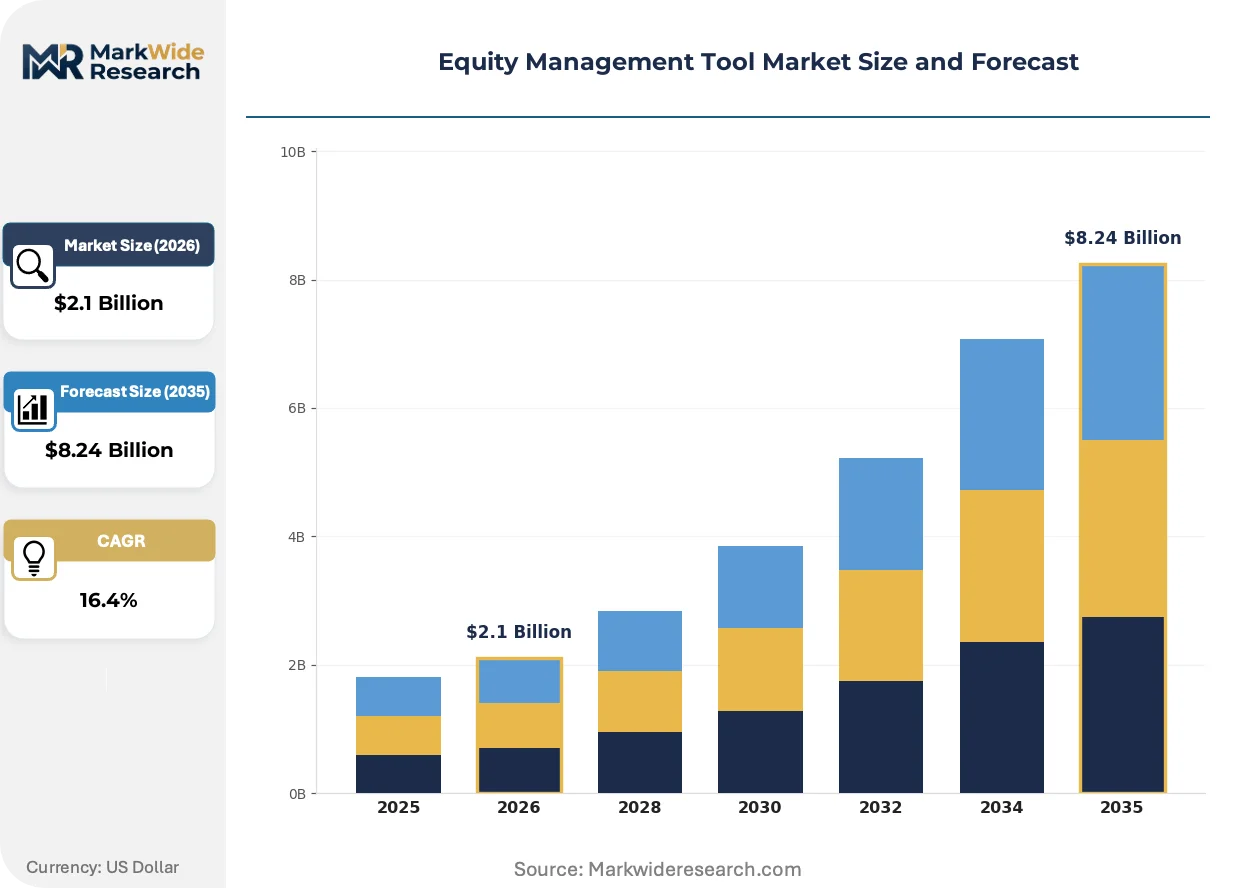
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $8.24 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Private Cloud Solution Offering: Cap Table Management, Compliance Tracking, Valuation Software, Grant Administration, Reporting & Analytics Use Case: Startups, Venture Capital Firms, Private Equity, Corporate Legal Departments, Employee Stock Ownership Plans End User: Financial Advisors, Legal Counsel, Human Resources, Equity Plan Administrators |
| Companies Covered | Carta, Pulley, JP Morgan Workplace Solutions, Qapita, Ledgy, Astrella, Deel, OptionTrax, Trica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equity Management Tool Market Trends and Innovations
Artificial intelligence and machine learning capabilities are penetrating equity management workflows, automating previously manual processes in valuation modeling, compliance monitoring, and predictive scenario planning for dilution impacts.
Embedded 409A valuation engines are overtaking standalone appraisal services by integrating automated fair market value calculations directly into cap table platforms. Growth-stage companies with frequent grant cycles are adopting these tools to compress valuation turnaround from weeks to days. This convergence is compressing vendor relationships and collapsing the traditional separation between equity administration and valuation services.
The SEC's private market disclosure enhancements are mandating granular equity compensation reporting that exceeds current spreadsheet capabilities. Private companies must now produce standardized, machine-readable equity data that mirrors public company transparency requirements. Early-stage venture firms are responding by requiring portfolio companies to adopt compliant platforms prior to Series A financing.
Subscription pricing models are displacing perpetual licenses and implementation fees as the dominant commercial structure. Buyers prefer predictable annual costs aligned with headcount growth rather than large upfront capital expenditures. This shift is most pronounced among technology startups in the United States, where cash conservation priorities favor operational expenditure treatment for software procurement.
Equity Management Tool Market Segmentation
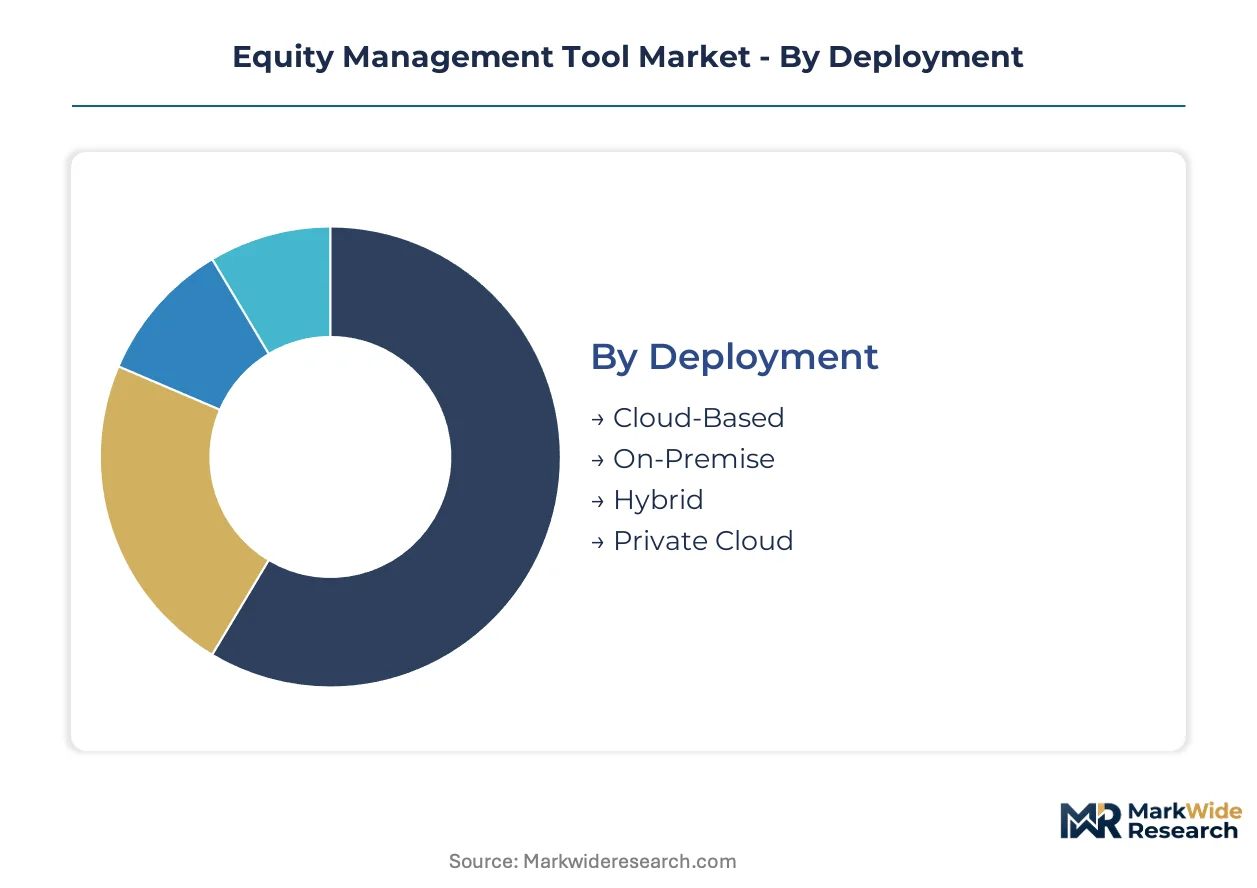
Segmentation in equity management tools reflects divergent buyer priorities across technical infrastructure, regulatory complexity, and organizational scale. Deployment preferences separate cash-constrained startups from security-conscious enterprises, while solution specialization tracks the maturation of equity programs from simple cap tables to multi-jurisdictional compliance.
Deployment:
Cost tier drives deployment selection, with implementation friction and ongoing operational expenditure treatment determining buyer trade-offs between accessibility and control.
- Cloud-Based:Multi-tenant SaaS architecture delivers immediate provisioning without capital expenditure, eliminating server maintenance burdens for venture-backed startups in Silicon Valley and Austin. Network effects concentrate demand here as lead investors mandate standardized platforms across portfolio companies.
- On-Premise:Dedicated server installations within client data centers satisfy financial institutions and defense contractors with stringent data residency requirements. Procurement concentrates among established private equity firms in New York and Boston managing decades of sensitive transaction history.
- Hybrid:Split configurations place cap table data in private infrastructure while routing employee-facing portals through public cloud edge nodes. This appeals to mid-market technology issuers navigating GDPR data sovereignty constraints.
- Private Cloud:Single-tenant virtualized environments hosted by managed service providers offer isolation without full capital burden. Demand clusters among healthcare and biotech startups handling HIPAA-protected participant information.
Volume sits with Cloud-Based deployments; growth tilts toward Hybrid configurations as data sovereignty fragmentation intensifies.
Solution Offering:
Application maturity determines solution adoption sequencing, with buyers prioritizing foundational administration before layering compliance and analytics capabilities.
- Cap Table Management:Centralized equity ownership tracking with automated waterfall modeling and scenario-based dilution analysis. This remains the entry point for seed-stage companies in San Francisco and Seattle replacing spreadsheet-based tracking.
- Compliance Tracking:Automated SEC disclosure generation, 409A valuation documentation, and multi-jurisdictional tax withholding calculations. This commands premium pricing as regulatory complexity escalates across state and federal requirements.
- Valuation Software:Embedded fair market value engines applying option pricing models and comparable company analysis. Growth-stage firms with quarterly grant cycles adopt these to compress appraisal timelines.
- Grant Administration:End-to-end equity award lifecycle management from board approval through vesting acceleration and exercise processing. This segment is expanding most quickly as companies broaden participation beyond executive ranks to all-employee pools.
- Reporting & Analytics:Real-time dashboards for investors and employees with self-service access to holdings, tax implications, and scenario modeling. Subscription tiers for premium visibility features create recurring revenue expansion.
Revenue concentrates in Cap Table Management; margin expansion favors Compliance Tracking as regulatory scrutiny intensifies.
Use Case:
Customer type shapes functional requirements, with organizational structure and stakeholder complexity dictating platform configuration priorities.
- Startups:Pre-IPO companies with simple capital structures prioritize rapid onboarding and investor-ready reporting. Founders in Denver and Miami select platforms based on venture firm preferences and Series A readiness.
- Venture Capital Firms:Investment managers require portfolio-level aggregation across dozens of holdings with standardized reporting for limited partners. Platform selection cascades downstream through investment agreements.
- Private Equity:Buyout firms managing complex capital stacks with multiple share classes and co-investor arrangements demand granular control rights tracking and waterfall precision.
- Corporate Legal Departments:Public company subsidiaries and spin-offs need public-company-grade disclosure capabilities with SOX-compliant audit trails and internal control documentation.
- Employee Stock Ownership Plans:ESOP trustees require specialized valuation integration and participant communication tools for broad-based ownership structures in manufacturing and professional services.
Adoption depth sits with Venture Capital Firms; platform complexity escalates fastest among Private Equity users managing intricate capital structures.
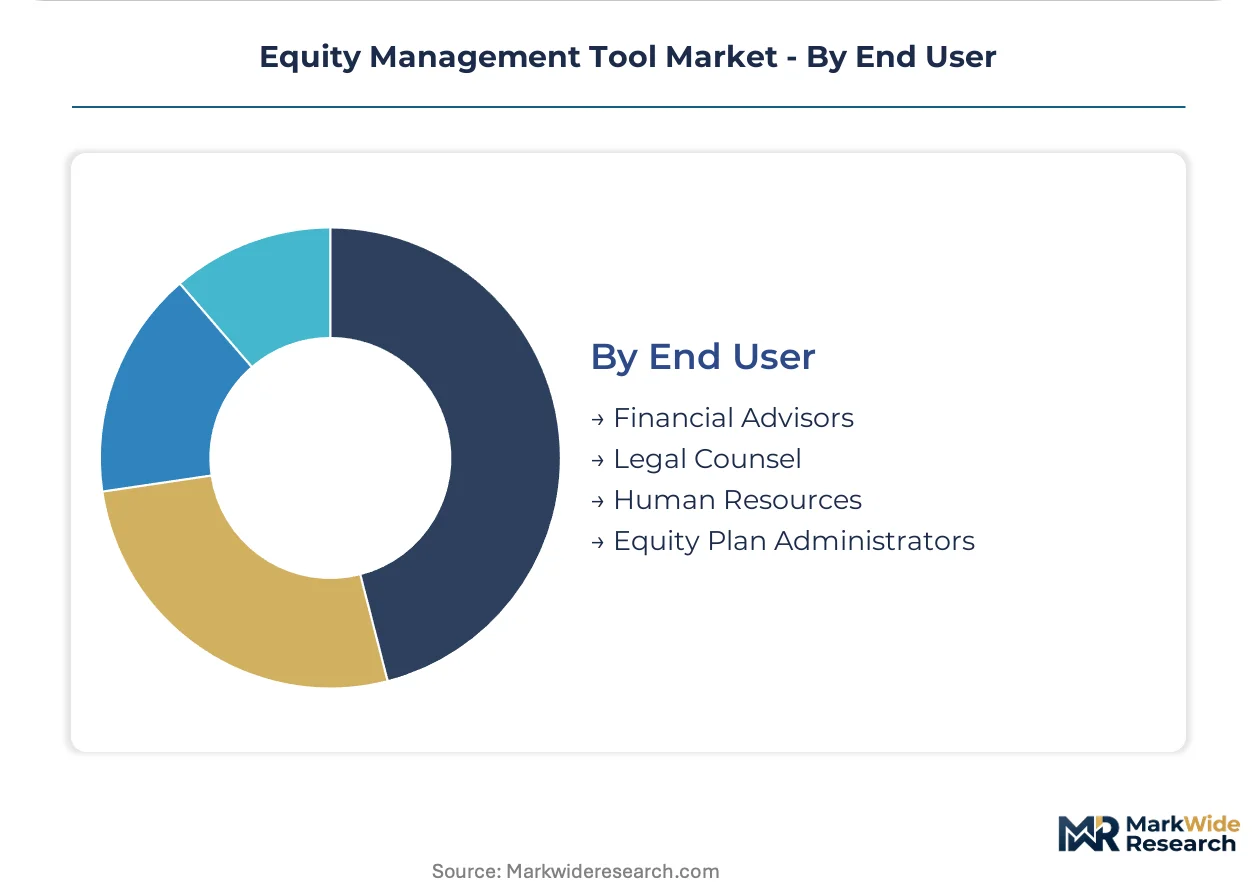
End User:
Professional role determines interface requirements and workflow integration points, with technical sophistication varying sharply across functional boundaries.
- Financial Advisors:Wealth managers and family offices serving equity-compensated executives need tax-optimization modeling and liquidity event planning tools integrated with broader portfolio management.
- Legal Counsel:Corporate attorneys require document generation, electronic signature workflows, and board resolution tracking with version control and approval audit trails.
- Human Resources:HR business partners prioritize employee self-service portals, payroll integration, and compensation statement generation for total rewards communication.
- Equity Plan Administrators:Dedicated specialists managing large participant bases need bulk transaction processing, automated vesting schedules, and reconciliation tools across multiple equity instruments.
Platform stickiness concentrates with Equity Plan Administrators; interface investment prioritizes Human Resources for employee experience differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform development concentrates in the United States while consumption spreads across venture capital corridors in Western Europe and Asia-Pacific. The production-consumption divide reflects how cloud-native architecture enables remote deployment while regulatory complexity keeps customization anchored near SEC and IRS rulemaking centers.
United States
Silicon Valley startup density and New York financial advisory clusters generate concentrated platform adoption. The SEC's enhanced disclosure requirements for private company equity compensation compel automated reporting adoption. Austin and Denver emerging as secondary hubs where venture firm platform mandates cascade to portfolio companies.
United Kingdom
London's fintech corridor and Cambridge venture ecosystem drive demand for multi-jurisdictional compliance tools. GDPR constraints on cross-border participant data storage shape platform configuration requirements. The Financial Conduct Authority's evolving guidance on equity compensation disclosure influences product development priorities.
Germany
Berlin's startup ecosystem and Frankfurt private equity offices anchor continental European adoption. The country's national data protection regulator enforces strict localization requirements for participant personal information. Munich and Hamburg clusters show particular concentration in compliance-heavy industries including automotive and industrial technology.
India
Bangalore's venture capital inflows and Mumbai financial services corridors accelerate platform adoption among growth-stage startups. SEBI regulations governing employee stock option plans create documentation requirements that automated platforms address. The PLI scheme for technology manufacturing indirectly expands equity participation to broader employee pools.
Singapore
Sovereign wealth fund portfolio requirements and regional headquarters concentration drive sophisticated equity administration needs. The Monetary Authority of Singapore's guidelines on financial technology governance influence platform security standards. The city-state serves as deployment hub for Southeast Asian remote workforce equity plans.
Equity Management Tool Market Competitive Landscape
The competitive structure tilts toward vertically integrated suites displacing point solutions. Cloud-native entrants with API-first architectures challenge legacy providers dependent on manual implementation services. Two strategic archetypes dominate: full-stack platforms bundling valuation and compliance, and modular specialists scaling with early-stage headcount growth. Consolidation pressure intensifies as venture capital firms mandate standardized platforms across portfolio companies, compressing vendor selection windows.
Within the full-stack tier, Carta leverages its position across valuation services and compliance tracking to sustain pricing power. Pulley anchors the modular specialist archetype through onboarding configurations that scale with startup headcount growth. JP Morgan Workplace Solutions occupies a position bridging traditional financial services infrastructure with cloud-native delivery. These three represent distinct competitive vectors: vertical integration depth, startup-centric agility, and institutional-grade infrastructure heritage.
| Leading Market Players |
|---|
| Carta |
| Pulley |
| JP Morgan Workplace Solutions |
| Qapita |
| Ledgy |
| Astrella |
| Deel |
| OptionTrax |
| Trica |
| Others |
Pricing and Supply Chain Analysis
Venture capital-rolled platform specialists anchor supply behavior and pricing discipline in equity management tools, with investor-mandated standardization compressing vendor selection windows and sustaining subscription pricing power across portfolio company networks.
Pricing Analysis
Margin tightening in mid-market tiers reflects 409A valuation service bundling and compliance automation demands. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth and jurisdictional coverage. Cost-down pressure accelerates because seed-stage startups prioritize cash conservation and operational expenditure treatment. Early-stage companies exhibit highest price sensitivity; enterprise legal departments demonstrate lowest.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data center networks concentrated in the United States, Ireland, and Singapore. Engineering talent pools and API development frameworks constitute critical inputs alongside SOC 2 compliance certification pathways. Single-source vulnerability concentrates in valuation algorithm providers and multi-jurisdictional tax engine specialists. Distribution runs through direct SaaS sales teams and venture capital firm platform mandate programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform engineering talent scarcity props pricing across all tiers, constraining feature velocity for entrants and sustaining incumbent renewal rates.
For Market Incumbents: Extend API ecosystem depth to capture HRIS and payroll integration points before modular specialists consolidate adjacent workflows. Carta's vertical integration across valuation services demonstrates defensive positioning against compliance-tracking pure-plays. Capacity addition in Singapore and Frankfurt addresses data sovereignty fragmentation threatening cross-border contract renewals. For New Entrants and Emerging Players: The price-point gap between premium full-stack suites and economy cap-table-only tools creates entry space for mid-market configurations serving 200-2,000 employee companies. Grant administration automation for broad-based employee pools represents the most penetrable solution segment. Channel partnerships with regional law firms provide lower customer acquisition cost than direct enterprise sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-tracking specialists with IRS documentation engines in the United Kingdom and Germany. Long-term viability hinges on regulatory divergence across SEC, FCA, and BaFin disclosure requirements. Watch for venture capital firm platform mandate consolidation as inflection signal for vendor rollup opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded 409A Valuation Engine Development | Compresses appraisal timelines from weeks to days for growth-stage grant cycles. |
| Multi-Jurisdictional Tax Engine Expansion | Captures remote workforce equity compensation demand across GDPR-constrained corridors. |
| API-First HRIS Integration Partnership | Eliminates manual data reconciliation friction for IT-constrained startup buyers. |
| Real-Time Stakeholder Dashboard Launch | Displaces quarterly PDF reports with subscription-tier premium visibility revenue. |
| Mid-Market Configuration Tailoring | Addresses 200-2,000 employee whitespace underserved by startup or public-issuer solutions. |
Research Methodology
Multi-period observation of venture capital platform mandate patterns and cap table migration rates anchored the trend analysis, supplemented by interviews with equity plan administrators, corporate legal counsel, CTOs at growth-stage startups, and HRIS integration specialists. Secondary validation drew from SEC private market disclosure filings, IRS 409A documentation requirements, GDPR enforcement actions, and cloud software procurement databases. Bottom-up deployment modeling triangulated against top-down venture capital flow analysis.
Input-output matrices mapped deployment mode against solution maturity and organizational scale across the projection horizon. Segmentation dimensions modeled include cloud versus on-premise infrastructure, cap table management versus compliance tracking versus grant administration, and startup versus venture capital firm versus private equity use cases. CAGRs derived from installed base growth rates and average revenue per account expansion curves. Forecast inputs incorporated API connectivity adoption velocities and regulatory disclosure timeline accelerations.
Inputs from venture capital firm platform mandate programs were available through the study window; gaps in private company equity compensation disclosure granularity introduce uncertainty bands around compliance automation demand forecasts. Forecasts reflect documented assumptions regarding SEC rulemaking trajectories and data sovereignty enforcement intensities. Regulatory divergence across United States, United Kingdom, and German jurisdictions warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Asset Management System Market
Asset Management
India AMC Industry Market
Asset Management
Assets Under Management Market
Asset Management
Global Remote Asset Management Market
Asset Management
Global AI in Asset Management Market
Asset Management
Pension Fund Management Software Market
Asset Management
APAC Mutual Fund Market
Asset Management
Japan Asset Management Market
Asset Management
Mutual Fund Assets Market
Asset Management
Fund Management Fee Market
Asset Management
Capital Expenditure Market
Asset Management
Smart Asset Management Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
Global Asset Performance Management Market
Asset Management
Fixed Income Asset Management Market
Asset Management
US Asset Management Market