
 Asset Optimization Solutions Market | 2026-2036
Asset Optimization Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Asset Optimization Solutions Market Intelligence
The capital-intensity divergence between full-stack platform providers and point-solution vendors is redrawing competitive boundaries in asset optimization. SAP leverages its ERP backbone to anchor enterprise-wide asset lifecycle management across process industries. IBM Maximo sustains deep technical moats in predictive maintenance through decades of industrial IoT integration. Eptura competes by unifying workplace and asset data streams for facilities-intensive organizations.
Asset optimization solutions encompass software platforms, analytics engines, and connected sensor networks that monitor equipment health, schedule maintenance interventions, and allocate capital across physical asset portfolios. These systems typically process vibration, thermal, and operational telemetry at sub-second intervals to forecast failure modes before critical downtime occurs. Predictive maintenance leads solution spending as manufacturers prioritize uptime guarantees over periodic inspection regimes. Cloud-based deployment is expanding fastest among mid-market adopters seeking to bypass on-premises infrastructure costs. Energy optimization commands premium pricing in utilities and heavy industry where fuel and power inputs dominate operating expenditures.
ISO 55000 frameworks shape enterprise procurement standards by mandating systematic risk-based asset management governance. The EPA enforces emissions monitoring requirements that drive energy optimization investments across US industrial facilities. EU CSRD disclosure rules compel European asset owners to quantify and report physical infrastructure climate risks. Stakeholders must monitor how evolving sustainability mandates rewrite software evaluation criteria and channel deployment preferences toward platforms with embedded carbon accounting modules.
Market Dynamics
Cloud-native predictive maintenance architectures are compressing deployment timelines from quarters to weeks, forcing incumbent platform providers to rearchitect delivery models or cede mid-market share to software-as-a-service specialists.
Growth Catalysts
- ISO 55000 compliance mandates:Asset-intensive enterprises in Germany and the United States are rewriting procurement specifications to require certified asset management governance frameworks, elevating platform vendors with embedded audit trails.
- Process industry uptime guarantees:Petrochemical and refining operators are replacing calendar-based inspection regimes with continuous vibration and thermal monitoring to eliminate unplanned shutdowns.
- China's infrastructure modernization wave:State-owned steel and power generators are deploying connected sensor networks across aging equipment fleets to extend operational lifespans.
Market Restraints
- Semiconductor supply concentration:Industrial IoT sensor production depends on Taiwanese and South Korean chip fabrication capacity, creating procurement bottlenecks during supply shocks.
- Cybersecurity certification delays:IEC 62443 industrial control system security standards impose lengthy validation timelines that stall platform rollouts in critical infrastructure sectors.
- Legacy SCADA integration friction:Decades-old proprietary protocols in heavy manufacturing limit real-time data interoperability with modern analytics engines.
Strategic Opportunities
- India's PLI-linked manufacturing expansion:Electronics and pharmaceutical production incentives are creating first-mover advantage for asset optimization vendors establishing local cloud infrastructure.
- EU CSRD physical risk disclosure:Mandatory climate vulnerability reporting is opening premium pricing for platforms with embedded carbon accounting and scenario modeling modules.
- Edge-AI convergence with 5G private networks:Ultra-low latency inference at the equipment level enables sub-second failure prediction that cloud-only architectures cannot match.
Industry Challenges
- Reliability engineering talent scarcity:Industrial facilities struggle to hire data scientists capable of translating vibration spectra into actionable maintenance schedules.
- Multi-vendor system integration complexity:Enterprises running SAP, Siemens, and Emerson stacks simultaneously face prohibitive customization costs for unified dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asset Optimization Solutions Market |
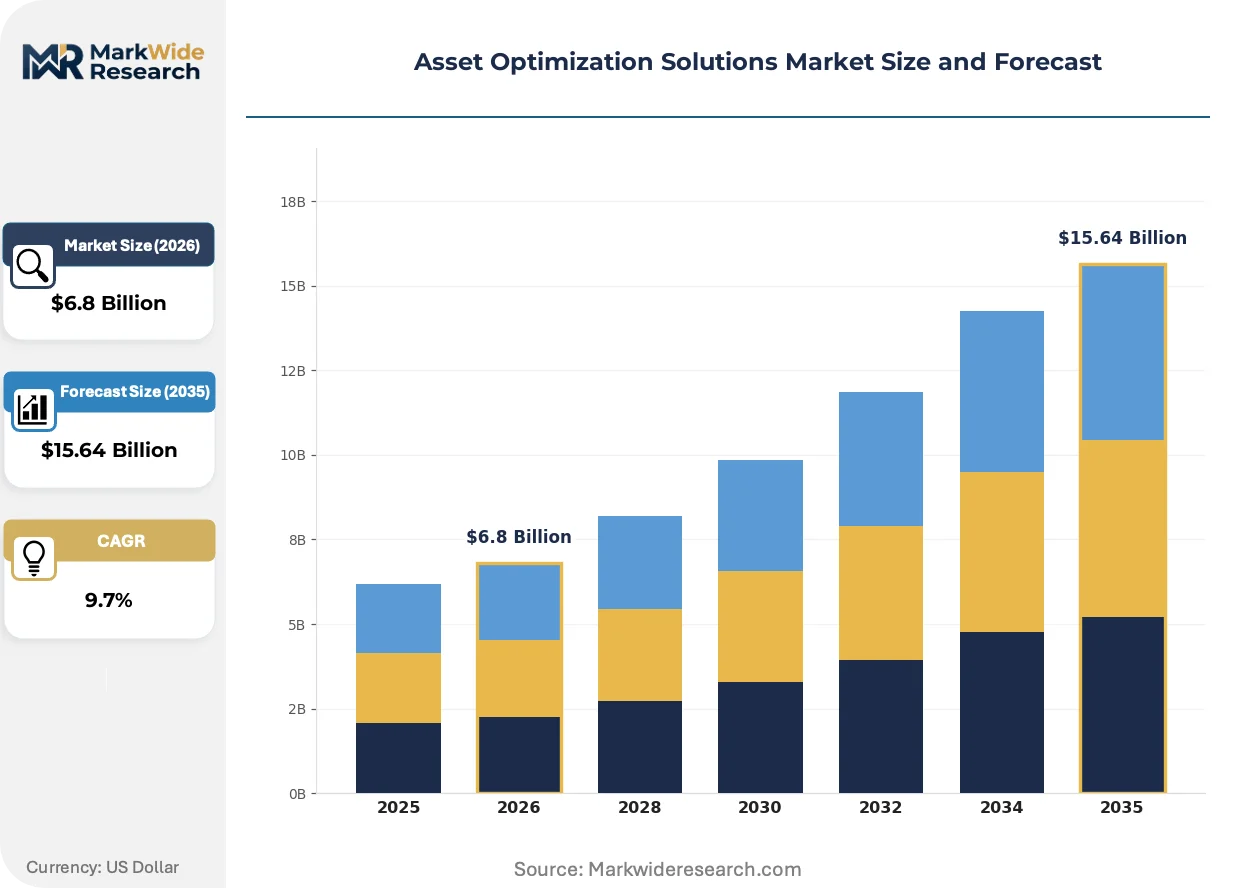
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.64 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Predictive Maintenance, Asset Tracking, Performance Management, Energy Optimization End User: Manufacturing, Transportation, Facilities Management, Utilities Deployment: On-Premises, Cloud-Based, Hybrid, Remote Monitoring Solution: Software Suite, Analytics Tool, Dashboard Solution, Consultation Services |
| Companies Covered | SAP, Asset Infinity, IBM Maximo, Eptura, Ivanti, Microsoft Dynamics 365, Accruent, IFS, ServiceNow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asset Optimization Solutions Market Strategic Shifts & Innovations
Digital twin fidelity is advancing from geometric visualization to physics-informed simulation, enabling operators to test maintenance interventions virtually before committing capital to physical execution.
Physics-informed neural networks are displacing purely statistical anomaly detection in rotating equipment monitoring. Turbomachinery operators in Texas and Alberta are adopting these hybrid models to capture failure modes absent from historical training data. The technology is displacing rule-based threshold alerting that generated excessive false positives and eroded technician trust.
EPA emissions monitoring enforcement under the Clean Air Act is compelling US refineries and chemical plants to integrate energy optimization modules with predictive maintenance platforms. Facilities must demonstrate continuous compliance with permit limits or face operating restrictions. This regulatory pressure is accelerating procurement of combined asset-performance-and-emissions suites that vendors previously sold separately.
Mid-market manufacturers are abandoning perpetual license purchases for consumption-based platform subscriptions that scale with sensor count. Distributors and system integrators are restructuring compensation to prioritize recurring revenue over upfront implementation fees. This behavioral shift is most pronounced among German Mittelstand firms seeking to preserve balance sheet flexibility during capital equipment upgrade cycles.
Asset Optimization Solutions Market Segmentation
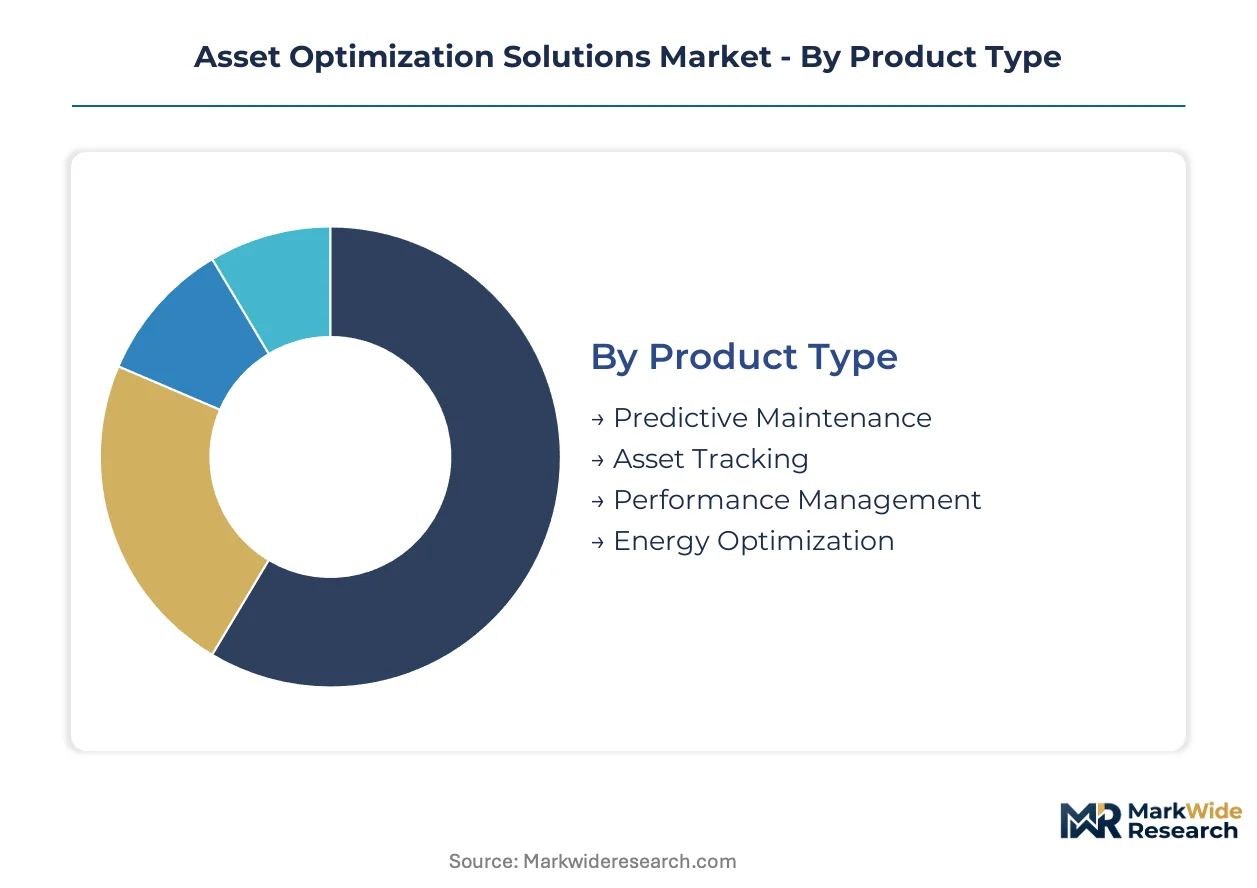
Asset optimization solutions fragment across four intersecting dimensions that determine pricing architecture and deployment complexity. Product type and deployment mode together shape margin capture, while end-user verticals and solution packaging dictate sales cycle length and renewal economics.
Product Type:
Premium margin pools concentrate in modules that combine hardware telemetry with algorithmic failure prediction rather than standalone software licenses.
- Predictive Maintenance:Vibration, thermal, and acoustic sensors feed physics-informed neural networks to forecast equipment failures before critical downtime. Petrochemical operators in Texas and Alberta are replacing rule-based threshold alerting with these hybrid models to eliminate false positives that eroded technician trust.
- Energy Optimization:Real-time power consumption analytics identify load-balancing opportunities and emissions compliance gaps across industrial facilities. US refineries facing EPA Clean Air Act enforcement are procuring combined asset-performance-and-emissions suites that vendors previously sold separately.
- Asset Tracking:RFID and GPS-enabled location monitoring for mobile equipment fleets and spare parts inventory.
- Performance Management:KPI dashboards benchmarking asset utilization against operational targets and ISO 55000 governance standards.
Predictive Maintenance holds installed capacity. Energy Optimization is rotating up the share rankings.
End User:
Volume concentration follows capital intensity and regulatory pressure rather than facility count.
- Manufacturing:Discrete and process manufacturers deploy continuous monitoring to convert calendar-based inspection regimes into condition-based interventions. German Mittelstand firms are shifting from perpetual licenses to consumption-based subscriptions that preserve balance sheet flexibility during equipment upgrade cycles.
- Utilities:Power generators and grid operators optimize aging infrastructure lifespans through connected sensor networks. State-owned steel and power operators in China are modernizing equipment fleets to extend operational longevity.
- Transportation:Fleet operators and rail networks tracking vehicle health and route efficiency.
- Facilities Management:Commercial real estate and healthcare campuses unifying workplace and asset data streams.
Manufacturing commands the largest deployment base. Utilities are climbing the fastest as infrastructure ages and emissions rules tighten.
Deployment:
Customer type and IT maturity determine architecture preference more than industry vertical.
- Cloud-Based:Subscription models compress deployment timelines from quarters to weeks, enabling mid-market adopters to bypass on-premises infrastructure costs. Mid-market manufacturers across Germany and the United States are abandoning capital-intensive implementations for sensor-count-scaled pricing.
- Hybrid:Sensitive operational data remains on-premises while analytics and reporting migrate to cloud infrastructure. Critical infrastructure operators facing IEC 62443 cybersecurity certification delays favor this architecture to isolate control systems from external exposure.
- On-Premises:Fully captive infrastructure for facilities with stringent data sovereignty or air-gapped security requirements.
- Remote Monitoring:Vendor-managed operations centers handling alert triage and maintenance dispatch.
On-Premises retains the legacy footprint. Cloud-Based is displacing fastest among new procurement decisions.
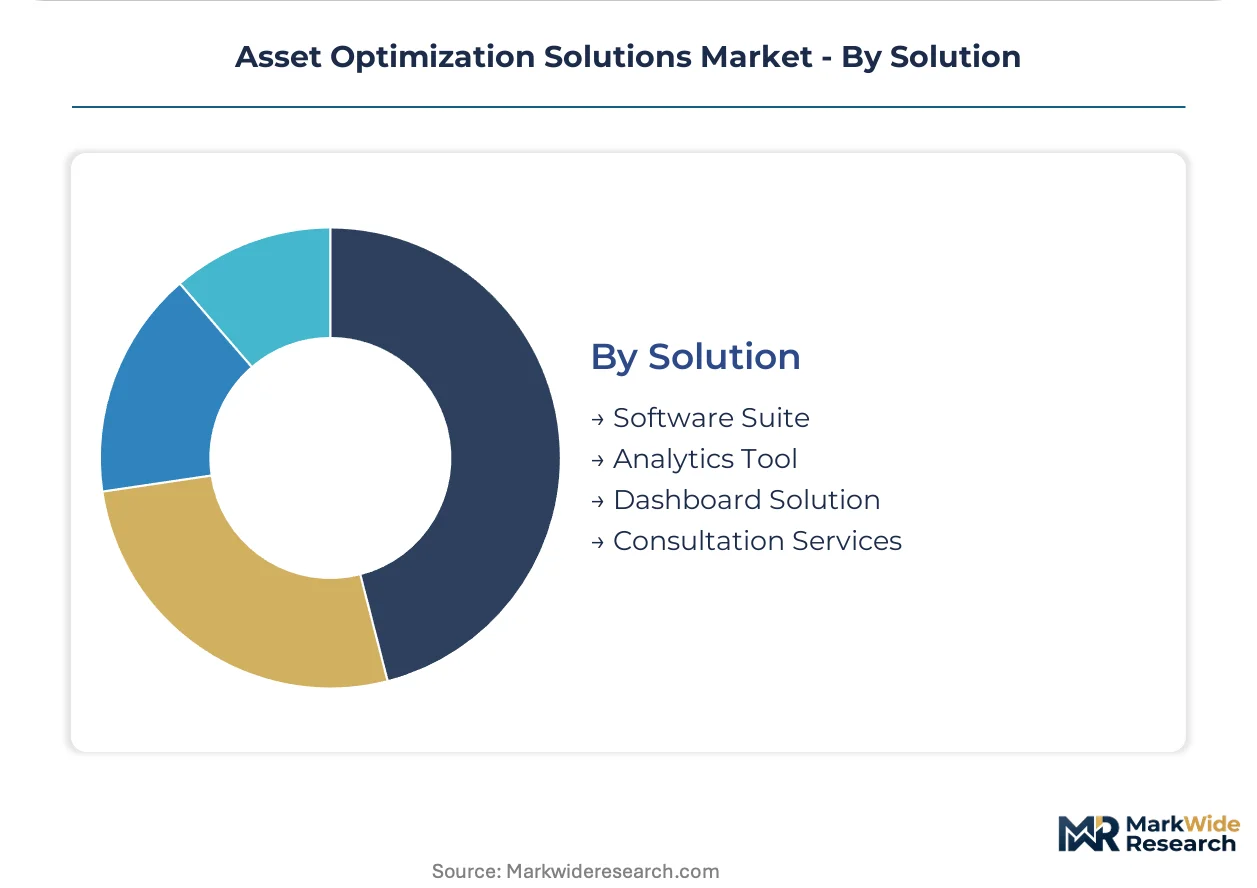
Solution:
Packaging strategy separates platform consolidators from specialized tool vendors.
- Software Suite:Integrated modules spanning maintenance scheduling, spare parts management, and capital planning. ERP-anchored providers leverage existing enterprise relationships to embed asset lifecycle management across process industries.
- Analytics Tool:Point solutions delivering specific capabilities like vibration analysis or thermal imaging interpretation.
- Dashboard Solution:Visualization layers aggregating multi-vendor data streams into unified operational views.
- Consultation Services:Implementation support, reliability engineering training, and ISO 55000 compliance advisory.
Software Suite dominates enterprise accounts. Analytics Tool is gaining traction where best-of-breed specialization outweighs integration overhead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asset optimization deployment patterns diverge sharply by geography. US manufacturers prioritize predictive maintenance uptime guarantees. German industrial buyers embed ISO 55000 governance into procurement specifications. Chinese state enterprises modernize aging infrastructure through connected sensor networks at scale.
United States
Petrochemical operators in Texas and Louisiana are replacing calendar-based inspection regimes with continuous vibration monitoring to eliminate unplanned shutdowns. EPA Clean Air Act enforcement compels refineries to integrate emissions compliance modules with asset performance platforms. The Houston Ship Channel cluster anchors North American demand for combined predictive maintenance and energy optimization suites.
Germany
Mittelstand manufacturers are abandoning perpetual software licenses for consumption-based subscriptions that preserve balance sheet flexibility during equipment upgrade cycles. ISO 55000 compliance mandates rewrite procurement specifications to require certified asset management governance frameworks. The Ruhr industrial belt and Bavarian automotive corridors concentrate deployment of ERP-anchored asset lifecycle management systems.
China
State-owned steel and power generators are deploying connected sensor networks across aging equipment fleets to extend operational lifespans. MIIT industrial internet policies accelerate cloud-native platform adoption among infrastructure operators. The Yangtze River Delta and Pearl River Delta manufacturing clusters drive volume demand for remote monitoring and edge-AI convergence solutions.
India
Electronics and pharmaceutical production incentives under the PLI scheme create first-mover advantage for vendors establishing local cloud infrastructure. CEA grid modernization directives push utilities toward predictive maintenance for aging transmission assets. The Maharashtra and Gujarat industrial corridors concentrate mid-market manufacturing adoption of subscription-based deployment models.
United Kingdom
North Sea oil and gas operators are retrofitting offshore platforms with predictive maintenance systems to reduce helicopter-dependent maintenance trips. EU CSRD-aligned disclosure requirements compel asset owners to quantify physical infrastructure climate risks. The Aberdeen energy cluster and Midlands manufacturing belt anchor British demand for hybrid cloud deployment architectures.
Asset Optimization Solutions Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in asset optimization solutions. Full-stack platform providers leverage ERP backbones and decades of industrial IoT integration to anchor enterprise-wide contracts. Point-solution vendors compete through best-of-breed specialization in vibration analysis, thermal imaging, or emissions compliance modules. Dominant competitive moves include cloud-native rearchitecture to compress deployment timelines and strategic partnerships with system integrators to bypass direct sales overhead.
Within the integrated platform tier, SAP and IBM Maximo exemplify archetypes that embed asset lifecycle management within broader enterprise software ecosystems. Eptura occupies a position unifying workplace and asset data streams for facilities-intensive organizations. These three represent the strategic spectrum from ERP-anchored consolidation to vertical specialization.
| Leading Market Players |
|---|
| SAP |
| Asset Infinity |
| IBM Maximo |
| Eptura |
| Ivanti |
| Microsoft Dynamics 365 |
| Accruent |
| IFS |
| ServiceNow |
| Others |
Cost & Logistics Intelligence
ISO 55000 certification requirements gate both vendor qualification and price tiering simultaneously, compelling asset-intensive buyers to pay premiums for platforms with embedded audit trails while excluding uncertified competitors from enterprise procurement shortlists. Cloud-native delivery is compressing deployment timelines and enabling consumption-based models that preserve buyer balance sheet flexibility.
Pricing Analysis
Long-term subscription contracts dominate enterprise procurement, displacing perpetual licenses as German Mittelstand manufacturers and US mid-market adopters prioritize sensor-count-scaled SaaS tiers over capital-intensive implementations. Price differentiation rests on ISO 55000 certification tier and embedded carbon accounting module availability, with integrated suites commanding premiums over point-solution vendors. Cost compression in the mid-market tier is intensifying because cloud-native specialists are bypassing on-premises infrastructure costs that anchored incumbent pricing. Price sensitivity concentrates among facilities management and transportation verticals seeking dashboard-layer aggregation without full-stack platform investment.
Supply Chain Analysis
Strategic stockpiling of industrial IoT sensors is accelerating among critical infrastructure operators seeking to buffer against semiconductor supply volatility, while cloud-native vendors maintain lean inventory through just-in-time firmware delivery models. Hardware component supply draws from Taiwan, South Korea, and China for sensor chip fabrication, with edge-AI inference modules resting on NVIDIA and Qualcomm silicon availability. Single-source vulnerability in Taiwanese foundry capacity creates procurement bottlenecks during supply shocks. Distribution runs through system integrators and OEM channel partners that embed asset optimization modules within broader digital transformation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
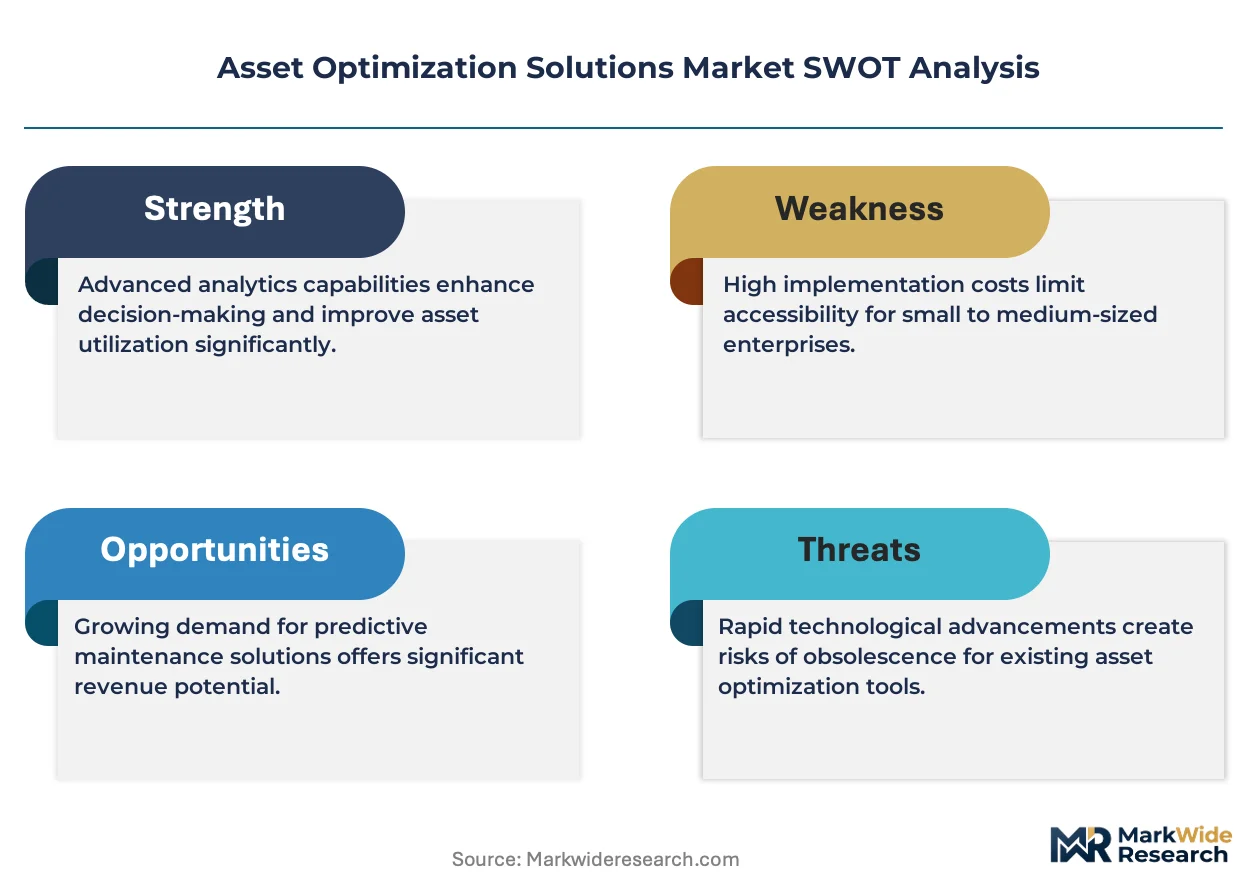
Platform economics in asset optimization are approaching an interoperability inflection as ERP-anchored incumbents battle API-native specialists for control of the maintenance workflow data layer. Buyers are consolidating vendor relationships around unified data lakes that span operational technology and enterprise resource planning systems.
For Market Incumbents: Consolidate position by acquiring edge-AI inference specialists to match sub-second failure prediction capabilities that 5G private networks now enable. Deepen SAP and IBM Maximo integration partnerships to lock out point-solution vendors from enterprise-wide asset lifecycle management contracts. Prioritize ISO 55000 certification fast-track investments to maintain procurement specification compliance as German and US buyers rewrite vendor qualification criteria.
For New Entrants and Emerging Players: IEC 62443 cybersecurity fast-track certification opens critical infrastructure segments where lengthy validation timelines stall incumbent platform rollouts. White-space targets include India's PLI-linked electronics manufacturing corridors and EU CSRD-aligned carbon accounting modules for physical risk disclosure mandates. A channel-native go-to-market strategy through hyperscaler marketplaces bypasses direct sales overhead that burdens full-stack competitors.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates spinning off non-core software units with captive maintenance workflows in petrochemical and power generation verticals. Long-term viability favors platforms with physics-informed neural network IP and embedded emissions compliance modules that EPA enforcement is making non-negotiable. Watch for inflection when edge-AI inference latency thresholds cross sub-second reliability benchmarks that cloud-only architectures cannot match.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP-anchored consolidation captures enterprise-wide asset lifecycle contracts across process industries. |
| Certification Investment | ISO 55000 and IEC 62443 compliance gates procurement shortlists in German and critical infrastructure sectors. |
| Edge-AI Acquisition | Sub-second inference capability matches 5G private network latency requirements for rotating equipment monitoring. |
| Carbon Module Development | Embedded accounting satisfies EU CSRD physical risk disclosure and EPA Clean Air Act enforcement convergence. |
| Geographic Expansion | Local cloud infrastructure in India PLI corridors captures first-mover advantage in electronics manufacturing. |
Research Approach
Operator-level perspectives from maintenance directors, plant engineers, reliability engineering leads, and IT procurement officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC filings from industrial software vendors, EPA enforcement action databases, EU CSRD disclosure registries, and ISO 55000 certification directories. Bottom-up sensor deployment estimates triangulated against top-down enterprise software spending benchmarks.
Sensitivity analysis tested forecast robustness across deployment model migration speeds, semiconductor supply shock durations, and regulatory enforcement intensity scenarios. Segmentation dimensions spanned product type, end-user vertical, deployment architecture, and solution packaging complexity. CAGRs derived from logistic diffusion curves fitted to cloud adoption patterns and capital expenditure cycles across manufacturing, utilities, and facilities management sectors. Physics-informed neural network penetration rates and edge-AI hardware cost curves informed technology adoption assumptions.
Underlying assumptions cover sustained EPA emissions enforcement, continued ISO 55000 procurement mandate expansion, and stable Taiwan-South Korea semiconductor fabrication capacity, with deviation risk concentrated in geopolitical supply disruptions and cybersecurity certification timeline extensions. Revision becomes warranted when edge-AI inference cost thresholds cross cloud-native economics or when EU CSRD disclosure requirements expand beyond physical infrastructure to encompass supply chain Scope 3 emissions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Europe Asset Management Market
Asset Management
Fixed Income Asset Management Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
Mutual Fund Assets Market
Asset Management
Fund Management Fee Market
Asset Management
Fund Management Software Market
Asset Management
India AMC Industry Market
Asset Management
Asset Management System Market
Asset Management
India Mutual Fund Market
Asset Management
Pension Fund Management Software Market
Asset Management
Capital Expenditure Market
Asset Management
Japan Asset Management Market
Asset Management
Global Remote Asset Management Market
Asset Management
US Asset Management Market
Asset Management
Equity Management Tool Market
Asset Management
India Asset Management Market