
 APAC Mutual Fund Market | 2026-2036
APAC Mutual Fund Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Mutual Fund Market Insights
Institutional buyer concentration is hardening across sovereign wealth funds and pension pools in the region. BlackRock leverages its ETF infrastructure to anchor liquidity in developed Asia-Pacific corridors. Mitsubishi UFJ Asset Management sustains dominance in Japan's domestic fixed-income landscape through captive banking distribution. Mirae Asset Global Investments positions aggressively in emerging market equity mandates from Seoul.
A mutual fund pools capital from multiple investors to purchase diversified portfolios of securities, operating under specific mandate constraints around asset allocation, liquidity thresholds, and fee structures. Its primary commercial purpose delivers professional asset management with risk dispersion to investors lacking scale for direct portfolio construction. Equity Funds lead product-type flows as retail participation broadens, while Money Market Funds attract flight capital during volatility spikes. Online Platforms represent the fastest-growing distribution channel, compressing traditional bank-dominant access models across Indonesia and Vietnam.
SEBI in India enforces strict disclosure norms and expense-ratio caps that shape product economics and distributor incentives across the subcontinent. China's CSRC and Japan's FSA impose divergent redemption-gate and liquidity-management standards that fragment cross-border fund passporting. Australia's ASIC and South Korea's FSC add layers of retail-investor protection that elevate compliance costs for foreign entrants. Stakeholders must monitor evolving fund passport agreements between ASEAN member states and anticipate which regulatory harmonization pathway unlocks scale.
Market Dynamics
SEBI's expense-ratio caps and CSRC's liquidity-management mandates are compressing distributor economics while accelerating direct-to-investor platform adoption across the region's largest fund pools.
Growth Catalysts
- SEBI's FPI Liberalization Framework:India's easing of foreign portfolio investment norms unlocks deeper capital deployment from sovereign wealth funds into domestic equity schemes.
- Online Platform Infrastructure:Digital distribution channels in Indonesia and Vietnam bypass legacy bank-dominated access models, slashing customer acquisition costs for fund houses.
- Pension Pool Expansion:Japan's Government Pension Investment Fund and Australia's superannuation system channel institutional mandates into diversified mutual fund vehicles.
Market Restraints
- Redemption-Gate Fragmentation:Divergent CSRC and FSA liquidity standards fragment cross-border fund passporting, trapping capital in jurisdiction-specific vehicles.
- Distribution Cost Compression:SEBI's total expense ratio caps squeeze trail commissions, forcing distributors toward volume-dependent advisory models.
- Currency Hedging Burden:ASEAN-domiciled funds face elevated swap costs when offering USD- or EUR-denominated share classes to regional investors.
Strategic Opportunities
- Vietnam's Underserved Retail Base:Mutual fund penetration remains below 5% of household financial assets, creating first-mover advantages for digital-native distributors.
- ASEAN Fund Passport Activation:Cross-border marketing permissions between Thailand, Malaysia, and Singapore enable unified product structuring across 650 million consumers.
- ESG Mandate Convergence:Australia's ASIC disclosure requirements and Japan's stewardship code are pulling capital into sustainable equity strategies.
Industry Challenges
- Legacy System Integration:Established asset managers in Japan and South Korea struggle to embed real-time NAV calculation engines within mainframe-dependent operations.
- Cross-Border Compliance Talent:Shortage of professionals fluent in both SEBI's disclosure architecture and CSRC's filing protocols limits product launch velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Mutual Fund Market |
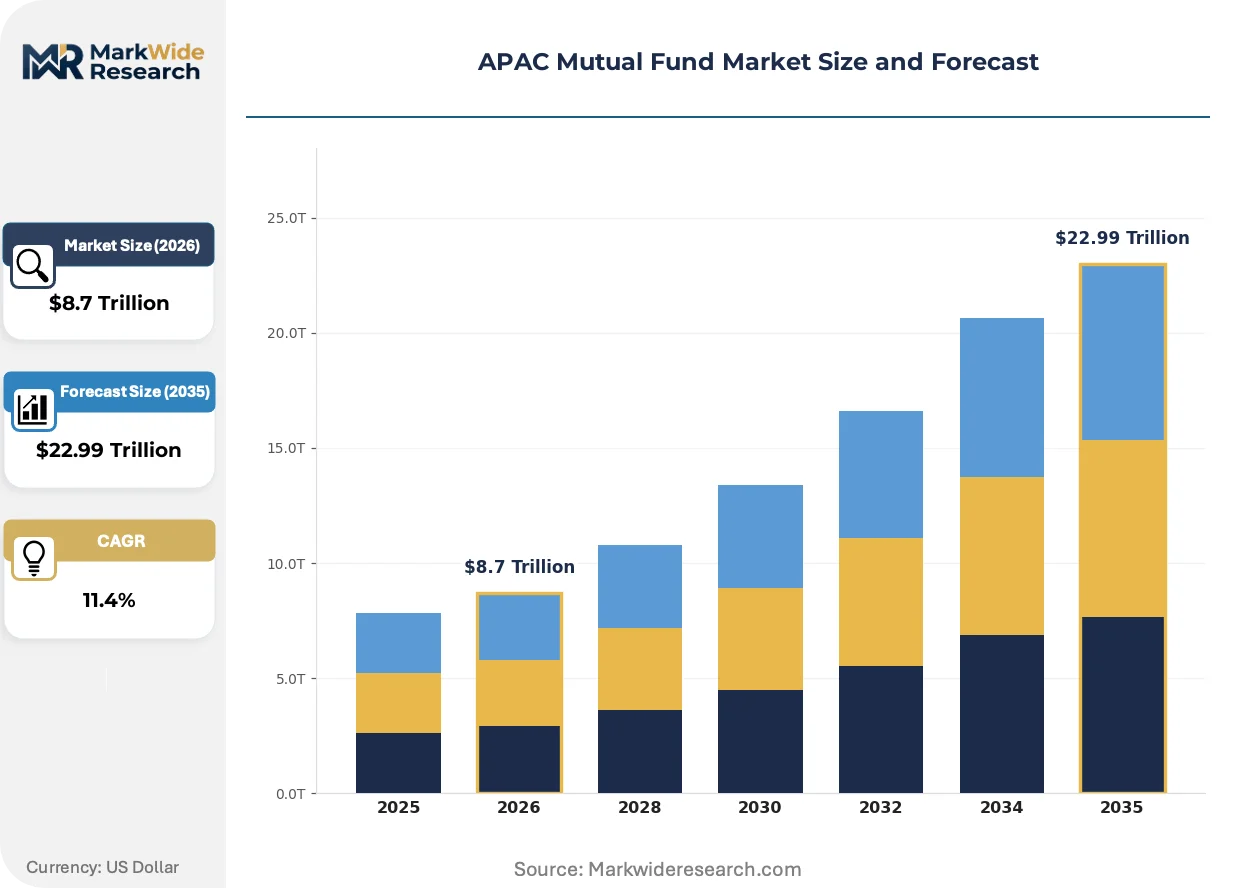
| Market Size in 2026 | $8.7 Trillion |
| Market Size in 2035 | $22.99 Trillion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Equity Funds, Debt Funds, Balanced Funds, Money Market Funds Investor Type: Individual Investors, Institutional Investors, High Net Worth Individuals, Retail Investors Fund Size: Small Cap, Mid Cap, Large Cap, Micro Cap Distribution Channel: Direct Sales, Financial Advisors, Banks, Online Platforms |
| Companies Covered | China Asset Management, BlackRock, JPMorgan Asset Management, Mitsubishi UFJ Asset Management, Nippon Life India Asset Management, Mirae Asset Global Investments, HDFC Asset Management, Fidelity, Allianz Global Investors, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Mutual Fund Market Trends and Innovations
Algorithmic portfolio construction and tokenized fund units are dismantling traditional custody and settlement hierarchies across Asia-Pacific's largest asset management hubs.
Artificial intelligence-driven risk scoring engines are rewriting how portfolio managers construct multi-asset mandates. Japanese mega-banks and Korean securities houses deploy these tools to automate duration matching across sovereign bond exposures. The compression of model-development cycles is forcing traditional quant teams to retool around machine-learning pipelines.
CSRC's tightened liquidity-management guidelines for money market funds impose daily asset-maturity reporting and stress-testing protocols. Asset managers must now maintain higher buffers of overnight repo and central bank reserves. Smaller fund houses in China's tier-two cities face compliance cost escalation that favors scale players.
Retail investors across India's metropolitan centers and Southeast Asian urban corridors now execute 70% of mutual fund subscriptions through mobile-first platforms. Robo-advisory interfaces displace branch-based relationship managers for entry-level SIP commitments. This behavioral pivot concentrates platform power with technology infrastructure providers rather than traditional distributor networks.
APAC Mutual Fund Market Segmentation
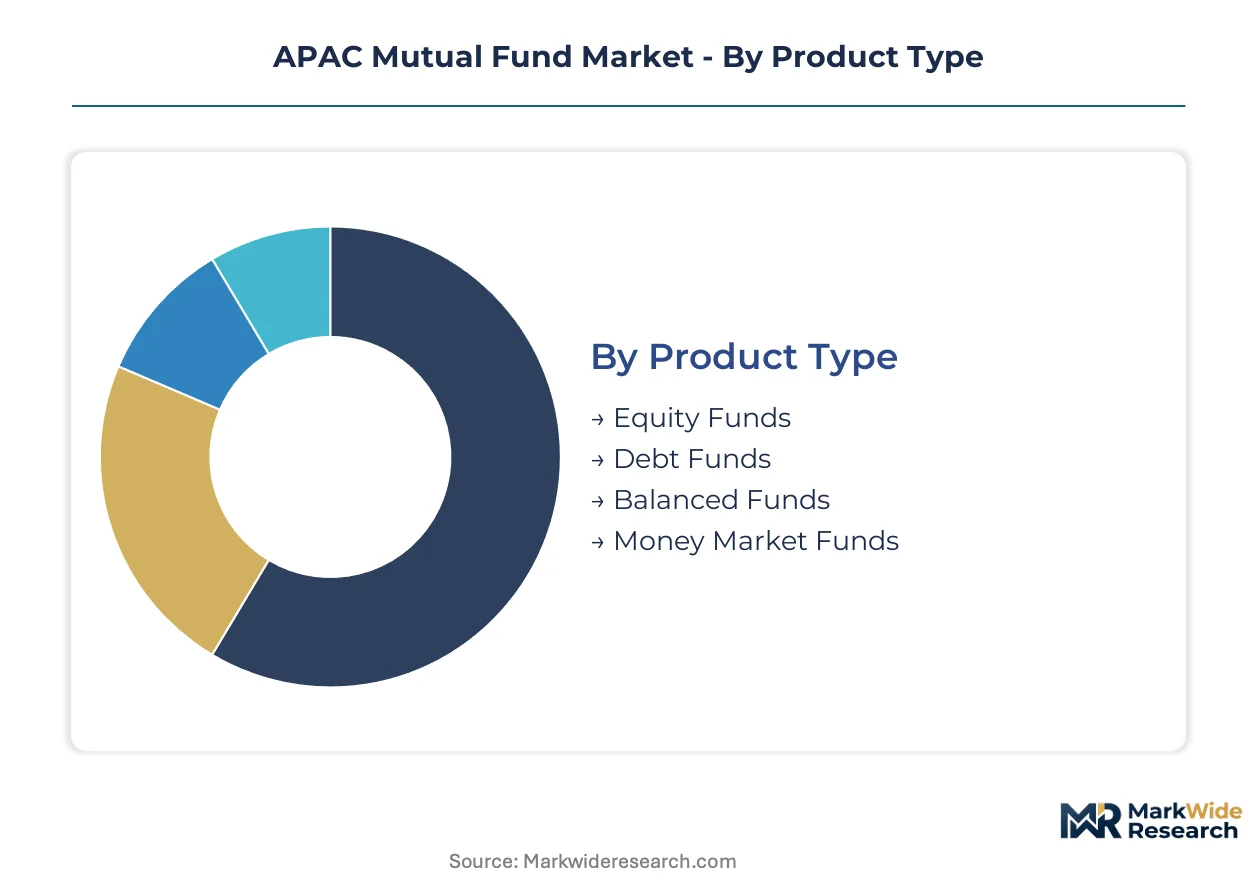
Mutual fund segmentation across Asia-Pacific reflects divergent regulatory architectures, distribution infrastructure maturity, and investor sophistication levels. Product structuring and channel economics vary sharply between developed markets like Japan and Australia versus emerging pools in Vietnam and Indonesia. Understanding these fault lines enables asset managers to calibrate fee structures, liquidity provisions, and marketing permissions.
Product Type:
Asset class specifications determine liquidity thresholds, expense ratio caps, and redemption gate protocols under national securities regulators.
- Equity Funds:These vehicles allocate capital primarily to listed stocks across market capitalizations, subject to SEBI's 2.25% total expense ratio ceiling for equity schemes in India. Demand concentrates in India's urban centers and China's tier-one cities where retail participation is deepening, driven by SIP automation and mobile platform penetration.
- Debt Funds:Fixed-income portfolios hold sovereign bonds, corporate credit, and money market instruments with duration-matched maturity profiles. India's SEBI mandates strict credit-quality disclosures and liquidity coverage ratios, compressing yields but attracting institutional treasury allocations from corporate balance sheets.
- Money Market Funds:CSRC imposes daily asset-maturity reporting and stress-testing protocols that elevate compliance costs for smaller fund houses.
- Balanced Funds:Hybrid mandates blend equity and debt exposures with automatic rebalancing triggers.
Mature deployment sits with Debt Funds. Newer deployment is concentrated in Equity Funds.
Investor Type:
Customer segmentation follows wealth thresholds, decision-making autonomy, and advisory dependence patterns across the region.
- Retail Investors:Individual subscribers committing systematic investment plans through mobile platforms now dominate flow volumes across Indonesia and Vietnam. Robo-advisory interfaces displace branch-based relationship managers for entry-level commitments, compressing distribution costs toward sub-50 basis points.
- Institutional Investors:Sovereign wealth funds, pension pools, and insurance mandates deploy block capital into segregated accounts with customized liquidity terms. Japan's Government Pension Investment Fund channels substantial allocations into domestic fixed-income and global equity index trackers.
- High Net Worth Individuals:Family offices and ultra-high-net-worth segments demand tailored tax-efficient structures across Singapore and Hong Kong domiciles.
- Individual Investors:Mass-affluent segments rely on distributor recommendations with trail-commission economics.
Institutional capital anchors liquidity in developed corridors. Retail flows are expanding most quickly in Southeast Asian markets.
Fund Size:
Market capitalization targeting aligns with risk-return profiles and benchmark selection methodologies.
- Large Cap:Blue-chip equity mandates track established indices with lower volatility coefficients and deeper secondary market liquidity. Australian superannuation funds favor these vehicles for core equity allocations given their governance requirements for liquid, transparent holdings.
- Mid Cap:Growth-oriented portfolios target companies with established business models but expansion runway, particularly in India's manufacturing and services sectors. SEBI's categorization norms require minimum 65% allocation to mid-cap defined stocks.
- Small Cap:Higher volatility exposure attracts tactical allocations from domestic investors in South Korea and Taiwan.
- Micro Cap:Frontier equity segments face liquidity constraints and limited analyst coverage.
Large Cap vehicles dominate asset-weighted industry AUM. Micro Cap strategies are gaining share fastest among risk-tolerant domestic investors.
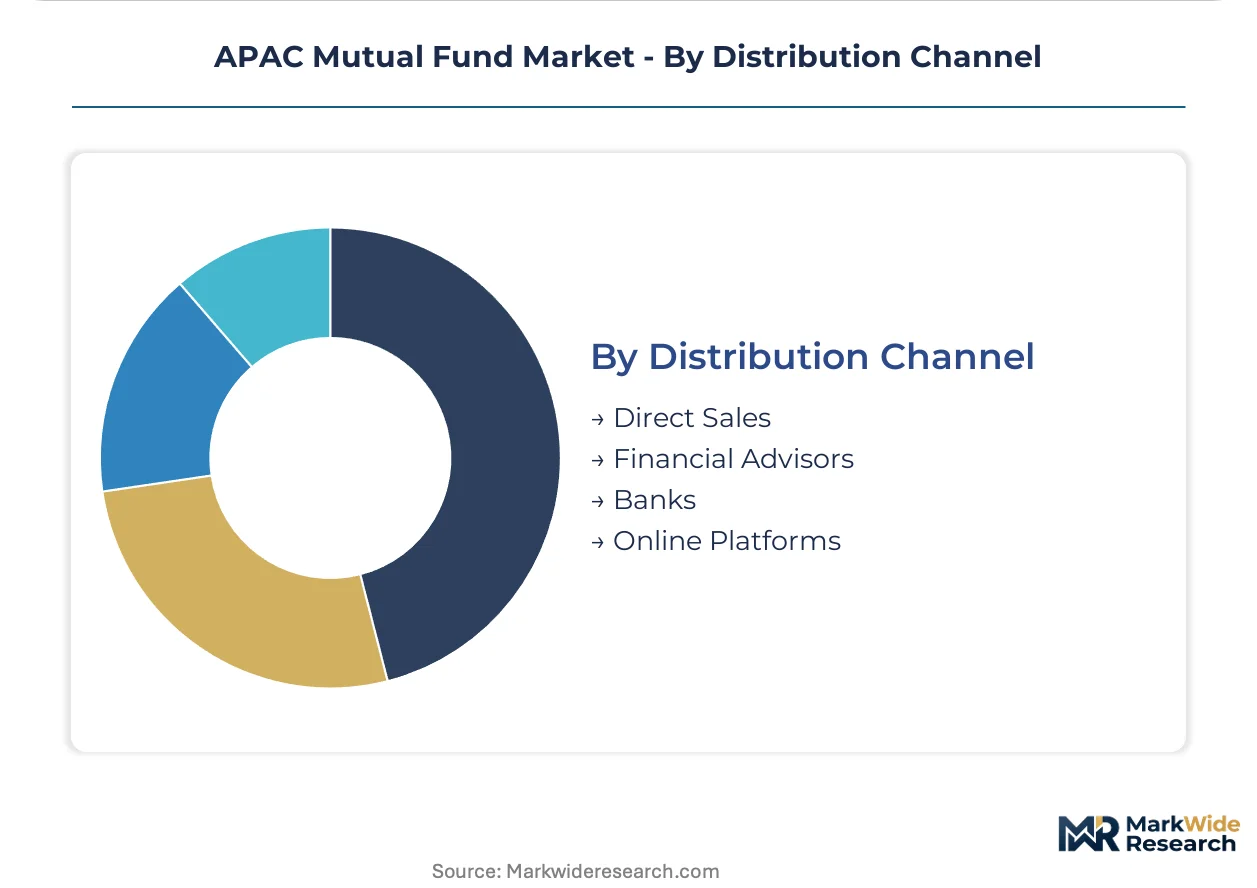
Distribution Channel:
Access infrastructure determines customer acquisition economics and investor education burdens.
- Online Platforms:Digital-native distributors bypass legacy bank networks with API-integrated onboarding and real-time NAV visibility. Indonesian fintech platforms and Indian wealth-tech aggregators now capture 70% of new SIP registrations through mobile-first interfaces.
- Banks:Captive distribution through Mitsubishi UFJ and other mega-bank networks sustains dominance in Japan's domestic fixed-income landscape, leveraging branch infrastructure and trust banking relationships.
- Financial Advisors:Independent distributors face margin compression from SEBI's expense-ratio caps, forcing migration toward fee-based advisory models.
- Direct Sales:Fund house proprietary channels eliminate intermediary economics but require substantial marketing investment.
Bank networks retain structural advantages in Japan and Australia. Online Platforms are climbing the fastest across emerging Southeast Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's urban centers and China's tier-one cities concentrate mutual fund demand, while Tokyo and Sydney anchor institutional liquidity pools. SEBI's regulatory liberalization and CSRC's liquidity mandates reshape capital flows across these corridors.
India
Systematic investment plans through mobile platforms now capture 70% of new retail subscriptions in Mumbai and Delhi-NCR. SEBI's expense-ratio caps compress distributor margins while accelerating direct-to-investor adoption. Bangalore's fintech clusters host wealth-tech aggregators that bypass traditional bank distribution networks.
China
Tier-one cities including Shanghai and Shenzhen drive equity fund flows as retail participation broadens beyond property-heavy portfolios. CSRC mandates daily asset-maturity reporting and stress-testing protocols for money market funds. Beijing's asset management hubs absorb compliance cost escalations that squeeze smaller fund houses in tier-two cities.
Japan
The Government Pension Investment Fund channels substantial institutional mandates into domestic fixed-income and global equity trackers. FSA liquidity standards diverge from regional norms, fragmenting cross-border fund passporting. Tokyo's mega-bank networks sustain captive distribution dominance through trust banking relationships.
Australia
Superannuation system inflows anchor core equity allocations toward large-cap mandates with governance-mandated liquidity requirements. ASIC disclosure requirements elevate compliance costs for foreign entrants while pulling capital into sustainable strategies. Sydney and Melbourne fund houses concentrate ESG-mandate product development.
Vietnam
Mutual fund penetration remains below 5% of household financial assets, creating first-mover advantages for digital-native distributors. Ho Chi Minh City and Hanoi concentrate mobile-first platform adoption that compresses customer acquisition costs. Indonesian fintech expansion patterns suggest similar trajectory acceleration.
APAC Mutual Fund Market Competitive Landscape
Established asset managers occupy the standard tier; emerging fintech platforms pursue direct-to-investor channels. The market structures around three archetypes: mega-bank captive distributors, independent global asset managers, and digital-native wealth-tech aggregators. Competitive moves concentrate on ETF infrastructure expansion and mobile platform API integration.
Among global asset managers, BlackRock anchors liquidity infrastructure across developed Asia-Pacific corridors. Mitsubishi UFJ Asset Management occupies a position within Japan's domestic fixed-income landscape through captive banking distribution. Mirae Asset Global Investments exemplifies emerging market equity mandate specialization from Seoul-based operations.
| Leading Market Players |
|---|
| China Asset Management |
| BlackRock |
| JPMorgan Asset Management |
| Mitsubishi UFJ Asset Management |
| Nippon Life India Asset Management |
| Mirae Asset Global Investments |
| HDFC Asset Management |
| Fidelity |
| Allianz Global Investors |
| Others |
Pricing and Supply Chain Analysis
SEBI's total expense ratio caps function as a de facto price index, cascading through distributor economics and compressing trail commissions toward sub-50 basis points for entry-level systematic investment plans across India's urban centers.
Pricing Analysis
Advisory-service bundling separates full-service distributor relationships from unbundled direct-to-investor platform access across Southeast Asian markets. Three-tier pricing structure across premium, standard, and economy levels aligns with investor wealth thresholds and customization demands. Cost compression in the standard tier is intensifying because SEBI's expense-ratio ceilings force distributors toward volume-dependent models. Retail investors in Indonesia and Vietnam exhibit highest price sensitivity, while sovereign wealth funds and pension pools in Tokyo and Sydney demonstrate lowest sensitivity due to governance-mandated liquidity requirements.
Supply Chain Analysis
Regional distribution centers in Singapore and Hong Kong anchor hub-and-spoke custody networks that feed into local registrar and transfer agent operations across ASEAN member states. Fund administration draws from Ireland and Luxembourg for cross-border UCITS structures, while domestic custody rests on local banking infrastructure in Japan, Australia, and India. Single-source vulnerability concentrates in platform technology providers serving mobile-first distributors. Distribution runs through bank-captive networks in developed markets and fintech aggregators in emerging corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
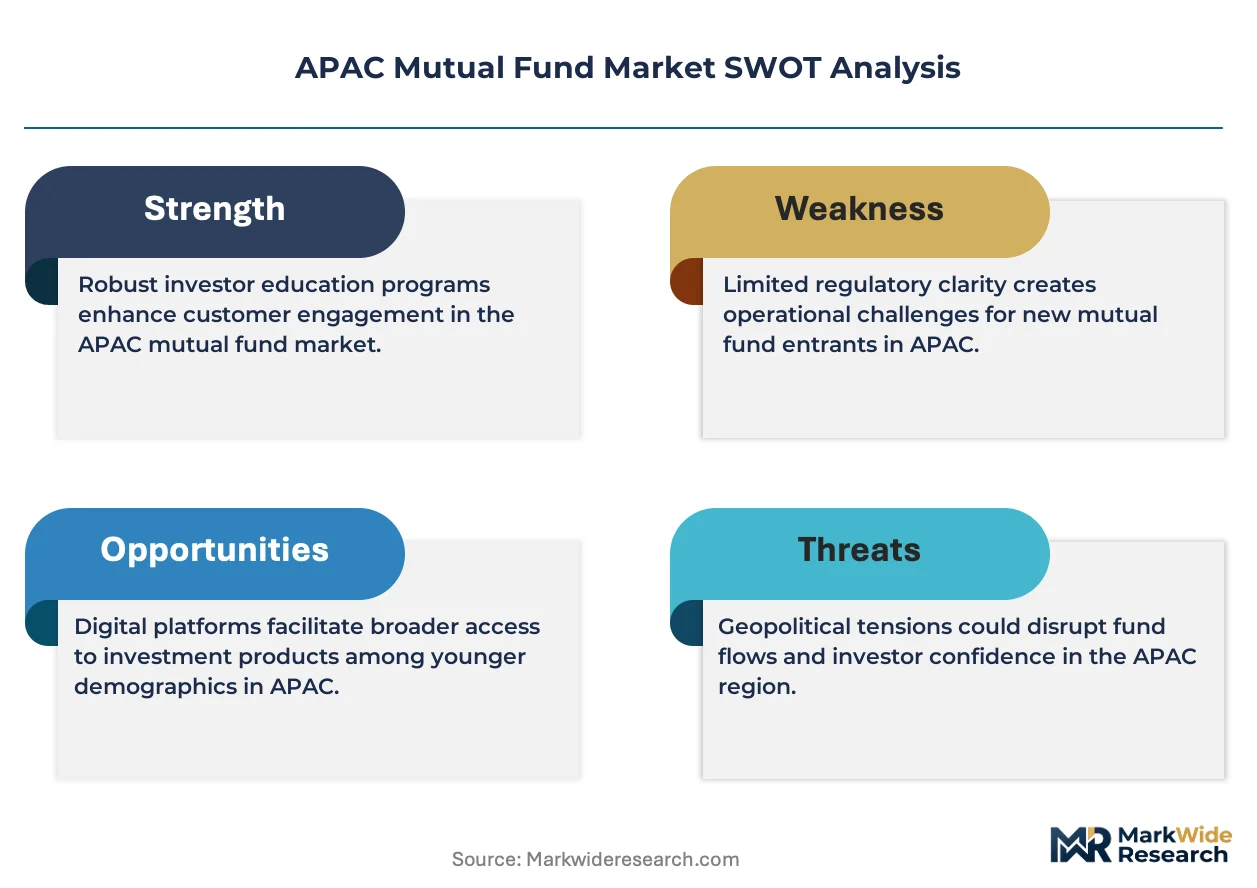
The APAC mutual fund market is becoming a vertical-integration race as asset managers pursue captive distribution control to defend margin structures against regulatory compression.
For Market Incumbents: Extend ETF infrastructure investments across developed Asia-Pacific corridors to anchor liquidity and deter platform disintermediation. Build proprietary direct-to-investor channels in India and Southeast Asia before fintech aggregators consolidate subscriber relationships. SEBI's expense-ratio caps represent the primary margin pressure point requiring scale-based cost absorption. For New Entrants and Emerging Players: Digital-native distributors in Vietnam offer the most penetrable white-space target given mutual fund penetration below 5% of household financial assets. Mobile-first systematic investment plan interfaces bypass legacy bank networks and compress customer acquisition costs toward sub-50 basis points. Partner with local registrar infrastructure to accelerate time-to-market rather than building captive operations. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier asset managers with established fund passports between Thailand, Malaysia, and Singapore but strained distributor economics. Long-term viability hinges on technology infrastructure ownership rather than third-party platform dependence. Watch SEBI's evolving foreign portfolio investment norms as the signal indicating capital flow inflection into Indian equity schemes.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Investor Platform Launch | SEBI's expense-ratio caps make distributor-bypass economics viable for scale players in India. |
| ASEAN Fund Passport Utilization | Cross-border marketing permissions unlock unified product structuring across 650 million consumers. |
| ETF Infrastructure Expansion | Liquidity anchoring in developed corridors defends against fintech platform disintermediation threats. |
| ESG Mandate Product Development | Australia's ASIC disclosure requirements and Japan's stewardship code pull capital into sustainable strategies. |
| Robo-Advisory Capability Buildout | Mobile-first SIP automation captures retail flows displacing branch-based relationship managers. |
Research Methodology
Document review covered SEBI circulars, CSRC liquidity-management guidelines, FSA disclosure standards, and ASEAN fund passport agreements, complemented by interviews with asset management distribution heads, fintech platform CTOs, pension fund investment officers, and regulatory compliance leads. Secondary validation drew from fund flow databases, expense ratio filings, and custody infrastructure disclosures. Bottom-up subscription data triangulated against top-down AUM estimates across product type, investor category, and distribution channel dimensions.
Segment-level projections across equity, debt, money market, and balanced fund categories combined with distribution channel splits yielded value and volume trajectories across the analysis window. CAGRs were derived from regression analysis against macroeconomic indicators, regulatory change vectors, and platform adoption curves. Forecast inputs incorporated SEBI's evolving foreign portfolio investment framework and CSRC's money market fund stress-testing protocols as structural demand shapers.
Several conditions sit outside the modeled scope, including sovereign debt default scenarios, abrupt currency control impositions, and technology platform security breaches that could freeze subscription flows. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Global AI in Asset Management Market
Asset Management
Equity Management Tool Market
Asset Management
Smart Asset Management Market
Asset Management
Asset and Wealth Management Market
Asset Management
Global Remote Asset Management Market
Asset Management
Hardware Asset Management Market
Asset Management
India Mutual Fund Market
Asset Management
Asia-Pacific Utilities Asset Management Market
Asset Management
US Pension Funds Market
Asset Management
Japan Asset Management Market
Asset Management
Global Asset Performance Management Market
Asset Management
US Healthcare Assets Management Market
Asset Management
Fixed Income Asset Management Market
Asset Management
Assets Under Management Market
Asset Management
China Mutual Funds Market
Asset Management
UK Asset Management Market