
 Global Asset Performance Management Market | 2026-2036
Global Asset Performance Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Asset Performance Management Market Foresight
The asset performance management software stack is pivoting between premium predictive analytics suites and commoditized condition monitoring dashboards. GE Vernova leverages its turbine installed base to anchor high-margin digital twin contracts across power generation fleets. AVEVA competes through deep vertical integration with process engineering software, while IBM differentiates via hybrid cloud architectures that bridge operational technology and enterprise IT systems.
Asset performance management encompasses software platforms, sensor networks, and analytical engines that monitor physical equipment health, predict failure modes, and optimize maintenance scheduling using vibration spectra, thermal imaging data, and lubricant analysis algorithms. The primary commercial purpose is to extend asset life cycles while minimizing unplanned downtime in capital-intensive industries. Predictive analytics commands the largest revenue share due to its direct linkage to avoided catastrophic failure costs, though edge computing deployments are expanding fastest as latency-sensitive applications migrate processing closer to plant floor sensors. Condition monitoring remains the most mature segment with established vendor relationships, while risk assessment modules capture disproportionate margin pools in oil and gas and mining sectors where regulatory exposure drives premium pricing.
The US EPA enforces emissions monitoring requirements that compel industrial operators to deploy continuous asset health tracking, while the EU F-Gas Regulation mandates leak detection protocols that integrate with performance management platforms. Japan's METI promotes smart factory standards that explicitly require predictive maintenance capabilities for subsidy eligibility. Stakeholders must evaluate whether cloud-native architectures or hybrid deployments better align with evolving data sovereignty requirements across multiple jurisdictions.
Market Dynamics
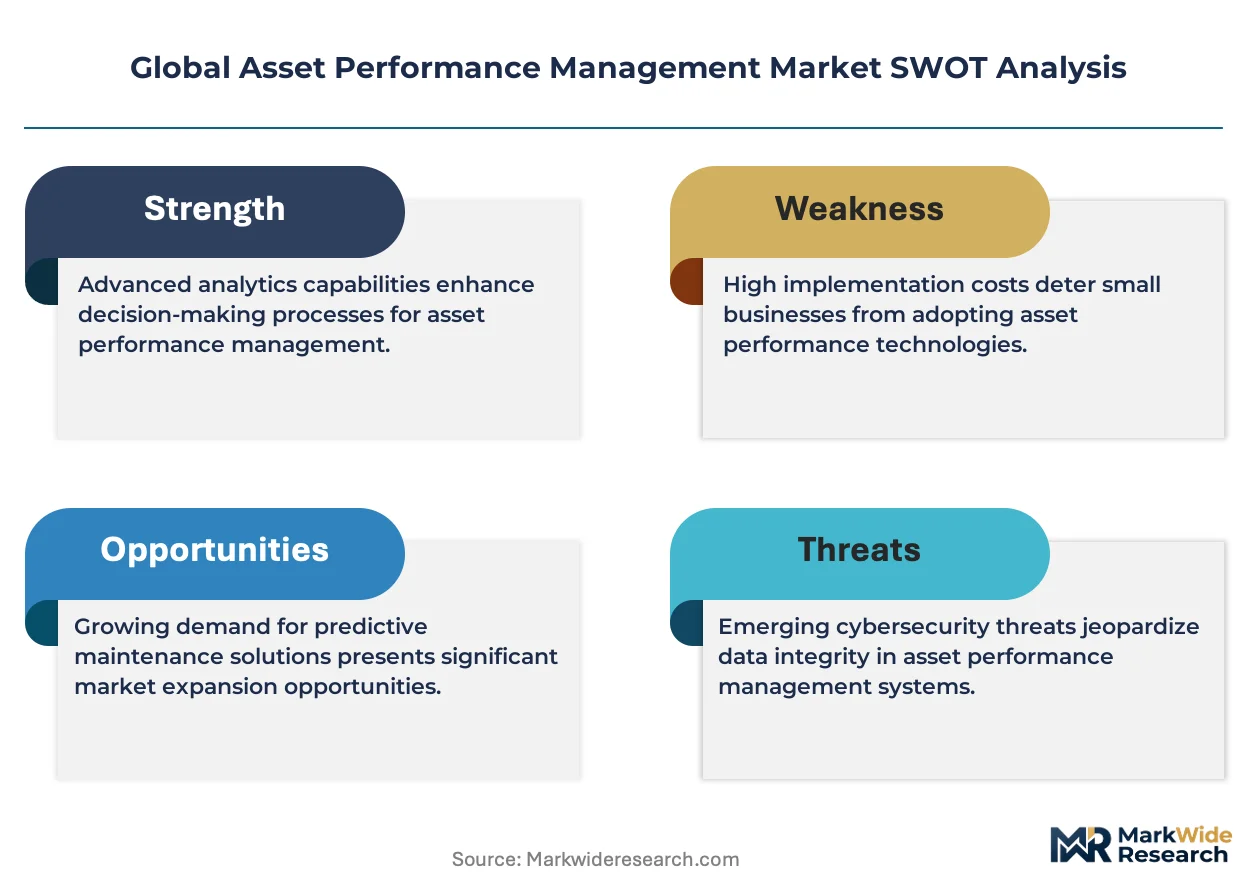
Power generation utilities are compressing maintenance cycles as predictive analytics platforms prove their value in avoiding catastrophic turbine failures. The EU Green Deal's carbon border adjustments are forcing industrial operators to document asset efficiency gains with auditable digital trails.
Growth Catalysts
- EU F-Gas Regulation:Leak detection mandates in industrial refrigeration are integrating asset health monitoring into compliance workflows, expanding platform deployment across chemical processing facilities.
- Edge computing architectures:Latency-sensitive vibration analysis is migrating processing closer to plant floor sensors, enabling real-time anomaly detection in rotating equipment.
- Japan METI smart factory subsidies:Predictive maintenance capabilities are now explicit requirements for manufacturing digitization grants, accelerating adoption among automotive suppliers.
Market Restraints
- Sensor hardware concentration:MEMS accelerometer supply chains cluster in East Asian manufacturing hubs, creating procurement vulnerability for vibration monitoring deployments.
- OT-IT integration complexity:Legacy SCADA systems in process industries resist seamless data extraction, requiring costly middleware development for platform connectivity.
- Data sovereignty fragmentation:Divergent national cloud storage requirements across Germany, France, and Japan complicate multi-site deployment architectures for multinational operators.
Strategic Opportunities
- India PLI scheme for manufacturing:Production-linked incentives for capital goods are creating first-mover advantage for APM vendors establishing localized service infrastructure.
- Digital twin convergence with AI:Physics-based simulation models are merging with machine learning inference engines to enable prescriptive maintenance recommendations beyond prediction.
- Outcome-based contracting channels:Equipment OEMs are repositioning as availability guarantors, embedding performance management platforms into power-by-the-hour service agreements.
Industry Challenges
- Reliability engineering talent scarcity:Competence in Weibull analysis and failure mode classification remains concentrated among aging specialist cohorts in aerospace and defense sectors.
- IEC 61508 functional safety certification:Safety instrumented system integration demands rigorous SIL verification timelines that extend platform deployment cycles in oil and gas applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Asset Performance Management Market |
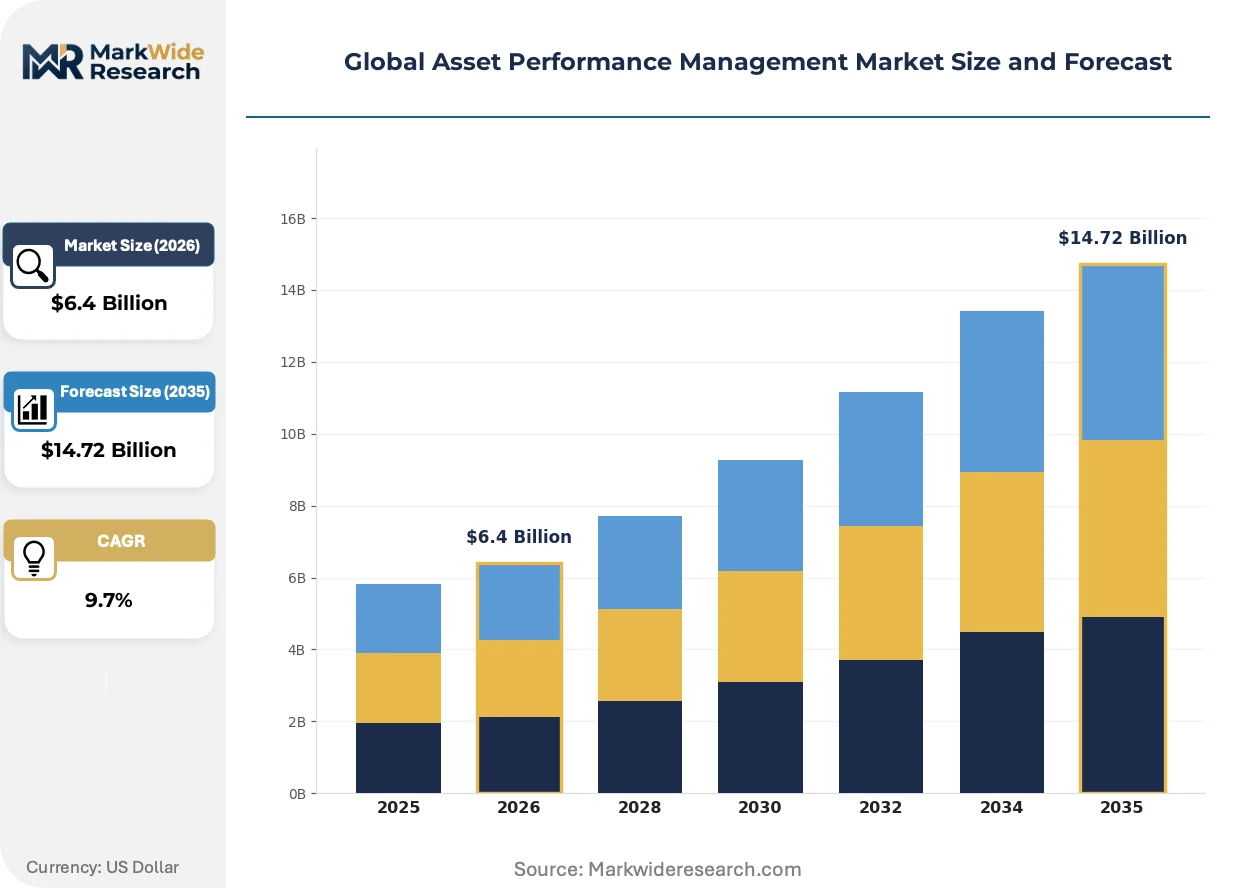
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $14.72 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Predictive Analytics, Condition Monitoring, Risk Assessment, Root Cause Analysis, Performance Optimization Deployment Mode: On-Premise, Cloud-Based, Hybrid, Edge Computing Application: Manufacturing Efficiency, Energy Management, Supply Chain Optimization, Equipment Reliability, Quality Control, Asset Utilization End User Industry: Power Generation, Oil & Gas, Transportation, Mining, Telecommunications |
| Companies Covered | GE Vernova, AVEVA, ABB, IBM, SAP, Rockwell Automation, Honeywell, Emerson, Aspen Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Asset Performance Management Market Shifts & Advancements
Digital twin technology is compressing the gap between physical asset behavior and virtual simulation fidelity. Vendors are racing to embed generative AI into diagnostic workflows while regulatory pressure accelerates platform standardization.
Physics-informed neural networks are electrifying predictive model accuracy by encoding thermodynamic and mechanical first principles into machine learning architectures. Power generation operators in Germany and Texas are deploying these hybrid models for gas turbine blade degradation forecasting. The technology is electrifying competitive differentiation between premium analytics suites and commodity monitoring dashboards.
The EU AI Act's risk classification framework is mandating human oversight protocols for automated maintenance recommendations in critical infrastructure. Industrial operators must now document algorithmic decision trails to satisfy conformity assessments for high-risk AI systems. Oil and gas majors with North Sea assets are restructuring platform governance to embed these accountability mechanisms before enforcement deadlines.
Equipment-as-a-service contracting is fragmenting traditional software licensing models across capital-intensive sectors. Mining operators in Western Australia are demanding vendor absorption of uptime risk through performance-based payment structures. This procurement evolution is most visible in wind energy, where OEMs now bundle twenty-year availability guarantees with turbine sales.
Global Asset Performance Management Market Segmentation
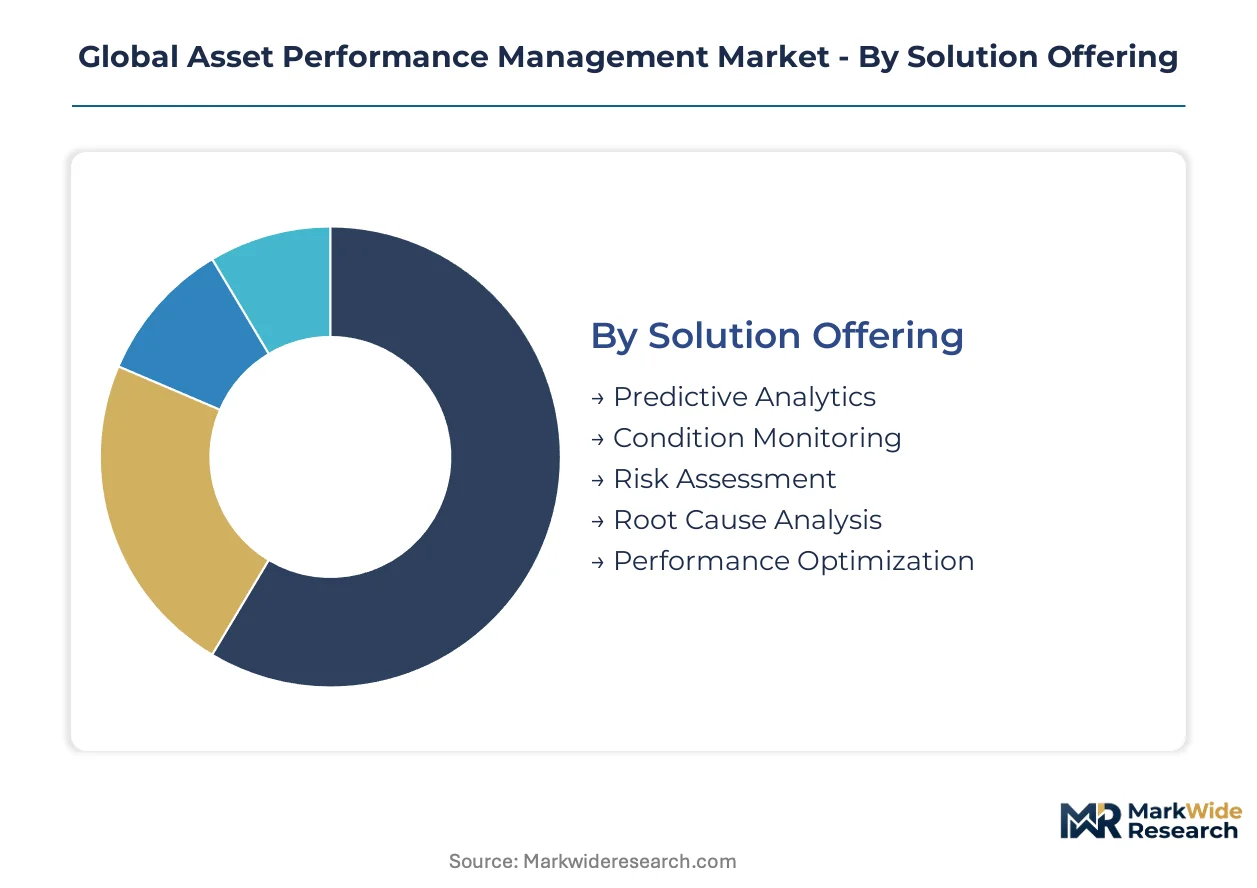
Asset performance management platforms fragment across solution architectures, infrastructure choices, and operational contexts. Each segmentation axis reveals distinct competitive dynamics and margin structures.
Solution Offering:
Predictive analytics engines dominate revenue pools through direct linkage to avoided catastrophic failure costs.
- Predictive Analytics:Machine learning models process vibration spectra, thermal imaging, and lubricant degradation patterns to forecast equipment failures before operational impact. Power generation utilities in Germany deploy these platforms to compress turbine maintenance cycles and eliminate unplanned downtime.
- Condition Monitoring:Real-time sensor networks track asset health through continuous data streams from accelerometers, temperature probes, and pressure transducers. Established vendor relationships in process industries create switching costs that protect incumbent positions.
- Risk Assessment:Regulatory compliance modules quantify operational exposure for safety-critical systems.
- Root Cause Analysis:Diagnostic engines trace failure propagation through equipment hierarchies.
- Performance Optimization:Prescriptive algorithms recommend operating parameter adjustments.
Predictive analytics leads on scale; risk assessment leads on momentum.
Deployment Mode:
Infrastructure choices reflect latency requirements, data sovereignty constraints, and legacy system integration burdens.
- Edge Computing:Processing migrates to plant-floor gateways for millisecond-response vibration analysis in rotating equipment. Japanese automotive suppliers leverage METI smart factory subsidies to deploy these architectures for real-time anomaly detection.
- Hybrid:Split architectures bridge operational technology silos with enterprise IT systems. Oil and gas operators with North Sea assets favor this model to satisfy EU AI Act accountability requirements while maintaining local control over safety-critical functions.
- Cloud-Based:Scalable compute pools support multi-site analytics standardization.
- On-Premise:Air-gapped deployments persist in defense and nuclear applications.
Hybrid deployments lead on scale; edge computing climbs the fastest.
Application:
Use case prioritization varies by sector maturity and regulatory pressure intensity.
- Equipment Reliability:Failure prevention protocols target rotating machinery, electrical infrastructure, and pressure vessels. Mining operators in Western Australia bundle these capabilities into equipment-as-a-service contracts that transfer uptime risk to vendors.
- Energy Management:Efficiency optimization aligns with EU Green Deal carbon border adjustment documentation requirements. German industrial operators deploy these modules to generate auditable digital trails of asset performance improvements.
- Manufacturing Efficiency:Throughput optimization integrates with MES and ERP systems.
- Supply Chain Optimization:Asset visibility extends to logistics and warehousing equipment.
- Quality Control:Process deviation detection prevents out-of-specification production.
- Asset Utilization:Capacity planning maximizes return on installed base.
Equipment reliability leads on scale; energy management gains share fastest.
End User Industry:
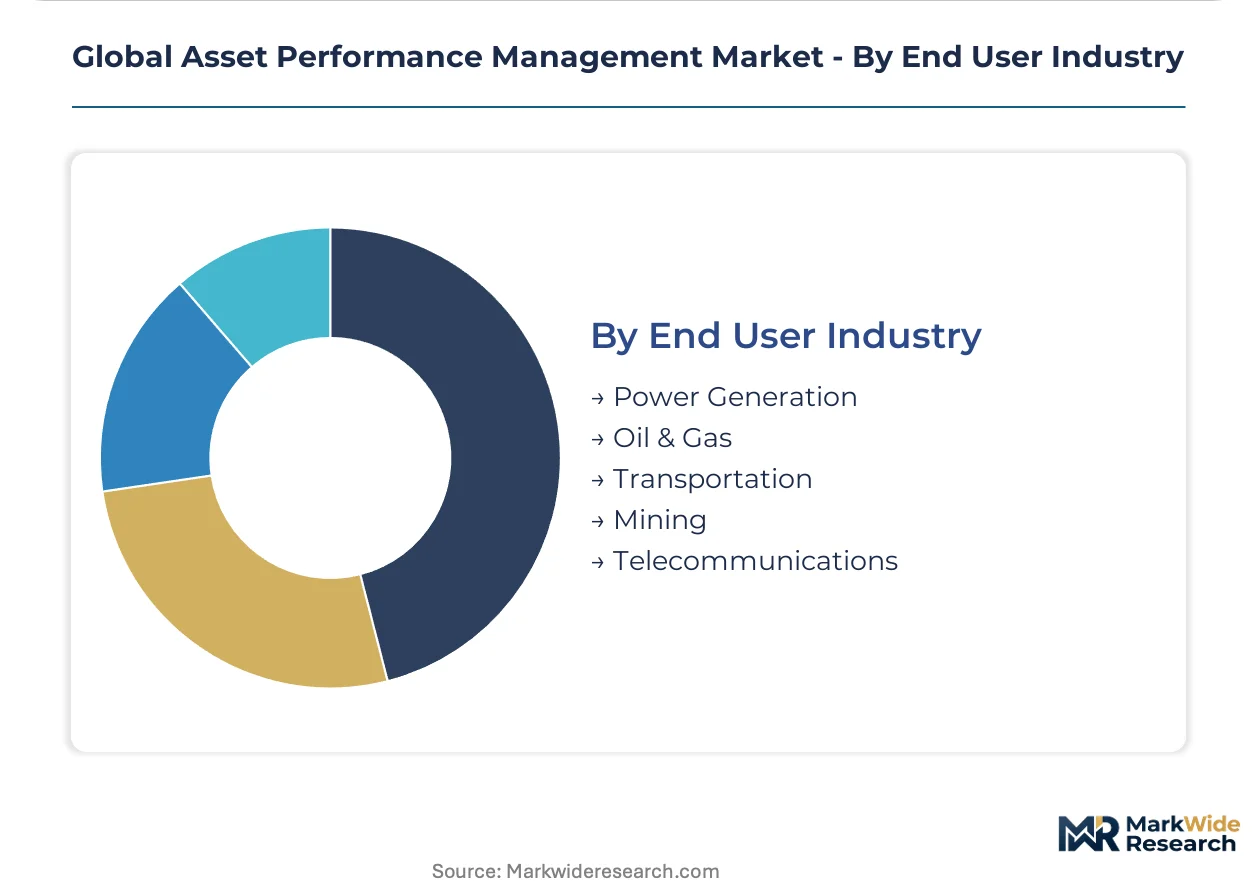
Sector-specific regulatory frameworks and asset criticality drive platform configuration requirements.
- Power Generation:Gas turbine digital twins and wind farm availability guarantees anchor long-term service contracts. GE Vernova leverages installed base relationships to secure high-margin predictive maintenance subscriptions across fleet operators.
- Oil & Gas:IEC 61508 functional safety certification demands extend deployment timelines but command premium pricing for safety instrumented system integration. F-Gas Regulation leak detection mandates in the EU expand platform penetration in refrigeration and chemical processing.
- Mining:Remote asset locations favor edge architectures with intermittent connectivity tolerance.
- Transportation:Rolling stock and fleet applications emphasize mobile connectivity.
- Telecommunications:Infrastructure monitoring targets cooling and power systems.
Power generation leads on scale; oil and gas leads on margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reliability engineering talent pools concentrate in Germany, the United States, and Japan, anchoring platform development and deployment expertise across three continents. These workforce clusters shape regional competitive dynamics and technology adoption trajectories.
United States
Power generation utilities and oil and gas operators drive demand for predictive maintenance platforms across Texas and the Gulf Coast. The EPA enforces emissions monitoring requirements that compel industrial operators to deploy continuous asset health tracking systems. Houston anchors deployment concentration for offshore platform monitoring and refinery optimization.
Germany
Manufacturing digitization and energy transition policies accelerate platform deployment across heavy industry in the Ruhr region and Bavaria. The EU Green Deal and associated carbon border adjustments pressure industrial operators to document asset efficiency gains with auditable digital trails. Stuttgart and Munich host automotive supplier clusters adopting METI-aligned predictive maintenance for smart factory certification.
Japan
Automotive suppliers and precision machinery manufacturers expand edge computing deployments for real-time anomaly detection. METI promotes smart factory standards that explicitly require predictive maintenance capabilities for subsidy eligibility. Nagoya's Chubu region concentrates aerospace and automotive tier-one supplier adoption of vibration monitoring systems.
India
Production-linked incentives for capital goods manufacturing create first-mover advantage for APM vendors establishing localized service infrastructure. The PLI scheme for manufacturing drives adoption among capital goods producers in Gujarat and Maharashtra. Pune and Ahmedabad host emerging deployment clusters for textile and pharmaceutical processing equipment monitoring.
United Kingdom
North Sea oil and gas operators restructure platform governance to embed EU AI Act accountability mechanisms before enforcement deadlines. The EU AI Act's risk classification framework mandates human oversight protocols for automated maintenance recommendations in critical infrastructure. Aberdeen anchors offshore asset monitoring concentration with hybrid cloud architectures bridging operational technology and enterprise IT systems.
Global Asset Performance Management Market Competitive Landscape
Top-tier vendors anchor high-margin predictive analytics suites, while mid-tier specialists compete on vertical-specific condition monitoring dashboards. The vendor base stratifies between turbine OEMs leveraging installed base relationships and software houses competing through cloud-native architectures. Strategic archetypes include equipment OEMs repositioning as availability guarantors, engineering software vendors extending into operational technology, and hybrid cloud providers bridging IT-OT integration gaps. Dominant competitive moves include outcome-based contracting channels and physics-informed AI model development.
Within the equipment OEM tier, GE Vernova and ABB exemplify vendors leveraging turbine and electrical infrastructure installed bases to anchor long-term service contracts. AVEVA occupies a position representing engineering software vertical extension into operational technology platforms. IBM sits within the hybrid cloud provider archetype, bridging enterprise IT systems with plant-floor operational technology through architecture differentiation.
| Leading Market Players |
|---|
| GE Vernova |
| AVEVA |
| ABB |
| IBM |
| SAP |
| Rockwell Automation |
| Honeywell |
| Emerson |
| Aspen Technology |
| Others |
Supply & Pricing Matrix
A bifurcation between premium predictive analytics suites and commoditized condition monitoring dashboards manifests in divergent pricing architectures and supply chain configurations. Premium vendors anchor high-margin digital twin contracts through turbine installed base relationships, while commodity players compete on sensor hardware volume and standardized dashboard licensing. This tier divergence concentrates software development talent in Germany and the United States, while MEMS accelerometer manufacturing clusters in East Asian hubs create procurement asymmetries.
Pricing Analysis
Bundled availability-guarantee contracts versus unbundled software licensing splits buyer archetypes and pricing power. Equipment OEMs command value-based pricing through power-by-the-hour service agreements that transfer uptime risk, while pure-play software vendors compete on subscription tiers differentiated by analytics depth and integration complexity. Cost compression in condition monitoring stems from open-source dashboard proliferation and sensor hardware commoditization. Mid-tier manufacturing operators exhibit acute price sensitivity, whereas power generation utilities prioritize failure avoidance over licensing costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale utility demand, while systems integrators serve fragmented process industry deployments. MEMS accelerometer supply concentrates in Taiwan, South Korea, and Japan, with vibration sensor assembly distributed across China and Mexico. Platform software development draws from engineering talent pools in Germany, the United States, and Japan. Single-source vulnerability in MEMS foundry capacity creates procurement risk for real-time monitoring deployments. Distribution runs through OEM captive service organizations, independent automation distributors, and cloud-native direct sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU F-Gas Regulation compliance costs in Europe exceed subsidy-supported deployment economics in India, creating divergent return profiles for identical platform capabilities.
For Market Incumbents: To counter cloud-native entrants with lower IT-IT integration overhead, established vendors must deepen installed base data moats through physics-informed AI model development and secure IEC 61508 certification pipelines that extend deployment timelines for challengers. Capacity addition in India through PLI-aligned service infrastructure captures manufacturing digitization subsidies before local competitors consolidate. For New Entrants and Emerging Players: Mid-tier automotive suppliers in Japan's Chubu region represent an underserved buyer archetype seeking METI-compliant predictive maintenance without full ERP integration complexity. These tier-two manufacturers prioritize standalone edge computing deployments over enterprise-wide platform commitments. A channel partnership strategy with regional systems integrators accelerates subsidy-capture without direct sales overhead. For Investors and Strategic Acquirers: Consolidation pressure builds where OT-IT integration competence concentrates among aging reliability engineering cohorts in aerospace and defense sectors. Viability over the next decade hinges on acquiring physics-based simulation capabilities that merge with machine learning inference engines. The signal to watch is equipment-as-a-service contract proliferation in mining and wind energy, which repositions software margins within OEM balance sheets and triggers vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Physics-Informed AI Model Development | Hybrid neural networks encoding thermodynamic first principles differentiate premium analytics from commodity dashboards for German turbine operators. |
| Edge Computing Architecture Deployment | Plant-floor processing migration satisfies METI smart factory latency requirements for Japanese automotive supplier real-time anomaly detection. |
| Outcome-Based Contracting Expansion | Availability guarantees bundled with turbine sales transfer uptime risk and embed long-term platform subscriptions for power generation fleets. |
| India Service Infrastructure Localization | PLI scheme alignment captures manufacturing digitization subsidies among capital goods producers in Gujarat and Maharashtra. |
| IEC 61508 Certification Pipeline Investment | Functional safety verification timelines extend competitive moats in oil and gas safety instrumented system integration. |
Research Methodology
Multiple input streams — executive interviews with maintenance directors and plant engineers, OEM procurement team discussions, aftermarket service head consultations, and systems integrator channel assessments — were reconciled against secondary validation from EPA emissions filings, EU ETS compliance databases, METI smart factory subsidy disclosures, and SEC 10-K equipment revenue segmentations. Bottom-up deployment estimates across power generation, oil and gas, and manufacturing verticals were triangulated with top-down market sizing from platform vendor reported subscriptions.
Data-stream reconciliation applied analytical frameworks across solution architecture, deployment mode, application context, and end-user industry dimensions throughout the projection horizon. CAGRs were derived from segment-level growth rate synthesis and cross-referenced with regulatory mandate enforcement timelines. Forecast inputs incorporated EU AI Act risk classification implementation schedules, India PLI scheme capital goods incentive trajectories, and edge computing hardware cost decline curves.
Inputs from utility planning officers and automotive supplier engineering leads were available through the study window; gaps in real-time equipment failure cost disclosure introduce uncertainty bands around predictive analytics value-capture estimates. Forecasts reflect assumptions regarding subsidy program continuity, regulatory enforcement intensity, and MEMS supply chain resilience. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Fund Management Fee Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
Fixed Income Asset Management Market
Asset Management
Asset Management System Market
Asset Management
India Asset Management Market
Asset Management
Canada Pension Fund Market
Asset Management
US Asset Management Market
Asset Management
Global Investment Management Software Market
Asset Management
UK Asset Management Market
Asset Management
Global AI in Asset Management Market
Asset Management
Fund Management Software Market
Asset Management
Europe Asset Management Market
Asset Management
Asset and Wealth Management Market
Asset Management
China Mutual Funds Market
Asset Management
Asia-Pacific Utilities Asset Management Market
Asset Management
Smart Asset Management Market