
 US Asset Management Market | 2026-2036
US Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
US Asset Management Market Outlook
Retail distribution through wirehouse broker-dealers is fragmenting as independent registered investment advisors capture flow migration from traditional channels. BlackRock leverages its ETF platform dominance to sustain scale advantages across passive vehicles. Vanguard Group anchors retail investor loyalty through its mutual ownership structure and fee compression strategy. State Street Global Advisors competes in institutional custody and index management where operational precision differentiates service tiers.
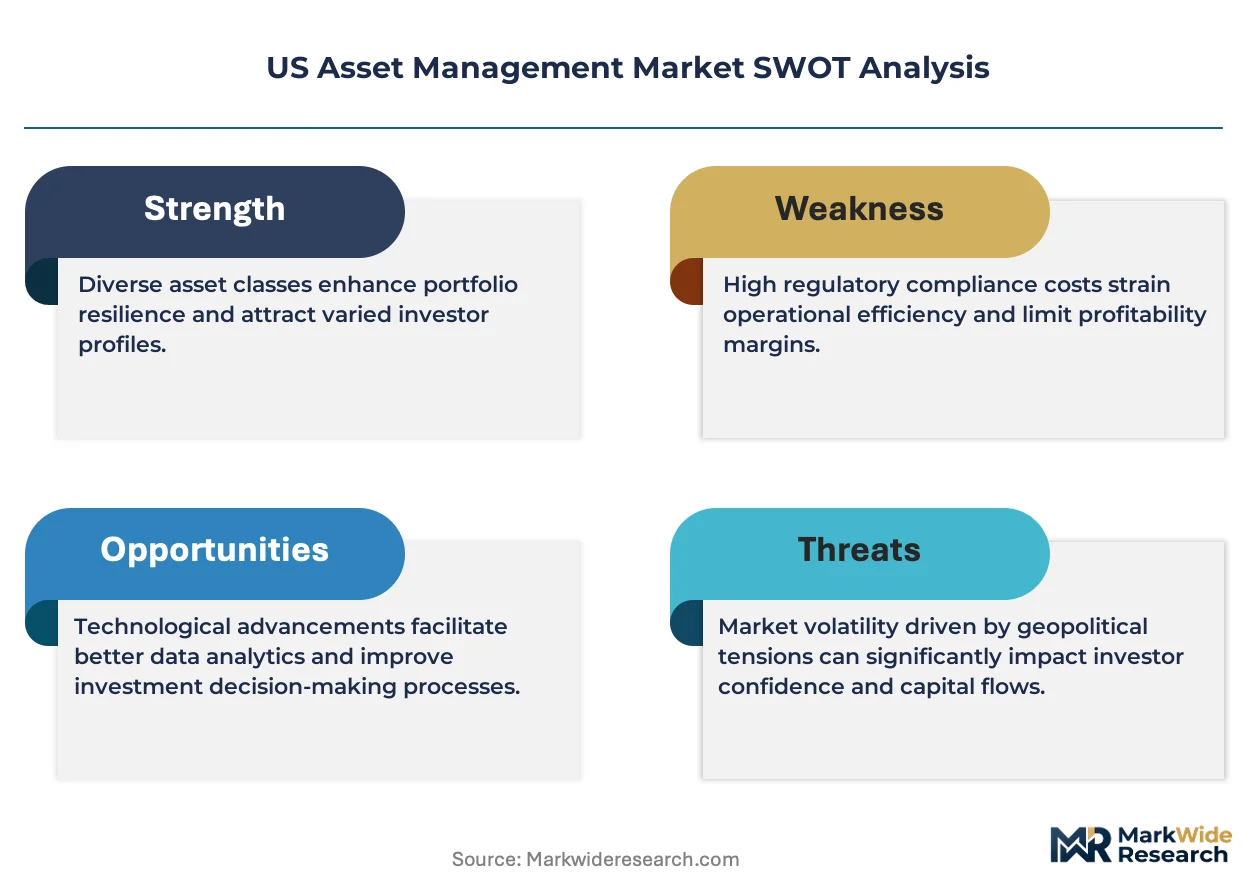
US asset management encompasses the professional administration of investment portfolios spanning equities, fixed income, and alternative instruments, governed by prospectus disclosures, SEC registration requirements, and fiduciary standards under the Investment Advisers Act of 1940. The practice pools capital from dispersed investors to achieve diversification, liquidity transformation, and risk-adjusted returns through systematic allocation frameworks. Wealth management and institutional investment service types command the deepest margin pools due to sticky advisory relationships and performance fee structures. Active management strategies retain premium pricing power among HNWI and endowment segments despite sustained fee pressure from passive management expansion across pension fund allocations.
SEC examination priorities, DOL fiduciary standards under ERISA, and FINRA suitability rules collectively elevate compliance infrastructure costs while reshaping product distribution economics across advisory and brokerage channels. The SEC's marketing rule and private fund adviser reforms tighten disclosure obligations, redirecting technology investment toward regulatory reporting automation. Stakeholders must calibrate strategic resource allocation between passive scale economics and active performance alpha as regulatory intensity and investor preference evolution converge on fee transparency and outcome accountability.
Market Dynamics
Delegated investment mandates from retirement plan sponsors are compressing active management fee structures while SEC marketing rule reforms and DOL fiduciary standards force advisory firms to reconfigure compliance infrastructure around disclosure automation.
Growth Catalysts
- SEC Marketing Rule reforms:The SEC's updated marketing rule creates standardized disclosure frameworks that reduce compliance fragmentation across state boundaries, enabling advisory firms to scale digital client acquisition.
- California institutional capital pools:Concentrated pension fund assets in the California corridor sustain demand for specialized fixed income and alternative investment strategies with above-benchmark yield targets.
- ETF platform technology:Exchange-traded fund infrastructure innovations lower portfolio construction costs for wirehouse broker-dealers transitioning from commission-based to fee-based advisory models.
Market Restraints
- Fee compression mechanics:Passive vehicle expense ratios below ten basis points constrain revenue per dollar under management across core equity allocation strategies.
- Compliance infrastructure costs:FINRA suitability examination intensity and SEC private fund adviser reforms require technology investments that disproportionately burden mid-sized registered investment advisors.
- Index provider concentration:Licensing dependencies on S&P Dow Jones and MSCI for benchmark construction create margin pressure through escalating index royalty structures.
Strategic Opportunities
- Texas municipal pension systems:Underpenetrated public employee retirement plans in the Dallas-Houston corridor present whitespace for outsourced chief investment officer services and liability-driven investment frameworks.
- IRA distribution channel innovation:The Inflation Reduction Act's clean energy tax credit provisions create specialized fixed income demand that asset managers can access through direct-to-consumer digital platforms.
- Direct indexing technology convergence:Customization engines combining tax-loss harvesting algorithms with separately managed account infrastructure enable personalized beta strategies at scale.
Industry Challenges
- Quantitative analyst talent scarcity:Competitive compensation from technology firms and hedge funds restricts access to machine learning and alternative data integration capabilities for traditional asset managers.
- Legacy portfolio accounting system integration:Migration from on-premise custody and accounting platforms to cloud-native architectures requires multi-year capital commitments with uncertain operational continuity during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Asset Management Market |
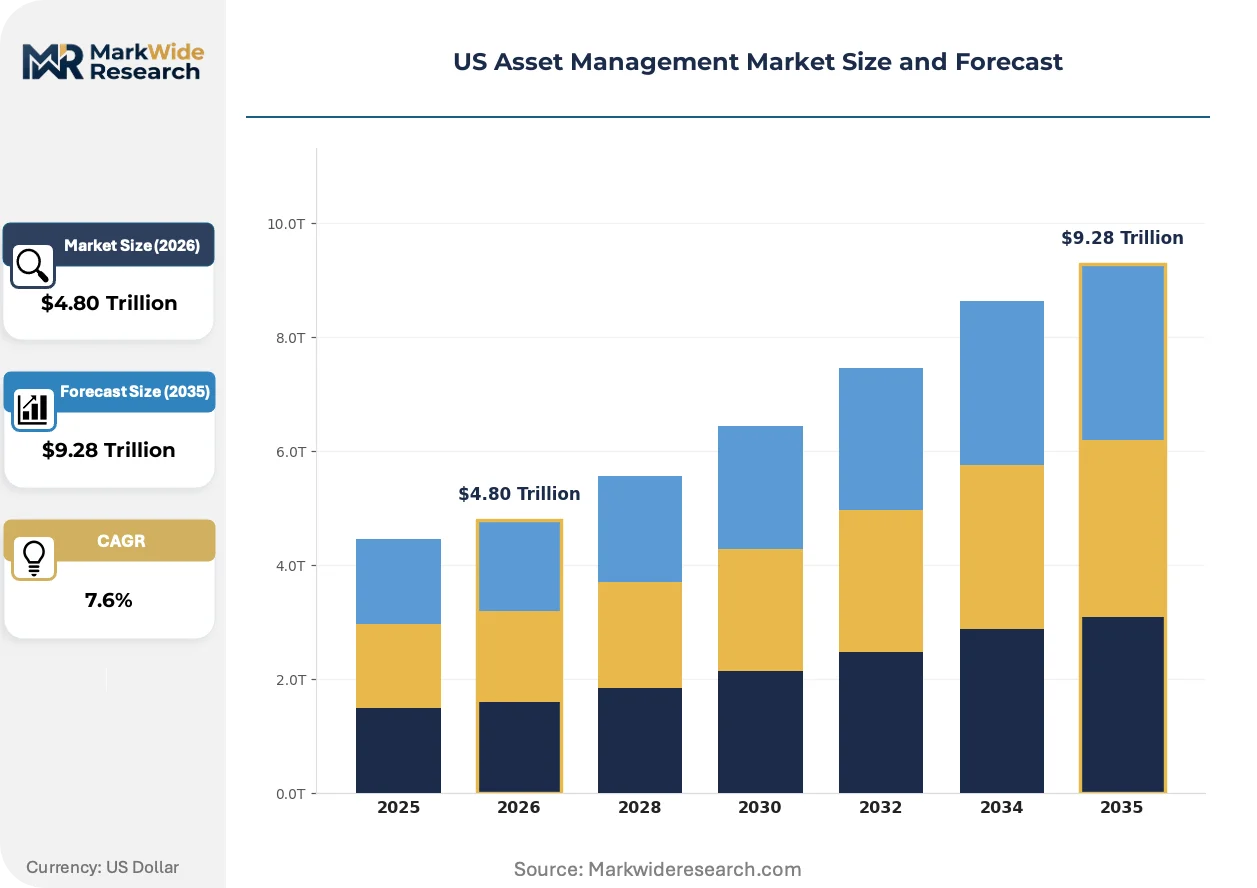
| Market Size in 2026 | $4.80 Trillion |
| Market Size in 2035 | $9.28 Trillion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wealth Management, Retail Investment, Institutional Investment, Private Equity Investor Type: HNWIs, Pension Funds, Insurance Companies, Endowments Asset Class: Equities, Fixed Income, Alternatives, Real Estate Investment Strategy: Active Management, Passive Management, Tactical Allocation, Risk Parity |
| Companies Covered | BlackRock, Vanguard Group, Fidelity Investments, State Street Global Advisors, Capital Group, JPMorgan Chase, Morgan Stanley, T. Rowe Price, Invesco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Asset Management Market Strategic Shifts
Digital infrastructure investments are reconfiguring how investment strategies reach end investors, with regulatory technology automation and personalized portfolio construction emerging as the dominant competitive battlegrounds.
Artificial intelligence-driven research platforms are virtualizing traditional fundamental analyst workflows. Mid-sized registered investment advisors deploy natural language processing tools for earnings call sentiment analysis and alternative data signal extraction. This technology compression enables smaller firms to replicate institutional-grade research coverage without proportional headcount expansion.
The SEC's private fund adviser reforms tighten quarterly statement disclosure requirements and restricted activity prohibitions. Advisers to private funds must now calculate and distribute performance metrics under standardized methodologies, elevating operational burden. Large alternative asset managers respond by consolidating fund administration relationships and automating waterfall distribution calculations.
Advisory clients increasingly unbundle investment management from comprehensive financial planning services. High-net-worth investors in the New York metropolitan area separately negotiate portfolio construction fees and wealth transfer consultation retainers. This service decomposition pressures traditional bundled pricing models and accelerates fee transparency demands across wirehouse and independent channels.
US Asset Management Market Segmentation
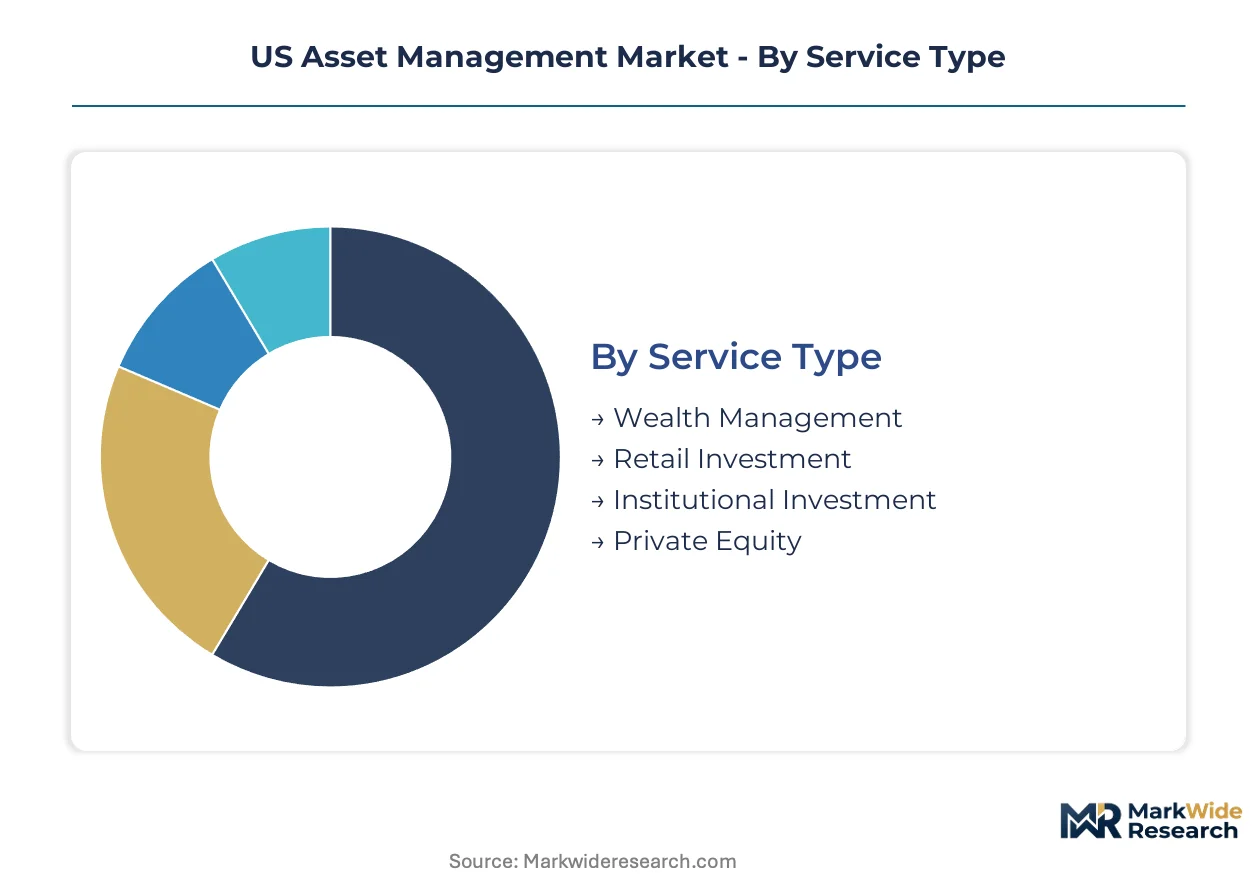
US asset management segmentation reveals distinct margin profiles and regulatory exposure across service tiers and investor categories. Each dimension carries specific fee structures, compliance obligations, and technology investment requirements that reshape competitive positioning.
Service Type:
Cost tier differentiation separates advisory models by revenue per dollar managed and relationship stickiness.
- Wealth Management:Comprehensive financial planning bundled with portfolio construction targets HNWIs and multi-generational families. California and New York metro corridors concentrate demand where advisory relationships command premium retainer structures.
- Institutional Investment:Outsourced CIO services and liability-driven investment frameworks serve pension funds and endowments with scale-based fee compression. Texas municipal pension systems present whitespace for specialized fixed income and alternative allocation strategies.
- Retail Investment:Mass-market brokerage and robo-advisory platforms compete on expense ratio minimization.
- Private Equity:Illiquid fund structures with performance fee waterfalls and carried interest mechanics.
Wealth management holds installed capacity. Institutional investment is rotating up the share rankings.
Investor Type:
Customer type determines product complexity, reporting granularity, and fiduciary duty intensity.
- Pension Funds:ERISA-governed defined benefit and defined contribution plans drive delegated investment mandate growth. SEC marketing rule reforms enable standardized performance disclosure across state boundaries for plan sponsor due diligence.
- HNWIs:Individual investors with investable assets exceeding liquid thresholds demand tax-optimized separately managed accounts and direct indexing customization. New York metropolitan area investors increasingly unbundle investment management from estate planning services.
- Insurance Companies:Regulatory capital requirements shape liability-matching fixed income portfolios.
- Endowments:Perpetual investment horizons support illiquid alternative asset allocations.
Pension funds anchor fee-based advisory revenue. HNWIs are gaining share fastest through direct-to-consumer platform migration.
Asset Class:
Application focus varies by liquidity transformation needs and benchmark dependency.
- Equities:Core allocation vehicles span passive index replication and active fundamental selection. Fee compression mechanics constrain revenue as expense ratios fall below ten basis points for large-cap beta exposure.
- Alternatives:Hedge funds, private credit, and infrastructure investments deliver uncorrelated return streams with lock-up structures. SEC private fund adviser reforms tighten quarterly statement disclosure and restricted activity prohibitions.
- Fixed Income:Duration management and credit selection for liability-driven frameworks.
- Real Estate:REITs and private property funds with appraisal-based valuation cycles.
Equities maintain dominant allocation share. Alternatives show the steepest expansion trajectory as investors seek yield beyond traditional benchmarks.
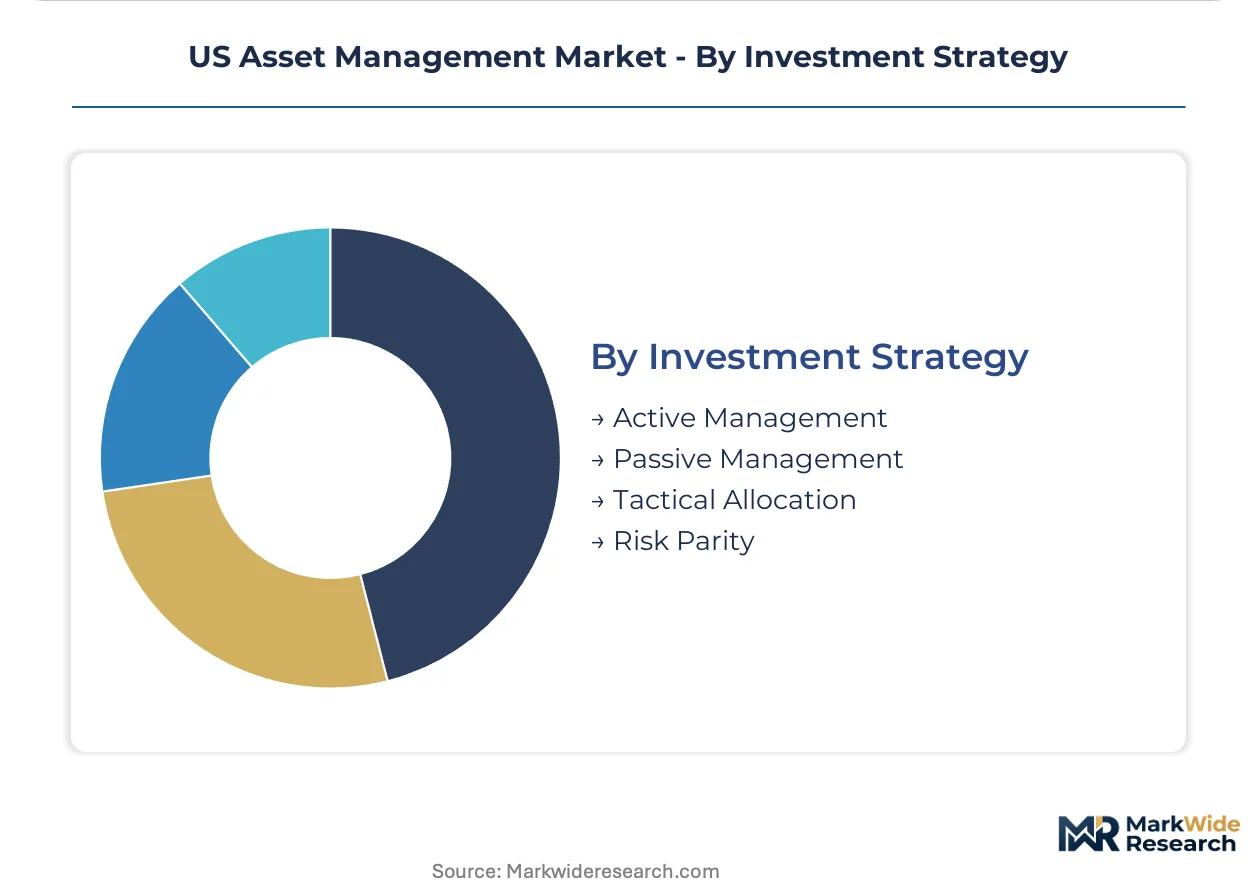
Investment Strategy:
Maturity and technology intensity separate systematic approaches from discretionary frameworks.
- Passive Management:Rules-based index replication through ETFs and mutual funds achieves scale economics. ETF platform technology innovations lower portfolio construction costs for wirehouse broker-dealers transitioning from commission-based models.
- Active Management:Fundamental research and security selection retain premium pricing among endowment and HNWI segments despite sustained fee pressure. Quantitative analyst talent scarcity restricts machine learning integration capabilities for traditional asset managers.
- Tactical Allocation:Dynamic sector and geographic rotation based on macroeconomic signals.
- Risk Parity:Volatility-targeted diversification across asset classes with leverage mechanics.
Passive management holds scale advantages. Active management is climbing the fastest in alternatives and specialized fixed income niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Chicago Mercantile Exchange's derivatives clearing infrastructure anchors Illinois as the backbone of US futures and options execution, while the Boston-Washington rail corridor channels institutional capital flows between pension fund headquarters and asset management centers.
California
CalPERS and CalSTRS pension systems drive delegated investment mandate demand exceeding $800 billion in combined assets. The SEC's marketing rule reforms enable standardized performance disclosure for plan sponsor due diligence across state boundaries. San Francisco's fintech corridor concentrates robo-advisory platform development where venture capital flows support direct-to-consumer wealth management innovation.
New York Metro
Wall Street custody banks and wirehouse headquarters sustain institutional trading volume and prime brokerage services. FINRA examination intensity elevates compliance infrastructure costs for broker-dealers operating under suitability rules. Manhattan's Midtown financial district anchors alternative asset manager headquarters where private fund adviser reforms tighten quarterly statement disclosure obligations.
Texas
Municipal pension systems in Dallas-Houston corridor present whitespace for outsourced CIO services and liability-driven investment frameworks. The Inflation Reduction Act's clean energy tax credit provisions create specialized fixed income demand through state infrastructure financing authorities. Austin's technology corridor attracts quantitative analyst talent from coastal financial centers as compensation differentials narrow.
Massachusetts
Mutual fund complexes and registered investment advisor clusters concentrate in Greater Boston's Route 128 technology belt. DOL fiduciary standards under ERISA reshape advisory obligations for retirement plan sponsors headquartered in the region. Cambridge's academic proximity sustains quantitative research partnerships between asset managers and university endowment investment offices.
Florida
High-net-worth individual migration from northeastern states expands demand for tax-optimized separately managed accounts and estate planning services. State-level regulatory frameworks for investment advisers operate alongside SEC registration requirements without duplicative compliance burdens. Miami's international banking hub attracts Latin American family office capital seeking US-domiciled asset management services.
US Asset Management Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in niche strategy construction. The US asset management market consolidates around scale-driven passive vehicle providers and relationship-intensive active managers, with mid-sized registered investment advisors occupying fragmented territory between these poles. Three archetypes dominate: ETF platform operators achieving scale economics, mutual ownership structures compressing fees to capture retail loyalty, and alternative specialists monetizing illiquidity premiums through performance fee waterfalls. Competitive intensity manifests through strategic partnerships for distribution access and technology licensing for portfolio construction automation.
Within the scale-driven platform tier, BlackRock and Vanguard Group exemplify divergent ownership models achieving dominant market presence. BlackRock's corporate structure supports ETF platform expansion across institutional and retail channels. Vanguard Group's mutual ownership model anchors retail investor loyalty through fee compression rather than external shareholder returns. State Street Global Advisors occupies a position in institutional custody and index management where operational precision differentiates service tiers.
| Leading Market Players |
|---|
| BlackRock |
| Vanguard Group |
| Fidelity Investments |
| State Street Global Advisors |
| Capital Group |
| JPMorgan Chase |
| Morgan Stanley |
| T. Rowe Price |
| Invesco |
| Others |
Value Chain & Pricing Dynamics
SEC marketing rule compliance costs operate as a regulatory chokepoint that simultaneously widens pricing tier spreads between scale-driven passive providers and mid-sized active managers while compressing supply chain options toward technology vendors capable of automated disclosure infrastructure.
Pricing Analysis
Volume-discount tiering structures dominate institutional mandate pricing, with basis-point compression accelerating as assets under management scale beyond defined thresholds. Pricing stratifies across premium active management, standard hybrid strategies, and economy passive beta exposure, with fee differentiation driven by performance fee waterfall complexity and operational alpha claims. Cost compression in core equity beta is intensifying because expense ratios for large-cap index vehicles have compressed below sustainable levels for non-scale operators. Pension fund sponsors exhibit the highest price sensitivity due to fiduciary benchmarking requirements, while family offices demonstrate the lowest sensitivity where tax-loss harvesting and direct indexing customization command retainer premiums.
Supply Chain Analysis
Upstream feedstock for asset management technology infrastructure draws from software development clusters in India, cloud computing infrastructure concentrated in the United States, and specialized data analytics talent pools distributed across the United Kingdom and Singapore. Critical dependencies include portfolio accounting systems, regulatory reporting automation platforms, and alternative data feeds from satellite imagery and credit card transaction aggregators. Single-source vulnerability concentrates in index licensing arrangements with S&P Dow Jones and MSCI, where escalating royalty structures create margin pressure without viable substitution. Distribution runs through wirehouse broker-dealer networks, independent registered investment advisor platforms, and direct-to-consumer digital channels with varying custody and clearing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the US asset management landscape creates whitespace for specialized operators as retirement plan sponsors unbundle investment management from record-keeping and advisory services, generating demand for outsourced CIO capabilities and liability-driven investment frameworks.
For Market Incumbents: Harden competitive position by consolidating fund administration relationships to achieve scale economies in SEC private fund adviser reform compliance, and deepen vertical integration into direct indexing technology engines to capture tax-optimization revenue pools before platform commoditization accelerates. For New Entrants and Emerging Players: Pursue whitespace in Texas municipal pension systems where outsourced CIO penetration remains underdeveloped relative to California and New York corridors, and anchor go-to-market strategy through specialized fixed income strategies targeting Inflation Reduction Act clean energy infrastructure financing demand. For Investors and Strategic Acquirers: DOL fiduciary rule evolution reshapes the acquisition landscape by elevating compliance infrastructure to strategic asset status, positioning vertically integrated RIA roll-ups with automated disclosure capabilities as preferred targets; the signal to watch is SEC examination priority shifts toward private fund valuation methodologies.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Automation | SEC marketing rule compliance costs disproportionately burden mid-sized advisors, creating acquisition targets with automated infrastructure. |
| Direct Indexing Platform Development | Tax-loss harvesting engines combined with separately managed account infrastructure enable personalized beta at institutional scale. |
| Alternative Data Integration | Machine learning pipelines processing satellite imagery and credit card aggregates differentiate active management research capabilities. |
| Outsourced CIO Service Expansion | Delegated investment mandate growth from municipal pension systems in underpenetrated corridors drives specialized fixed income demand. |
| ETF Platform Technology Licensing | Portfolio construction automation lowers barriers for wirehouse broker-dealers transitioning from commission-based to fee-based models. |
Study Parameters
A spread of perspectives from pension fund investment officers, independent registered investment advisor principals, wirehouse broker-dealer product specialists, and regulatory compliance technology vendors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filing disclosures, FINRA examination priority publications, DOL regulatory guidance documents, and industry association survey data. Bottom-up asset flow modeling and top-down macroeconomic scenario triangulation anchored the quantitative framework.
Demand-supply-balance framing structured the forecast architecture across the analysis window, with segmentation dimensions spanning service type, investor category, asset class, and investment strategy maturity. CAGRs derived from historical flow trajectories, fee compression elasticities, and regulatory implementation timelines. Model inputs incorporated pension fund delegation mandate growth rates, passive vehicle expense ratio decay curves, and alternative asset allocation shifts among endowment and family office segments.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories, equity market volatility regimes, or regulatory enforcement intensity would shift the trajectory materially. Cross-checking against Flow of Funds Accounts data and Investment Company Institute statistical releases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Europe Asset Management Market
Asset Management
Hardware Asset Management Market
Asset Management
Fund Management Fee Market
Asset Management
Smart Asset Management Market
Asset Management
Asset and Wealth Management Market
Asset Management
India Mutual Fund Market
Asset Management
US Healthcare Assets Management Market
Asset Management
US Pension Funds Market
Asset Management
LAMEA Equity Management Software Market
Asset Management
Equity Management Tool Market
Asset Management
China Mutual Funds Market
Asset Management
Assets Under Management Market
Asset Management
Fund Management Software Market
Asset Management
Healthcare Asset Management Market
Asset Management
UK Asset Management Market
Asset Management
India Asset Management Market