
 Canada Asset Management Market | 2026-2036
Canada Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Asset Management Market Outlook
Active management fee spreads over passive alternatives is narrowing as institutional mandates shift toward lower-cost structures. BlackRock Asset Management Canada leverages its ETF infrastructure to capture flows from fee-sensitive pension sponsors. Manulife Investment Management anchors its position through proprietary insurance-linked asset origination. Brookfield Asset Management dominates alternative credit and infrastructure deployment, extending its global platform into Canadian institutional portfolios.
Canada asset management encompasses the professional administration of investment portfolios across equities, fixed income, real estate, and alternative assets, governed by prospectus requirements and fiduciary standards under provincial securities legislation. The practice centers on optimizing risk-adjusted returns for beneficiaries while maintaining liquidity, transparency, and regulatory compliance across pooled and segregated structures. Pension fund allocations to alternative investments now represent the fastest-expanding asset class segment, driven by liability-matching imperatives and yield compression in traditional fixed income. Exchange-traded funds continue to displace open-end mutual fund structures in retail channels, with fee compression most severe in plain-vanilla equity exposures where scale determines profitability.
The Canadian Securities Administrators coordinate provincial registration and disclosure standards, while OSFI mandates capital and liquidity buffers for bank-owned asset managers that constrain leverage and product complexity. CIRO rules govern dealer conduct and client suitability, shaping product distribution economics and advisor compensation structures. Stakeholders must monitor whether proposed CSA reforms to embedded compensation and enhanced fund cost disclosure will accelerate advisor migration toward fee-based models or compress product manufacturing margins further.
Market Dynamics
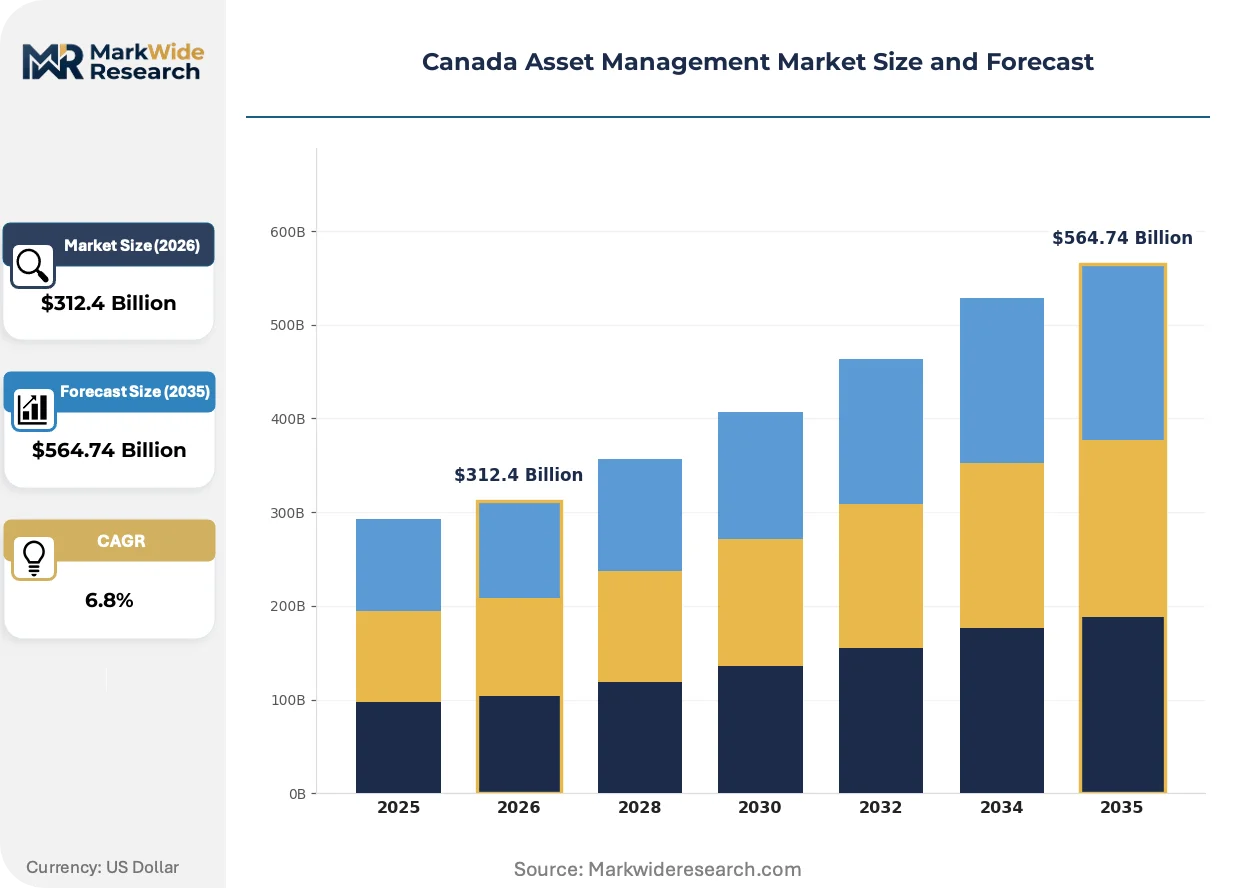
Pension fund liability-matching imperatives are compressing active management fee spreads while accelerating flows into alternative credit and infrastructure structures across Ontario and Quebec.
Growth Catalysts
- CSA Harmonized Regulatory Framework:The Canadian Securities Administrators' unified prospectus and disclosure standards reduce cross-provincial friction for product distribution. Asset managers gain operational scale through simplified registration.
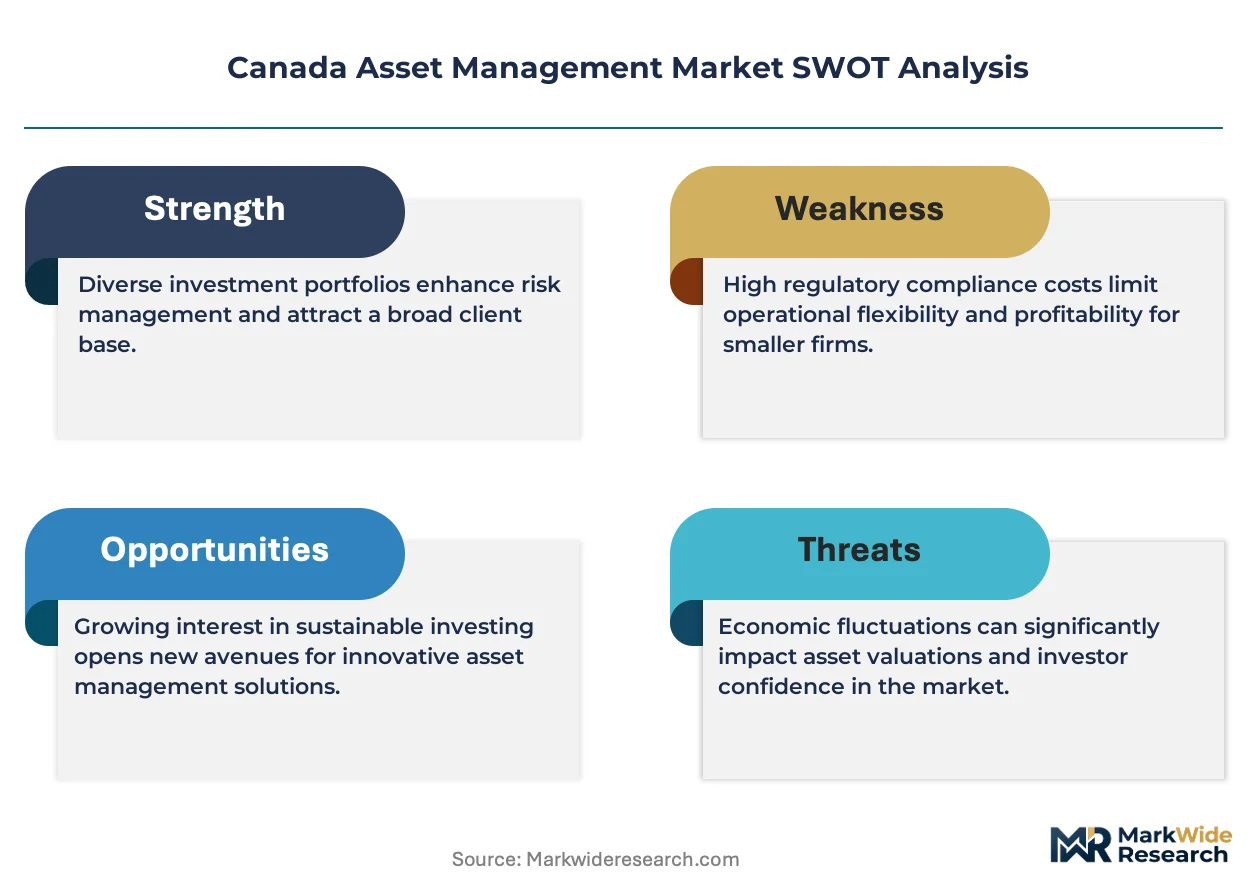
- Pension Fund Alternative Allocation:Ontario Teachers' Pension Plan and Caisse de dépôt drive demand for private credit and infrastructure. Liability duration extension necessitates yield-seeking beyond public fixed income.
- ETF Infrastructure Expansion:Toronto Stock Exchange listing protocols and market-maker incentives deepen liquidity for exchange-traded products. Retail channels migrate from higher-cost mutual fund wrappers.
Market Restraints
- OSFI Capital Buffer Requirements:Office of the Superintendent of Financial Institutions mandates constrain leverage at bank-owned asset managers. Product complexity and balance sheet deployment face prudential limits.
- Fee Compression in Plain-Vanilla Equity:Scale-driven profitability erosion in passive equity exposures compresses manufacturing margins. Differentiation requires specialized origination or alternative asset capabilities.
- Concentrated Distribution Economics:CIRO dealer conduct rules and embedded compensation structures concentrate advisor relationships with incumbent manufacturers. New entrants face shelf-space barriers.
Strategic Opportunities
- Quebec Pension Sovereign Alignment:Caisse de dépôt et placement du Québec's climate transition mandate creates dedicated capital pools for green infrastructure and carbon-intensive asset repositioning.
- Insurance-Linked Asset Origination:Proprietary liability-driven investment structures from life insurers unlock captive demand for long-duration private assets. Manufacturing and distribution integration captures full value chain.
- Wealth Management Channel Disintermediation:Direct-to-investor digital platforms bypass traditional dealer networks for fee-sensitive retail segments. Robo-advisory penetration remains below saturation in Prairie provinces.
Industry Challenges
- Quantitative Portfolio Construction Talent Scarcity:Systematic and factor-based strategy development requires specialized skill sets concentrated in Toronto and Montreal. Compensation inflation pressures non-bank managers.
- Legacy System Integration Complexity:Consolidation of back-office infrastructure across acquired asset management platforms demands multi-year technology expenditure. Data architecture standardization delays product harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Asset Management Market |
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investor Type: Institutional Investors, Retail Investors, High-Net-Worth Individuals, Pension Funds Fund Structure: Open-End Funds, Closed-End Funds, Exchange-Traded Funds, Unit Trusts Asset Class: Equities, Fixed Income, Real Estate, Alternative Investments Investment Strategy: Growth Investing, Value Investing, Income Investing, Market Neutral |
| Companies Covered | RBC Global Asset Management, TD Asset Management, Manulife Investment Management, BlackRock Asset Management Canada, BMO Global Asset Management, Sun Life Financial, Brookfield Asset Management, Fidelity Investments, CI Financial Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Asset Management Market Strategic Shifts
Active-to-passive migration is fragmenting manufacturing economics while regulatory disclosure mandates and climate-alignment imperatives reshape product development priorities.
Artificial intelligence-driven risk analytics is hybridizing traditional fundamental credit analysis with alternative data ingestion. Canadian pension sponsors now demand machine-learning overlays for private market due diligence. This convergence compresses research timelines while elevating data infrastructure expenditure requirements.
The Canadian Securities Administrators' proposed reforms to embedded compensation disclosure and fund cost transparency are accelerating advisor migration toward fee-based advisory models. Dealer platforms face margin compression as trail commissions face regulatory scrutiny. Product manufacturers must restructure distribution economics or cede shelf access to lower-cost structures.
Institutional procurement of asset management services is unbundling alpha generation from beta exposure through mandate segmentation. Ontario municipal pension plans now separately source passive implementation and active overlay strategies. This bifurcation concentrates scale advantages with specialist providers in each layer while compressing blended-fee structures.
Canada Asset Management Market Segmentation
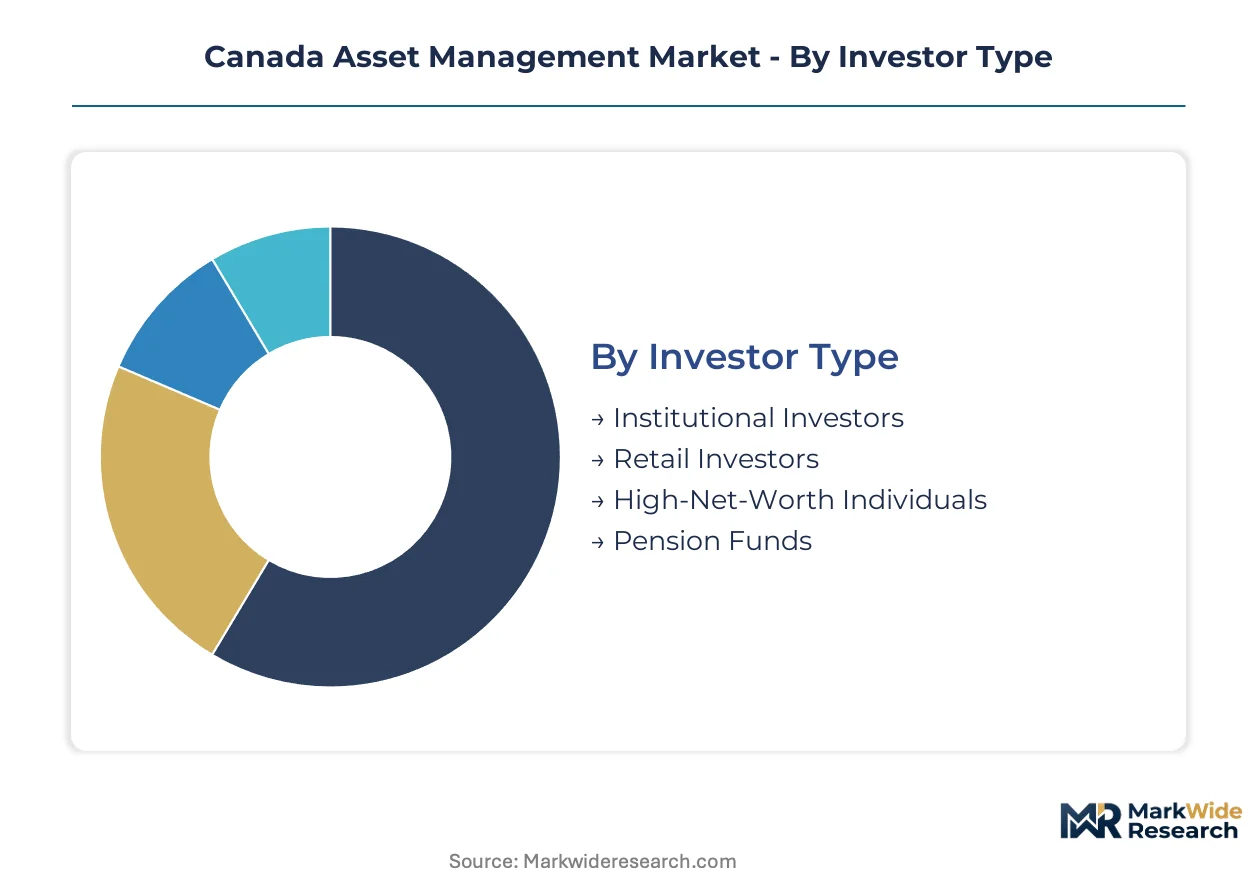
Segmentation in the Canada asset management market reveals how investor mandates, regulatory wrappers, and return objectives reshape product economics. Understanding these divides explains why fee compression concentrates in certain channels while alternative assets command premium pricing elsewhere.
Investor Type:
Mature institutional relationships anchor fee stability while emerging retail digitalization disrupts traditional distribution economics.
- Institutional Investors:Corporate treasury desks, insurance general accounts, and endowment funds deploy segregated mandates with customized benchmarks. Ontario municipal pension plans unbundle alpha and beta sourcing, compressing blended fees while elevating specialist procurement.
- Pension Funds:Liability-driven investment frameworks dominate Ontario Teachers' and Caisse de dépôt deployment. Duration-matching imperatives drive private credit and infrastructure allocation beyond public market capacity.
- Retail Investors:Mass-affluent households access products through CIRO-regulated dealer networks. Embedded compensation scrutiny from CSA reforms accelerates migration toward fee-based advisory models.
- High-Net-Worth Individuals:Family office structures and bespoke portfolio construction demand illiquid alternative access alongside traditional liquidity sleeves.
Institutional Investors retain volume leadership; Pension Funds hold the steepest expansion curve.
Fund Structure:
Cost tier stratification separates scale-driven passive vehicles from complexity-tolerant illiquid wrappers.
- Exchange-Traded Funds:Toronto Stock Exchange listing protocols and designated market-maker arrangements sustain tight bid-ask spreads. Retail channel displacement of mutual fund wrappers accelerates as CIRO dealers face trail commission compression.
- Open-End Funds:Daily liquidity provisions and prospectus disclosure requirements govern traditional mutual fund distribution. Manufacturing margins erode most severely in plain-vanilla equity exposures where scale determines profitability.
- Closed-End Funds:Fixed capital structures enable illiquid asset deployment without redemption pressure. Leverage constraints from OSFI capital buffers limit complexity at bank-owned managers.
- Unit Trusts:Flow-through tax structures concentrate in real estate and energy income vehicles. Quebec and Alberta investor bases show persistent preference for trust-format yield products.
Exchange-Traded Funds gain share fastest; Open-End Funds retain the largest asset base.
Asset Class:
Application-driven allocation shifts reward yield-seeking beyond traditional fixed income while equity beta commoditizes.
- Alternative Investments:Private credit, infrastructure equity, and natural resources exposure match extended liability duration. Brookfield Asset Management and OTPP co-investment structures concentrate origination capability in Toronto and Montreal.
- Fixed Income:Government and corporate bond mandates face yield compression and duration extension pressures. Pension liability hedging demands long-duration private credit substitution.
- Equities:Domestic and international equity exposure faces passive migration and fee compression. Active differentiation requires factor tilts or concentrated fundamental selection.
- Real Estate:Direct property and REIT allocation serves inflation-hedging and income objectives. Caisse de dépôt climate transition mandate redirects capital toward green building retrofit and carbon-intensive asset repositioning.
Fixed Income retains the deepest institutional allocation; Alternative Investments climb the fastest.
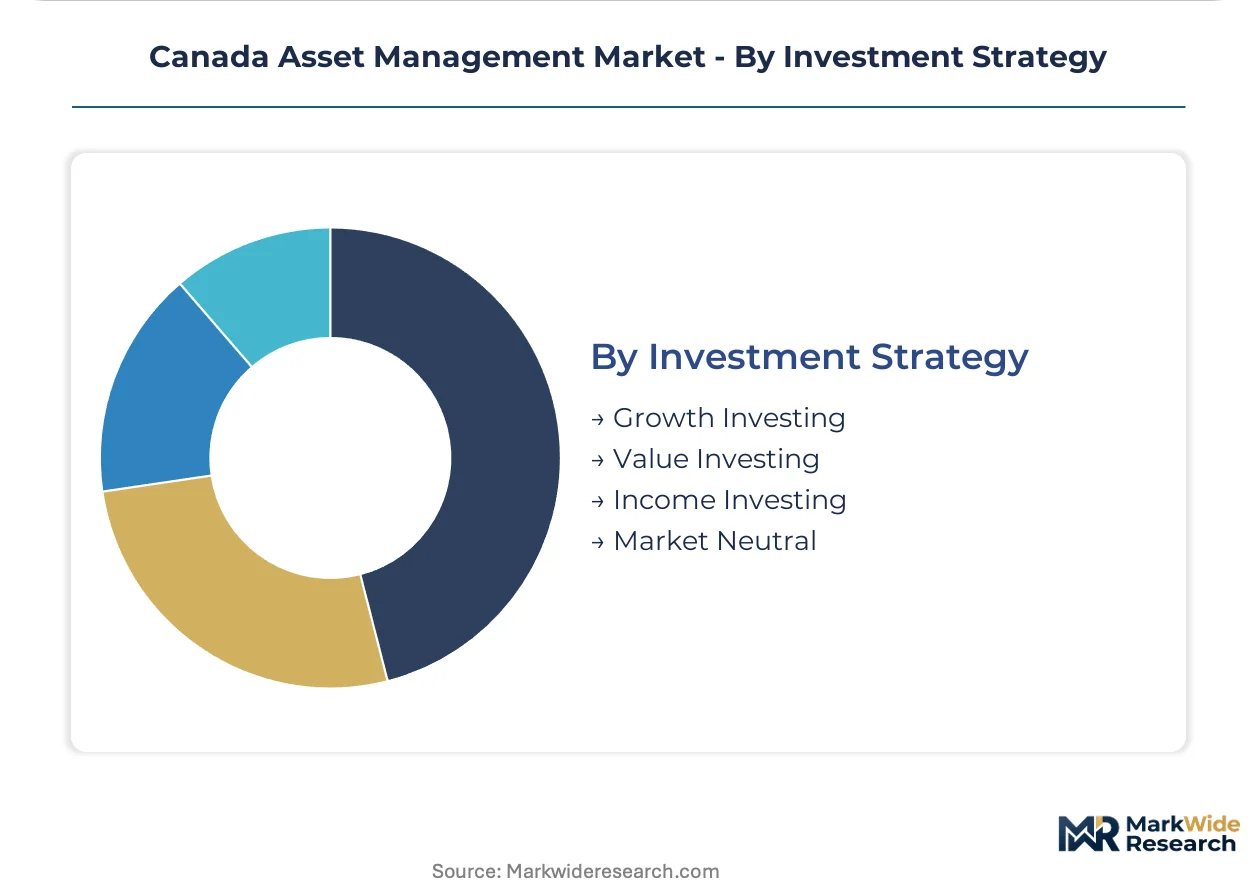
Investment Strategy:
Customer-type differentiation separates outcome-oriented institutional procurement from retail risk-tolerance segmentation.
- Income Investing:Yield-focused mandates prioritize cash flow stability and liability matching. Life insurer general accounts and pension fixed income desks drive demand for long-duration private credit origination.
- Growth Investing:Capital appreciation targets dominate younger retail investor profiles and endowment spending rules. Technology and healthcare sector concentration requires active security selection to justify fee premiums.
- Value Investing:Discount-to-intrinsic-value approaches face factor performance headwinds and asset flow challenges. Deep value specialization concentrates in boutique Toronto managers.
- Market Neutral:Absolute return objectives with beta elimination appeal to defined benefit plans seeking uncorrelated return streams. Quantitative portfolio construction talent scarcity elevates compensation costs for systematic strategy development.
Income Investing commands the largest mandate volume; Market Neutral strategies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fee sensitivity concentrates in Ontario's retail corridors while institutional procurement in Quebec tolerates premium pricing for specialized mandates. The report identifies this demand-elasticity divide as shaping regional product strategies across Canadian asset management.
Ontario
Toronto's Bay Street corridor anchors institutional custody and trading infrastructure while retail investors in the Greater Toronto Area drive ETF adoption. The Ontario Securities Commission enforces prospectus disclosure standards that harmonize with CSA national instruments. Pension funds at Ontario Teachers' Pension Plan deploy private credit origination through downtown Toronto co-investment structures.
Quebec
Montreal's fund management cluster concentrates French-language product manufacturing and sovereign wealth alignment strategies. The Autorité des marchés financiers supervises registration and embedded compensation disclosure under provincial securities law. Caisse de dépôt et placement du Québec channels climate transition capital through Montreal-based infrastructure equity teams.
Alberta
Calgary's energy-focused institutional investors demand natural resource and carbon transition exposure within diversified portfolios. Alberta Securities Commission registration requirements align with CSA harmonized standards for cross-border distribution. Energy sector pension plans in Calgary deploy private equity through captive origination platforms.
British Columbia
Vancouver's wealth management channels serve Asia-Pacific connected high-net-worth households through cross-border advisory structures. The British Columbia Securities Commission mandates enhanced fund cost disclosure that accelerates fee-based advisory migration. Family office concentration in Vancouver's West Side drives demand for bespoke alternative asset access.
Atlantic Canada
Halifax and St. John's municipal pension plans seek yield enhancement through pooled fund structures given limited local origination capacity. Provincial securities regulators in Nova Scotia and Newfoundland and Labrador apply CSA harmonized standards with limited local rule variation. Regional dealer networks in Halifax concentrate distribution of bank-owned manufacturer products.
Canada Asset Management Market Competitive Environment
Capability concentration sits with alternative origination specialists; scale advantage sits with diversified banking platforms. The market structures around three tiers: bank-owned asset managers with captive distribution, insurance-linked manufacturers with proprietary liability matching, and independent boutiques with specialized factor or ESG capabilities. Dominant competitive moves include consolidation of back-office infrastructure across acquired platforms and unbundling of alpha generation from beta implementation in institutional procurement.
Among bank-owned diversified platforms, RBC Global Asset Management and TD Asset Management occupy positions defined by integrated manufacturing and distribution economics. BlackRock Asset Management Canada anchors the scale-driven passive tier through ETF infrastructure and institutional index mandate dominance. Brookfield Asset Management exemplifies alternative origination capability concentration, extending infrastructure and private credit deployment into Canadian institutional portfolios from its Toronto base.
| Leading Market Players |
|---|
| RBC Global Asset Management |
| TD Asset Management |
| Manulife Investment Management |
| BlackRock Asset Management Canada |
| BMO Global Asset Management |
| Sun Life Financial |
| Brookfield Asset Management |
| Fidelity Investments |
| CI Financial Corp. |
| Others |
Value Chain & Pricing Dynamics
OSFI capital buffer requirements as a regulatory chokepoint determine both pricing tier spreads and supply chain shape. The Office of the Superintendent of Financial Institutions mandates constrain leverage at bank-owned asset managers, compressing manufacturing margins in plain-vanilla equity while elevating premium pricing for alternative origination capabilities that sit outside prudential limits.
Pricing Analysis
After-sales revenue from advisory services and overlay mandates drives lifetime value in institutional relationships. Three-tier pricing structure across premium alternative origination, standard active management, and economy passive implementation dominates the market. Price differentiation rests on proprietary deal flow access and quantitative portfolio construction certification. Cost compression in economy-tier equity beta is intensifying because scale-driven providers capture flows from fee-sensitive pension sponsors. Retail investors through CIRO-regulated dealer networks show highest price sensitivity; pension funds deploying liability-matching alternatives show lowest.
Supply Chain Analysis
Tariff exposure between Canada and the United States dominates supply chain risk for cross-border distribution infrastructure. Asset management capability concentrates in Canada, the United Kingdom, and the United States. Technology infrastructure and data analytics talent feed from Toronto and Montreal clusters. Single-source vulnerability sits with concentrated quantitative strategy development talent pools. Distribution runs through CIRO-regulated dealer networks and direct-to-investor digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Systematic strategy development talent scarcity defines competitive advantage in this market. Firms securing machine-learning overlay capabilities and alternative data infrastructure gain procurement preference from Ontario and Quebec pension sponsors.
For Market Incumbents: Harden origination lock-in through captive infrastructure equity partnerships with Caisse de dépôt and Ontario Teachers' Pension Plan. Deepen proprietary liability-matching product suites before CSA embedded compensation reforms accelerate advisor migration. Vertical integration into data analytics infrastructure protects margin position against fee compression in passive tiers. For New Entrants and Emerging Players: Build out direct-to-investor digital platforms targeting Prairie provinces where robo-advisory penetration remains below saturation. Capture shelf space in Atlantic Canada municipal pension plans seeking yield enhancement through pooled fund structures. Lead with fee-based advisory models ahead of CSA disclosure mandates. For Investors and Strategic Acquirers: CSA harmonized regulatory framework reshapes the acquisition landscape by elevating scale advantages in cross-provincial product distribution. Long-term viability favors platforms with integrated alternative origination and manufacturing capabilities. Boutique quantitative specialists with factor-based track records represent priority acquisition archetypes. Watch for advisor migration velocity toward fee-based models as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Origination Platform Expansion | Captures Caisse de dépôt climate transition capital pools through Montreal-based infrastructure teams. |
| Quantitative Strategy Development Investment | Secures machine-learning overlay capabilities demanded by Ontario municipal pension plans. |
| Fee-Based Advisory Model Migration | Anticipates CSA embedded compensation reforms before trail commission compression accelerates. |
| Direct-to-Investor Digital Platform Launch | Bypasses CIRO dealer concentration in Prairie provinces with below-saturation robo-advisory penetration. |
| Back-Office Infrastructure Consolidation | Reduces multi-year technology expenditure burdens from acquired asset management platform integration. |
Study Parameters
Initial hypotheses were tested against primary input from pension fund investment officers, insurance general account managers, CIRO dealer platform heads, quantitative strategy developers, and regulatory affairs specialists at CSA member agencies and refined through secondary validation. Bottom-up and top-down triangulation combined interview-derived procurement patterns with regulatory filing analysis, OSFI prudential guideline documentation, CSA national instrument disclosures, and Toronto Stock Exchange listing protocol records.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include investor type, fund structure, asset class, investment strategy, and provincial regulatory cluster. CAGRs were derived through growth driver decomposition and scenario-weighted probability assessment. Forecast inputs incorporated pension liability duration extension trajectories and ETF flow migration patterns from mutual fund wrappers.
Stress conditions across OSFI capital buffer adjustments, CSA reform implementation timelines, and quantitative talent compensation inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization progress and pension alternative allocation ceilings. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Global AI in Asset Management Market
Asset Management
Equity Management Tool Market
Asset Management
India Mutual Fund Market
Asset Management
Asia-Pacific Utilities Asset Management Market
Asset Management
China Mutual Funds Market
Asset Management
India Asset Management Market
Asset Management
US Pension Funds Market
Asset Management
Global Remote Asset Management Market
Asset Management
Europe Asset Management Market
Asset Management
Fund Management Fee Market
Asset Management
Mutual Fund Assets Market
Asset Management
Healthcare Asset Management Market
Asset Management
Asset Optimization Solutions Market
Asset Management
Assets Under Management Market
Asset Management
US Healthcare Assets Management Market
Asset Management
India AMC Industry Market