
 Mutual Fund Assets Market | 2026-2036
Mutual Fund Assets Market Size, Share, and Industry Trends Forecast 2026-2036
Mutual Fund Assets Market Intelligence
Market Context with Strategic Players
Buyer concentration in the mutual fund industry is shifting as institutional pension pools consolidate mandates while retail participation fragments across robo-advisory and direct-to-consumer channels. BlackRock leverages its Aladdin risk analytics platform to sustain dominance across passive and active mandates globally. Vanguard anchors retail investor trust through its investor-owned cooperative structure and ultra-low expense ratios. Fidelity Investments competes aggressively on digital brokerage integration, combining mutual fund distribution with self-directed trading ecosystems.
Technical Definition and Structural Segments
Mutual fund assets represent pooled investment vehicles registered under the Investment Company Act, professionally managed portfolios holding diversified securities baskets with daily net asset value (NAV) pricing and regulated redemption liquidity. The primary commercial purpose is to provide retail and institutional investors with diversified market exposure, professional management, and regulatory safeguards unavailable through direct security ownership. Equity funds occupy the largest asset pool but face margin compression from passive indexing, while hybrid strategies are capturing fastest-growing inflows as investors seek volatility-buffered returns. Institutional investor type segments command premium fee structures despite representing smaller unit counts, whereas retail channels drive volume scale but exert downward pressure on management expense ratios.
Regulatory Framework and Forward Outlook
SEC 1940 Act oversight and FINRA sales practice rules govern US fund operations, while EU SFDR and MiFID II disclosure standards reshape cross-border product distribution and ESG labeling integrity. India's SEBI mutual fund regulations mandate stringent valuation norms and distributor commission caps, tightening market access for foreign asset managers. China's CSRC fund supervision framework imposes foreign ownership limits and qualified domestic institutional investor (QDII) quotas that constrain capital mobility. Stakeholders must monitor evolving SEC climate disclosure proposals and EU taxonomy alignment requirements to preempt product reclassification risks and distribution channel restrictions.
Market Dynamics
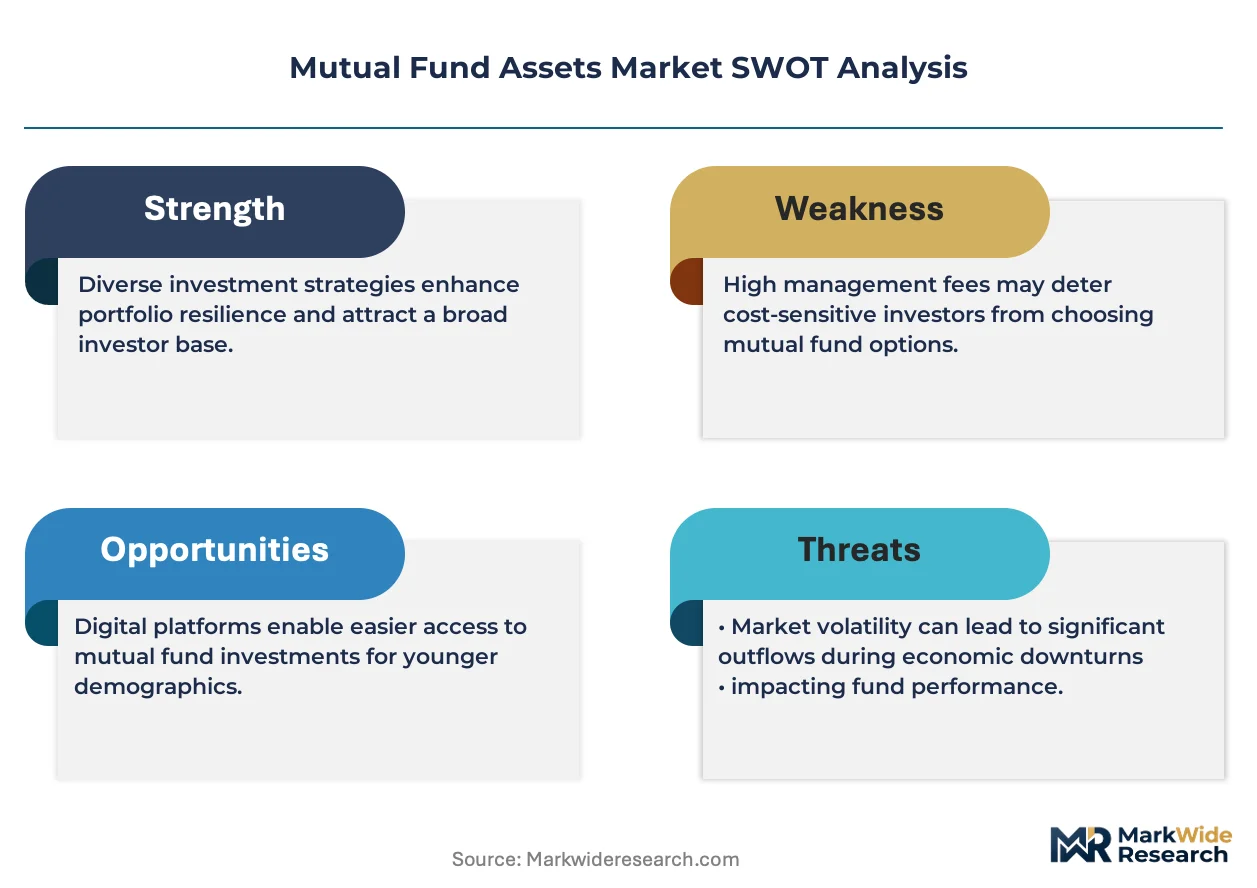
Passive indexing algorithms and zero-commission digital brokerage platforms are compressing active management fee structures while redistributing investor flows toward direct indexing and ETF wrappers.
Growth Catalysts
- SEC Retail Investor Protection Rule:Enhanced disclosure standards around fee transparency are accelerating investor migration toward lower-cost fund structures, expanding total addressable market participation.
- Artificial Intelligence-driven portfolio construction:Machine learning tools for risk factor analysis and tax-loss harvesting are democratizing sophisticated strategies previously reserved for institutional mandates.
- India's domestic savings mobilization:Systematic Investment Plan (SIP) penetration in tier-2 and tier-3 cities is converting household gold holdings into regulated mutual fund assets through distributor networks.
Market Restraints
- Management fee compression:Passive fund expense ratios approaching single basis points are squeezing revenue per dollar of assets under management across equity fund categories.
- Qualified Domestic Institutional Investor quota constraints:China's capital mobility restrictions limit foreign fund manager market access and repatriation flexibility for cross-border pooled vehicles.
- Substitution by direct indexing platforms:Separately managed accounts offering customization without fund-level tax liabilities are capturing taxable investor flows from conventional mutual fund structures.
Strategic Opportunities
- Brazil's pension reform implementation:Mandatory contribution shifts from public to private pension systems are creating captive demand for target-date and balanced fund products.
- EU Sustainable Finance Disclosure Regulation Article 8/9 classification:ESG-labeled fund frameworks are attracting Article 173-mandated institutional capital from French and Dutch pension pools.
- Tokenized fund share settlement:Distributed ledger infrastructure for same-day NAV settlement and fractional share ownership is integrating with existing transfer agent systems.
Industry Challenges
- Quantitative risk modeling talent scarcity:Shortages of professionals proficient in Aladdin-style portfolio analytics and factor-based construction are inflating compensation costs for active managers.
- Legacy core banking system integration:Mainframe-dependent custodian banks face multi-year timelines to connect with real-time data feeds required for intraday liquidity products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mutual Fund Assets Market |
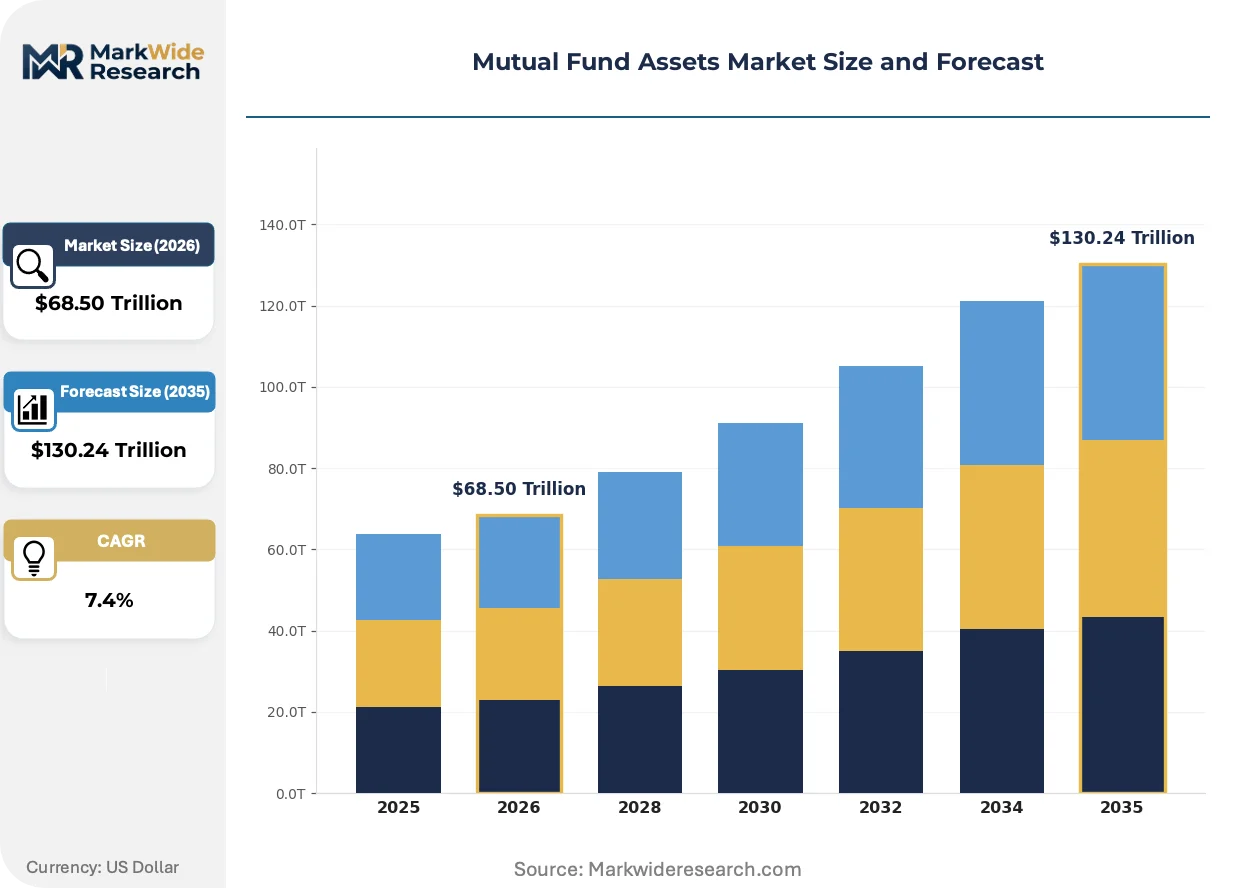
| Market Size in 2026 | $68.50 Trillion |
| Market Size in 2035 | $130.24 Trillion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fund Type: Equity, Debt, Hybrid, Money Market Investment Strategy: Active, Passive, Indexing, Growth Investor Type: Retail, Institutional, High-Net-Worth, Corporate Fund Size: Small Cap, Mid Cap, Large Cap, Mega Funds |
| Companies Covered | State Street Global Advisors, J.P. Morgan Asset Management, BlackRock, Invesco, Goldman Sachs Asset Management, Vanguard, Capital Group, T. Rowe Price Group, Fidelity Investments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mutual Fund Assets Market Strategic Shifts & Innovations
Algorithmic personalization engines and regulatory taxonomy alignment are reconfiguring how fund products are manufactured, distributed, and consumed across retail and institutional channels.
Artificial intelligence-powered natural language processing is integrating into regulatory filing automation and investor communication workflows. Asset managers in the United States and United Kingdom are deploying these tools to parse SEC comment letters and automate Form N-CSR preparation. The structural consequence is compressing compliance staffing ratios while accelerating product launch timelines.
EU Corporate Sustainability Reporting Directive disclosure mandates are forcing fund managers to source granular Scope 3 emissions data from portfolio companies. This regulatory pressure is reshaping supply chain due diligence requirements for private equity fund-of-funds and infrastructure debt vehicles. European institutional investors are responding by embedding CSRD alignment clauses into investment management agreements.
Direct-to-investor distribution platforms are disintermediating traditional broker-dealer networks for equity fund sales. Robo-advisory channels in the United States and Australia are capturing younger demographic cohorts through mobile-first onboarding and micro-investment features. This channel shift is most visible in target-date fund categories where automated glide path adjustments replace advisor-mediated rebalancing conversations.
Mutual Fund Assets Market Segmentation
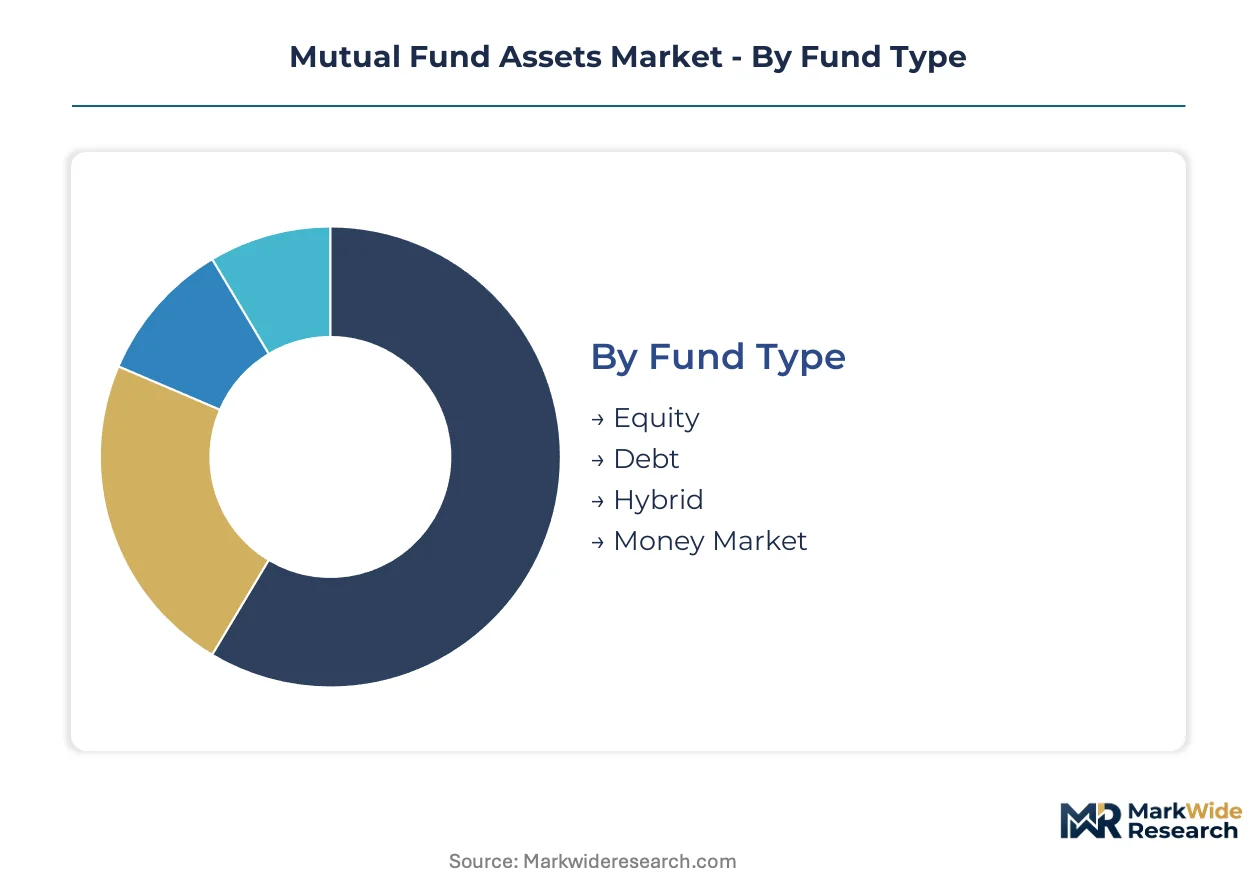
Segmentation in mutual fund assets reveals how fee structures, liquidity profiles, and regulatory treatment diverge across investor pools and product architectures. Understanding these fault lines helps stakeholders anticipate where passive compression will accelerate and where active premiums can still be defended.
Fund Type:
Standalone fund vehicles dominate retail distribution channels, while embedded fund-of-funds structures proliferate within insurance wrappers and defined contribution platforms.
- Equity:Comprises diversified stock portfolios holding domestic and international securities with daily NAV pricing and SEC 1940 Act registration requirements. Demand concentrates in the United States and India where household equity participation is deepening through systematic investment plans and target-date retirement products. Active equity faces relentless fee compression from passive alternatives.
- Debt:Fixed-income portfolios holding government securities, corporate bonds, and municipal obligations with duration-matched maturity profiles. Institutional pension pools in the Netherlands and French insurance conglomerates anchor demand for investment-grade debt funds under Solvency II and Article 173 constraints. Duration risk management drives manager selection.
- Hybrid:Multi-asset vehicles blending equity and fixed-income exposure with dynamic rebalancing protocols. Balanced allocation strategies attract risk-averse retail investors seeking volatility-buffered returns through single-ticket solutions.
- Money Market:Short-duration instruments maintaining stable NAV through high-quality liquid asset holdings. Corporate treasury departments utilize these vehicles for cash management liquidity in overnight and weekly settlement windows.
Volume placements concentrate in Equity; the faster expansion belongs to Hybrid.
Investment Strategy:
Cost tier stratification separates premium-priced active management from commoditized indexing, with hybrid approaches capturing middle-market fee tolerance.
- Active:Discretionary security selection by portfolio managers charging expense ratios reflecting research intensity and trading activity. High-net-worth family offices and endowment funds in Boston and London sustain demand for concentrated active mandates where information asymmetries persist in small-cap and emerging market categories.
- Passive:Rules-based replication of benchmark indices with minimal portfolio turnover and single-digit basis point fee structures. Vanguard and BlackRock passive vehicles dominate 401(k) menu placements across United States employer-sponsored plans.
- Indexing:Mechanical tracking of broad market or sector-specific benchmarks with precise factor exposure control. Robo-advisory platforms in Australia and the United States deploy indexing as core portfolio building blocks for mass-affluent demographics.
- Growth:Concentrated equity positions in companies exhibiting above-average revenue expansion and reinvestment rates. Technology sector concentration defines growth fund positioning, attracting younger retail investors through direct-to-consumer platforms.
Fee compression hits Active most severely; Indexing gains share fastest through platform distribution scale.
Investor Type:
Customer type determines distribution economics, with institutional mandates supporting relationship-manager staffing while retail channels demand automated onboarding infrastructure.
- Retail:Individual investors accessing mutual funds through broker-dealer networks, direct-sold platforms, or employer retirement plans. India's tier-2 and tier-3 cities are converting household savings into retail fund assets through distributor-led systematic investment plan penetration.
- Institutional:Pension funds, insurance companies, and sovereign wealth vehicles negotiating customized fee schedules and separate account structures. Dutch and French pension pools drive ESG-labeled fund demand under EU SFDR Article 8 and 9 classification requirements.
- High-Net-Worth:Affluent individuals with investable assets above threshold minimums accessing share classes with reduced expense ratios and personalized tax management. Private banking divisions at Fidelity and Schwab compete for this segment through integrated wealth management offerings.
- Corporate:Non-financial enterprises deploying treasury reserves into liquidity-managed fund vehicles for operational cash optimization. Money market funds serve this function predominantly in United States and European corporate treasury operations.
Retail channels generate the highest unit volumes; Institutional relationships deliver the steepest expansion trajectory in ESG-mandated categories.
Fund Size:
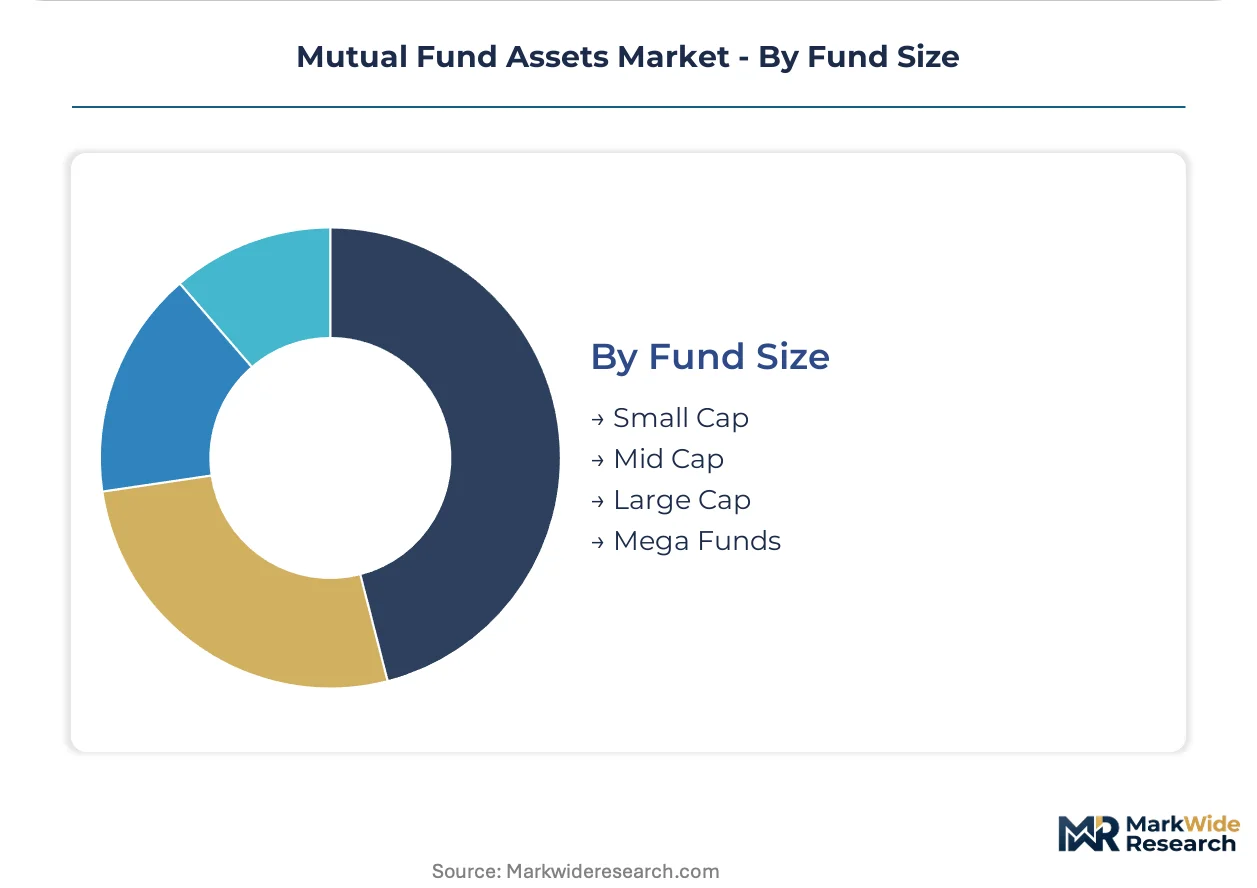
Scale economics create divergent competitive dynamics, with mega funds leveraging operational leverage while small-cap specialists defend performance-based fee premiums.
- Small Cap:Funds with assets under management below threshold thresholds focusing on niche strategies or emerging market exposures where capacity constraints limit scale. Boutique managers in London and Singapore maintain active small-cap equity franchises where information advantages persist.
- Mid Cap:Intermediate-scale vehicles balancing operational efficiency with strategy flexibility, often serving as incubation platforms for emerging manager talent. Mid-tier fund complexes compete on specialized sector exposures and regional expertise.
- Large Cap:Established funds with substantial asset bases achieving expense ratio compression through operational scale and negotiating leverage with service providers. Large-cap equity index funds dominate 401(k) core menu placements in the United States.
- Mega Funds:Industry-dominant vehicles with assets exceeding institutional thresholds, typically passive index trackers or flagship active strategies from major asset managers. BlackRock and Vanguard mega funds benefit from self-reinforcing scale advantages in trading cost absorption and research coverage access.
Volume placements concentrate in Mega Funds; the fastest climb in assets is occurring in Mid Cap specialist strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household savings-to-investment pipelines are deepening fastest in the United States, China, and India. These three markets command disproportionate mutual fund asset flows as retail participation accelerates through digital distribution channels.
United States
Employer-sponsored 401(k) plans and individual retirement accounts channel steady inflows into target-date and index fund vehicles. SEC disclosure reforms under the Retail Investor Protection Rule mandate enhanced fee transparency, accelerating migration toward lower-cost fund structures. Boston and New York asset management clusters dominate active equity and fixed-income mandate origination.
China
Rising middle-class wealth accumulation and policy-driven capital market deepening are expanding mutual fund penetration beyond coastal urban centers. CSRC qualified domestic institutional investor quotas constrain foreign manager market access while directing domestic savings into locally registered pooled vehicles. Shanghai and Shenzhen fund complexes lead product innovation in hybrid and money market categories.
India
Systematic investment plan penetration in tier-2 and tier-3 cities converts household gold holdings into regulated mutual fund assets through distributor networks. SEBI mutual fund regulations enforce stringent valuation norms and distributor commission caps that tighten market access for foreign asset managers. Mumbai anchors fund management operations while Delhi-NCR and Bangalore drive digital distribution platform development.
United Kingdom
Defined contribution pension auto-enrollment and platform-based retail distribution sustain steady fund inflows despite post-Brexit regulatory divergence from EU frameworks. FCA consumer duty rules reshape product governance and fee disclosure obligations for fund manufacturers. London's City and Canary Wharf clusters concentrate European headquarters for US and Asian asset managers serving cross-border mandates.
Brazil
Mandatory contribution shifts from public to private pension systems under pension reform implementation create captive demand for target-date and balanced fund products. ANVISA and CVM regulatory frameworks govern fund registration and distribution conduct. São Paulo's financial district anchors Latin America's largest asset management concentration, with Rio de Janeiro serving as secondary fund administration hub.
Mutual Fund Assets Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue direct-to-investor digital platforms and ESG-labeled product architectures. The market structure concentrates around mega-scale passive index providers and boutique active specialists, with mid-tier firms competing on hybrid strategy differentiation. Three archetypes dominate: scale-driven index giants, relationship-heavy institutional active managers, and technology-integrated direct distribution platforms. Competitive moves center on strategic partnerships with robo-advisory channels and portfolio diversification into private market fund-of-funds wrappers.
Within the scale-driven tier, BlackRock and Vanguard exemplify operational leverage through ultra-low expense ratios and self-reinforcing asset accumulation. State Street Global Advisors occupies a position among institutional-focused specialists emphasizing risk analytics and custody-integrated solutions. These three firms anchor competitive dynamics across both retail retirement platforms and institutional pension mandates.
| Leading Market Players |
|---|
| State Street Global Advisors |
| J.P. Morgan Asset Management |
| BlackRock |
| Invesco |
| Goldman Sachs Asset Management |
| Vanguard |
| Capital Group |
| T. Rowe Price Group |
| Fidelity Investments |
| Others |
Cost & Logistics Intelligence
Benchmark fee compression indices for passive equity vehicles cascade through distribution economics, compressing revenue per dollar managed while concentrating pricing power among mega-scale providers with captive custody infrastructure.
Pricing Analysis
Volume-scale passive vehicles command single-digit basis point expense ratios while active mandates defend premium pricing through research intensity and tax-loss harvesting sophistication. Price differentiation separates institutional share classes with customized liquidity terms from retail tiers burdened by distribution overlays. Fee compression intensifies as zero-commission brokerage platforms disintermediate traditional load structures. Retail direct-to-consumer channels exhibit highest price sensitivity; institutional separate accounts demonstrate lowest sensitivity due to performance-based fee anchoring.
Supply Chain Analysis
Freight and settlement infrastructure costs concentrate in United States, Ireland, and Luxembourg as domiciliation hubs for cross-border fund vehicles. Transfer agent operations, custody banking, and fund administration services draw from specialized technology vendors and legacy mainframe-dependent financial institutions. Single-source vulnerability in transfer agent consolidation poses structural risk to same-day NAV settlement capabilities. Distribution runs through broker-dealer networks, employer-sponsored retirement platforms, and emerging robo-advisory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fee compression mechanics and passive indexing dominance are forcing consolidation among sub-scale active managers unable to sustain research infrastructure against declining revenue per dollar managed.
For Market Incumbents: Cement scale advantages through Aladdin-style risk analytics platform licensing and captive custody infrastructure buildout. Defend against direct indexing substitution by embedding tax-loss harvesting automation into core fund offerings. Prioritize vertical integration into transfer agent and fund administration services to capture fee stack compression. For New Entrants and Emerging Players: Robo-advisory platforms present the most penetrable channel for algorithmic personalization engines targeting mass-affluent demographics in tier-2 Indian cities and Australian superannuation rollovers. Target ESG-labeled hybrid strategies where SFDR Article 8/9 classification creates regulatory moats. Deploy direct-to-investor mobile onboarding with micro-investment thresholds below traditional fund minimums. For Investors and Strategic Acquirers: Distressed-cycle entries favor boutique active specialists with concentrated emerging market or small-cap franchises in London and Singapore. Long-term viability hinges on capacity-constrained strategy preservation and founder retention mechanisms. Watch for QDII quota expansion signals from CSRC as inflection indicator for China market re-entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Indexing Platform Launch | Captures taxable investor flows seeking customization without fund-level tax liabilities. |
| SFDR Article 8/9 Certification | Unlocks Article 173-mandated capital from Dutch and French pension pools. |
| Transfer Agent Technology Modernization | Enables same-day NAV settlement and fractional share ownership infrastructure. |
| Robo-Advisory Channel Partnership | Secures automated glide path placement in target-date fund categories for younger demographics. |
| ESG Data Provider Acquisition | Integrates granular Scope 3 emissions sourcing for CSRD alignment and product differentiation. |
Research Approach
Multi-period observation of SIP penetration rates, QDII quota utilization, and expense ratio trajectories anchored the trend analysis, supplemented by interviews with fund-of-funds portfolio managers, pension fund investment officers, distributor network heads, and SEBI regulatory affairs specialists. Secondary validation drew from SEC Form N-CSR filings, EU SFDR disclosure databases, AMFI monthly flow reports, and CSRC fund registration bulletins. Bottom-up asset flow modeling triangulated against top-down household savings rate projections.
Input-output matrices mapped fund type, investment strategy, investor type, and fund size dimensions across the projection horizon. CAGRs derived from regression analysis of historical flow volatility, demographic savings conversion rates, and regulatory reform implementation timelines. Forecast inputs incorporated robo-advisory platform adoption curves and ESG-labeled fund reclassification probabilities under evolving taxonomy standards.
Caveats apply where SEC climate disclosure mandates or EU taxonomy alignment revisions could materially shift product reclassification risks and distribution channel restrictions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
Europe Asset Management Market
Asset Management
Asset Management System Market
Asset Management
LAMEA Equity Management Software Market
Asset Management
Healthcare Asset Management Market
Asset Management
Pension Fund Management Software Market
Asset Management
APAC Mutual Fund Market
Asset Management
Canada Asset Management Market
Asset Management
Fund Management Software Market
Asset Management
India AMC Industry Market
Asset Management
Global Infrastructure Asset Management Market
Asset Management
US Healthcare Assets Management Market
Asset Management
Capital Expenditure Market
Asset Management
Asset Optimization Solutions Market
Asset Management
Equity Management Tool Market
Asset Management
US Pension Funds Market
Asset Management
Assets Under Management Market