
 Global Vehicle Insurance Market | 2026-2036
Global Vehicle Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vehicle Insurance Market Outlook
Direct-to-consumer digital channels is reconfiguring how vehicle insurance reaches policyholders, bypassing traditional agent networks and compressing acquisition costs. Allianz SE leverages its proprietary digital platform to sustain pan-European reach without proportional branch expansion. State Farm Mutual Automobile Insurance Company anchors its position through captive agency networks that dominate the US personal auto segment. Progressive Corporation differentiates via telematics-driven pricing algorithms that compete on precision rather than brand alone.
Vehicle insurance constitutes a risk-transfer contract indemnifying policyholders against physical damage, theft, or third-party liability arising from automobile operation, priced through actuarial models incorporating driver history, vehicle safety ratings, and geographic loss frequency. The contract's primary commercial purpose lies in restoring capital position after stochastic loss events while satisfying mandatory financial responsibility laws. Comprehensive coverage dominates premium pools in mature markets where asset protection motives outweigh minimum legal compliance, while third-party liability retains volume leadership across emerging economies with lower vehicle values but strict regulatory mandates. Fleet operators represent the fastest-growing customer type as logistics centralization and ride-sharing platform expansion concentrate risk into commercial portfolios requiring tailored underwriting expertise.
US state insurance commissioners enforce solvency standards and rate approval processes that shape product availability and pricing flexibility across jurisdictions. EMA and national regulators across Europe impose conduct rules and capital requirements through Solvency II and emerging mobility-specific frameworks. China's NMPA and banking and insurance regulatory commission enforce data localization and consumer protection standards that constrain foreign carrier market access. Stakeholders must monitor how autonomous vehicle liability frameworks evolve from driver-centric to product-centric risk allocation, as this shift will redefine coverage architecture, pricing models, and competitive positioning without reference to any specific implementation timeline.
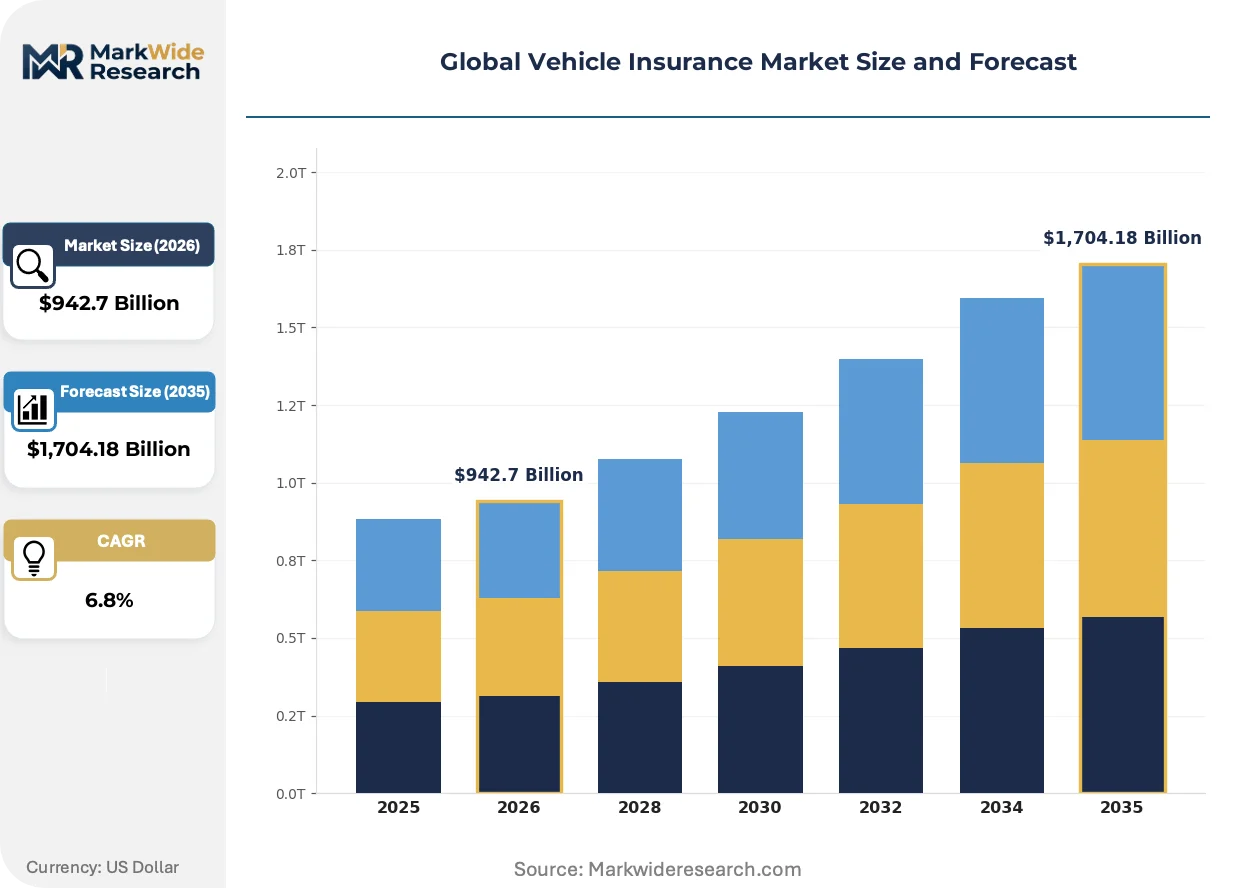
Market Dynamics
Telematics integration is compressing traditional actuarial cycles as real-time driving data supplants historical claims records for risk segmentation and dynamic pricing recalibration across personal and commercial auto portfolios.
Growth Catalysts
- Usage-Based Insurance Mandates:Several US states have enacted regulatory frameworks requiring insurers to offer mileage-verified policies, accelerating telematics adoption among price-sensitive consumer segments.
- Ride-Sharing Fleet Expansion:Platform operators in China and India are procuring commercial auto coverage at scale, creating dedicated underwriting verticals for gig-economy vehicle pools.
- Connected Vehicle Data Streams:OEM-embedded telemetry is digitizing loss prevention through predictive maintenance alerts and crash detection protocols that reduce claim severity.
Market Restraints
- Silicon Supply Concentration:Telematics hardware dependency on Taiwanese semiconductor foundries exposes insurers to device procurement delays and cost volatility.
- Data Localization Requirements:China's NMPA and banking regulatory commission mandate domestic server storage for telematics data, constraining cross-border underwriting analytics.
- Legacy System Integration Friction:Mainframe-based policy administration platforms at established carriers resist real-time API connectivity with IoT data feeds.
Strategic Opportunities
- Autonomous Vehicle Liability Gaps:Product-centric risk frameworks are displacing driver-centric coverage architectures, opening specialized cyber-physical policy design.
- Embedded Insurance Distribution:Automotive OEMs and digital retail platforms are becoming policy origination channels, bypassing traditional agent networks.
- Parametric Weather Coverage:Satellite-triggered flood and hail policies address protection gaps in climate-exposed regions where traditional indemnity models underperform.
Industry Challenges
- Actuarial Talent Scarcity:Shortage of data scientists capable of building machine-learning pricing models that satisfy state regulatory filing requirements.
- Cross-Border Data Governance:Conflicting GDPR, state privacy laws, and China's data security frameworks complicate multinational telematics program deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vehicle Insurance Market |
| Market Size in 2026 | $942.7 Billion |
| Market Size in 2035 | $1,704.18 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Comprehensive, Third-Party Liability, Collision, Personal Injury Protection Policy Feature: No-Claim Bonus, Add-on Covers, Roadside Assistance, Flexible Premiums Customer Type: Individual Owners, Fleet Operators, Commercial Users, Ride-Sharing Services Coverage Area: Urban, Rural, Global, Local |
| Companies Covered | Allianz SE, State Farm Mutual Automobile Insurance Company, Progressive Corporation, AXA Group, Zurich Insurance Group Ltd, Assicurazioni Generali S.p.A., Ping An Insurance, American International Group Inc., Berkshire Hathaway Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vehicle Insurance Market Strategic Shifts
Real-time data infrastructure is collapsing the latency between risk exposure measurement and premium adjustment, enabling dynamic contract structures that were technically infeasible under batch-processed legacy systems.
Artificial intelligence is digitizing claims adjudication through computer vision damage assessment and natural language processing of repair estimates. Mid-market carriers in Germany and the United Kingdom are deploying these tools to compress loss-adjustment expense ratios. The technology is digitizing back-office functions that previously required field adjuster deployment.
The EU AI Act imposes algorithmic transparency requirements on automated underwriting decisions affecting consumer access to coverage. Insurers must document training data provenance and enable human review of declined applications. Personal auto lines in France and Italy face the steepest compliance adaptation as national regulators align supervisory frameworks with the Brussels mandate.
Fleet managers are consolidating procurement through insurance-as-a-service platforms that bundle telematics hardware, risk analytics, and coverage into per-mile subscriptions. Third-party administrators are displacing traditional broker relationships for logistics operators with over five hundred vehicles. This concentration is most visible in the United States and Brazil where transportation asset financing ties coverage to equipment leases.
Global Vehicle Insurance Market Segmentation
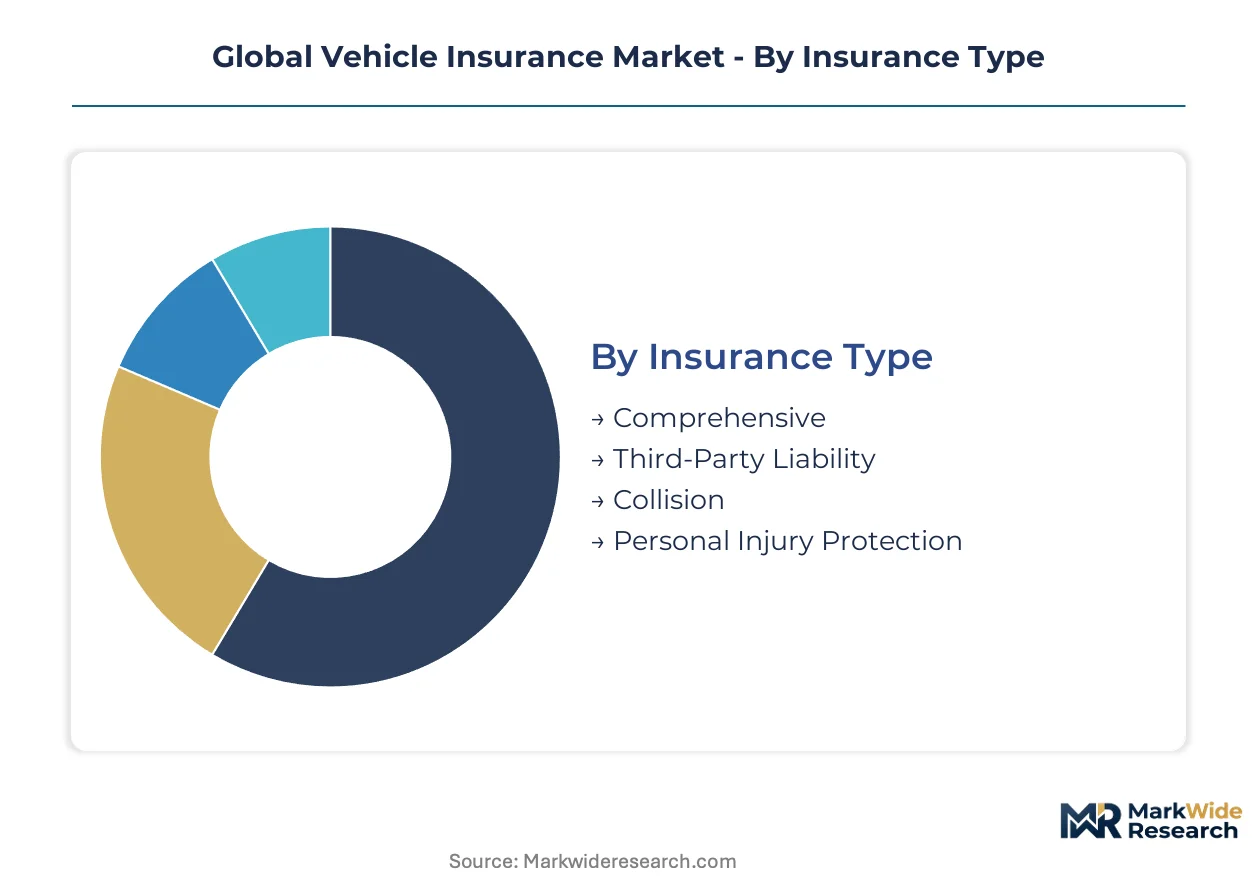
Vehicle insurance segmentation reflects divergent risk profiles and contract economics across coverage types, customer structures, and geographic deployment patterns. Understanding these partitions reveals where pricing power concentrates and which segments drive underwriting innovation.
Insurance Type:
Comprehensive coverage renews on annual cycles with stable retention, while collision and personal injury protection exhibit faster policy turnover tied to vehicle replacement rates and driver demographic churn.
- Comprehensive:Bundles physical damage, theft, and third-party liability into single contracts with higher premium density. Demand clusters in Germany, the United Kingdom, and Japan where asset protection motives dominate purchasing decisions and lenders mandate full coverage for financed vehicles.
- Third-Party Liability:Covers legal obligations to third parties for bodily injury and property damage without insuring the policyholder's own vehicle. Volume leadership persists across India, Brazil, and South Africa where regulatory mandates enforce minimum coverage thresholds and vehicle values remain below comprehensive attachment points.
- Collision:Indemnifies policyholders for damage from accidents regardless of fault. Fleet operators in the United States and Canada deploy this coverage alongside self-insured retention layers to manage predictable loss frequency.
- Personal Injury Protection:Covers medical expenses and lost wages for insured drivers and passengers regardless of fault. No-fault jurisdictions in Florida, Michigan, and New York sustain concentrated demand despite legislative pressure to reform unlimited benefit structures.
Third-party liability anchors the volume base while comprehensive coverage gains share at the steepest rate as emerging market vehicle values appreciate toward insurable thresholds.
Policy Feature:
Cost tier differentiation separates basic compliance-grade offerings from premium-priced service bundles, with roadside assistance and flexible premium structures commanding margin premiums over stripped-down no-claim bonus products.
- No-Claim Bonus:Discount mechanisms reward loss-free histories with graduated premium reductions. Insurers in France and Spain leverage these programs to lock in multi-year customer relationships and reduce acquisition spend.
- Add-on Covers:Optional extensions for engine protection, zero depreciation, and consumables reimbursement. Demand concentrates among first-time buyers in China and India purchasing extended warranties through OEM dealership channels.
- Roadside Assistance:Emergency service dispatch for breakdowns, flat tires, and lockouts. Commercial fleets in Australia and the United Kingdom bundle this feature into total cost of ownership contracts with third-party administrators.
- Flexible Premiums:Usage-based and pay-as-you-drive structures calibrated to actual mileage and driving behavior. Telematics-enabled deployment is expanding most quickly in Italy and the United States where regulatory frameworks accommodate real-time pricing adjustments.
No-claim bonus programs dominate policy attachment rates while flexible premium structures are climbing the fastest as connected vehicle data streams mature.
Customer Type:
Application context distinguishes personal mobility protection from commercial risk concentration, with fleet and platform economics demanding fundamentally different underwriting expertise and capital deployment.
- Individual Owners:Personal auto coverage for private passenger vehicles driven for commuting and leisure. Retention challenges intensify in competitive markets where digital aggregators compress switching costs.
- Fleet Operators:Commercial portfolios covering logistics, delivery, and service vehicle pools with centralized procurement and loss control programs. Risk engineering services from Zurich Insurance and Munich Re dominate this segment in Germany and Switzerland.
- Commercial Users:Small business auto coverage for contractors, tradespeople, and professional service providers mixing personal and business use. Agents in the United States maintain channel control through policy customization for local regulatory variations.
- Ride-Sharing Services:Platform-integrated coverage bridging personal and commercial use periods for gig-economy drivers. Didi in China and Ola in India negotiate master policies covering millions of vehicles under single underwriting arrangements.
Individual owners anchor premium volume while ride-sharing services are expanding most quickly as mobility platforms scale fleet coverage procurement.
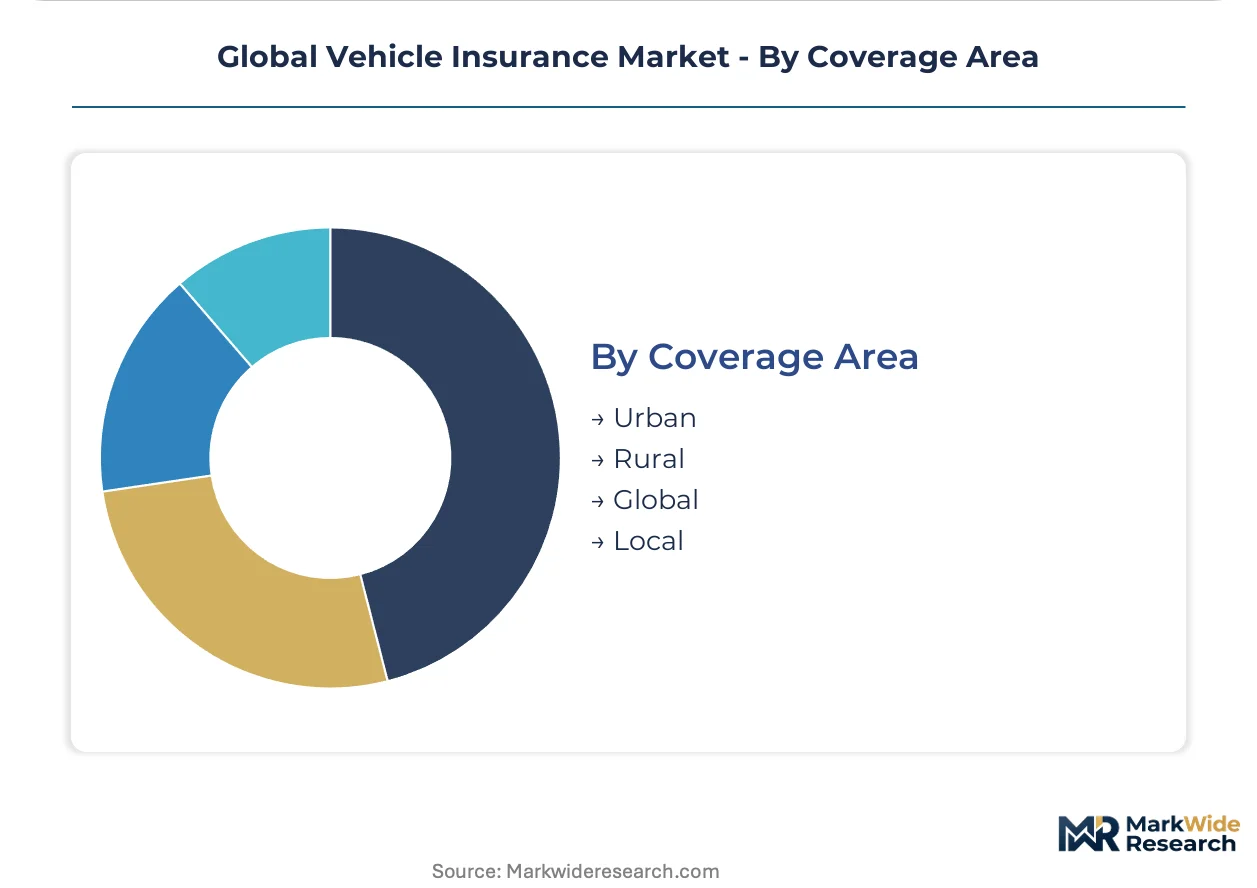
Coverage Area:
Geographic scope determines regulatory jurisdiction complexity and claims service infrastructure requirements, with local and urban concentrations enabling cost efficiency against the administrative burden of global portability.
- Urban:Metropolitan-focused coverage with higher frequency but lower severity loss profiles due to speed limits and traffic density. Telematics adoption rates exceed rural markets in London, Tokyo, and Singapore where congestion pricing and parking scarcity already condition driver behavior.
- Rural:Territory-rated policies for agricultural, remote, and low-population-density regions. Longer response times for emergency services elevate bodily injury severity in the United States Midwest and Australian outback.
- Global:Multi-territory coverage for internationally mobile policyholders and cross-border fleet operations. GDPR and China's data security law create compliance friction for telematics-enabled global programs.
- Local:Single-jurisdiction policies optimized for specific regulatory and claims environments. Domestic carriers in South Korea and Mexico retain pricing advantages through superior loss cost data and repair network relationships.
Urban coverage anchors premium density while global policies are gaining share at the steepest rate among multinational corporate fleet accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and Switzerland exceeds that in India and Brazil by substantial margins, reflecting divergent regulatory frameworks and loss cost environments. This asymmetry shapes carrier capital deployment and product architecture across markets.
United States
State-level rate approval processes and telematics adoption drive carrier differentiation. NHTSA and state insurance commissioners enforce solvency standards that constrain pricing flexibility. Texas and Florida concentrate commercial auto volume where fleet operators negotiate master policies through third-party administrators.
Germany
Comprehensive coverage mandates for financed vehicles sustain premium density above global averages. KBA and BaFin impose strict capital requirements through Solvency II implementation. Munich and Stuttgart anchor risk engineering expertise serving continental fleet portfolios.
China
Digital-first distribution platforms and ride-sharing fleet procurement expand commercial coverage demand. NMPA and banking regulatory commission enforce data localization for telematics analytics. Shenzhen and Shanghai concentrate Ping An Insurance's platform scale and domestic carrier technology investment.
United Kingdom
Price comparison website dominance compresses acquisition costs while fragmenting carrier loyalty. FCA conduct rules and GDPR compliance shape telematics program design. London concentrates specialty auto underwriting and Lloyd's syndicate participation in commercial motor risks.
India
Mandatory third-party liability enforcement and rising vehicle values expand addressable premium pools. IRDAI regulates tariff structures and solvency margins for domestic and foreign joint ventures. Mumbai and Bangalore concentrate broker networks and InsurTech platform development for two-wheeler and commercial auto lines.
Global Vehicle Insurance Market Competitive Environment
Diversified financial conglomerates and specialized auto carriers split the market across personal and commercial lines. Consolidation pressure intensifies as telematics-enabled pricing advantages concentrate share among data-rich incumbents. Three archetypes dominate: captive agency networks with exclusive distribution, direct-to-consumer digital platforms, and risk-engineering-focused commercial specialists. Competitive moves center on embedded insurance partnerships with automotive OEMs and vertical integration into telematics hardware supply chains.
Within the diversified multinational tier, Allianz SE and AXA Group represent pan-European scale with proprietary digital distribution capabilities. State Farm Mutual Automobile Insurance Company anchors the captive agency archetype in North American personal auto. Progressive Corporation exemplifies telematics-driven pricing precision competing on data advantage rather than brand equity alone.
| Leading Market Players |
|---|
| Allianz SE |
| State Farm Mutual Automobile Insurance Company |
| Progressive Corporation |
| AXA Group |
| Zurich Insurance Group Ltd |
| Assicurazioni Generali S.p.A. |
| Ping An Insurance |
| American International Group Inc. |
| Berkshire Hathaway Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Taiwanese semiconductor foundries is compressing telematics hardware availability and forcing insurers toward longer contract terms with embedded device suppliers. This utilization squeeze transmits directly into pricing posture, as carriers absorb component volatility through premium adjustments rather than coverage restrictions.
Pricing Analysis
The customization-premium spread between configured-to-order fleet policies and standard personal auto coverage spans substantial margin bands. Three-tier pricing structure across premium, standard, and economy levels dominates personal lines, with telematics-enabled flexible premiums commanding service premiums over stripped-down third-party liability. Cost compression in the standard tier is intensifying because digital aggregators compress acquisition economics and retention rates. Fleet operators exhibit lowest price sensitivity due to bundled risk engineering services, while individual policyholders in emerging markets demonstrate highest elasticity.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor manufacturing equipment constrain Taiwanese and South Korean foundry capacity expansion for telematics chipsets. Hardware supply concentrates in Taiwan, South Korea, and China, with silicon wafers, GPS modules, and cellular modems anchoring bill-of-materials exposure. Single-source vulnerability runs through TSMC's automotive-grade chip allocation priorities. Distribution runs through OEM-embedded channels and aftermarket device installers serving insurer direct procurement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vehicle insurance sits in early-cycle expansion as telematics penetration in commercial auto remains below saturation thresholds across major markets. Connected vehicle data streams and usage-based policy structures are accelerating adoption curves faster than legacy pricing models anticipated.
For Market Incumbents: Entrench data advantages through captive telematics hardware supply and exclusive OEM data partnerships. Insurers must consolidate risk engineering capabilities against emerging InsurTech pricing algorithms. State-level rate approval friction favors incumbents with established regulatory filing infrastructure.
For New Entrants and Emerging Players: Pursue embedded insurance distribution through ride-sharing platform APIs and automotive retail finance channels. The ride-sharing services segment offers lowest competitive density relative to policy volume concentration. White-label telematics infrastructure from third-party administrators enables rapid deployment without capital-intensive hardware development.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across telematics-enabled underwriting platforms as data infrastructure and regulatory compliance costs compound. Long-term viability favors carriers with scaled proprietary data streams rather than licensed third-party telemetry. The signal to watch is regulatory adoption of real-time pricing frameworks in additional US states and European jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time driving data from OEM-embedded systems enables dynamic premium recalibration for Progressive and Allianz. |
| Embedded Insurance Partnership | Automotive retail finance channels at Ping An and AXA bypass traditional agent acquisition costs. |
| Ride-Sharing Fleet Master Policy | Platform-integrated coverage at Didi and Ola concentrates millions of vehicles under single underwriting arrangements. |
| Parametric Weather Coverage Launch | Satellite-triggered hail and flood policies address protection gaps in climate-exposed US Midwest and Australian regions. |
| Autonomous Vehicle Liability Framework | Product-centric risk allocation opens specialized cyber-physical policy design ahead of regulatory standardization. |
Study Parameters
A spread of perspectives from underwriting executives, telematics platform engineers, regulatory affairs leads at state insurance commissions, and fleet procurement managers converged on the working assumptions. Primary interviews combined with secondary validation from NHTSA guidance documents, state rate filing databases, EU Solvency II regulatory texts, and connected vehicle deployment disclosures. Bottom-up policy volume estimates and top-down premium pool assessments were triangulated against carrier financial filings.
Demand-supply balance across personal auto, commercial fleet, and ride-sharing coverage segments anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include insurance type, policy feature tier, customer application context, and geographic coverage scope. CAGRs derived from loss cost trend analysis, telematics adoption curve projections, and regulatory framework evolution assumptions. Forecast inputs incorporated vehicle registration forecasts and platform fleet expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments and claims inflation trajectories would shift the trajectory. Forecasts reflect documented assumptions on telematics penetration rates and autonomous vehicle liability framework timing. Material shifts in semiconductor supply availability or data localization regulatory enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Family Floater Health Insurance Market
Insurance
Road Assistance Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
Cancer Insurance Market
Insurance
US Extended Warranty Market
Insurance
Germany Health and Medical Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Europe Road Assistance Insurance Market
Insurance
Workers Compensation Insurance Market
Insurance
Europe Parametric Insurance Market
Insurance
Middle East and Africa Travel Insurance Market
Insurance
Asia-Pacific Insurance Aggregators Market
Insurance
Saudi Arabia Property and Casualty Insurance Market
Insurance
Parametric Insurance Market
Insurance
Saudi Arabia Health & Medical Insurance Market