
 Jams, Jellies & Preserves Market | 2026-2036
Jams, Jellies & Preserves Market Size, Share, and Industry Trends Forecast 2026-2036
Jams, Jellies & Preserves Market Insights
High-fructose corn syrup is decoupling from premium jam formulations as brands reformulate with cane sugar and fruit concentrates to meet clean-label expectations. The J.M. Smucker Company leverages its extensive retail distribution network to sustain shelf dominance across North American grocery channels. Hero Group anchors its competitive position through specialized organic and reduced-sugar portfolios that command premium positioning in European markets. Andros Group extends its manufacturing scale across private-label and branded segments, competing aggressively on cost-adjusted volume.
Jams, jellies, and preserves are semisolid food products manufactured by cooking fruit pulp, juice, or concentrate with sugar and gelling agents—typically pectin at concentrations of 0.5–1.5% by weight—to achieve a gelled consistency with soluble solids exceeding 65%. These products serve commercial purposes ranging from household table spreads to industrial bakery fillings and food service portion-control applications. Fruit jams occupy the largest volume share within the product type dimension, though vegetable preserves represent the fastest-growing margin pool as savory applications expand. Glass jars dominate packaging type due to consumer perception of quality and shelf stability, while pouches are gaining traction in food service channels where dispensing efficiency reduces waste.
FDA standards of identity under 21 CFR 150 govern fruit content minimums and permissible additives in US interstate commerce, while EFSA guidance on added sugars influences reformulation targets for European exporters. The EU Green Deal and national sugar reduction frameworks in France and Germany are forcing manufacturers to recalibrate ingredient sourcing and label claims. Stakeholders must monitor evolving pectin supply contracts and organic certification backlogs as these constraints tighten input availability and compliance timelines.
Market Dynamics
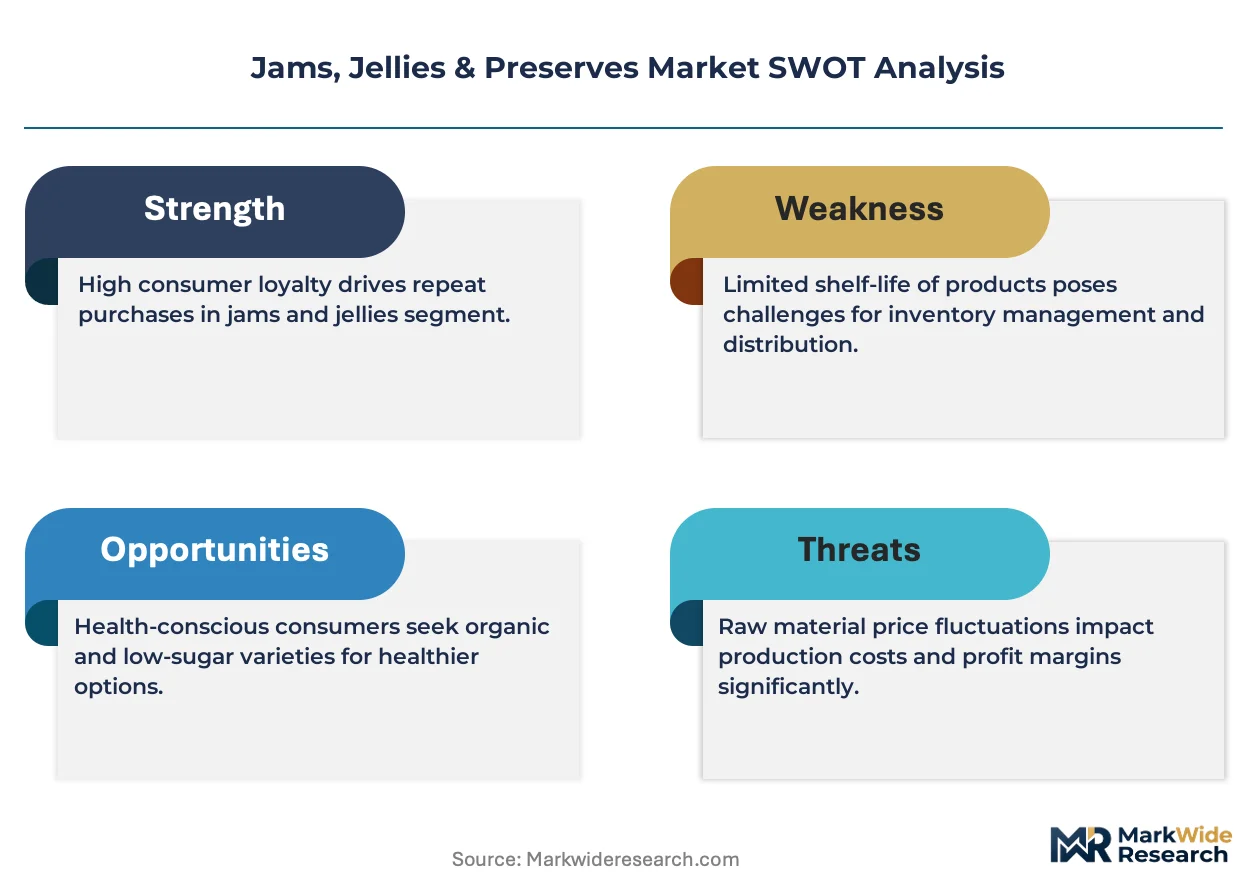
The Jams, Jellies & Preserves Market is experiencing structural pressure from sugar reduction mandates under EU Green Deal frameworks and FDA guidance, forcing simultaneous reformulation of legacy recipes and requalification of pectin supply contracts across manufacturing networks.
Growth Catalysts
- Clean-label pectin sourcing:Citrus peel and apple pomace extraction methods are displacing synthetic gelling agents as EFSA guidance tightens additive approvals. German retailers now mandate natural pectin declarations for shelf placement.
- Food service portion innovation:Single-serve squeeze pouches are capturing institutional bakery and hotel breakfast contracts. This format reduces waste and labor costs for operators managing high-volume spreads.
- France's national sugar reduction framework:The policy creates compliance-driven demand for fruit concentrate sweeteners and monk fruit blends. Manufacturers achieving reformulation targets secure preferential retail positioning.
Market Restraints
- Organic certification backlogs:EU 2018/848 regulation implementation has created approval queues exceeding months for fruit suppliers. This delays product launches and ties up working capital.
- Pectin supply concentration:Citrus peel pectin production clusters in southern Spain and Italy, exposing buyers to climate-driven harvest volatility and price spikes.
- High-fructose corn syrup substitution ceiling:Technical limitations prevent complete replacement in low-cost private-label formulations without texture degradation or accelerated syneresis.
Strategic Opportunities
- Savory vegetable preserves:Carrot, beet, and pepper jams are penetrating charcuterie boards and gastropub menus. This application commands margin premiums over traditional fruit spreads.
- Direct-to-foodservice digital platforms:Specialty distributors are bypassing traditional grocery wholesale to capture artisanal producer volumes. This channel reduces slotting fee burdens and improves producer margins.
- Germany's organic conversion subsidies:Federal programs under the EU Common Agricultural Policy are accelerating hectare expansion for organic berry cultivation. Processors securing forward contracts gain input cost stability.
Industry Challenges
- Reformulation R&D talent scarcity:Food scientists capable of balancing sugar reduction targets with gel strength and shelf stability requirements command premium compensation. Smaller manufacturers struggle to retain this expertise.
- Dual-label compliance complexity:Simultaneous FDA and EFSA qualification for export products demands parallel testing protocols. This extends product development timelines and increases regulatory affairs overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jams, Jellies & Preserves Market |
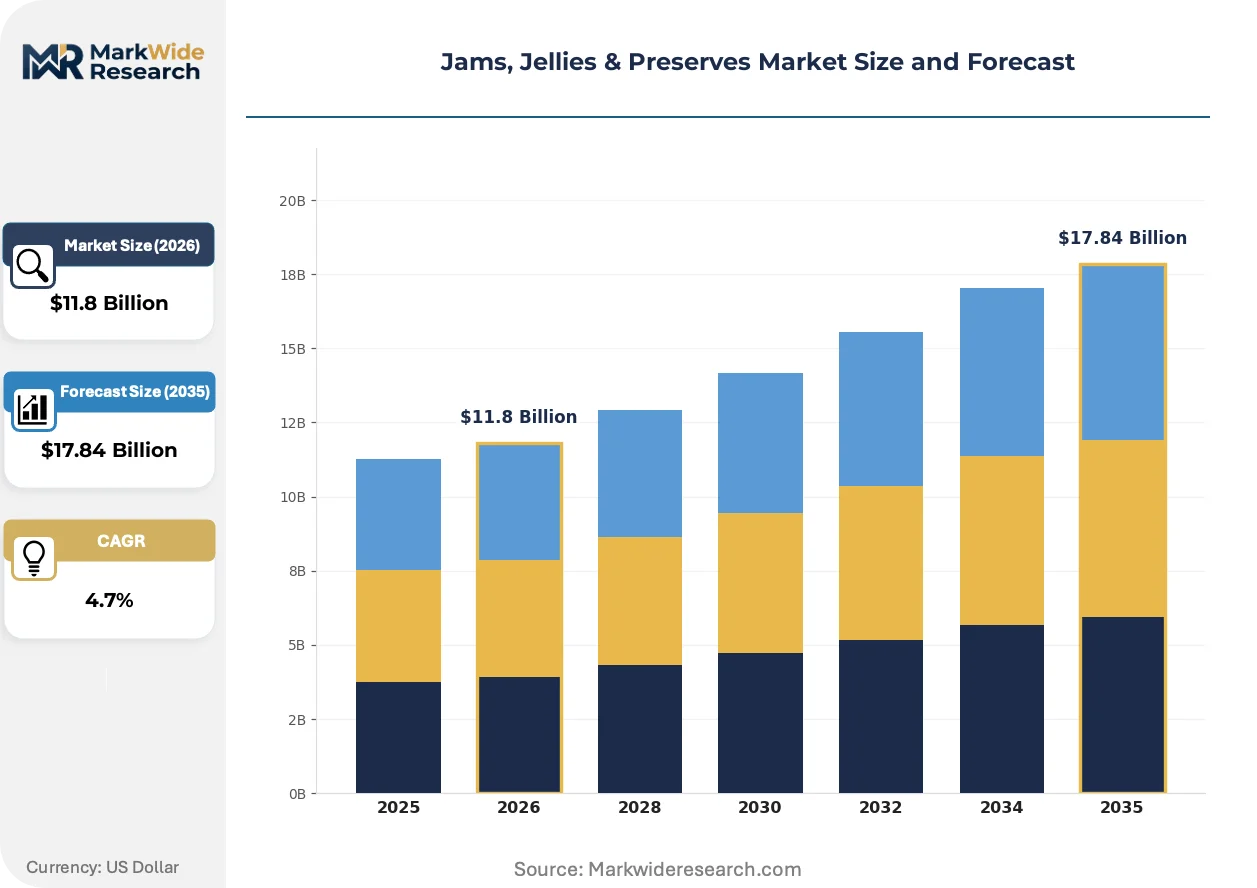
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.84 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Jams, Fruit Jellies, Vegetable Preserves, Citrus Marmalade Ingredient Type: Natural Sweeteners, Artificial Sweeteners, Organic Fruits, Preservatives Packaging Type: Glass Jars, Plastic Containers, Pouches, Tetra Packs End User: Households, Food Service Industry, Retailers, Food Manufacturers |
| Companies Covered | Conagra Brands, F. Duerr & Sons, The J.M. Smucker Company, Hero Group, Unilever, The Kraft Heinz Company, Andros Group, Welch Foods, B&G Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jams, Jellies & Preserves Market Trends and Innovations
Reformulation chemistry and packaging engineering are converging to address simultaneous demands for reduced sugar content, extended ambient stability, and dispensing convenience across retail and food service channels.
High-pressure processing technology is unifying pasteurization and texture preservation in reduced-sugar formulations. Mid-sized manufacturers in France and Germany are adopting HPP lines to achieve clean-label positioning without thermal degradation of fruit integrity. This technology is compressing the traditional trade-off between shelf stability and ingredient simplicity that has constrained premium product development.
EFSA's evolving guidance on added sugars and health claims is recalibrulating European formulation roadmaps. Manufacturers must now substantiate "no added sugar" declarations through analytical documentation of naturally occurring versus introduced fructose. Export-oriented producers targeting both EU and US markets are maintaining dual specification sheets to satisfy divergent FDA and EFSA threshold definitions.
Food service buyers are consolidating procurement around portion-controlled formats that reduce labor and waste. Pouch dispensers and single-serve cups are displacing traditional jar service in hotel breakfast operations and institutional catering across Germany and France. This shift is most visible in contract catering chains where operational efficiency metrics dominate supplier selection criteria.
Jams, Jellies & Preserves Market Segmentation
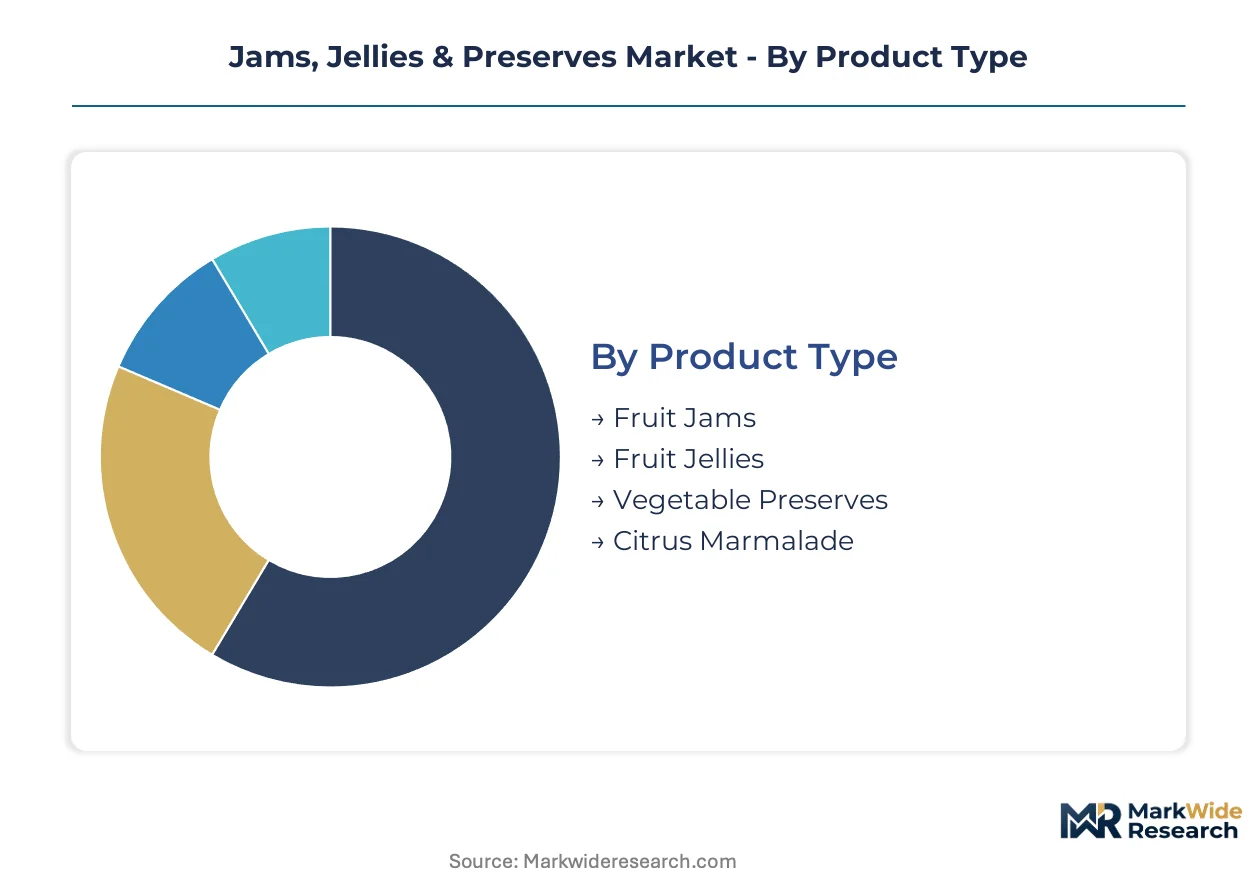
Segmentation in the Jams, Jellies & Preserves Market reveals how formulation choices, packaging formats, and channel strategies create distinct margin profiles. Manufacturers align R&D investment and supply contracts with the specific technical and regulatory requirements of each segment cluster.
Product Type:
Volume concentration sits with traditional fruit spreads, while premium positioning shifts toward experimental savory variants and heritage citrus formulations.
- Fruit Jams:These products combine fruit pulp or puree with sugar and pectin at soluble solids exceeding 65%, achieving gelled consistency through controlled cooking. Demand concentrates in German retail channels where organic and reduced-sugar SKUs command preferential shelf placement under EFSA-influenced retailer guidelines. Clean-label reformulation pressures are forcing manufacturers to recalibrate pectin sourcing and sweetener blends.
- Vegetable Preserves:Carrot, beet, and pepper-based spreads incorporate savory flavor profiles through spice integration and reduced sugar content. Gastropub menus and charcuterie board applications in France are driving procurement, with operators paying margin premiums over conventional fruit spreads for differentiation. Supply constraints from organic certification backlogs under EU 2018/848 delay new product launches.
- Fruit Jellies:Clarified fruit juice formulations deliver transparent, firm gels through precise pectin-acid balance. Bakery filling applications dominate procurement volumes.
- Citrus Marmalade:Bitter orange and Seville varieties utilize peel suspension for texture contrast. Heritage positioning supports premium pricing in UK and Irish markets.
Today's leader: Fruit Jams. Tomorrow's challenger: Vegetable Preserves.
Ingredient Type:
Clean-label mandates are restructuring procurement priorities, with natural and organic inputs displacing synthetic alternatives despite cost premiums and supply volatility.
- Natural Sweeteners:Cane sugar, fruit concentrates, and monk fruit extracts replace high-fructose corn syrup in premium formulations. France's national sugar reduction framework creates compliance-driven demand, with manufacturers achieving reformulation targets securing favorable retail positioning.
- Organic Fruits:Berries and stone fruits cultivated under EU 2018/848 standards command price premiums but face certification backlogs exceeding months. Germany's federal conversion subsidies under the EU Common Agricultural Policy are accelerating hectare expansion for organic berry cultivation.
- Artificial Sweeteners:Aspartame and sucralose formulations maintain presence in diabetic and reduced-calorie private-label lines despite clean-label headwinds.
- Preservatives:Potassium sorbate and sodium benzoate face tightening EFSA scrutiny, with natural alternatives gaining trial in ambient-stable formulations.
Procurement gravity centers on Natural Sweeteners. Certification bottlenecks constrain Organic Fruits expansion.
Packaging Type:
Format selection trades perceived quality against operational efficiency, with glass retaining retail dominance while flexible formats capture food service growth.
- Glass Jars:Amber and clear glass containers deliver shelf stability and premium perception through inert material properties. German and French retailers mandate this format for artisanal and organic SKU placement.
- Pouches:Flexible dispensing formats reduce waste and labor costs in hotel breakfast operations and institutional catering across Germany. Single-serve configurations capture contract catering procurement.
- Plastic Containers:Polypropylene jars offer shatter resistance and weight reduction for retail and food service distribution.
- Tetra Packs:Aseptic carton formats enable ambient distribution with reduced logistics cost, penetrating private-label retail in price-sensitive segments.
Glass Jars anchor retail premium positioning. Pouches are climbing the fastest in food service channels.
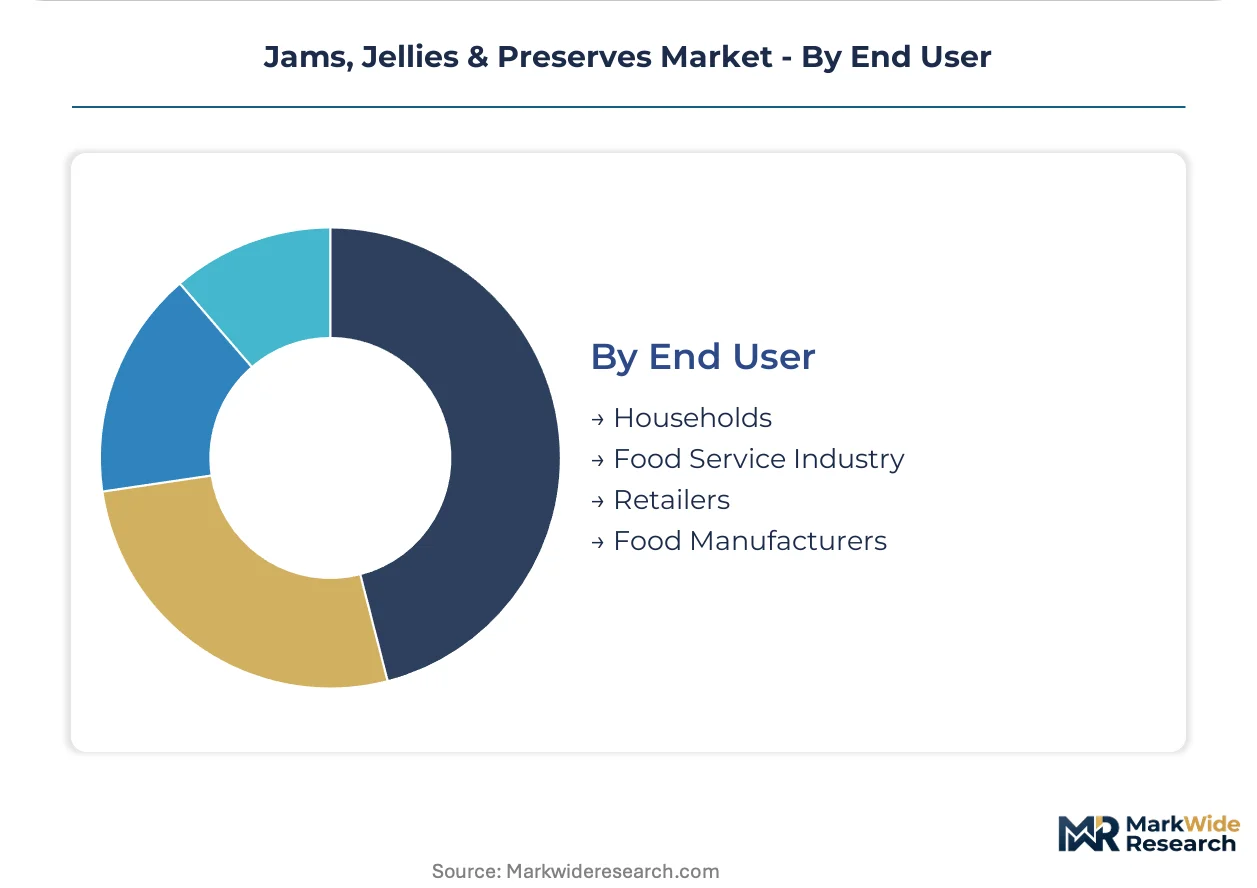
End User:
Channel requirements diverge sharply on portion control, label claims, and procurement scale, forcing manufacturers to maintain parallel product specifications.
- Households:Consumer purchasing prioritizes label transparency and heritage branding, with German shoppers demonstrating strongest willingness to pay for organic certification.
- Food Service Industry:Hotel chains and contract caterers consolidate procurement around portion-controlled formats that reduce labor and waste. Operational efficiency metrics dominate supplier selection in France and Germany.
- Retailers:Supermarket private-label programs demand cost-adjusted volume with clean-label positioning, squeezing mid-tier branded manufacturers.
- Food Manufacturers:Industrial bakery and confectionery buyers specify functional properties—gel strength, water activity, particle size—for automated processing integration.
Food Service Industry procurement is expanding most quickly. Households remain the value anchor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhineland-Palatinate and Baden-Württemberg regions anchor European fruit preserve production, hosting concentrated organic processing capacity that supplies retail chains across the continent. Clean-label reformulation mandates and sugar reduction frameworks are reshaping manufacturing footprints in established markets while emerging economies build import-dependent distribution networks.
Germany
Organic berry cultivation in Lower Saxony and Bavaria supplies artisanal processors serving Edeka and Rewe supermarket chains. The EU Common Agricultural Policy conversion subsidies accelerate hectare expansion for certified organic fruit. Stuttgart-based cooperatives dominate pectin extraction from regional apple pomace, securing natural gelling agent supply for premium formulations.
France
Provence-Alpes-Côte d'Azur stone fruit orchards and Île-de-France food tech clusters drive savory vegetable preserve innovation for gastropub procurement. The national sugar reduction framework mandates reformulation targets that manufacturers must achieve for favorable retail placement. Lyon contract caterers consolidate procurement around portion-controlled pouch formats for operational efficiency.
United States
California Central Valley fruit processors and Pacific Northwest berry cooperatives supply raw material for national brand manufacturing. FDA standards of identity under 21 CFR 150 govern interstate commerce specifications for fruit content minimums. Chicago and Minneapolis metropolitan areas concentrate private-label production capacity serving Walmart and Kroger distribution networks.
United Kingdom
Kent and East Anglia heritage citrus marmalade production maintains premium positioning in Waitrose and Marks & Spencer premium tiers. Post-Brexit UKCA marking requirements run parallel to retained EU food safety regulations for export-oriented manufacturers. Scottish raspberry preserves from Perthshire command protected geographical indication status in specialty retail channels.
Italy
Emilia-Romagna and Piedmont fruit processing corridors supply apricot and cherry preserves for European bakery filling applications. EFSA guidance on added sugars influences reformulation roadmaps for export products targeting German and French retail. Bologna-based food service distributors specialize in single-serve portion formats for hotel breakfast operations.
Jams, Jellies & Preserves Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers recalibrate toward clean-label positioning and reduced-sugar formulations. The vendor base clusters around three strategic tiers: multinational conglomerates with integrated fruit supply chains, mid-sized European specialists commanding organic premium positioning, and private-label fabricators competing on cost-adjusted volume. Strategic archetypes include heritage brand custodians leveraging century-old recipes, reformulation technology licensors, and direct-to-foodservice platform operators. M&A activity and pectin supply contract requalification represent the dominant competitive moves reshaping market structure.
Within the multinational conglomerate tier, The J.M. Smucker Company and The Kraft Heinz Company occupy positions defined by retail shelf dominance and national distribution infrastructure. Hero Group and Andros Group exemplify the European specialist archetype, anchoring competitive positioning through organic certification and regional fruit sourcing relationships. These named entities represent the structural poles around which mid-tier manufacturers and private-label competitors organize their market entry and differentiation strategies.
| Leading Market Players |
|---|
| Conagra Brands |
| F. Duerr & Sons |
| The J.M. Smucker Company |
| Hero Group |
| Unilever |
| The Kraft Heinz Company |
| Andros Group |
| Welch Foods |
| B&G Foods |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap processors in France and Germany anchor pricing discipline through generational control of regional fruit supply contracts, enabling selective pass-through of pectin and organic certification cost swings while resisting margin compression from private-label fabricators.
Pricing Analysis
Input-cost pass-through from citrus peel pectin and organic berry supply governs manufacturer pricing power across the analysis window. Three-tier pricing structure across premium organic, standard clean-label, and economy private-label levels stratifies by certification grade and volume scale. Pricing pressure stems from EU Green Deal sugar reduction mandates forcing reformulation investment without proportional retail price recovery. Private-label retail buyers exhibit highest price sensitivity, while German food service operators accept premiums for portion-controlled pouch formats that reduce labor costs.
Supply Chain Analysis
Pectin supply rests on citrus peel extraction concentrated in southern Spain and Italy, with apple pomace alternatives emerging from German and Polish processors. Raw material dependencies include Seville orange peel, organic strawberry and raspberry crops, and monk fruit extract for natural sweetening. Single-source vulnerability in Spanish citrus pectin exposes buyers to climate-driven harvest volatility and price spikes. Distribution runs through Stuttgart-based cooperatives and Lyon contract catering distributors to retail chains and institutional food service across Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as food service procurement shifts toward premium clean-label specifications that command sustainable margin premiums over commodity private-label alternatives.
For Market Incumbents: Anchor competitive position through backward integration into organic berry cultivation under Germany's EU Common Agricultural Policy conversion subsidies, securing input cost stability against certification backlog delays. Deepen channel control by bypassing traditional grocery wholesale through direct-to-foodservice digital platforms that reduce slotting fee burdens. Invest in high-pressure processing lines to achieve clean-label positioning without thermal degradation, defending against mid-tier reformulation technology licensors. For New Entrants and Emerging Players: France's national sugar reduction framework opens a window for specialty producers achieving reformulation targets with fruit concentrate sweeteners and monk fruit blends. Target savory vegetable preserves for gastropub and charcuterie board applications in France, where margin premiums exceed conventional fruit spreads. Pursue go-to-market partnerships with Bologna-based food service distributors specializing in single-serve portion formats for hotel breakfast operations. For Investors and Strategic Acquirers: Valuations sit cheapest among private-label fabricators lacking clean-label certification, while organic specialists with EU 2018/848 compliance command scarcity premiums. Long-term viability favors processors with captive pectin supply and forward contracts under Germany's organic conversion subsidies. Watch EFSA guidance evolution on added sugar thresholds as the inflection indicator for reformulation investment cycles and M&A timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | High-pressure processing adoption in France and Germany satisfies EFSA guidance without thermal degradation. |
| Backward Integration into Organic Cultivation | German processors securing hectare expansion under CAP subsidies gain input cost stability against certification delays. |
| Direct-to-Foodservice Channel Development | Specialty distributors bypassing grocery wholesale capture artisanal volumes with improved producer margins. |
| Pectin Supply Contract Requalification | Natural citrus peel and apple pomace sourcing displaces synthetic gelling agents under tightening EFSA additive approvals. |
| Premium Packaging Format Innovation | Single-serve squeeze pouches reduce waste and labor costs for German hotel chains and contract caterers. |
Research Methodology
Coverage spans Germany, France, the United States, the United Kingdom, and Italy, with primary inputs from each market combining executive interviews with fruit processors, category buyers at Edeka and Rewe, food service procurement directors, and regulatory affairs specialists with secondary validation. Secondary sources include FDA standards of identity filings, EFSA guidance documents, EU 2018/848 certification databases, and national sugar reduction framework policy texts. Bottom-up volume modeling and top-down value triangulation cross-validate segment outputs.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon. Segmentation dimensions modeled include product type, ingredient certification tier, packaging format, and end-user channel. CAGRs derive from trend extrapolation of pectin supply constraints, organic hectare expansion rates under CAP subsidies, and food service format adoption curves. Industry-specific inputs incorporate EFSA added sugar threshold guidance evolution and FDA 21 CFR 150 reformulation compliance timelines.
Revisions become necessary when EFSA additive approval restrictions tighten, organic certification backlogs extend beyond current queues, or climate events disrupt Spanish and Italian citrus peel harvests. Forecasts reflect assumptions about regulatory stability, input supply continuity, and food service procurement consolidation trajectories. A small set of named triggers—EFSA guidance updates, CAP subsidy renewal terms, and pectin supply contract renegotiation cycles—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Low Calorie Hummus Market
Specialty Foods
Maple Syrup Market
Specialty Foods
Global Guilt-Free Desserts Market
Specialty Foods
Grain Free Dog Food Market
Specialty Foods
Low Calorie Vegetable Dip Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Thai Cuisine Market
Specialty Foods
Aloe Butter Market
Specialty Foods
North America Hummus Market
Specialty Foods
Guacamole Market
Specialty Foods
Curculin Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Reishi Mushroom Market
Specialty Foods
Spirulina Chocolate Market
Specialty Foods
Healthy Low-Fat Desserts Market