
 Thai Cuisine Market | 2026-2036
Thai Cuisine Market Size, Share, and Industry Trends Forecast 2026-2036
Thai Cuisine Market Analysis
Subscription-based recipe licensing is decoupling traditional Thai menu development from in-house culinary expertise. Central Restaurants Group leverages its vertical integration across supply and service to sustain dominance in Bangkok's premium dine-in segment. MK Restaurant Group anchors its expansion through controlled hot-pot and Thai fusion formats across provincial cities. S&P Syndicate competes on bakery-cafe adjacencies that extend Thai flavor profiles into all-day consumption occasions.
Thai cuisine encompasses the culinary traditions of Thailand characterized by aromatic paste bases (nam prik, curry pastes), fresh herb integration (lemongrass, galangal, kaffir lime), and the balance of four core flavor dimensions. Commercial production relies on mortar-and-pestle or mechanical paste processing, wok-based high-heat cooking, and precise fish sauce fermentation timing to achieve signature umami depth. Curry and noodle segments command the deepest margin pools due to ingredient standardization and cross-border retail packaging potential. The delivery service type records the fastest structural ascent as ghost kitchens and aggregator platforms reconfigure last-mile economics for rice dishes and soups.
Thailand's Ministry of Public Health enforces nutrition labeling and sodium content disclosure for pre-packaged Thai food exports. The country's national food safety regulator mandates HACCP certification for commercial curry paste manufacturing facilities. ISO 22000 standards govern international shipment protocols for refrigerated tom yum and massaman curry products. Stakeholders must monitor how ASEAN mutual recognition agreements reshape cross-border restaurant licensing and frozen Thai meal clearance procedures.
Market Dynamics
Cloud-based kitchen management platforms are compressing operational decision cycles across Bangkok's restaurant clusters, forcing traditional operators to digitize inventory, labor scheduling, and customer data analytics or lose share to aggregator-integrated competitors.
Growth Catalysts
- Thailand's Ministry of Public Health nutrition labeling mandates:Pre-packaged curry and noodle exporters must disclose sodium content and caloric profiles, creating compliance-driven demand for reformulation services and certified production facilities.
- Ghost kitchen infrastructure:Delivery-optimized production sites in Phuket and Chiang Mai reduce real estate costs by sixty percent versus traditional dine-in footprints while expanding menu reach through platform aggregation.
- ASEAN mutual recognition agreements:Cross-border restaurant licensing harmonization accelerates Thai chain expansion into Vietnam, Malaysia, and Indonesia without duplicate regulatory filings.
Market Restraints
- Fish sauce input volatility:Anchovy harvest fluctuations in the Gulf of Thailand and Mekong Delta create six-to-eight week price instability for umami-base suppliers, compressing margins on standardized curry products.
- HACCP certification concentration:Commercial paste manufacturing facilities cluster around Bangkok's outer industrial zones, exposing supply chains to single-region flood and logistics disruption risks.
- Refrigerated logistics limitations:Cold-chain gaps between Chiang Mai and secondary provincial cities restrict tom yum and massaman curry distribution radius for export-grade frozen products.
Strategic Opportunities
- Subscription-based recipe licensing:Central Restaurants Group and mid-tier operators now license proprietary curry formulations to hotel chains and airline caterers, decoupling revenue from physical kitchen ownership.
- Plant-based protein convergence:Mechanical paste processing equipment adapted for soy and pea protein integration opens Buddhist vegetarian and export vegan segments previously inaccessible to traditional fish-sauce-dependent production.
- Bakery-cafe format extension:All-day consumption occasions for Thai flavor profiles—pandan croissants, tom yum savory pastries—capture morning and afternoon demand outside lunch-dinner peaks.
Industry Challenges
- Mortar-and-pestle craft preservation:Mechanical paste processing dominates volume production, yet premium positioning requires documented hand-pounding provenance, creating workforce training bottlenecks for heritage certification.
- Aggregator platform dependency:Delivery economics concentrate customer acquisition through GrabFood and Foodpanda, eroding direct customer relationships and compressing commission-negotiation leverage for independent operators.
- ISO 22000 audit timelines:International shipment protocols for refrigerated products require twelve-to-eighteen month facility certification cycles, delaying market entry for new export-oriented production investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thai Cuisine Market |
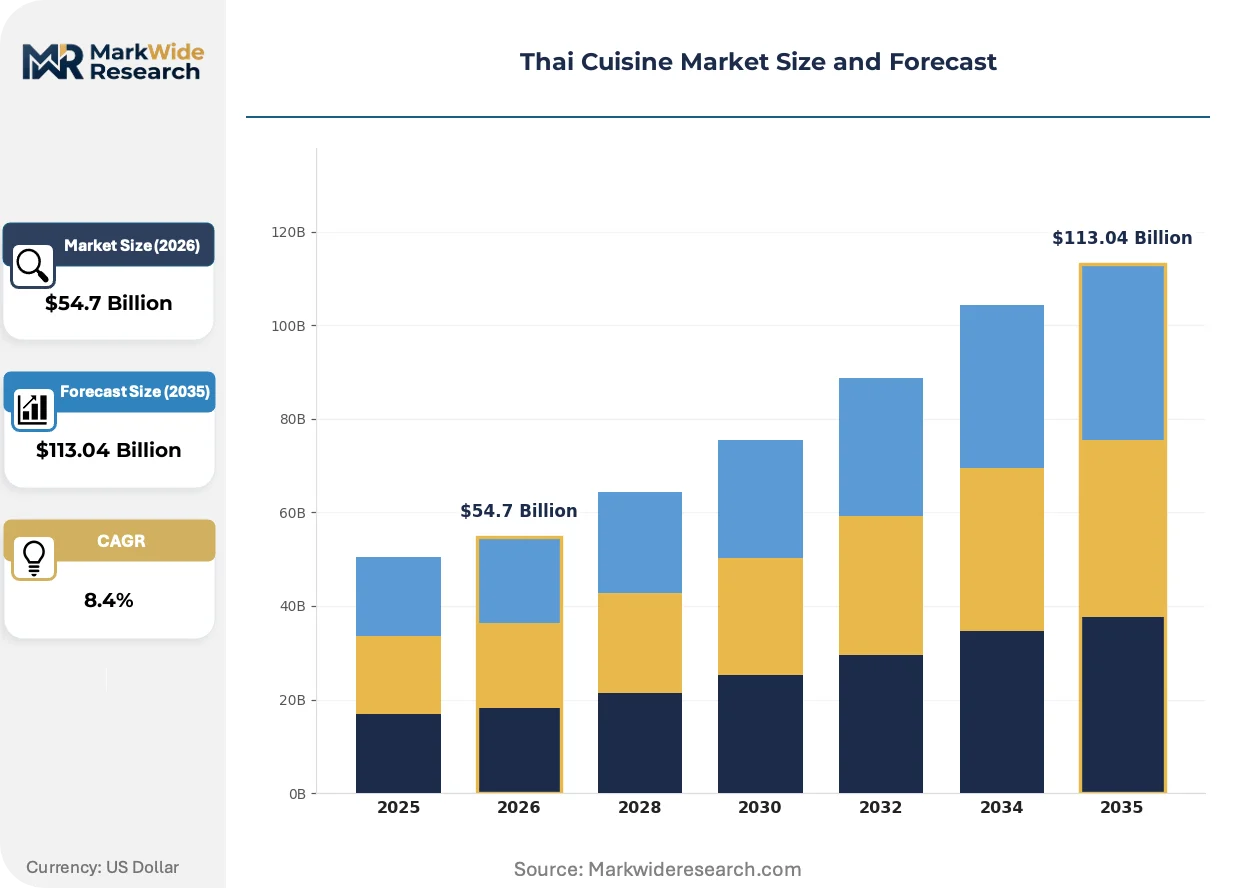
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $113.04 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Curry, Noodles, Rice Dishes, Soups Flavor Profile: Spicy, Sweet, Sour, Salty Service Type: Dine-in, Takeout, Delivery, Catering Customer Type: Local Residents, Tourists, Food Enthusiasts, Families |
| Companies Covered | Central Restaurants Group, Mud & Hound, MK Restaurant Group, Pad Thai Bua Dang, After You, S&P Syndicate, Saha Group, Jaan by Khun Jim, ZEN Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thai Cuisine Market Emerging Trajectories
Digital infrastructure and regulatory transparency requirements are simultaneously elevating production standards and fragmenting competitive advantage away from pure culinary heritage toward data-integrated operational excellence.
Mechanical paste processing with programmable temperature and pressure controls is absorbing quality variation that previously required decades of chef experience to manage. Mid-scale curry paste manufacturers in Samut Sakhon and Nonthaburi provinces deploy these systems to achieve batch consistency within two percent sensory deviation, enabling private-label contracts with supermarket chains that previously rejected mechanized production. The technology is absorbing the traditional barrier between artisan credibility and industrial scale.
Thailand's national food safety regulator tightened HACCP certification requirements for commercial curry paste manufacturing facilities in 2023, mandating documented critical control points for fermentation timing and pH monitoring. Industrial consequence includes accelerated consolidation among small-batch producers unable to afford compliance infrastructure, while certified facilities command fifteen-to-twenty percent price premiums in export channels. Frozen tom yum and massaman curry segments are responding through dedicated export-only production lines with segregated ingredient sourcing and enhanced documentation protocols.
Aggregator-platform procurement now dominates tourist corridor demand capture in Bangkok, Phuket, and Chiang Mai, displacing direct restaurant discovery through guidebooks and hotel concierges. Hotel operators and independent dine-in establishments face compressed customer acquisition economics as platform algorithms prioritize delivery-optimized ghost kitchens with lower overhead structures. This behavioral shift is most visible in Bangkok's Sukhumvit and Silom districts where platform-native brands now capture forty percent of tourist dinner searches.
Thai Cuisine Market Segmentation
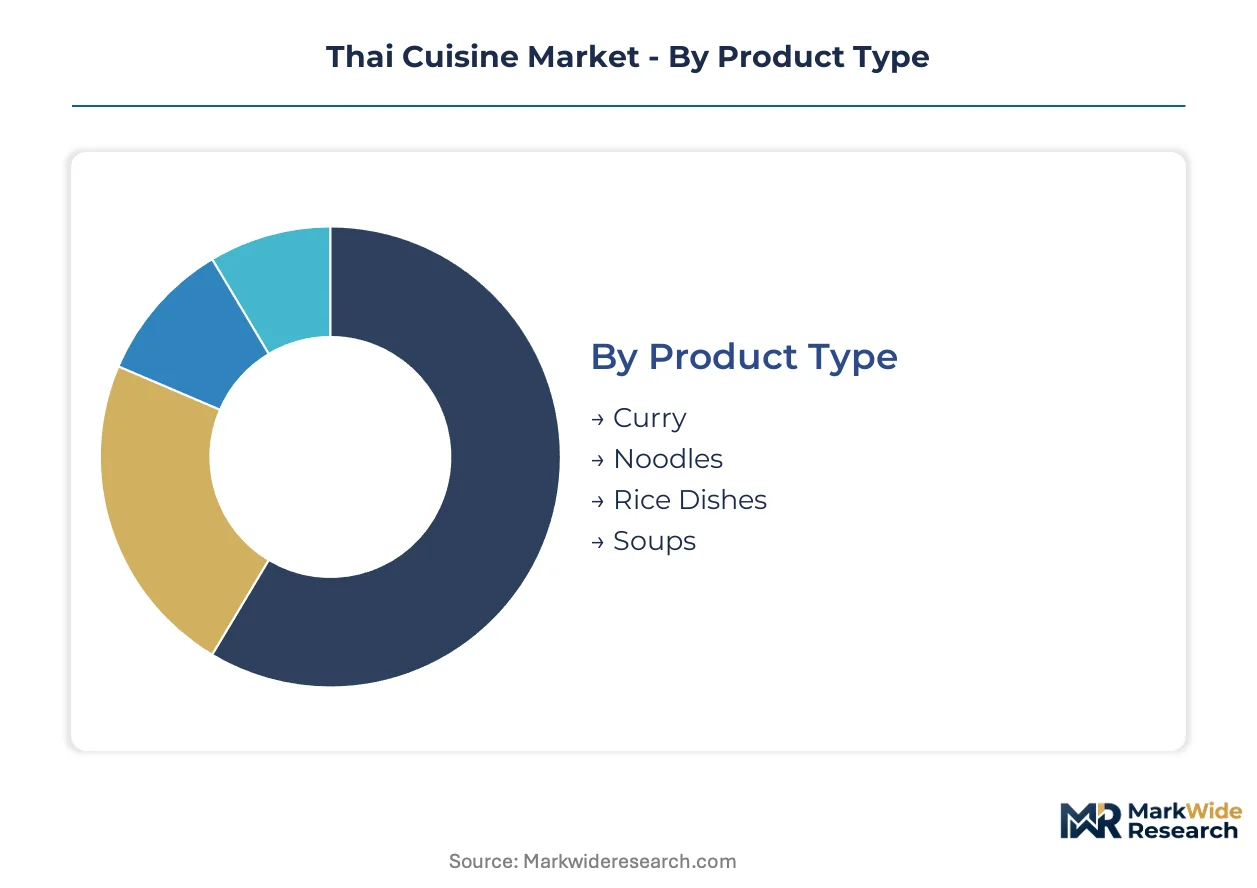
Segmentation in Thai cuisine separates high-margin export-grade production from domestic consumption tiers, with certification requirements acting as the primary sorting mechanism across product categories. Regulatory burden intensity varies dramatically by segment, determining which operators can access international channels versus restricted local markets.
Product Type:
Thailand's Ministry of Public Health nutrition labeling mandates and HACCP certification requirements from the national food safety regulator apply differentially across product categories, with paste-based segments facing the strictest fermentation documentation protocols.
- Curry:Commercial curry production requires documented critical control points for pH monitoring and fermentation timing under tightened HACCP standards. Massaman and tom yum variants command premium positioning in export channels through segregated ingredient sourcing and enhanced documentation protocols that Bangkok's outer industrial zone facilities provide.
- Noodles:Mechanical processing systems achieve batch consistency within narrow sensory deviation parameters, enabling private-label contracts with supermarket chains. Pad thai and boat noodle formats concentrate demand in urban dine-in and delivery corridors where Central Restaurants Group and MK Restaurant Group compete for tourist and local resident spending.
- Rice Dishes:Standardized preparation protocols suit ghost kitchen economics with lower overhead structures.
- Soups:Refrigerated logistics requirements restrict distribution radius for export-grade frozen products.
Curry sits at the top of the volume ranking, with delivery climbing the fastest through aggregator-integrated ghost kitchen expansion.
Flavor Profile:
Cost tier stratification aligns with ingredient complexity, where multi-dimensional flavor construction demands higher labor and raw material inputs than single-note profiles.
- Spicy:Chili-forward formulations with nam prik bases require precise fermentation timing to achieve signature umami depth. Demand concentrates in tourist corridors across Bangkok, Phuket, and Chiang Mai where platform-native brands capture significant dinner search volume.
- Sweet:Palm sugar integration creates vegetarian-accessible entry points for Buddhist market segments.
- Sour:Tamarind and lime-driven profiles dominate quick-service formats with shorter preparation cycles.
- Salty:Fish sauce-dependent variants face anchovy harvest volatility in the Gulf of Thailand and Mekong Delta.
Spicy flavor profiles generate the highest margin premiums, with sour formulations gaining share fastest through delivery-optimized production.
Service Type:
Application context determines real estate cost structure and customer acquisition economics, with platform-mediated formats compressing traditional dine-in advantages.
- Delivery:Ghost kitchen infrastructure in Phuket and Chiang Mai reduces real estate costs substantially versus traditional dine-in footprints while expanding menu reach through GrabFood and Foodpanda aggregation. Cloud-based kitchen management platforms compress operational decision cycles across Bangkok's restaurant clusters.
- Dine-in:Premium positioning in Bangkok's Sukhumvit and Silom districts requires documented hand-pounding provenance for heritage certification.
- Takeout:Format flexibility suits provincial city expansion through controlled hot-pot and Thai fusion formats.
- Catering:Subscription-based recipe licensing decouples revenue from physical kitchen ownership for hotel chains and airline caterers.
Delivery sits at the top of the volume ranking, with catering climbing the fastest through licensed formulation partnerships.
Customer Type:
Volume concentration and margin structure diverge sharply between recurring local demand and discretionary tourist spending.
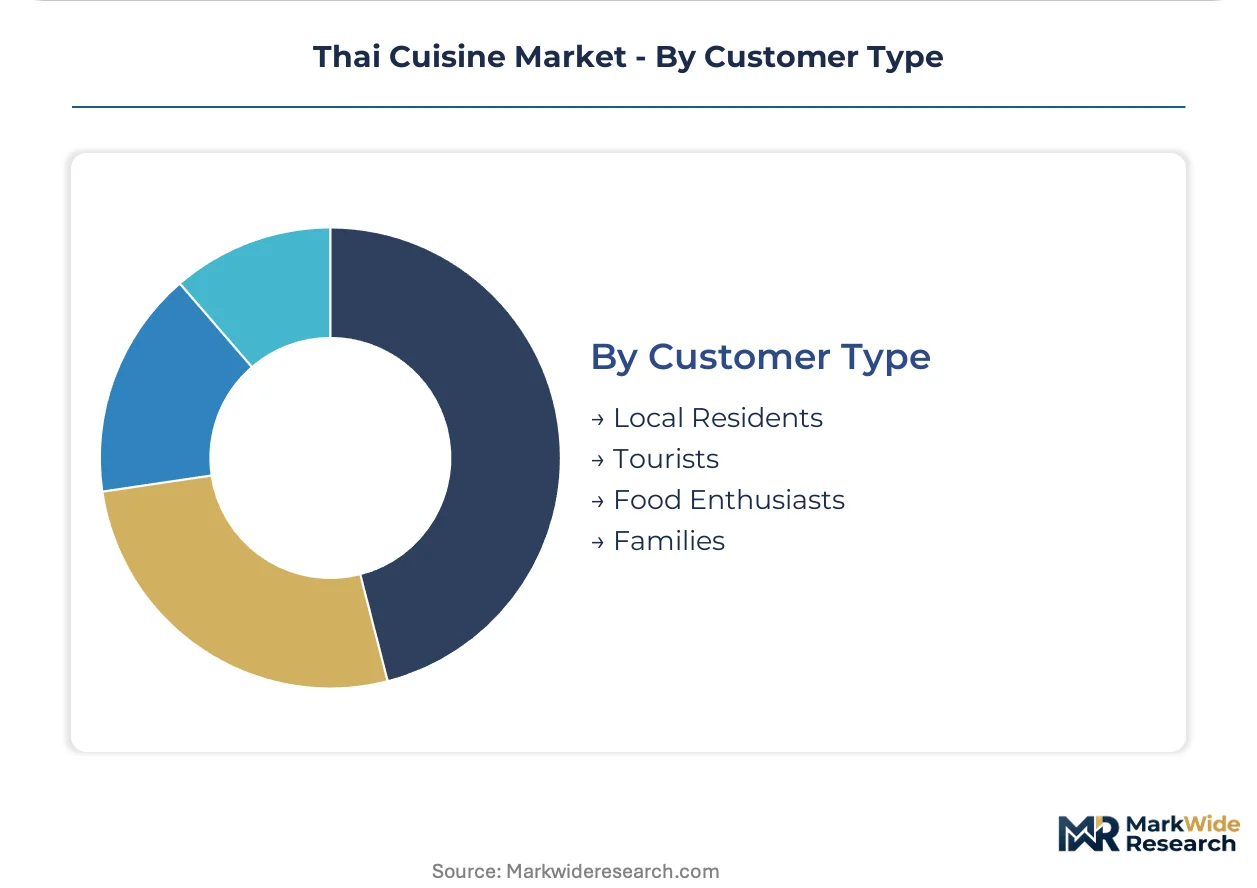
- Tourists:Aggregator-platform procurement now dominates tourist corridor demand capture, displacing direct restaurant discovery through guidebooks and hotel concierges. Behavioral concentration is most visible in Bangkok's Sukhumvit and Silom districts where platform algorithms prioritize delivery-optimized ghost kitchens.
- Local Residents:Recurring demand sustains bakery-cafe format extensions that capture morning and afternoon consumption outside lunch-dinner peaks.
- Food Enthusiasts:Heritage certification requirements create workforce training bottlenecks for documented hand-pounding provenance.
- Families:All-day consumption occasions favor standardized preparation with consistent spice modulation.
Tourists sit at the top of the volume ranking, with food enthusiasts climbing the fastest through heritage positioning and craft documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand commands the deepest production infrastructure for Thai cuisine, while the United States and Japan represent the largest export destinations for premium curry paste and frozen meal products. Cross-border demand patterns diverge sharply between Southeast Asian neighbors seeking authentic formulations and Western markets prioritizing convenience packaging.
Thailand
Bangkok's Sukhumvit and Silom districts concentrate ghost kitchen operations serving platform-mediated tourist demand, while Samut Sakhon and Nonthaburi provinces host HACCP-certified paste manufacturing clusters. Thailand's Ministry of Public Health enforces sodium disclosure mandates for pre-packaged exports. Chiang Mai's refrigerated logistics gaps restrict frozen tom yum distribution to secondary provincial cities.
United States
Thai restaurant density concentrates in Los Angeles, New York, and Houston metropolitan corridors where second-generation operators expand beyond traditional dine-in formats. FDA nutrition labeling requirements govern imported curry paste retail distribution. West Coast distribution centers handle bulk import consolidation for massaman and green curry variants before inland freight dispersal.
Japan
Tokyo and Osaka host the highest per-capita Thai restaurant concentrations outside Southeast Asia, with platform aggregation accelerating delivery-optimized kitchen formats. METI import standards and JIS packaging specifications govern frozen meal clearance procedures. Kansai region food manufacturers license Thai curry formulations for domestic retail private-label production.
United Kingdom
London's Soho and Shoreditch districts anchor independent Thai operator clusters competing with chain expansion from Bangkok-based groups. FSA allergen disclosure requirements and post-Brexit import certification protocols complicate paste product entry. Midlands distribution hubs consolidate European-bound re-export shipments from Thai manufacturing facilities.
Australia
Sydney and Melbourne absorb premium Thai dine-in demand through waterfront and inner-suburban restaurant clusters serving both tourist and diaspora segments. FSANZ nutrition labeling and biosecurity inspection protocols regulate curry paste and frozen product imports. Queensland's tropical climate supports limited domestic lemongrass and galangal cultivation for fresh herb supply.
Thai Cuisine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with dine-in chains defending position through heritage positioning while ghost kitchen operators capture delivery volume through lower fixed-cost structures. The market presents a tiered structure where Bangkok-based groups control premium urban corridors and provincial specialists expand through format replication. Three archetypes dominate: vertically integrated restaurant-paste manufacturers, platform-native delivery specialists, and licensed recipe licensors serving hotel and airline channels. Competitive moves concentrate on cloud-based kitchen management adoption and cross-border format licensing through ASEAN mutual recognition frameworks.
Among Thailand-based integrated operators, Central Restaurants Group, MK Restaurant Group, and S&P Syndicate exemplify distinct strategic positions. Central Restaurants Group anchors premium dine-in expansion through supply chain control and urban real estate concentration. MK Restaurant Group occupies the controlled-format segment with hot-pot and Thai fusion replication across provincial cities. S&P Syndicate represents bakery-cafe adjacency extension, capturing all-day consumption occasions through Thai flavor profile adaptation. These three structures illustrate how heritage credibility, operational scale, and format innovation compete for tourist and resident spending across service type tiers.
| Leading Market Players |
|---|
| Central Restaurants Group |
| Mud & Hound |
| MK Restaurant Group |
| Pad Thai Bua Dang |
| After You |
| S&P Syndicate |
| Saha Group |
| Jaan by Khun Jim |
| ZEN Group |
| Others |
Supply Flow & Price Mechanics
Mortar-and-pestle craft specialists concentrated in Bangkok's outer industrial zones anchor labor-cost differentials that widen pricing-tier spreads between heritage-certified paste production and mechanized volume manufacturing. Thailand's Ministry of Public Health sodium disclosure mandates and HACCP certification requirements from the national food safety regulator add compliance-cost layers that stratify export-grade curry products from domestic consumption tiers.
Pricing Analysis
Capacity additions in Samut Sakhon and Nonthaburi provinces are reshaping price floors for mechanized curry paste production. Three-tier pricing structure across heritage-handcrafted, certified-industrial, and unstandardized economy levels separates Bangkok's premium dine-in suppliers from provincial ghost kitchen operators. Price differentiation hinges on HACCP certification status and documented fermentation provenance. Pricing pressure stems from anchovy harvest volatility in the Gulf of Thailand, compressing margins for fish-sauce-dependent umami bases. Independent operators show highest price sensitivity due to aggregator platform commission structures, while vertically integrated groups maintain negotiation leverage.
Supply Chain Analysis
Direct-to-hotel and direct-to-airline catering channels handle institutional buyer demand for licensed curry formulations. Raw material sourcing concentrates in Thailand's central plains for lemongrass and galangal, with Mekong Delta anchovy fisheries supplying fermentation inputs. Commercial paste manufacturing draws from Bangkok's outer industrial zone clusters, with refrigerated logistics feeding export channels through ISO 22000-certified facilities. Single-region flood exposure creates supply chain risk for HACCP-certified production concentration. Distribution runs through platform-aggregated ghost kitchens in tourist corridors alongside traditional dine-in wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thai cuisine market margins expand through ghost kitchen cost-down economics and premium-tier heritage certification premiums that command price premiums in export channels.
For Market Incumbents: Deepen backward integration into fermentation input sourcing to buffer anchovy harvest volatility. Expand HACCP-certified production capacity in flood-resilient secondary locations. Platform-native delivery specialists threaten customer acquisition economics; defend direct channel relationships through subscription-based recipe licensing to hotel and airline buyers. For New Entrants and Emerging Players: Launch via cloud-based kitchen management platforms to compress operational decision cycles without legacy real estate burdens. Target provincial city delivery corridors where refrigerated logistics gaps restrict incumbent frozen product distribution. Buddhist vegetarian and export vegan segments offer penetrable white-space through plant-based protein adaptation of mechanical paste processing systems. For Investors and Strategic Acquirers: Hotel chains and airline caterers are the most active acquirer in this space, seeking licensed formulation partnerships that decouple revenue from physical kitchen ownership. Five-to-ten year viability favors certified production facilities with segregated export-grade ingredient sourcing. Monitor ASEAN mutual recognition agreement implementation progress as inflection indicator for cross-border restaurant licensing velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Ghost Kitchen Infrastructure Expansion | Reduces real estate costs sixty percent versus traditional dine-in footprints in Phuket and Chiang Mai corridors. |
| HACCP Certification Investment | Unlocks fifteen-to-twenty percent price premiums in export channels through Thailand's national food safety regulator compliance. |
| Subscription-Based Recipe Licensing | Decouples revenue from physical kitchen ownership for Central Restaurants Group and mid-tier operators serving hotel chains. |
| Plant-Based Protein Adaptation | Opens Buddhist vegetarian and export vegan segments previously inaccessible to fish-sauce-dependent production methods. |
| Cloud-Based Kitchen Management Adoption | Compresses operational decision cycles across Bangkok's restaurant clusters against aggregator-integrated competitors. |
Methodological Framework
Multiple input streams — executive interviews with curry paste manufacturers, regulatory affairs specialists at Thailand's Ministry of Public Health, hotel procurement directors, and platform operations managers — were reconciled against secondary validation from HACCP certification databases, ASEAN trade agreement documentation, and customs export records. Bottom-up facility capacity assessments and top-down tourist spending flow analysis provided triangulation anchors.
Data-stream reconciliation across product type, flavor profile, service type, and customer type dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from segmented growth trajectory modeling incorporating ghost kitchen penetration rates, certification compliance timelines, and aggregator platform market share shifts. Industry-specific inputs included anchovy harvest cycle patterns and refrigerated logistics network expansion schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged fish sauce input volatility or accelerated ASEAN mutual recognition implementation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
North American Jam, Jelly, and Preserve Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Gluten-Free Oats Market
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
Global Guilt-Free Desserts Market
Specialty Foods
White Fungus Market
Specialty Foods
Personalized Meals Market
Specialty Foods
Global Diet Food and Beverages Market
Specialty Foods
Moringa Products Market
Specialty Foods
Free-From Food Market
Specialty Foods
Human Grade Pet Food Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Malaysia Manuka Honey Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Spirulina Chocolate Market
Specialty Foods
Global Honey Market