
 Morocco Couscous Market | 2026-2036
Morocco Couscous Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Couscous Market Intelligence
Subscription-based replenishment models for instant couscous is restructuring how Moroccan producers monetize repeat consumption. Dari Couspate leverages its coastal milling infrastructure to dominate bulk supply contracts with European distributors. Ebro Foods, S.A. anchors its Maghreb position through backward integration into durum wheat procurement networks. Barilla G. e R. Fratelli S.p.A. competes on brand recognition in premium retail channels across France and Italy.
Couscous consists of steamed semolina granules, typically under three millimeters in diameter, produced through a multi-step hydration and rolling process before final drying to moisture levels below twelve percent. The product serves as a staple carbohydrate base across North African and Middle Eastern cuisines, valued for its rapid rehydration properties and neutral flavor profile. Traditional couscous retains the largest volume share in Moroccan domestic consumption, while instant couscous captures expanding margin pools through convenience positioning in European export markets. Whole wheat and organic variants within product type segmentation attract premium pricing from health-conscious consumers in French and German retail channels.
ONSSA, Morocco's national food safety authority, enforces strict aflatoxin and pesticide residue limits on durum wheat entering couscous production chains. The country's Ministry of Agriculture, under Plan Maroc Vert, subsidizes certified seed programs that directly shape raw material quality standards for industrial millers. BSI Kitemark and IFS certifications function as de facto market access requirements for Moroccan exporters targeting British and continental European retail buyers. Stakeholders must monitor evolving EU deforestation regulation traceability requirements that could reshape durum wheat sourcing verification costs.
Market Dynamics
Plan Maroc Vert is restructuring durum wheat sourcing standards across Moroccan couscous production chains, forcing industrial millers to recertify procurement networks and reshaping competitive positioning between coastal processing clusters and inland agricultural zones.
Growth Catalysts
- Institutional catering expansion:French and German foodservice distributors are expanding Moroccan couscous placement in university and hospital contracts, creating volume pull for bulk semolina processors.
- EU deforestation regulation traceability:Moroccan exporters gaining early compliance certification are securing preferential shelf access in British and continental European retail channels ahead of enforcement deadlines.
- Whole wheat premium positioning:Health-conscious consumers in Paris and Milan retail markets are paying price premiums for fiber-enriched couscous variants, expanding margin pools beyond traditional semolina grades.
Market Restraints
- Durum wheat price volatility:Moroccan millers face input cost pressure from Black Sea supply disruptions and domestic harvest variability under erratic rainfall patterns.
- ONSSA compliance costs:Aflatoxin testing protocols and pesticide residue screening requirements add fixed overhead for small-to-midscale processors without captive laboratory infrastructure.
- Instant pasta substitution:North African diaspora consumers in Belgium and Netherlands are partially shifting toward convenience pasta formats that compete for the same meal occasions.
Strategic Opportunities
- Subscription replenishment models:Direct-to-consumer platforms in French urban markets are capturing repeat purchase data that enables predictive production scheduling for Moroccan suppliers.
- Organic certification arbitrage:IFS-certified Moroccan producers can access German organic retail channels where domestic supply falls short of demand growth for chemical-free grain products.
- Casablanca-Rabat corridor consolidation:Processing capacity concentration along Morocco's Atlantic rail freight axis enables economies of scale in packaging and export logistics that inland competitors cannot replicate.
Industry Challenges
- Semolina milling technician scarcity:Traditional couscous craftsmanship skills are aging out of the workforce faster than vocational training programs in Fes and Meknes can replenish qualified operators.
- BSI Kitemark certification timelines:British retail market entry requires 14-18 month approval cycles that strain working capital for exporters targeting post-Brexit procurement windows.
- Legacy drying equipment retrofitting:Natural gas-to-solar thermal conversion in pre-cooking facilities demands capital outlays that family-owned mills cannot finance without cooperative pooling arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Couscous Market |
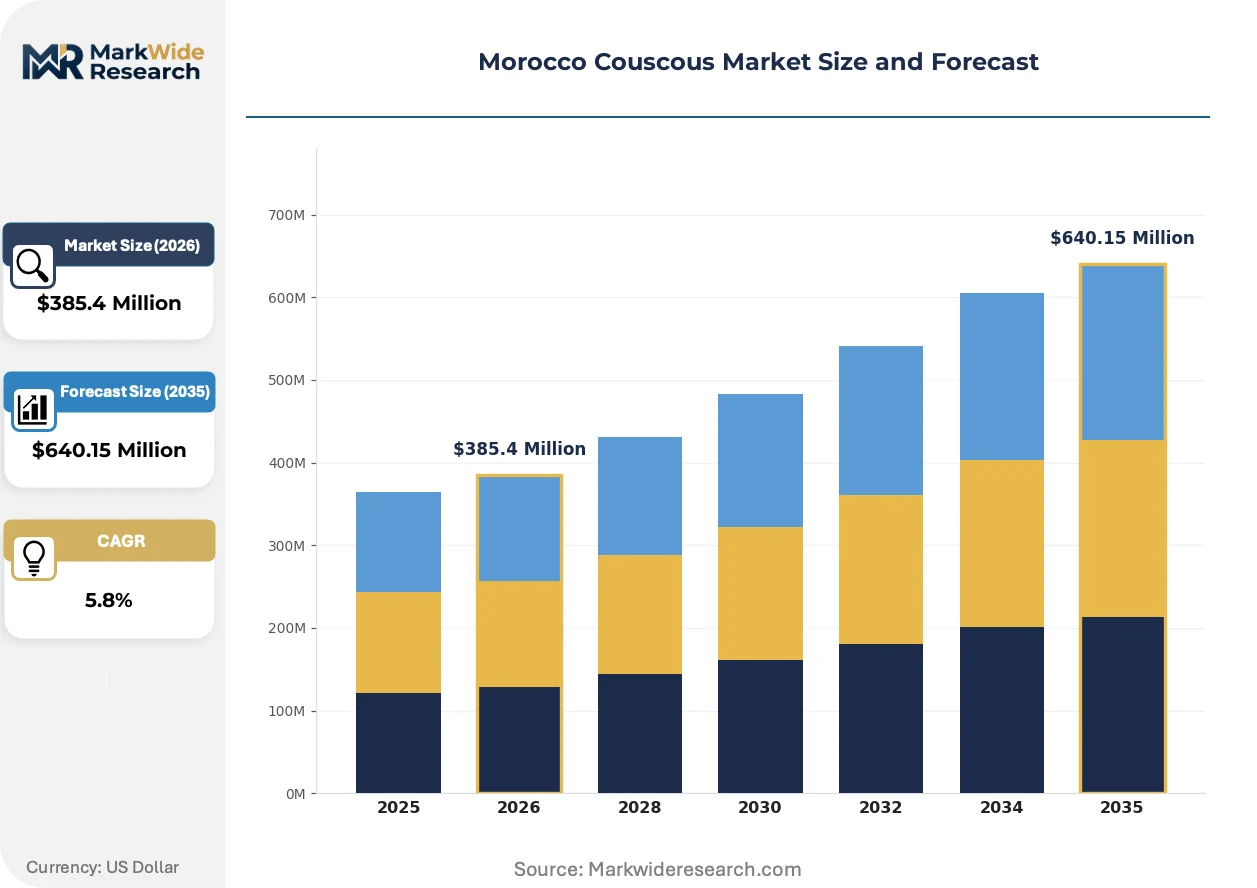
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Couscous, Instant Couscous, Whole Wheat Couscous, Organic Couscous End User: Households, Restaurants, Catering Services, Food Manufacturers Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Direct Sales Packaging Type: Bulk Packaging, Retail Packs, Eco-friendly Packaging, Vacuum-sealed Packs |
| Companies Covered | Barilla G. e R. Fratelli S.p.A., Ebro Foods, S.A., Dari Couspate, Sabarot Wassner S.A., Tipiak S.A., Dalia Foods, Al'Fez by AB World Foods Ltd., Roland Foods, LLC, Kayna Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Couscous Market Strategic Shifts & Innovations
Automation in semolina hydration and rolling is compressing production cycle times while traceability technologies are redefining what Moroccan exporters must document to retain European retail access.
Near-infrared spectroscopy for real-time moisture detection during the final drying stage is converging with blockchain-based lot tracking to create integrated quality assurance systems. Casablanca-based industrial millers are adopting these combined platforms at accelerating rates. The technology convergence is enabling Moroccan suppliers to offer batch-specific certificates that satisfy EFSA-aligned retailer requirements without third-party laboratory delays.
EU deforestation regulation due diligence obligations are mandating geolocation documentation for every durum wheat field entering couscous supply chains. Moroccan agricultural cooperatives must now deploy GPS mapping and satellite verification tools to maintain export eligibility. Smallholder-dominated sourcing networks in the Saïss plain and Tadla regions face particular adaptation pressure as compliance costs concentrate among non-integrated processors.
French supermarket buyers are consolidating couscous procurement through centralized category management teams that bypass traditional import-distributor relationships. This channel compression is displacing fragmented wholesale purchasing across Carrefour and Auchan retail networks. The shift is most visible in Paris and Lyon metropolitan areas where private-label couscous volumes are expanding at the expense of branded import SKUs.
Morocco Couscous Market Segmentation
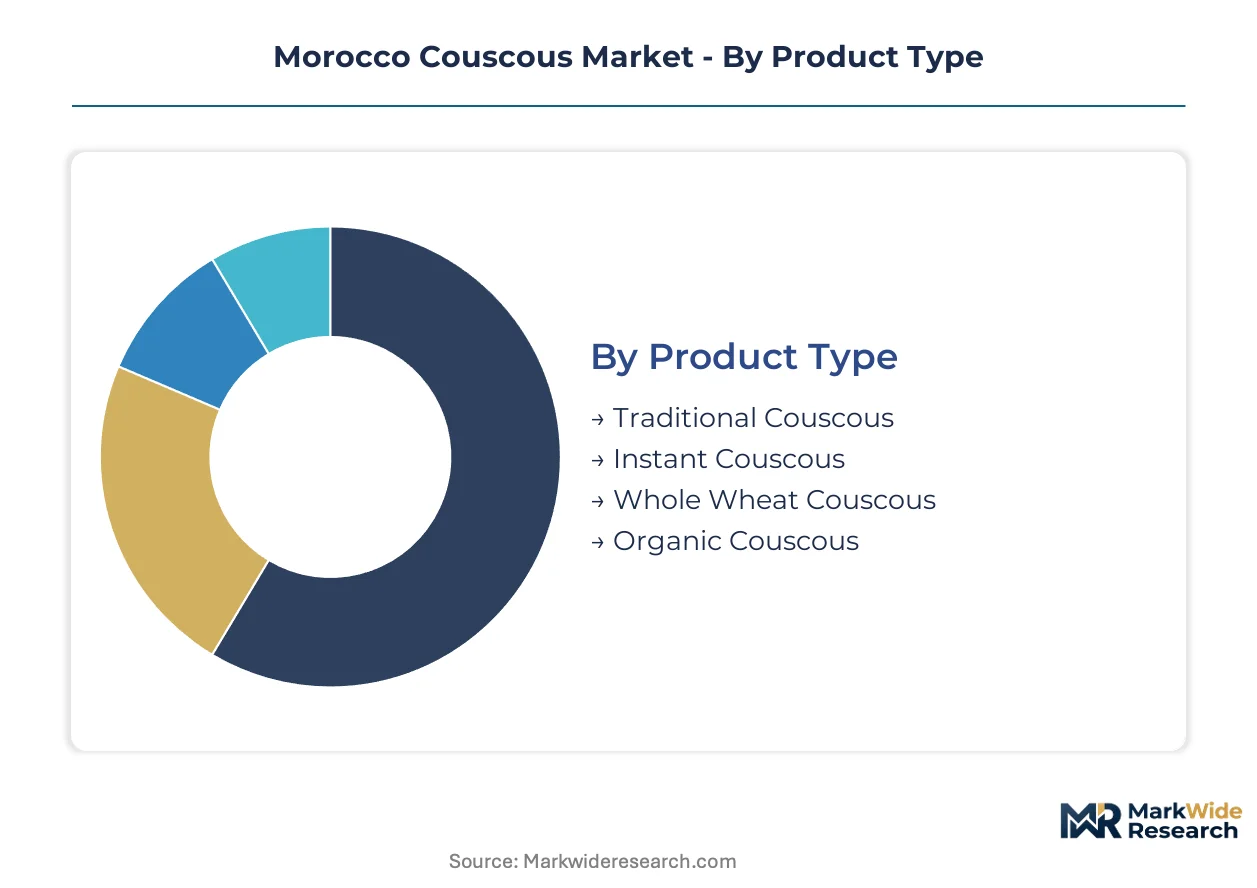
Couscous segmentation in Morocco reflects divergent margin structures between artisanal domestic consumption and export-oriented convenience formats. Buyers prioritize rehydration speed, certification grade, or unit economics depending on end-use application and channel access.
Product Type:
Buyers select couscous format based on preparation time constraints and price elasticity relative to meal occasion value.
- Traditional Couscous:Coarse semolina granules require steaming preparation and retain the largest volume share in Moroccan domestic consumption. Demand concentrates in household meal preparation across Fes and Marrakech where extended cooking time aligns with cultural dining rituals and lower price sensitivity for ceremonial occasions.
- Instant Couscous:Pre-steamed and dried granules rehydrate in boiling water within five minutes, capturing expanding margin pools through convenience positioning. Demand from French and German retail channels is accelerating as urban consumers substitute labor-intensive traditional preparation with speed-optimized formats.
- Whole Wheat Couscous:Fiber-enriched semolina variant attracts premium pricing from health-conscious consumers in Paris and Milan retail markets.
- Organic Couscous:Chemical-free grain certification enables access to German organic retail channels where domestic supply falls short of demand growth.
Traditional Couscous leads on scale; Instant Couscous leads on momentum.
End User:
Volume concentration and margin capture diverge sharply between fragmented household purchasing and consolidated institutional contracts.
- Households:Fragmented consumer base purchases through retail channels with high brand loyalty to established Moroccan labels. Casablanca-Rabat corridor households demonstrate strongest per-capita consumption frequency.
- Restaurants:High-volume operators in European cities require consistent semolina granule size for plating standardization and batch predictability. French foodservice distributors are expanding Moroccan couscous placement in university and hospital contracts.
- Catering Services:Event and institutional caterers prioritize bulk packaging economics and rapid rehydration for large-scale meal service.
- Food Manufacturers:Industrial buyers source semolina for ready-meal and ingredient applications requiring ONSSA-compliant aflatoxin documentation.
Households anchor volume absorption; Restaurants are climbing the fastest on contract consolidation.
Distribution Channel:
Channel selection determines certification requirements, margin retention, and buyer relationship depth for Moroccan suppliers.
- Supermarkets:Centralized category management at Carrefour and Auchan networks is displacing fragmented wholesale purchasing across Paris and Lyon metropolitan areas.
- Online Retail:Direct-to-consumer platforms in French urban markets capture repeat purchase data enabling predictive production scheduling for Moroccan suppliers.
- Specialty Stores:Ethnic grocery channels in Belgium and Netherlands serve North African diaspora consumers with heritage brand preferences.
- Direct Sales:Bulk institutional contracts bypass distributor markups for high-volume catering and food manufacturing accounts.
Supermarkets dominate transaction volume; Online Retail shows steepest expansion trajectory on subscription model adoption.
Packaging Type:
Packaging specification aligns with shelf-life requirements, logistics economics, and sustainability positioning in target markets.
- Bulk Packaging:Industrial totes and sacks serve food manufacturers and catering operators with captive processing facilities.
- Retail Packs:Standardized consumer units face margin compression from private-label expansion in French supermarket networks.
- Eco-friendly Packaging:Compostable and recyclable materials attract shelf placement premiums in German and British retail channels with sustainability mandates.
- Vacuum-sealed Packs:Extended shelf-life formats enable export distribution to distant markets without cold chain infrastructure.
Retail Packs maintain widest deployment; Eco-friendly Packaging gains share fastest on EU regulatory alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France absorbs higher couscous volumes per capita than Germany despite both markets operating under identical EU food safety frameworks. Italian retail channels favor coarser semolina grades that diverge from French preparation preferences. Spanish import patterns reflect distinct North African diaspora settlement histories.
France
Paris and Lyon metropolitan areas drive concentrated demand through Carrefour and Auchan centralized category management teams. ANSM enforces aflatoxin screening protocols that Moroccan exporters must satisfy for retail shelf placement. Processing contracts concentrate around Marseille port logistics corridors where bulk semolina enters European distribution networks.
Germany
Organic retail channels in Berlin and Munich generate premium pricing for IFS-certified Moroccan suppliers where domestic chemical-free grain supply falls short. BfR pesticide residue guidelines shape import documentation requirements that differ from French enforcement intensity. Hamburg and Frankfurt foodservice distributors are expanding university and hospital contract placements for bulk couscous formats.
Italy
Milan retail markets pay fiber-enriched whole wheat premiums that exceed traditional semolina pricing tiers. Ministry of Health decrees on durum wheat origin labeling create compliance overlays beyond baseline EU regulations. Processing gravity centers on Piedmont milling clusters where Barilla maintains captive semolina supply relationships.
Spain
Barcelona and Madrid ethnic grocery channels serve Moroccan and Algerian diaspora populations with heritage brand loyalties distinct from French supermarket preferences. AESAN traceability mandates align with evolving EU deforestation regulation geolocation documentation requirements. Valencia port infrastructure handles increasing transshipment volumes for North African couscous re-export to Latin American markets.
Belgium
Brussels and Antwerp foodservice operators report partial consumer shifts toward convenience pasta formats competing for identical meal occasions. FAVV food safety authority applies Belgian-specific interpretation of EFSA mycotoxin thresholds that exceed Dutch enforcement stringency. Liège processing facilities serve as secondary consolidation points for German-bound couscous shipments.
Morocco Couscous Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with heritage Moroccan labels commanding retail premiums while European food conglomerates dominate institutional procurement channels. The vendor base organizes around three archetypes: coastal Moroccan millers with captive durum wheat sourcing, European multinationals with backward integration into semolina supply, and specialty importers serving diaspora ethnic channels. Consolidation pressure concentrates among Casablanca-Rabat corridor processors seeking economies of scale in packaging and export logistics. Competitive maneuvering centers on certification acquisition for EU market access and subscription platform partnerships for direct-to-consumer reach.
Within the multinational tier, Barilla G. e R. Fratelli S.p.A. and Ebro Foods, S.A. exemplify divergent geographic anchoring strategies, with the former representing Italian-centric premium retail positioning and the latter occupying Spanish-led Maghreb procurement integration. Dari Couspate sits within the coastal Moroccan miller archetype, leveraging proximity to Atlantic port infrastructure for European bulk contract fulfillment.
| Leading Market Players |
|---|
| Barilla G. e R. Fratelli S.p.A. |
| Ebro Foods, S.A. |
| Dari Couspate |
| Sabarot Wassner S.A. |
| Tipiak S.A. |
| Dalia Foods |
| Al'Fez by AB World Foods Ltd. |
| Roland Foods, LLC |
| Kayna Group |
| Others |
Cost & Logistics Intelligence
EU deforestation regulation traceability mandates are forcing Moroccan millers to absorb geolocation verification costs that reshape procurement economics and compress margins for non-integrated processors. Coastal processors in the Casablanca-Rabat corridor leverage captive laboratory infrastructure to offset compliance overhead while inland competitors face price disadvantage.
Pricing Analysis
Capacity additions in the Casablanca-Rabat corridor are reshaping price floors for bulk semolina contracts as economies of scale concentrate among Atlantic rail-linked processors. Three-tier pricing structure across organic-certified, IFS-grade, and standard export tiers reflects certification investment differentials. Cost compression in standard-grade couscous is intensifying because Black Sea durum wheat volatility feeds into input costs. Food manufacturers and institutional caterers demonstrate highest price sensitivity, while German organic retail channels accept substantial premiums for chemical-free grain documentation.
Supply Chain Analysis
Plan Maroc Vert domestic-content mandates are reshaping sourcing patterns as subsidized certified seed programs tether industrial millers to Moroccan durum wheat cooperatives. Supply concentrates in Morocco's Saïss plain and Tadla regions, with secondary sourcing from French and Italian durum wheat markets for premium grades. Raw material dependencies center on durum wheat semolina, natural gas for pre-cooking thermal energy, and compostable packaging substrates for EU sustainability compliance. Single-source vulnerability runs through aging semolina milling technician pools in Fes and Meknes. Distribution runs through Marseille and Valencia port logistics corridors for European bulk contracts, with direct rail freight to Paris and Lyon metropolitan areas for retail replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Morocco couscous market operates as a regulatory compounder where EU deforestation regulation enforcement creates structural demand for traceability-certified supply chains. This dynamic rewards early compliance investment with preferential shelf access.
For Market Incumbents: Extend certification coverage beyond baseline IFS requirements to capture German organic retail premiums before supply catches demand. Anchor backward integration into durum wheat procurement networks to insulate margin structures from Black Sea price volatility. Coastal processors should consolidate packaging capacity along the Atlantic rail freight axis to replicate Casablanca-Rabat corridor economies of scale that inland competitors cannot match.
For New Entrants and Emerging Players: Subscription platform partnerships in French urban markets offer the most penetrable entry vector, capturing repeat purchase data that enables predictive production scheduling without legacy distributor relationships. Target Belgian and Netherlands ethnic grocery channels where heritage brand loyalty among North African diaspora consumers resists supermarket consolidation. Lead with vacuum-sealed extended shelf-life formats to access distant export markets lacking cold chain infrastructure.
For Investors and Strategic Acquirers: Asymmetric upside sits with IFS-certified mid-scale processors in the Saïss plain facing manageable compliance adaptation costs relative to valuation discounts. Long-term viability hinges on Plan Maroc Vert alignment and vocational training program partnerships that replenish qualified semolina milling technicians. Watch for BSI Kitemark certification completion as inflection signal for British retail market entry readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| EU Deforestation Regulation Compliance | Geolocation documentation capabilities unlock preferential shelf access at Carrefour and Auchan networks. |
| Backward Integration into Durum Wheat | Captive sourcing from Plan Maroc Vert certified cooperatives insulates margin structures from input volatility. |
| Subscription Platform Partnership | Direct-to-consumer data capture enables predictive production scheduling for French urban market replenishment. |
| Solar Thermal Retrofit | Natural gas-to-solar conversion in pre-cooking facilities aligns with EU Green Deal sustainability mandates. |
| Vocational Training Investment | Fes and Meknes technician pipeline partnerships address aging workforce scarcity in traditional couscous craftsmanship. |
Research Approach
Coverage spans Morocco, France, Germany, Italy, and Spain, with primary inputs from each market combining interviews with couscous processing plant managers, Carrefour category buyers, ONSSA compliance officers, and Marseille port logistics coordinators. Secondary validation draws from EU customs trade data, Plan Maroc Vert agricultural ministry disclosures, EFSA aflatoxin threshold documentation, and IFS certification registry records. Bottom-up volume triangulation across product type, end user, and distribution channel segments converges with top-down macroeconomic anchoring.
Rate-of-change decomposition separates volume drivers from price evolution across the projection horizon. Segmentation dimensions modeled include product format granularity, certification tier, buyer concentration level, and regional regulatory cluster intensity. CAGRs derive from historical trajectory analysis adjusted for structural break points including Plan Maroc Vert implementation and EU deforestation regulation phase-in. Industry-specific forecast inputs incorporate durum wheat harvest variability patterns and ONSSA laboratory capacity expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Black Sea supply disruption recurrence and EU organic certification demand saturation. Forecasts reflect documented assumptions about Plan Maroc Vert subsidy continuity and vocational training program graduation rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Truffle Market
Specialty Foods
Wheatgrass Products Market
Specialty Foods
Aloe Vera Gel Market
Specialty Foods
Vegan Salad Dressing Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Europe Hummus Market
Specialty Foods
Edible Cutlery Market
Specialty Foods
Global Cordyceps Militaris Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Edible Mushroom Market
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market
Specialty Foods
Kosher Food Market
Specialty Foods
Space Food Market
Specialty Foods
Free-From Food Market