
 Reishi Mushroom Market | 2026-2036
Reishi Mushroom Market Size, Share, and Industry Trends Forecast 2026-2036
Reishi Mushroom Market Outlook
Dietary supplement brands is rebalancing the Reishi Mushroom Market as functional wellness consumers shift from sporadic purchases to subscription-based routines. Hokkaido Reishi Co. Ltd. anchors premium cultivation through controlled-environment farms in northern Japan. DXN Holdings Bhd dominates direct-to-consumer channels across Southeast Asia with integrated plantation-to-shelf operations. Nammex differentiates through certified organic extraction protocols serving North American contract manufacturers.
Reishi mushroom comprises the fruiting body and mycelium of Ganoderma lucidum, a polypore fungus containing triterpenoids, beta-glucans, and peptidoglycans extracted through hot water or alcohol processing for immunomodulatory and adaptogenic applications. Powder and extract forms command the largest volume positions due to their incorporation into bulk supplement manufacturing and functional beverage formulations. Capsule segments sustain higher margin pools as finished brands capture value through convenience positioning and dosage standardization. Liquid formats occupy emerging niches in wellness-focused food service and personalized nutrition protocols.
FDA dietary supplement regulations and DSHEA compliance requirements shape product labeling, structure-function claims, and new ingredient notification pathways for US market access. China's NMPA and GB standards govern extraction solvent residues and heavy metal thresholds for domestic and export-bound material. EFSA and EMA frameworks in Europe influence novel food approvals and health claim substantiation. Stakeholders must monitor evolving mycelium-versus-fruiting-body labeling standards and carbon-footprint disclosure requirements as procurement criteria tighten across major import markets.
Market Dynamics
China's NMPA is tightening extraction solvent residue limits while the country's dual carbon goals force cultivation facilities toward renewable energy retrofits, compressing margins for exporters who must simultaneously meet EFSA novel food standards and FDA DSHEA compliance.
Growth Catalysts
- EFSA novel food approval pathways:European supplement brands are accelerating reishi inclusion as the framework clarifies mycelium-versus-fruiting-body distinction, opening shelf space previously blocked by regulatory ambiguity.
- South Korea's functional food certification expansion:MFDS streamlined health claim substantiation for polysaccharide extracts, pulling Japanese and Chinese suppliers into Seoul-directed formulation partnerships.
- Hot water extraction automation:Continuous processing systems are cutting beta-glucan recovery costs by half, enabling mid-tier contract manufacturers to compete with established extraction houses.
Market Restraints
- Substrate cost volatility:Hardwood sawdust prices fluctuate with construction cycles in Zhejiang and Fujian provinces, where 60 percent of Chinese fruiting body production concentrates.
- Heavy metal thresholds:China's GB standards for cadmium and lead are stricter than CODEX Alimentarius limits, forcing dual testing protocols that add 12-18 percent to export-bound material costs.
- Mycelium substitution threat:Grain-grown mycelial biomass commands lower input costs than log-cultivated fruiting bodies, pressuring premium positioning for traditional extraction houses.
Strategic Opportunities
- Personalized nutrition protocols:Liquid reishi extracts are entering compounding pharmacy workflows in Germany and Switzerland, where practitioners blend adaptogenic stacks for individual patient profiles.
- Carbon footprint disclosure mandates:EU CSRD reporting requirements are creating first-mover advantage for Japanese suppliers with certified renewable energy credentials at Hokkaido cultivation sites.
- Direct-to-practitioner channels:Telehealth-integrated supplement dispensaries in North America are bypassing retail markup, capturing margin previously lost to brick-and-shelf intermediaries.
Industry Challenges
- Trained mycologist scarcity:Quality control laboratories lack personnel capable of distinguishing Ganoderma lucidum from adulterant species like G. sinense using microscopic morphology.
- Dual certification timelines:Simultaneous pursuit of USDA Organic and EU Organic labels requires 18-24 month field conversion periods that freeze working capital.
- Legacy ERP integration:Batch traceability systems for NMPA compliance rarely interface with North American contract manufacturers' inventory platforms, forcing manual reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reishi Mushroom Market |
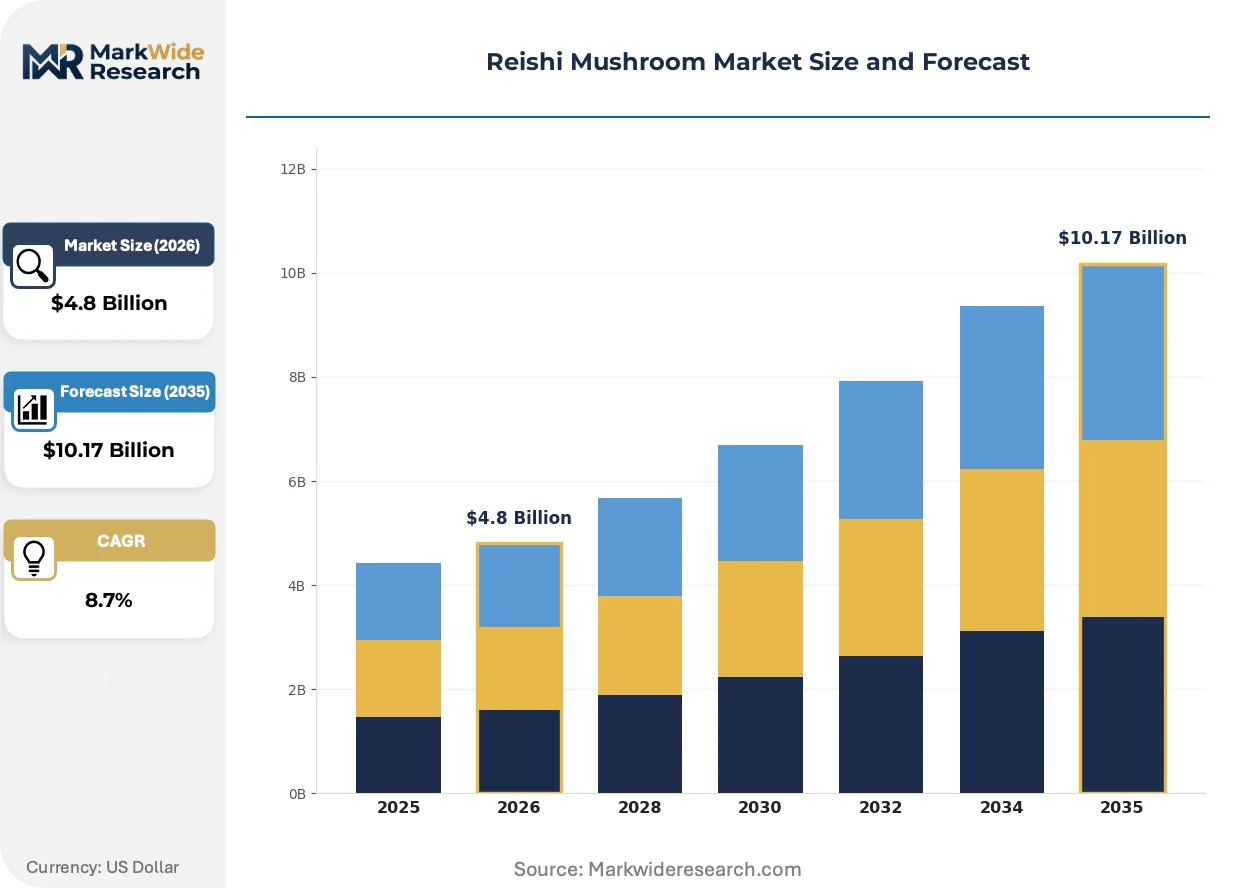
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Extract, Capsule, Liquid Application: Healthcare, Dietary Supplements, Cosmetics, Food & Beverage Distribution Channel: Online, Offline, Specialty Stores, Pharmacies End User: Retail Consumers, Health Practitioners, Food Manufacturers, Cosmetic Companies |
| Companies Covered | Bio-Botanica Inc., Bristol Botanicals Limited, Hokkaido Reishi Co. Ltd., Nammex, DXN Holdings Bhd, Alphay International Inc., Mushroom Science, Qingdao Dacon Trading Co. Ltd., Ron Teeguarden Enterprises Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reishi Mushroom Market Strategic Shifts
Bioprocessing advances and regulatory clarity are compressing the gap between traditional cultivation and pharmaceutical-grade extraction, while procurement patterns fragment across subscription wellness platforms and clinical dispensing channels.
Submerged fermentation technology for mycelial biomass production is integrating pharmaceutical-grade bioreactor controls into supplement supply chains. North American contract manufacturers are adopting these systems at pilot scale to secure consistent triterpenoid profiles regardless of harvest seasonality. The technology is integrating quality predictability into formulations previously dependent on variable wild-simulated material.
China's GB 2762-2022 food contaminant limits are forcing extraction houses to relocate drying operations away from industrial zones in Zhejiang province. Facilities in Fujian and Jiangxi are capturing displaced volume as coastal plants invest in activated carbon filtration and reverse osmosis wash systems. Powder and extract segments face the steepest compliance cost escalation, while capsule finished goods absorb margin compression through convenience pricing power.
Subscription-based replenishment models are displacing sporadic retail purchases among functional wellness consumers in Japan and South Korea. Hokkaido Reishi Co. Ltd. and DXN Holdings Bhd. are both piloting direct-to-consumer platforms with practitioner integration, where telehealth consultations drive protocol adherence. This behavioral shift concentrates lifetime value in cohorts with demonstrated compliance, reducing customer acquisition cost amortization pressure.
Reishi Mushroom Market Segmentation
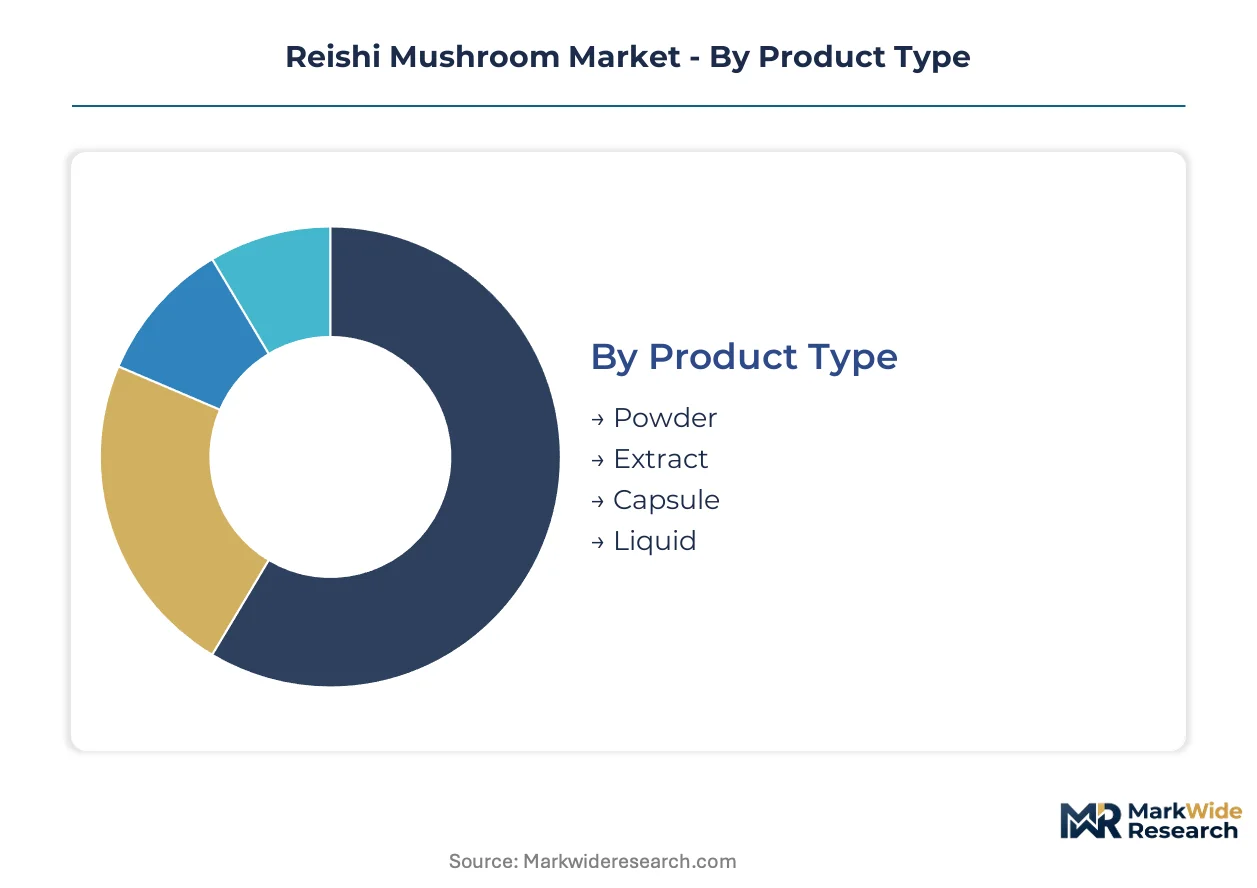
Reishi mushroom supply chains fragment across four distinct product formats, each commanding different margin pools and regulatory compliance burdens. Extraction protocols and finished dosage forms create tiered value capture that shapes competitive positioning across dietary supplement and functional food channels.
Product Type:
Upgrade cycles from bulk powder to standardized extracts are accelerating as contract manufacturers face FDA DSHEA substantiation requirements and EFSA novel food scrutiny.
- Powder:Ground fruiting body or mycelial biomass retains full fiber matrix and requires minimal processing, making it the default input for bulk supplement blending and functional bakery applications. Demand concentrates in North American contract manufacturing, where powder integrates into multi-ingredient formulations despite variable beta-glucan potency.
- Extract:Hot water or dual-stage alcohol extraction isolates triterpenoids and polysaccharides into standardized potencies, commanding premium positioning for clinical and practitioner-directed protocols. Japanese and South Korean brands are pulling extract volumes as MFDS functional food certification clarifies polysaccharide claim substantiation.
- Capsule:Encapsulated powder or extract delivers dose precision and convenience for direct-to-consumer wellness platforms.
- Liquid:Tinctures and concentrated drops serve compounding pharmacy workflows and personalized nutrition stacks in German and Swiss markets.
Volume placements concentrate in Powder; the faster expansion belongs to Extract.
Application:
Cost tier stratification separates commodity ingredient supply from finished brand value capture across therapeutic and lifestyle positioning.
- Dietary Supplements:Capsule and tablet finished goods dominate revenue pools through subscription replenishment models in Japan and South Korea, where functional wellness consumers prioritize protocol adherence over sporadic retail purchasing. Hokkaido Reishi Co. Ltd. and DXN Holdings Bhd. are both building direct-to-consumer infrastructure around this behavioral shift.
- Healthcare:Practitioner-directed extracts and compounded formulations serve integrative medicine protocols in Germany and Switzerland, where telehealth-integrated dispensaries bypass traditional retail markup.
- Food & Beverage:Powder incorporation into functional beverages and adaptogenic coffee alternatives is gaining formulation share among North American beverage startups.
- Cosmetics:Triterpenoid-rich extracts enter premium skincare lines targeting antioxidant and anti-inflammatory positioning in Seoul and Tokyo beauty markets.
Margin capture peaks in Healthcare practitioner channels; broadest volume scaling occurs in Dietary Supplements.
Distribution Channel:
Customer type fragmentation is splitting procurement between convenience-driven direct platforms and relationship-heavy professional networks.
- Online:Direct-to-consumer platforms and subscription services are displacing sporadic retail purchases among functional wellness cohorts in Japan and South Korea.
- Specialty Stores:Curated retail environments in Tokyo and Seoul districts serve educated consumers seeking origin transparency and organic certification verification.
- Offline:Traditional retail and mass-market pharmacy chains retain volume in Southeast Asian markets where DXN Holdings Bhd. maintains plantation-to-shelf integration.
- Pharmacies:Clinical dispensing channels in Germany and Switzerland integrate liquid extracts into practitioner-compounded adaptogenic protocols.
Fastest channel expansion is occurring in Online; Pharmacy channels sustain the highest per-unit margins.
End User:
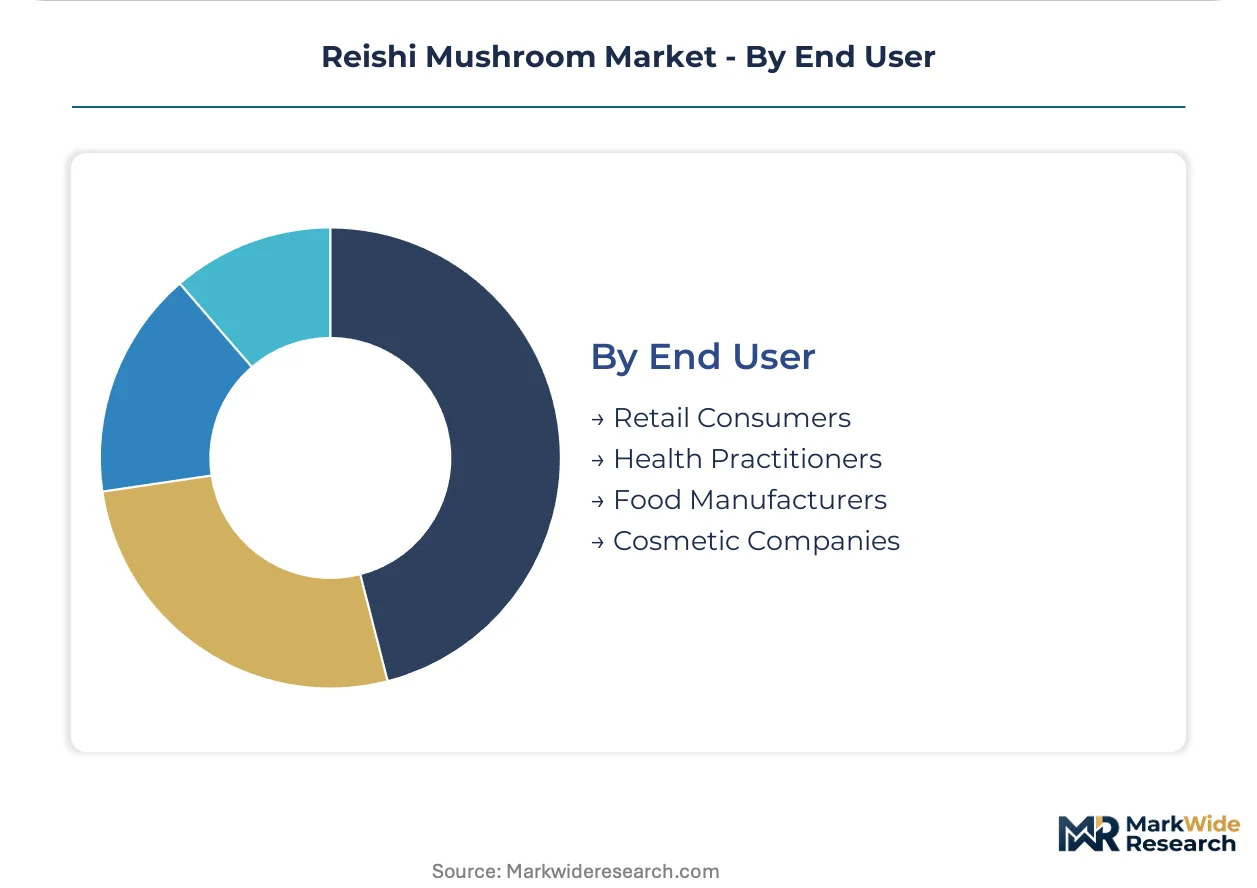
Supply concentration among extraction houses and finished brands maps directly to end-user sophistication and quality verification requirements.
- Retail Consumers:Subscription-based replenishment models concentrate lifetime value among compliance-demonstrated cohorts, reducing customer acquisition cost pressure for brands like Hokkaido Reishi Co. Ltd.
- Health Practitioners:Integrative medicine and naturopathic clinicians in Germany and Switzerland drive demand for certified organic extracts with batch-specific COA documentation.
- Food Manufacturers:Beverage and functional food formulators in North America require consistent beta-glucan profiles that submerged fermentation systems increasingly satisfy.
- Cosmetic Companies:Premium skincare brands in Seoul and Tokyo specify triterpenoid-standardized extracts for antioxidant positioning in anti-aging product lines.
Practitioner-directed procurement is climbing the fastest; Retail Consumer volumes maintain the broadest base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang province's agricultural technology parks offer preferential land leases and tax holidays for certified organic cultivation operations, concentrating extraction facility investment along the Yangtze River Delta corridor.
China
Domestic functional food brands are absorbing surplus fruiting body output previously destined for export. NMPA's GB 2762-2022 contaminant limits are forcing drying operation relocations from industrial zones to Fujian and Jiangxi provinces. Hangzhou and Ningbo clusters are installing activated carbon filtration systems to maintain EU-bound shipment eligibility.
Japan
Subscription wellness platforms in Tokyo and Osaka are displacing traditional pharmacy retail for reishi capsule purchases. METI's carbon footprint disclosure guidelines for functional foods are privileging Hokkaido-based suppliers with renewable energy credentials. Northern Japan cultivation sites are capturing premium positioning through controlled-environment farm certification.
South Korea
MFDS streamlined health claim substantiation for polysaccharide extracts is pulling Japanese and Chinese suppliers into Seoul-directed formulation partnerships. Daegu-Gyeongbuk region's traditional medicine distributors are integrating direct-to-consumer telehealth platforms. Seoul Capital Area consumers are driving demand for triterpenoid-standardized extracts in beauty-adjacent wellness protocols.
Germany
Compounding pharmacies in Munich and Hamburg are incorporating liquid reishi extracts into personalized adaptogenic stacks for integrative medicine patients. EFSA novel food approval clarity is enabling supplement brands to expand mycelium-versus-fruiting-body labeled product lines. Bavaria's practitioner network is bypassing retail markup through telehealth-integrated dispensary channels.
United States
FDA DSHEA structure-function claim enforcement is pressuring contract manufacturers toward standardized extract inputs with batch-specific COA documentation. Pacific Northwest beverage startups are driving powder demand for adaptogenic coffee alternatives. California's dietary supplement brands are building subscription infrastructure to capture lifetime value from compliance-demonstrated consumer cohorts.
Reishi Mushroom Market Competitive Environment
Top-tier vendors anchor premium extraction and finished brand positioning, while mid-tier contract manufacturers compete on beta-glucan recovery automation. The vendor base stratifies across plantation-integrated multinationals, certified organic specialists, and regional extraction houses serving North American formulators. Three archetypes dominate: controlled-environment cultivators with renewable energy credentials, direct-to-consumer platform operators with subscription infrastructure, and extraction protocol specialists serving practitioner channels. Capacity expansion and certification stacking represent the dominant competitive moves as dual USDA-EU Organic timelines freeze working capital for 18-24 month field conversion periods.
Within the plantation-integrated tier, Hokkaido Reishi Co. Ltd. and DXN Holdings Bhd occupy positions exemplifying geographic specialization and channel control respectively, while Nammex represents the North American extraction protocol specialist archetype serving contract manufacturing demand.
| Leading Market Players |
|---|
| Bio-Botanica Inc. |
| Bristol Botanicals Limited |
| Hokkaido Reishi Co. Ltd. |
| Nammex |
| DXN Holdings Bhd |
| Alphay International Inc. |
| Mushroom Science |
| Qingdao Dacon Trading Co. Ltd. |
| Ron Teeguarden Enterprises Inc |
| Others |
Value Chain & Pricing Dynamics
Hardwood sawdust substrate costs in Zhejiang and Fujian provinces cascade through three distinct pricing tiers as log-cultivated fruiting bodies command premium positioning over grain-grown mycelial biomass. Buyers in practitioner-directed channels absorb elevated per-unit costs for certified organic extracts with batch-specific COA documentation, while North American contract manufacturers optimize for beta-glucan consistency at mid-tier price points.
Pricing Analysis
Short lead-time premiums separate emergency procurement from contract-based offtake arrangements, with Japanese and South Korean subscription platforms capturing 12-18 month replenishment commitments at standard rates. Three-tier pricing structure across premium, standard, and economy levels reflects certification stacking intensity, with dual USDA-EU Organic labels commanding top positioning. Cost compression in powder segments intensifies as submerged fermentation systems democratize beta-glucan standardization. Retail consumers in Southeast Asian mass markets exhibit highest price sensitivity, while German compounding pharmacies demonstrate lowest sensitivity due to protocol-driven specification adherence.
Supply Chain Analysis
Dual certification timelines for USDA Organic and EU Organic labels gate supplier eligibility, freezing working capital through 18-24 month field conversion periods that constrain mid-tier entrants. Supply concentrates in China, Japan, and South Korea, with extraction houses drawing from hardwood sawdust, liquid fermentation media, and activated carbon filtration systems. Single-source vulnerability runs through Zhejiang province's drying operation concentration, where NMPA's GB 2762-2022 relocations are fragmenting legacy capacity. Distribution runs through direct-to-consumer platforms in East Asia and telehealth-integrated dispensaries in German-speaking markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's NMPA solvent residue limits and dual carbon goals erect compliance moats that favor extraction houses with activated carbon filtration and renewable energy credentials, marginalizing unretrofitted competitors.
For Market Incumbents: Deepen backward integration into Fujian and Jiangxi cultivation sites as coastal Zhejiang facilities face drying operation relocations under GB 2762-2022. Fortify practitioner channel relationships through telehealth-integrated dispensary partnerships in Germany and Switzerland, where subscription infrastructure captures lifetime value from compliance-demonstrated cohorts and defends margin pools against mycelial biomass substitution. For New Entrants and Emerging Players: Launch via direct-to-practitioner channels in North America, where telehealth-integrated supplement dispensaries bypass retail markup and tolerate premium positioning for certified organic extracts. Target personalized nutrition protocols in German and Swiss compounding pharmacies as the most penetrable application segment, leveraging liquid format adaptability for adaptogenic stack customization. For Investors and Strategic Acquirers: MFDS streamlined health claim substantiation for polysaccharide extracts is the leading indicator that Seoul-directed formulation partnerships will concentrate procurement power among Japanese and Chinese suppliers with established MFDS dossier experience. Acquisition targets should demonstrate captive cultivation with renewable energy credentials and existing dual certification timelines in progress. Watch for NMPA enforcement actions against extraction solvent residue violations as the signal for compliance-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | USDA-EU Organic stacking captures premium positioning in practitioner-directed channels while freezing competitor working capital. |
| Submerged Fermentation Scale-Up | Pharmaceutical-grade bioreactor controls secure consistent triterpenoid profiles regardless of harvest seasonality for North American formulators. |
| Renewable Energy Retrofit | Hokkaido cultivation sites with certified renewable credentials capture EU CSRD first-mover advantage in carbon footprint disclosure. |
| Telehealth Platform Integration | Direct-to-practitioner dispensaries in Germany and Switzerland bypass brick-and-shelf intermediaries to retain margin previously lost to retail markup. |
| MFDS Dossier Development | Seoul-directed formulation partnerships accelerate as South Korea's functional food certification expansion pulls Japanese and Chinese suppliers. |
Study Parameters
Trade databases, NMPA regulatory filings, and EFSA novel food approval records formed the secondary backbone, supplemented by customs data from Zhejiang and Fujian export corridors. Primary interviews with extraction house quality control directors, dietary supplement brand formulation managers, and German compounding pharmacy procurement officers validated supply chain fragmentation patterns. Bottom-up volume modeling across powder, extract, capsule, and liquid formats triangulated against top-down category spend analysis from subscription platform disclosures.
Historical trendline analysis of cultivation facility investment patterns and extraction technology adoption curves anchored the projection framework across the analysis window. Segmentation dimensions included product format, application channel, distribution model, and end-user sophistication tier, with CAGRs derived from penetration rate modeling in subscription wellness platforms and practitioner-directed procurement channels. Forecast inputs incorporated NMPA enforcement intensity scenarios and EFSA mycelium-versus-fruiting-body labeling clarification timelines.
Regulatory enforcement variance, substrate cost volatility tied to construction cycles, and mycelial biomass substitution acceleration are the dominant revision risks that could compress or expand addressable market boundaries. Stakeholders should weight assumptions against their own operating context and certification pipeline status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Cordyceps Militaris Market
Specialty Foods
Soft Tofu Market
Specialty Foods
Therapeutic Dog Food Market
Specialty Foods
Cat Food Flavors Market
Specialty Foods
Non-GMO Food Products Market
Specialty Foods
Curculin Market
Specialty Foods
Global Truffle Market
Specialty Foods
Cannabis Infused Drinks Market
Specialty Foods
Low Calorie Vegetable Dip Market
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
Global Pine Pollen Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Vegan Dressing Market
Specialty Foods
Moringa Products Market
Specialty Foods
Guacamole Market
Specialty Foods
Low Calorie Popsicles Market