
 Healthy Low-Fat Desserts Market | 2026-2036
Healthy Low-Fat Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
Healthy Low-Fat Desserts Market Foresight
Plant-based dairy is decoupling healthy low-fat desserts from traditional milkfat economics, enabling cost structures that compete with conventional formulations. Unilever leverages its global ice cream infrastructure to distribute oat- and almond-based frozen desserts across multiple continents. Halo Top Creamery specializes in high-protein, low-calorie pints that anchor its presence in grocery freezer sections. Nestlé competes through controlled supply chains for natural sweeteners that reduce added sugar claims.
Healthy low-fat desserts constitute formulated food products containing less than three grams of fat per serving, achieved through emulsifier systems, hydrocolloid stabilizers, and alternative lipid sources that replicate mouthfeel without caloric density; they serve commercial and retail channels seeking permissible indulgence within dietary constraint frameworks. Frozen desserts lead volume across distribution channels, while yogurt alternatives capture the fastest expansion as refrigerated probiotic formats displace traditional dairy snacks. Plant-based dairy ingredients concentrate margin pools where oat and pea protein extraction technologies command premium positioning against commodity soy isolates.
The FDA enforces Nutrition Facts panel requirements for added sugars disclosure, compelling reformulation toward organic sweeteners and natural flavorings that maintain palatability under reduced-fat parameters. The USDA Organic seal and Non-GMO Project verification create tiered market access where certified products command shelf space in health food shops and specialty stores. Stakeholders must monitor evolving clean-label definitions as regulatory bodies tighten permissible ingredient declarations and consumers scrutinize emulsifier sourcing.
Market Dynamics
FDA-mandated added sugar disclosure on Nutrition Facts panels is forcing wholesale reformulation across frozen novelties and refrigerated desserts, compressing formulation cycles and elevating clean-label ingredient costs.
Growth Catalysts
- Clean-label mandates:The FDA's updated Nutrition Facts requirements for added sugars push manufacturers toward organic sweeteners and natural flavorings that maintain palatability under reduced-fat parameters.
- Diabetic population concentration:Elevated diabetic prevalence in the United States sustains premium positioning for reduced-fat frozen novelties and dairy-alternative puddings targeting glycemic management.
- Pea protein extraction:Advanced pea protein isolation technologies enable cost-competitive dairy alternatives that replicate mouthfeel without milkfat economics.
Market Restraints
- Hydrocolloid cost volatility:Guar and locust bean gum prices fluctuate with Indian monsoon patterns, destabilizing emulsifier budgets for texture-critical formulations.
- Oat milk supply concentration:Nordic and Canadian oat processing infrastructure limits scalable sourcing for mass-market frozen dessert expansion.
- Technical mouthfeel ceiling:Current stabilizer systems cannot replicate the full fat bloom and meltdown profile of premium ice cream above 15% overrun.
Strategic Opportunities
- Probiotic yogurt alternatives:Refrigerated plant-based formats with live cultures capture fastest-expansion positioning as functional snacks displace traditional dairy.
- USDA Organic certification:The USDA Organic seal creates tiered shelf access where certified products command placement in health food shops and specialty retail.
- Direct-to-frozen distribution:E-commerce cold-chain investments enable subscription models for pint-sized novelties bypassing traditional grocery slotting fees.
Industry Challenges
- Clean-label emulsifier sourcing:Consumer scrutiny of mono- and diglyceride origins complicates supplier qualification timelines for Non-GMO Project verification.
- Refrigerated logistics capex:Cold-chain infrastructure requirements for probiotic formats demand capital deployment that mid-tier brands cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthy Low-Fat Desserts Market |
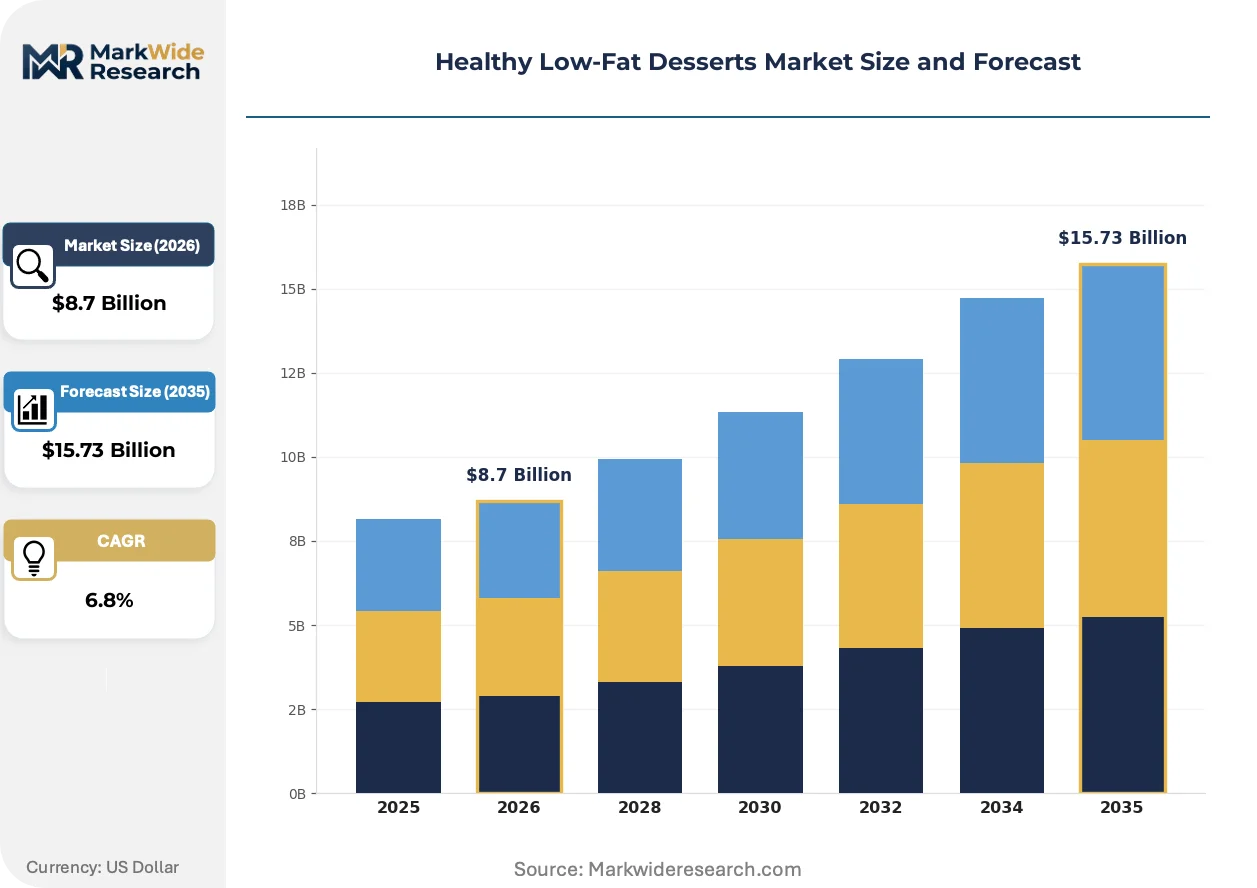
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Desserts, Baked Goods, Puddings, Yogurt Alternatives Ingredient Type: Organic Sweeteners, Plant-Based Dairy, Gluten-Free Flours, Natural Flavorings Distribution Channel: Online Retailers, Grocery Stores, Health Food Shops, Specialty Stores End User: Health Conscious Consumers, Athletes, Diabetics, Weight Watchers |
| Companies Covered | Unilever, Nestlé, Halo Top Creamery, Mars, Mondelez International, Chobani, General Mills, Post Holdings, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthy Low-Fat Desserts Market Shifts & Advancements
Formulation science and regulatory disclosure requirements are converging to reshape permissible indulgence, with texture replication and transparent sourcing now co-equal priorities for product development teams.
Precision fermentation of dairy proteins is automating the production of functional whey and casein equivalents without animal agriculture. Ingredient technology firms license these proteins to frozen dessert manufacturers seeking identical meltdown characteristics. The technology is automating cost parity between conventional and alternative lipid systems.
REACH registration requirements for novel food-contact substances in the European Union extend safety documentation timelines for imported emulsifier innovations. Manufacturers must submit comprehensive toxicological dossiers before commercial deployment. Frozen dessert exporters to Germany and France front-load compliance costs into NPD budgets.
Gym-centric consumption occasions now drive single-serve packaging formats with macro-nutrient callouts. Fitness-oriented buyers scan freezer sections for protein-per-calorie ratios rather than brand loyalty. This behavior concentrates in United States coastal metropolitan markets where health club density correlates with premium SKU velocity.
Healthy Low-Fat Desserts Market Segmentation
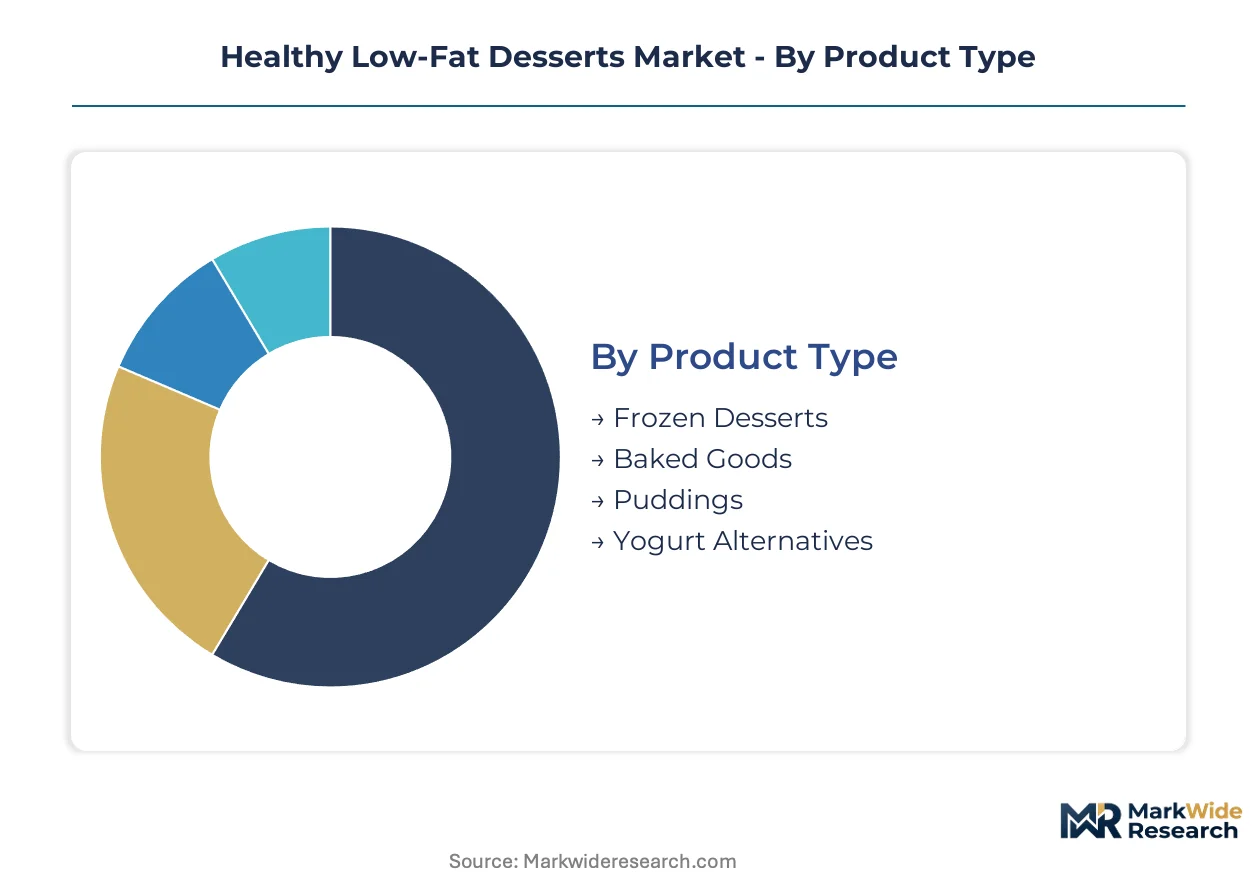
Segmentation in healthy low-fat desserts reveals how certification requirements, ingredient sourcing constraints, and channel access rules reshape competitive positioning across product formats. Manufacturers navigate tiered compliance burdens that segment profitability and shelf access.
Product Type:
FDA Nutrition Facts disclosure mandates and USDA Organic certification requirements vary sharply across frozen versus refrigerated formats, altering reformulation timelines and clean-label investment thresholds.
- Frozen Desserts:Ice cream novelties and frozen bars rely on hydrocolloid stabilizers and alternative lipid systems to replicate fat bloom and meltdown profiles under three grams fat per serving. Demand concentrates in United States metropolitan markets where health club density correlates with premium SKU velocity for high-protein, low-calorie pints.
- Yogurt Alternatives:Refrigerated plant-based formats with live probiotic cultures capture functional snack positioning through controlled cold-chain distribution. Expansion accelerates in coastal United States cities where dairy displacement and glycemic management drive repeat purchase.
- Baked Goods:Muffins, cookies, and cakes utilize gluten-free flours and emulsifier systems to achieve moisture retention without butter or shortening economics.
- Puddings:Dairy-alternative cups and refrigerated cups target diabetic consumers through natural sweetener formulations with reduced glycemic impact.
Frozen Desserts sits at the top of the volume ranking, with Yogurt Alternatives climbing the fastest.
Ingredient Type:
Cost tier separation between commodity inputs and certified alternatives determines margin architecture, with extraction technology maturity dictating price competitiveness against conventional formulations.
- Plant-Based Dairy:Oat and almond protein isolates, alongside pea protein extractions, enable mouthfeel replication without milkfat dependency. Nordic and Canadian oat processing infrastructure constrains scalable sourcing for mass-market expansion.
- Organic Sweeteners:Stevia, monk fruit, and allulose formulations satisfy FDA added sugar disclosure rules while maintaining palatability under reduced-fat parameters. United States diabetic prevalence sustains premium positioning for glycemic-neutral dessert applications.
- Natural Flavorings:Clean-label extracts and essential oils replace artificial flavor systems to meet Non-GMO Project verification standards.
- Gluten-Free Flours:Rice, tapioca, and almond meal blends serve celiac and grain-avoidant consumers through modified starch systems.
Plant-Based Dairy commands the largest volume share, with Organic Sweeteners expanding most quickly as reformulation accelerates.
Distribution Channel:
Customer type concentration varies by channel access rules, with certification tiers determining placement in mainstream grocery versus specialty retail environments.
- Grocery Stores:National freezer and refrigerated case placement requires slotting fee negotiations and velocity guarantees for pint-sized novelties. United States supermarket chains dominate volume through promotional calendar alignment with resolution-season demand spikes.
- Online Retailers:Direct-to-frozen subscription models bypass traditional grocery gatekeeping through cold-chain logistics investments. E-commerce penetration concentrates in United States urban corridors with same-day delivery infrastructure.
- Health Food Shops:Independent retailers prioritize USDA Organic and Non-GMO Project verified SKUs with transparent emulsifier sourcing documentation.
- Specialty Stores:Gourmet and natural product boutiques command premium pricing for limited-batch formulations with exotic flavor profiles.
Grocery Stores anchor volume throughput, with Online Retailers gaining share fastest as cold-chain reliability improves.
End User:
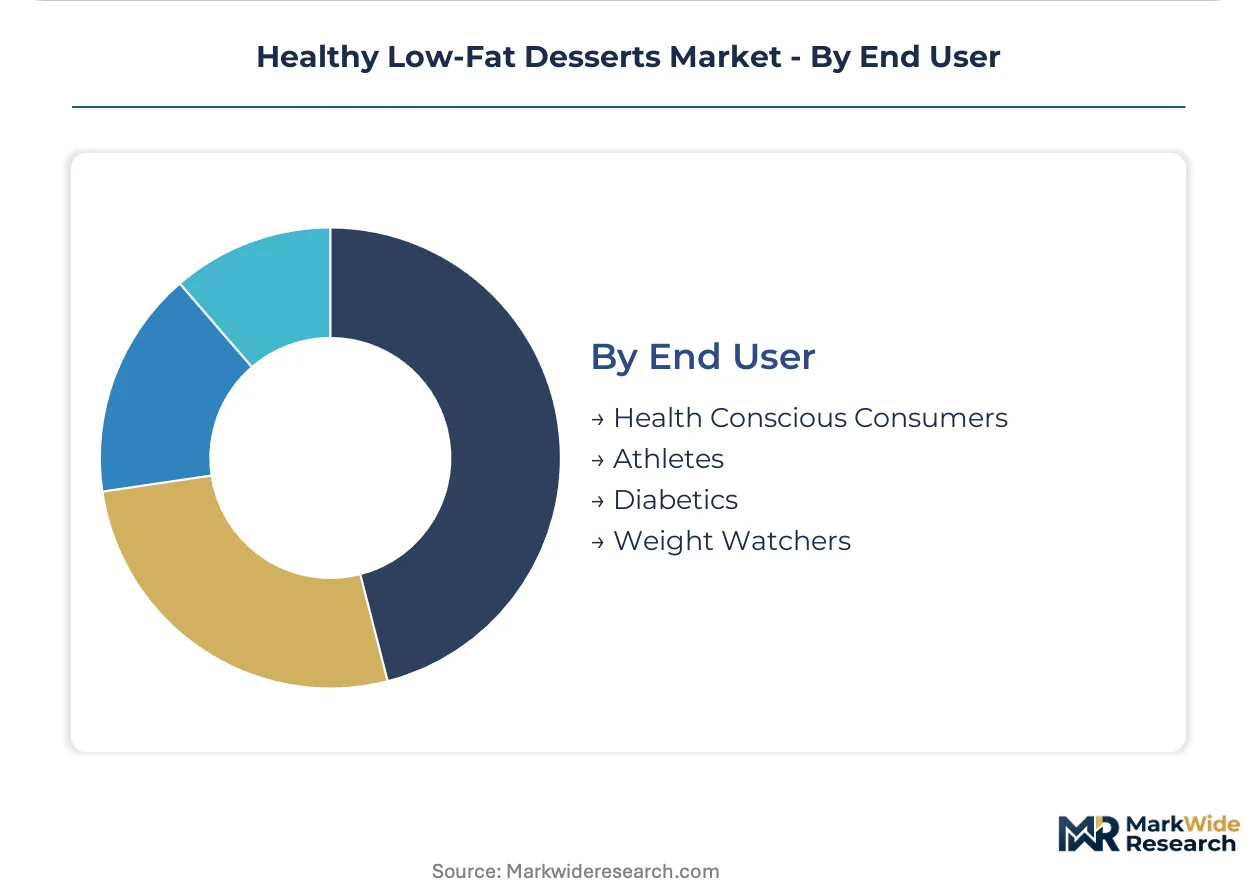
Application-specific nutritional requirements drive formulation divergence, with macro-nutrient callouts and glycemic indices shaping package design and marketing claims.
- Health Conscious Consumers:General wellness seekers prioritize clean-label ingredient decks and permissible indulgence positioning across all product formats. United States coastal metropolitan markets show highest per-capita spending on reduced-fat frozen novelties.
- Diabetics:Glycemic management requirements mandate specific sweetener systems and carbohydrate disclosure precision. Medical nutrition positioning supports premium pricing in pharmacy and clinic-adjacent retail channels.
- Athletes:Protein-per-calorie ratios and post-workout recovery framing drive single-serve packaging formats with macro-nutrient callouts.
- Weight Watchers:Calorie-controlled portion formats align with commercial diet program point systems and behavioral tracking applications.
Health Conscious Consumers represent the largest addressable base, with Diabetics showing the steepest expansion trajectory as prevalence rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States metropolitan markets anchor category volume through health club density and diabetic prevalence clusters that sustain premium positioning for reduced-fat frozen novelties.
United States
Fitness-oriented consumers in coastal cities drive single-serve packaging formats with macro-nutrient callouts. FDA added sugar disclosure mandates compress formulation cycles for frozen dessert manufacturers. Chicago and Los Angeles freezer case velocity concentrates premium SKU distribution for high-protein, low-calorie pints.
Germany
REACH registration requirements for novel food-contact substances extend safety documentation timelines for imported emulsifier innovations. EFSA clean-label scrutiny elevates organic sweetener adoption in reduced-fat formulations. Berlin and Hamburg health food retail clusters command Non-GMO Project verified placement for oat-based frozen desserts.
United Kingdom
Gym-centric consumption occasions reshape post-workout recovery snacking patterns in Greater London. FSA allergen labeling enforcement tightens ingredient declaration precision for dairy-alternative puddings. Manchester and Birmingham distribution hubs channel probiotic yogurt alternatives through controlled cold-chain networks.
Canada
Health Canada nutrition labeling regulations align with FDA added sugar disclosure frameworks, driving cross-border formulation standardization. Prairie oat processing infrastructure supplies raw material inputs for North American frozen dessert expansion. Toronto and Vancouver metropolitan markets concentrate diabetic consumer demand for glycemic-neutral dessert applications.
Australia
TGA complementary medicine frameworks influence functional positioning for probiotic refrigerated formats. Sydney and Melbourne fitness culture sustains protein-per-calorie ratio scanning behavior in freezer sections. Queensland dairy-alternative manufacturing clusters leverage pea protein extraction technologies for cost-competitive mouthfeel replication.
Healthy Low-Fat Desserts Market Competitive Landscape
Global majors compete with regional champions across distribution infrastructure and clean-label certification tiers. The vendor base stratifies between multinational CPG conglomerates with captive cold-chain networks and specialized challengers targeting fitness-oriented micro-segments. Three archetypes dominate: scale-driven freezer case incumbents, plant-based dairy specialists, and functional nutrition formulators. Competitive moves concentrate on M&A for natural sweetener supply chains and direct-to-frozen e-commerce capacity deployment.
Within the scale-driven tier, Unilever and Nestlé occupy positions defined by global ice cream infrastructure and controlled supply chains for natural sweeteners. Halo Top Creamery exemplifies the functional nutrition archetype through high-protein, low-calorie pint specialization that anchors grocery freezer section presence.
| Leading Market Players |
|---|
| Unilever |
| Nestlé |
| Halo Top Creamery |
| Mars |
| Mondelez International |
| Chobani |
| General Mills |
| Post Holdings |
| Danone |
| Others |
Supply & Pricing Matrix
Non-GMO Project verification gates qualified supply and premium-tier pricing access, as manufacturers sourcing emulsifiers from traceable origins absorb documentation costs that commodity suppliers cannot match. FDA added sugar disclosure mandates compress formulation timelines, forcing buyers to pay certification premiums or risk shelf-space disqualification.
Pricing Analysis
Input-cost pass-through from hydrocolloid volatility shapes tiered pricing across frozen dessert formats. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified pints from conventional reduced-fat novelties and private-label economy tubs. Price differentiation hinges on clean-label certification grade and cold-chain delivery infrastructure. Pricing pressure stems from Indian monsoon-driven guar gum cost spikes. Diabetic consumers show least price sensitivity for glycemic-neutral formulations, while mass-market weight watchers drive economy-tier volume.
Supply Chain Analysis
Reverse-logistics for temperature-compromised probiotic yogurt alternatives demands specialized cold-chain recovery networks that frozen dessert distributors rarely maintain. Raw material sourcing concentrates in Canada for oat protein isolates, India for guar and locust bean gum extraction, and Nordic regions for pea protein processing. Formulation draws from hydrocolloid stabilizers, alternative lipid systems, and natural sweetener inputs. Single-source vulnerability runs through concentrated Nordic oat milling infrastructure. Distribution runs through controlled cold-chain partnerships linking prairie processing hubs to coastal metropolitan freezer cases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between United States premium pricing power and Canadian raw material cost advantages, with Health Canada-FDA labeling alignment enabling cross-border formulation standardization.
For Market Incumbents: Hedge hydrocolloid cost exposure through backward integration into pea protein extraction or long-term offtake agreements with Nordic oat processors. Defend freezer case positioning by accelerating Non-GMO Project verification timelines before clean-label scrutiny tightens emulsifier sourcing standards. Channel control through direct-to-frozen subscription infrastructure insulates against grocery slotting fee inflation.
For New Entrants and Emerging Players: Capture probiotic yogurt alternative white space in United States coastal cities where refrigerated logistics gaps limit incumbent response speed. Target diabetic consumer micro-segments through pharmacy-adjacent retail channels with glycemic index callouts. Go-to-market leverage rests on precision-fermented protein licensing that shortcuts texture replication R&D cycles.
For Investors and Strategic Acquirers: Roll-up economics work for regional plant-based dairy specialists because fragmented cold-chain infrastructure prevents national scale without acquisition-led consolidation. Long-term viability centers on captive natural sweetener supply chains and USDA Organic certification assets. Watch FDA clean-label enforcement intensity as the signal for margin compression inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Licensing | Automates cost parity between conventional and alternative lipid systems for frozen dessert manufacturers. |
| Direct-to-Frozen E-Commerce Buildout | Bypasses grocery slotting fees through cold-chain subscription infrastructure in United States urban corridors. |
| USDA Organic Certification Acceleration | Secures tiered shelf access in health food retail channels before clean-label definitions tighten further. |
| Pea Protein Extraction Capacity Expansion | Reduces dependency on Nordic oat supply concentration for mass-market frozen dessert scaling. |
| Probiotic Cold-Chain Partnership | Enables functional yogurt alternative distribution through controlled logistics networks in coastal metropolitan markets. |
Research Methodology
Coverage spans North America and Western Europe, with primary inputs from each region combining formulation scientist interviews, retail category buyer discussions, and cold-chain logistics operator consultations. Secondary validation draws from FDA guidance documents, USDA Organic certification databases, Nielsen retail audit data, and trade customs records for hydrocolloid imports. Bottom-up SKU velocity analysis triangulates against top-down manufacturer capacity disclosures.
Granularity-level modeling extends to product type, ingredient certification tier, distribution channel, and end-user nutritional requirement dimensions. CAGRs derive from segment-level volume trajectory analysis cross-referenced with pricing trend assumptions. Forecast inputs incorporate diabetic prevalence clustering data, health club density metrics, and regulatory compliance timeline projections across the analysis window.
Monsoon pattern disruption, FDA clean-label enforcement acceleration, and precision fermentation cost curve shifts are the dominant revision risks. Forecasts reflect assumptions about emulsifier supply stability and certification standard evolution. Practitioners should monitor Indian agricultural output reports, FDA guidance release schedules, and synthetic biology partnership announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Cultures Market
Specialty Foods
Guacamole Market
Specialty Foods
Tunisia Couscous Market
Specialty Foods
Manuka Honey Market
Specialty Foods
Heat-Stable Fruit Fillings Market
Specialty Foods
Low Fat and Low Carb Foods Market
Specialty Foods
Silver Food Market
Specialty Foods
High Protein Cat Food Market
Specialty Foods
Sea Moss Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Areca Bowl Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Cannabis Infused Drinks Market
Specialty Foods
Global Honey Market
Specialty Foods
Global Bee Products Market
Specialty Foods
Moringa Products Market