
 Guacamole Market | 2026-2036
Guacamole Market Size, Share, and Industry Trends Forecast 2026-2036
Guacamole Market Intelligence
Mexican avocado packers is restructuring processing capacity to serve North American retail and foodservice contracts with greater speed. Sabra Dipping Company leverages refrigerated distribution networks to sustain brand presence across U.S. club and conventional grocery channels. Westfalia Fruit anchors supply security through integrated orchard ownership in Michoacán and Jalisco. Calavo Growers competes on scale, operating multiple processing facilities that handle volume contracts for private-label and branded guacamole programs.
Guacamole is an avocado-based preparation, typically containing mashed Hass avocado flesh combined with lime juice, salt, and varying proportions of onion, tomato, and chili, with a finished pH below 4.6 to inhibit microbial growth and extend refrigerated shelf life. The product serves as a ready-to-eat condiment, dip, and ingredient in commercial food manufacturing and foodservice operations. Chunky and smooth formats dominate retail velocity, while organic variants command margin premiums in premium and mid-range price tiers. Pouches and plastic tubs are displacing glass jars in convenience-oriented channels, reflecting logistics efficiency and breakage reduction priorities.
The U.S. FDA enforces hazard analysis and preventive controls for human food under FSMA, requiring foreign supplier verification programs that directly affect Mexican avocado processors exporting to American buyers. Mexico's national agricultural health authority, SENASICA, coordinates phytosanitary certification for fresh avocado movement, creating bilateral compliance obligations for cross-border guacamole ingredient flows. Stakeholders must monitor evolving traceability mandates and cold-chain integrity standards that will determine market access eligibility for imported and domestically processed products.
Market Dynamics
FSMA-mandated foreign supplier verification programs are restructuring how Mexican avocado processors qualify for U.S. market access, forcing bilateral compliance investments that favor scaled operators with dedicated regulatory affairs capacity.
Growth Catalysts
- Hispanic population expansion:Demographic concentration in Texas, California, and Florida sustains per-capita consumption premiums that outpace general population snack category growth.
- High-pressure processing (HPP):Cold-pasteurization technology extends refrigerated shelf life without thermal degradation, enabling wider retail distribution radii from centralized production.
- Foodservice menu proliferation:Fast-casual chains embed guacamole as a standard condiment option, normalizing consumption occasions beyond traditional Mexican cuisine contexts.
Market Restraints
- Input cost volatility:Hass avocado pricing swings with Michoacán harvest cycles and California drought conditions, compressing processor margins during supply contractions.
- Supply concentration risk:Michoacán state supplies roughly four-fifths of U.S. import volume, creating single-point vulnerability to climate events or organized labor disruptions.
- Regulatory friction:SENASICA phytosanitary certification delays at Lázaro Cárdenas port facilities extend inventory transit times and working capital cycles.
Strategic Opportunities
- Underpenetrated European markets:United Kingdom and German retail channels show accelerating velocity for chilled dips, with avocado familiarity rising through sushi and wellness cuisine exposure.
- Regulatory tailwind:USDA organic certification commands shelf-space allocations and margin premiums in premium grocery channels, rewarding dedicated organic supply chain investments.
- Direct-to-foodservice distribution:Bypassing broadline distributors through refrigerated last-mile partnerships captures margin otherwise lost to warehousing markups.
Industry Challenges
- Food safety certification timelines:Third-party audit requirements under SQF or BRCGS standards demand 12-18 month implementation cycles that delay new facility commissioning.
- Cold-chain integrity maintenance:Temperature excursion risks during cross-border trucking require real-time monitoring infrastructure investments that strain mid-scale processor capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guacamole Market |
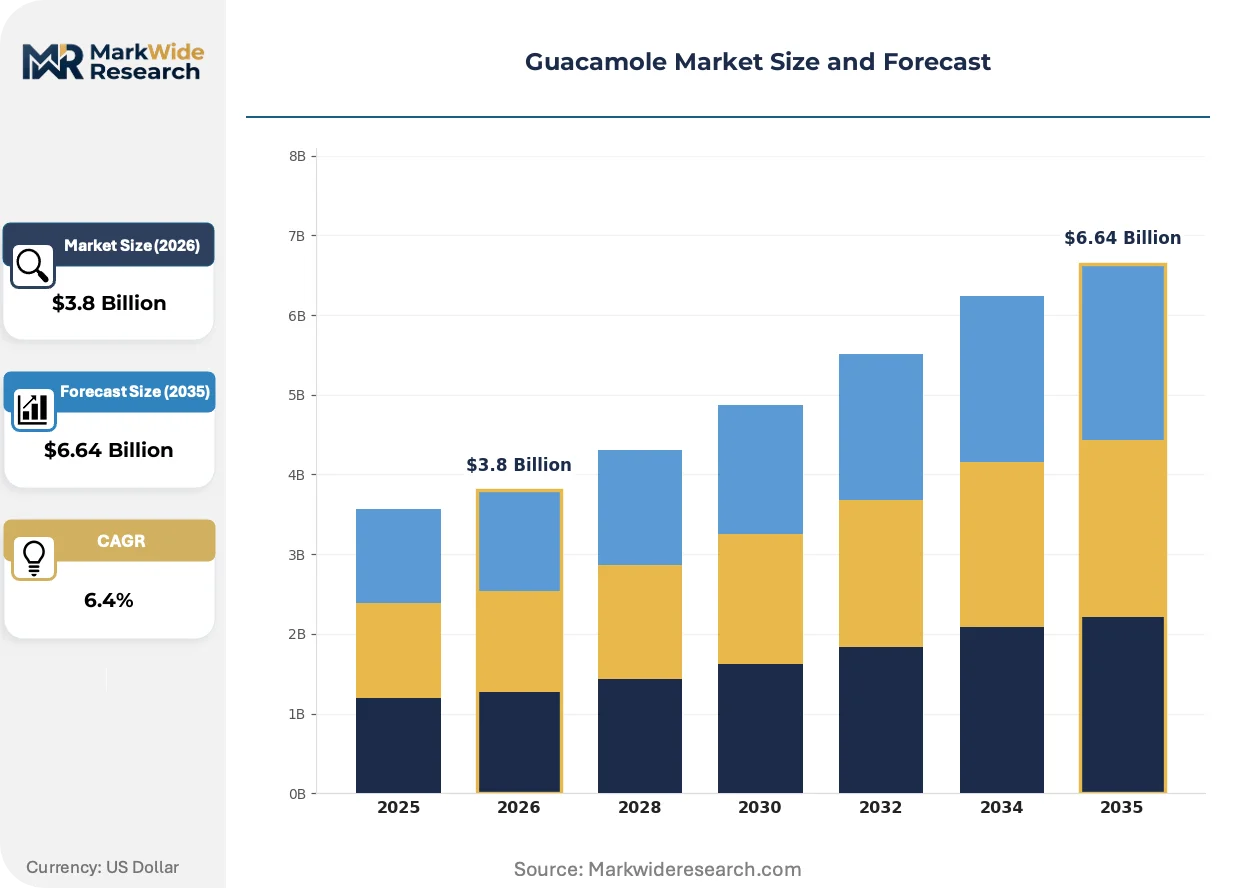
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chunky, Smooth, Organic, Spicy Packaging Type: Glass Jar, Plastic Tub, Sachets, Pouches Distribution Channel: Online, Supermarkets, Convenience Stores, Restaurants Price Tier: Premium, Mid-Range, Budget, Value Pack |
| Companies Covered | Sabra Dipping Company, LLC, Westfalia Fruit, Conagra Brands, Inc., Avo-King, MegaMex Foods, LLC., Hormel Foods Corporation, B&G Foods, Inc., Insignia International, Calavo Growers, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guacamole Market Strategic Shifts & Innovations
Processing technology and packaging formats are converging to extend shelf life while reducing environmental footprint, with regulatory pressure accelerating adoption curves beyond typical capital replacement cycles.
High-pressure processing (HPP) equipment is decentralizing guacamole production geography by eliminating the thermal pasteurization bottleneck that previously required centralized retort facilities. Regional processors in Jalisco and Baja California are installing HPP lines to serve West Coast foodservice accounts with 48-hour freshness windows. This technology is decentralizing supply chain risk away from Michoacán concentration while enabling smaller-batch production runs for private-label programs.
The FDA's Food Safety Modernization Act foreign supplier verification program imposes documentary burdens on Mexican exporters that favor vertically integrated packers with in-house laboratory testing capacity. Smaller processors without dedicated compliance staff face exclusion from branded retail contracts. U.S. import brokers are consolidating around specialists with SENASICA-certified documentation workflows, compressing the intermediary tier.
Club-store buyers are consolidating purchase volumes around fewer suppliers capable of delivering multi-SKU pallet programs spanning conventional, organic, and single-serve formats. This concentration is displacing fragmented distributor networks that previously aggregated regional processors. The shift is most visible in Texas and Arizona markets where Costco and Sam's Club account for disproportionate volume velocity.
Guacamole Market Segmentation
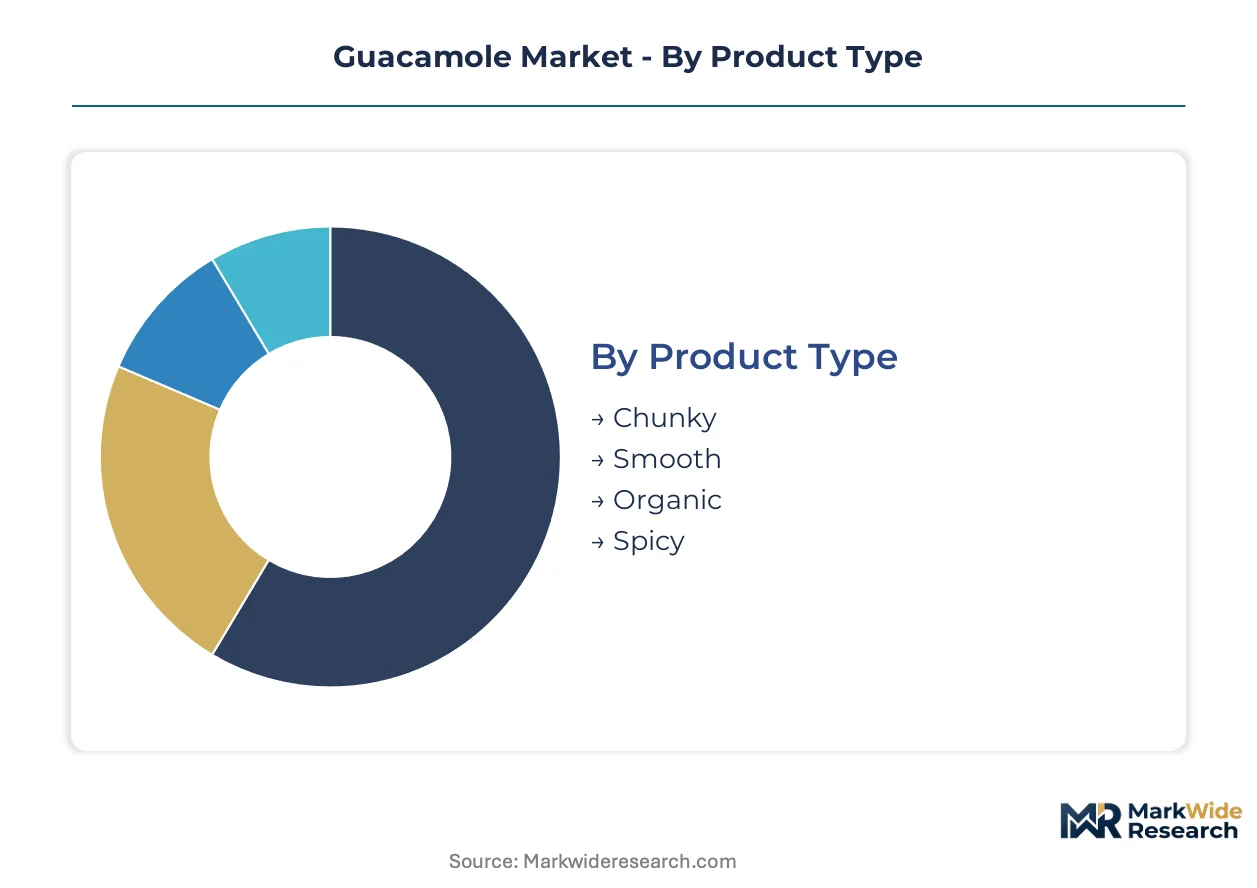
Guacamole processors structure product portfolios across texture, packaging, channel, and price positioning to capture distinct consumption occasions. Segmentation discipline separates foodservice volume contracts from retail margin opportunities while accommodating divergent cold-chain requirements.
Product Type:
Texture and ingredient certification define the primary product architecture, with format selection determining shelf-life extension methods and target channel placement.
- Chunky:Contains visible avocado pieces with coarse mash consistency and pH typically below 4.6 for microbial control. Foodservice accounts in Texas and California specify this format for bowl assembly and topping applications where texture integrity signals freshness.
- Smooth:Homogeneous puree consistency achieved through industrial milling enables uniform portioning for squeeze-bottle dispensing and manufacturing ingredient use. QSR chains prefer this format for operational speed and waste reduction.
- Organic:USDA-certified fruit from orchards meeting National Organic Program standards commands shelf-space allocations in premium grocery channels.
- Spicy:Jalapeño or serrano infusion targets Hispanic demographic concentration in Florida and southwestern states.
Chunky leads on scale; organic leads on momentum.
Packaging Type:
Material selection balances oxygen barrier performance, breakage risk, and logistics cube efficiency across divergent retail and foodservice handling environments.
- Plastic Tub:Polypropylene containers with modified atmosphere sealing dominate club-store and conventional grocery velocity. Costco and Sam's Club procurement specifications favor this format for pallet density and consumer refrigerator stackability.
- Pouches:Flexible film with fitment closures reduces freight cost per unit case and enables single-serve portioning for foodservice back-of-house efficiency.
- Glass Jar:Premium shelf presence in specialty retail persists despite breakage liability and weight penalties in distribution.
- Sachets:Portion-control packets serve airline, hospitality, and QSR condiment programs requiring extended ambient stability.
Plastic tub commands volume share; pouches gain share fastest in foodservice conversion.
Distribution Channel:
Channel strategy separates temperature-controlled direct delivery from ambient retail distribution, with margin capture varying by intermediary tier.
- Supermarkets:Conventional and organic SKUs compete for refrigerated case placement against hummus and salsa alternatives. Kroger and Albertsons banner negotiations determine regional distribution breadth.
- Restaurants:Direct-to-operator and broadline distributor routes serve fast-casual chains embedding guacamole as standard condiment options.
- Online:E-commerce penetration remains constrained by cold-chain fulfillment cost and perishability windows.
- Convenience Stores:Single-serve and snacking formats target immediate consumption occasions with limited refrigeration footprint.
Supermarkets anchor volume concentration; restaurants drive per-unit velocity expansion.
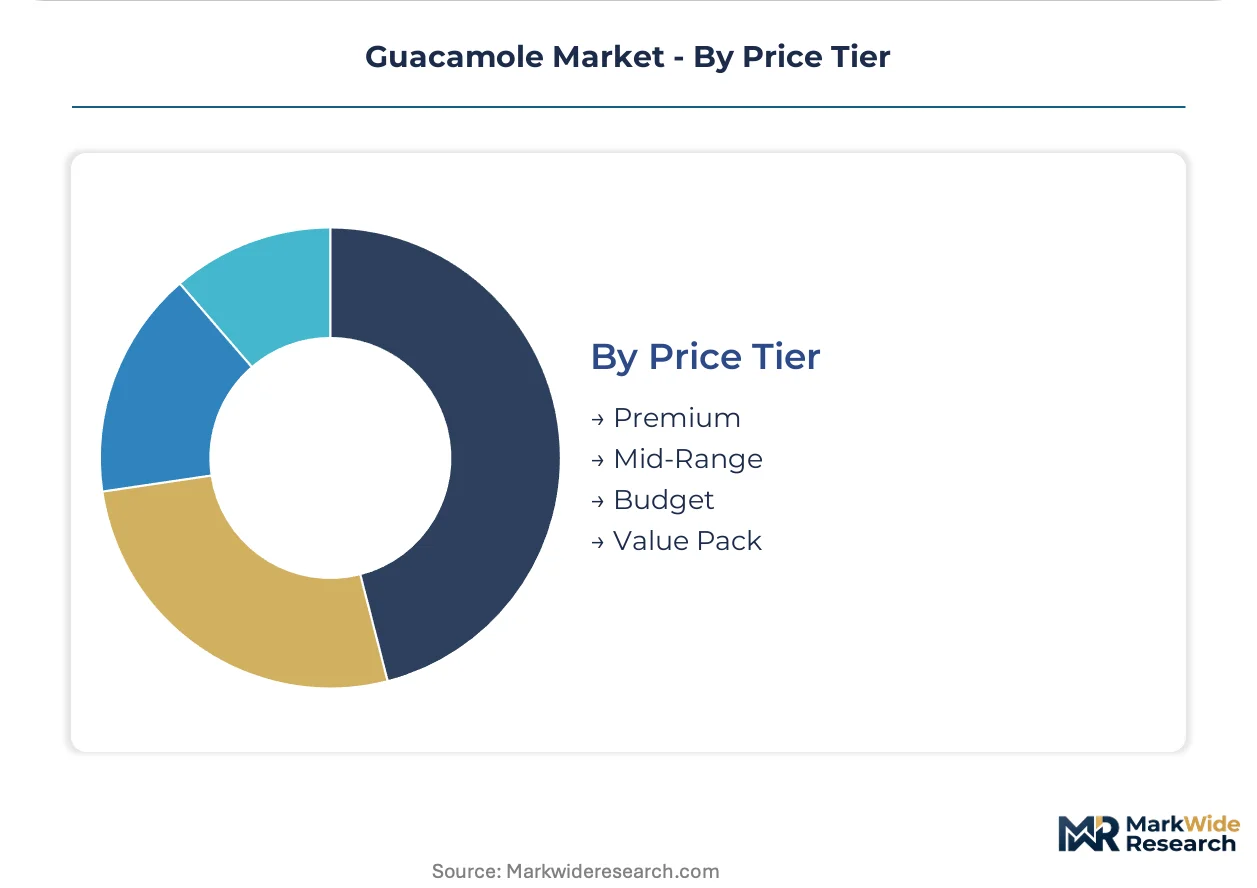
Price Tier:
Pricing architecture stratifies across ingredient provenance, organic certification, and packaging premiumization to segment willingness-to-pay across household income clusters.
- Premium:Organic certification, single-origin avocado sourcing, and HPP processing justify shelf-price positioning in Whole Foods Market and Sprouts Farmers Market channels.
- Mid-Range:Conventional Hass avocado base with standard pasteurization captures mainstream household penetration in conventional grocery.
- Budget:Value-engineered formulations with extended ingredient lists compete on price-per-ounce in price-sensitive retail banners.
- Value Pack:Multi-unit and club-size configurations reduce per-ounce cost for high-velocity households and small foodservice operators.
Mid-range holds volume dominance; premium tier climbs the fastest on organic conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping guacamole production geography. Mexican processors face escalating FDA compliance costs under FSMA foreign supplier verification programs, while U.S. operators absorb higher labor and avocado procurement expenses. This cost-of-compliance gap is driving facility investments and partnership structures that optimize border-adjacent capacity.
United States
Texas and California foodservice operators drive per-capita consumption premiums through fast-casual menu proliferation. The FDA enforces hazard analysis and preventive controls that require documented supply chain verification for Mexican-sourced avocado inputs. Processing clusters in Southern California and South Texas handle regional distribution for club-store and conventional grocery channels.
Mexico
Michoacán state supplies roughly four-fifths of U.S. import volume, creating concentrated production gravity around Uruapan and Peribán orchard zones. SENASICA coordinates phytosanitary certification for cross-border movement, with Lázaro Cárdenas port facilities serving as the primary export gateway. Jalisco processors are installing high-pressure processing lines to diversify supply geography away from Michoacán concentration.
Canada
Toronto and Vancouver metropolitan areas sustain refrigerated distribution demand for imported guacamole formats. Health Canada enforces food safety regulations aligned with FDA preventive controls frameworks, creating parallel compliance obligations for Mexican exporters. Club-store penetration in Ontario and British Columbia channels volume through consolidated supplier relationships.
United Kingdom
London and Southeast England retail channels show accelerating velocity for chilled avocado dips as sushi and wellness cuisine exposure builds familiarity. The Food Standards Agency enforces retained EU hygiene regulations post-Brexit, with import documentation requirements affecting Mexican processor market access. Tesco and Sainsbury's banner negotiations determine distribution breadth for organic and conventional SKUs.
Germany
Berlin and Munich urban centers drive demand for premium organic guacamole through discounter and specialty retail channels. EFSA guidelines on novel food ingredients and maximum residue levels shape import qualification protocols for non-EU suppliers. Processing partnerships with Dutch distribution hubs enable refrigerated last-mile coverage across North Rhine-Westphalia and Bavaria.
Guacamole Market Key Industry Players
Mexican producers anchor the supply-base tier; U.S.-based processors and brand marketers hold the demand-capture tier. The vendor structure concentrates around vertically integrated orchard operators and refrigerated distribution specialists, with mid-scale processors facing exclusion from branded retail contracts due to compliance capacity gaps. Three archetypes dominate: integrated packers with captive supply, brand marketers with cold-chain logistics mastery, and private-label converters with scale manufacturing. Competitive intensity centers on SENASICA certification speed and HPP technology deployment.
Among U.S.-based brand marketers, Sabra Dipping Company and Conagra Brands occupy positions that exemplify refrigerated distribution network leverage. Mexican integrated operators include Westfalia Fruit and Calavo Growers, representing the orchard-ownership archetype that secures supply through Michoacán and Jalisco land holdings. These three companies illustrate the geographic split between demand-capture marketing and supply-base integration that defines competitive positioning.
| Leading Market Players |
|---|
| Sabra Dipping Company, LLC |
| Westfalia Fruit |
| Conagra Brands, Inc. |
| Avo-King |
| MegaMex Foods, LLC. |
| Hormel Foods Corporation |
| B&G Foods, Inc. |
| Insignia International |
| Calavo Growers, Inc. |
| Others |
Cost & Logistics Intelligence
Captive orchard ownership in Michoacán and Jalisco anchors supply security for integrated Mexican packers while simultaneously constraining pricing power for non-integrated processors dependent on spot avocado markets. This backward integration into upstream fruit production insulates Calavo Growers and Westfalia Fruit from Hass price volatility that compresses margins for competitors sourcing through third-party growers.
Pricing Analysis
Retailer markup layers dominate final shelf positioning, with club-store buyers extracting volume discounts that compress processor margins while conventional grocers accept narrower wholesale spreads for organic SKUs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and HPP processing investment. Cost compression in the budget tier intensifies because value-engineered formulations compete on price-per-ounce. Foodservice operators show least price sensitivity due to operational speed requirements, while mass-market retail banners drive hardest bargain negotiations.
Supply Chain Analysis
Seasonal labor availability in Michoacán orchard zones constrains harvest timing flexibility, forcing processors to align production campaigns with peak avocado maturity windows. Supply concentrates in Mexico, the United States, and Canada for North American consumption, with raw material flows drawing from Hass orchards, lime juice concentrate, and modified atmosphere packaging films. Single-source vulnerability to Michoacán climate events and organized labor disruptions threatens inventory continuity. Distribution runs through refrigerated cross-border trucking networks with real-time temperature monitoring, club-store direct delivery, and broadline foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
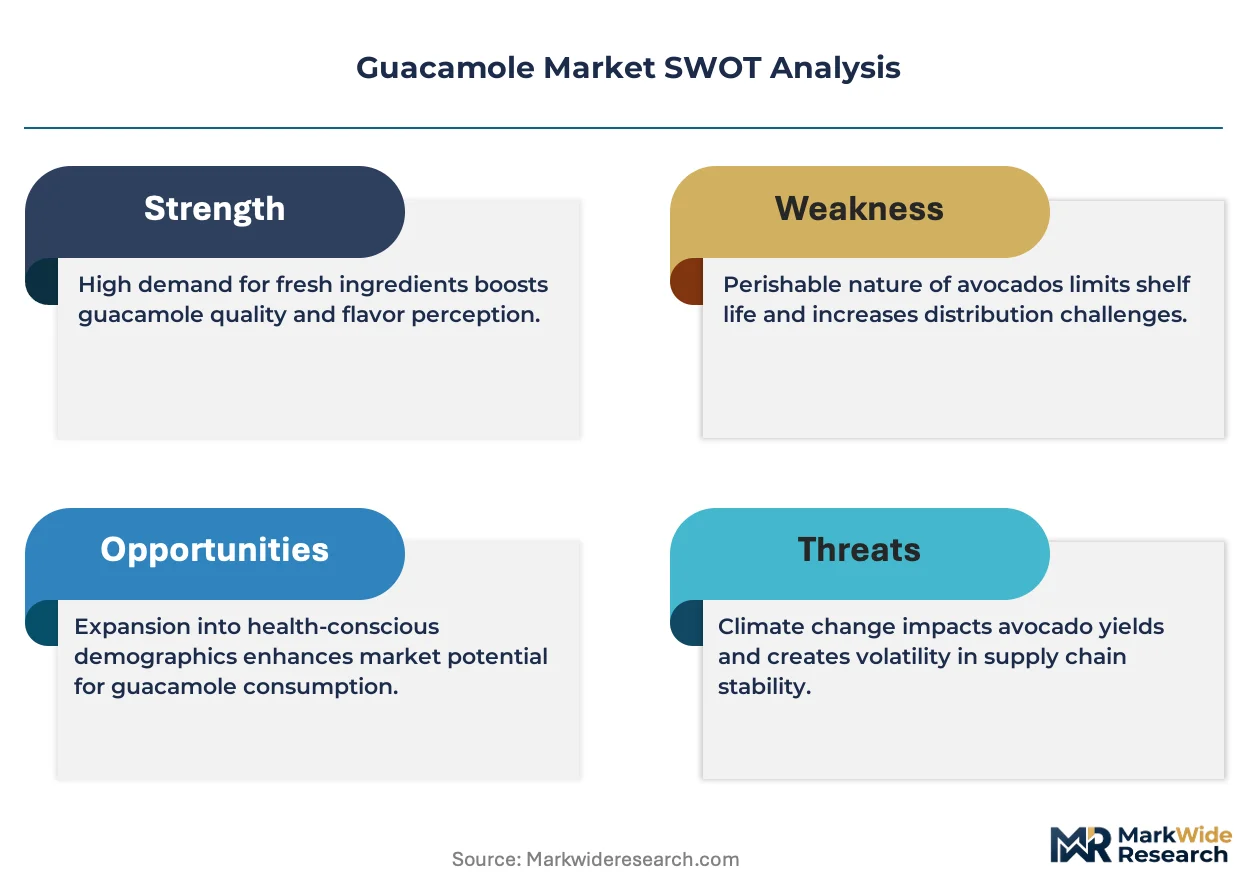
This market functions as a geographic-arbitrage play where FDA compliance costs in the United States diverge from SENASICA certification burdens in Mexico, creating facility-location incentives that favor border-adjacent processing investments.
For Market Incumbents: To counter HPP technology displacement of thermal pasteurization, accelerate high-pressure processing line deployment in Jalisco and Baja California to diversify supply geography away from Michoacán concentration. Deepen backward integration into certified organic orchard acreage to capture USDA premium shelf-space allocations and defend margin position against private-label converters.
For New Entrants and Emerging Players: Launch via direct-to-foodservice distribution partnerships that bypass broadline distributor markups, targeting fast-casual chains in Texas and California embedding guacamole as standard condiment options. White-space availability concentrates in organic private-label programs for European retail channels and single-serve pouch formats for airline hospitality programs.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale Mexican processors with SENASICA certification capacity because FDA foreign supplier verification program compliance barriers exclude fragmented competitors from branded retail contracts. Target acquisition archetypes include Jalisco-based HPP-equipped facilities and refrigerated distribution specialists with club-store pallet program capability. Monitor SENASICA certification speed at Lázaro Cárdenas as inflection indicator for working capital cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| HPP Technology Deployment | Cold-pasteurization adoption extends refrigerated shelf life without thermal degradation, enabling wider retail distribution radii. |
| Organic Certification Investment | USDA National Organic Program compliance commands premium shelf-space allocations in Whole Foods Market and Sprouts Farmers Market channels. |
| Direct-to-Foodservice Distribution | Refrigerated last-mile partnerships bypass broadline distributor markups, capturing margin otherwise lost to warehousing intermediaries. |
| Supply Geography Diversification | Jalisco and Baja California processing capacity reduces single-point vulnerability to Michoacán climate events and labor disruptions. |
| Club-Store Pallet Program Capability | Multi-SKU pallet configurations spanning conventional, organic, and single-serve formats secure volume consolidation with Costco and Sam's Club buyers. |
Research Approach
Multiple input streams — executive interviews with Mexican avocado packers and U.S. brand marketers, regulatory filing analysis, and trade flow documentation — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged processing facility managers, club-store category buyers, cold-chain logistics operators, and SENASICA certification specialists. Secondary validation drew from FDA FSMA guidance documents, USDA organic certification databases, U.S. Customs avocado import records, and refrigerated transportation industry reports.
Historical volume trajectories were cross-referenced against panel input from procurement executives to anchor projection assumptions across the analysis window. Segmentation modeling incorporated texture format, packaging type, distribution channel, and price tier dimensions with organic certification status as an industry-specific overlay. CAGRs were derived from fitted trend analysis calibrated to Hass avocado harvest cycle patterns and foodservice menu penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SENASICA phytosanitary certification delays or organized labor disruptions in Michoacán orchard zones. Material deviation in FDA foreign supplier verification program enforcement intensity or California drought severity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
United States Tofu Market
Specialty Foods
Healthy Low-Fat Desserts Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Low Calorie Diet Meal Plan Market
Specialty Foods
Europe Halal Food and Beverage Market
Specialty Foods
Asia-Pacific Tofu Market
Specialty Foods
Vegan Salad Dressing Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Low Fat Hummus Market
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market
Specialty Foods
Vegan Dressing Market
Specialty Foods
Dog Food Toppers Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Super Foods Market