
 Low Calorie Vegetable Dip Market | 2026-2036
Low Calorie Vegetable Dip Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Vegetable Dip Market Analytics
Asset-light co-manufacturing partnerships are reshaping competitive dynamics in low calorie vegetable dips, allowing regional brands to scale without capital-intensive production facilities. Bolthouse Farms leverages its captive carrot supply chain to control input costs across guacamole and hummus lines. Chobani LLC anchors its position through Greek yogurt-based formulations that deliver protein claims with reduced fat content. Sabra Dipping Co. LLC dominates refrigerated deli placement in North American supermarkets through direct store delivery networks.
Low calorie vegetable dip comprises reduced-fat, reduced-calorie condiments formulated for raw vegetable consumption, typically achieving calorie reduction through modified starch systems, yogurt or legume bases, and controlled oil content below five grams per serving. The category serves retail consumers seeking convenient, portion-controlled snacking alternatives to traditional full-fat dips. Hummus leads volume contribution due to its established legume-based nutrition profile and extended shelf stability, while single-serve packs represent the fastest-growing packaging configuration as convenience retailers expand fresh perimeter offerings. Dairy-based formulations retain margin concentration in premium supermarket channels where protein fortification commands price premiums over standard vegetable oil emulsions.
FDA nutrition labeling requirements and USDA organic certification standards govern formulation claims and ingredient sourcing across the category, creating compliance barriers for imported products without domestic certification. The EU Green Deal and REACH chemical safety protocols additionally constrain preservative and additive palettes for brands seeking European market access. Stakeholders must monitor evolving front-of-pack labeling mandates and plant-based protein qualification criteria that will determine which formulations retain shelf space in consolidated retail environments.
Market Dynamics
Clean-label mandates from FDA and USDA are compressing formulation options while refrigerated perimeter expansion at major retailers pulls production capacity toward single-serve formats with shorter shelf lives and stricter cold-chain requirements.
Growth Catalysts
- USDA Organic Certification:Federal standards for organic ingredient sourcing create premium pricing tiers that reward domestic supply chain investments and lock out uncertified imports from mainstream retail placement.
- Grab-and-Go Fresh Programs:Foodservice operators at convenience retailers and corporate cafeterias are standardizing portion-controlled dip formats that reduce food waste and labor costs while driving repeat purchase frequency.
- Plant-Based Protein Qualification:Evolving FDA guidance on protein content claims is accelerating reformulation toward legume bases that meet threshold requirements for front-of-pack labeling advantages.
Market Restraints
- Input Cost Volatility:Chickpea and tahini supply disruptions from Middle Eastern growing regions transmit directly to hummus manufacturing margins with limited near-term substitution options.
- Refrigerated Distribution Concentration:Direct store delivery networks controlled by incumbent brands create shelf-access barriers for regional entrants lacking capital for temperature-controlled logistics infrastructure.
- Preservative Restrictions:REACH chemical safety protocols in Europe and clean-label demands in North America eliminate traditional shelf-life extenders, compressing distribution radius and increasing spoilage risk.
Strategic Opportunities
- Underpenetrated European Markets:Mediterranean-adjacent consumption habits in Spain and Italy present expansion targets where hummus penetration lags behind Northern Europe and North America.
- E-Commerce Cold-Chain Innovation:Insulated last-mile delivery partnerships with meal-kit providers and specialty grocers open direct-to-consumer channels bypassing traditional retail slotting fee structures.
- EU Green Deal Alignment:Carbon footprint reduction requirements for packaged foods create first-mover advantages for manufacturers with renewable energy sourcing and biodegradable packaging certifications.
Industry Challenges
- Refrigerated Logistics Talent Scarcity:Qualified cold-chain operations managers and route optimization specialists command premium compensation in tight labor markets, constraining regional expansion velocity.
- Dual Certification Timelines:Simultaneous pursuit of USDA Organic and Non-GMO Project verification extends product development cycles by 8-14 months, delaying revenue recognition for reformulated lines.
- Legacy Equipment Retrofit Costs:Existing dairy-based dip production lines require substantial capital expenditure for allergen segregation protocols before handling legume or nut-based formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Vegetable Dip Market |
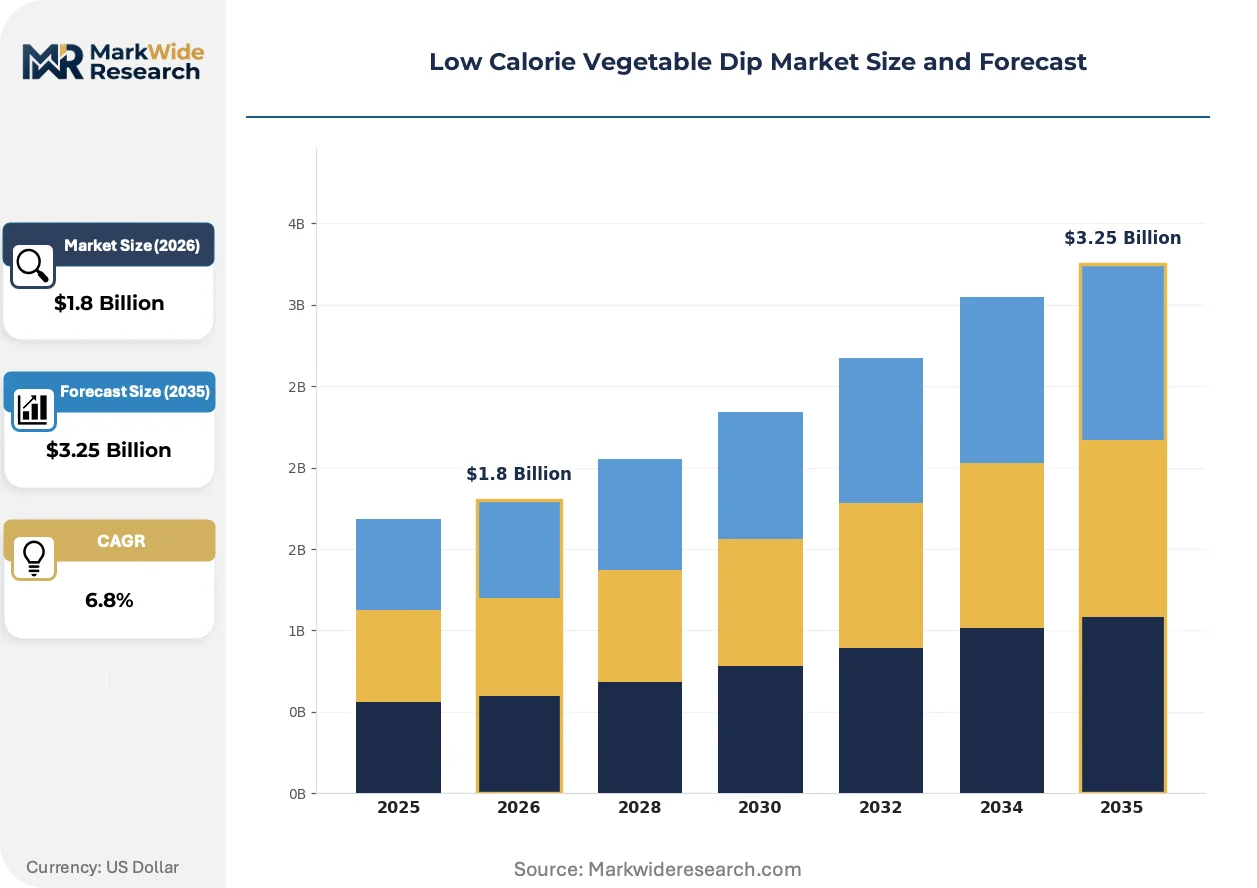
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hummus, Guacamole, Salsa, Tzatziki Ingredient Type: Legume-Based, Dairy, Avocado, Nut-Based Packaging Type: Pouches, Tubs, Jars, Single-Serve Packs Distribution Channel: Online Stores, Supermarkets, Convenience Stores, Specialty Shops |
| Companies Covered | Bolthouse Farms, Chobani LLC, General Mills Inc., Nestle S.A., PepsiCo Inc., Sabra Dipping Co. LLC, Good Foods Group LLC, Kite Hill, Hain Celestial Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Vegetable Dip Market Evolving Landscape
Digital formulation tools and precision fermentation are compressing traditional R&D timelines while regulatory clarity on novel ingredients opens protein diversification pathways previously blocked by GRAS uncertainty.
Modified starch systems derived from tapioca and potato sources are virtualizing the texture-building function previously delivered by dairy fats and vegetable oil emulsions. Clean-label-focused manufacturers at premium price tiers are adopting these systems to maintain mouthfeel while eliminating hydrogenated oils from ingredient decks. The technology is virtualizing the cost structure of reduced-fat formulation by reducing dependence on volatile dairy commodity markets.
REACH chemical safety protocols in Europe are systematically eliminating synthetic preservatives and artificial colorants from approved additive lists for food contact materials. Manufacturers seeking cross-border distribution must reformulate with cultured dextrose, vinegar derivatives, or high-pressure processing to achieve equivalent shelf stability. The policy shift most acutely affects imported brands from regions with permissive additive regulations, forcing facility investments or market withdrawal.
Corporate wellness programs and employer-subsidized snacking initiatives are consolidating procurement authority for office foodservice away from individual location managers toward centralized category managers. These buyers prioritize single-serve packaging with transparent nutrition panels and vendor sustainability scorecards over traditional bulk formats. The behavioral shift concentrates demand in United States metropolitan corridors with dense professional services employment.
Low Calorie Vegetable Dip Market Segmentation
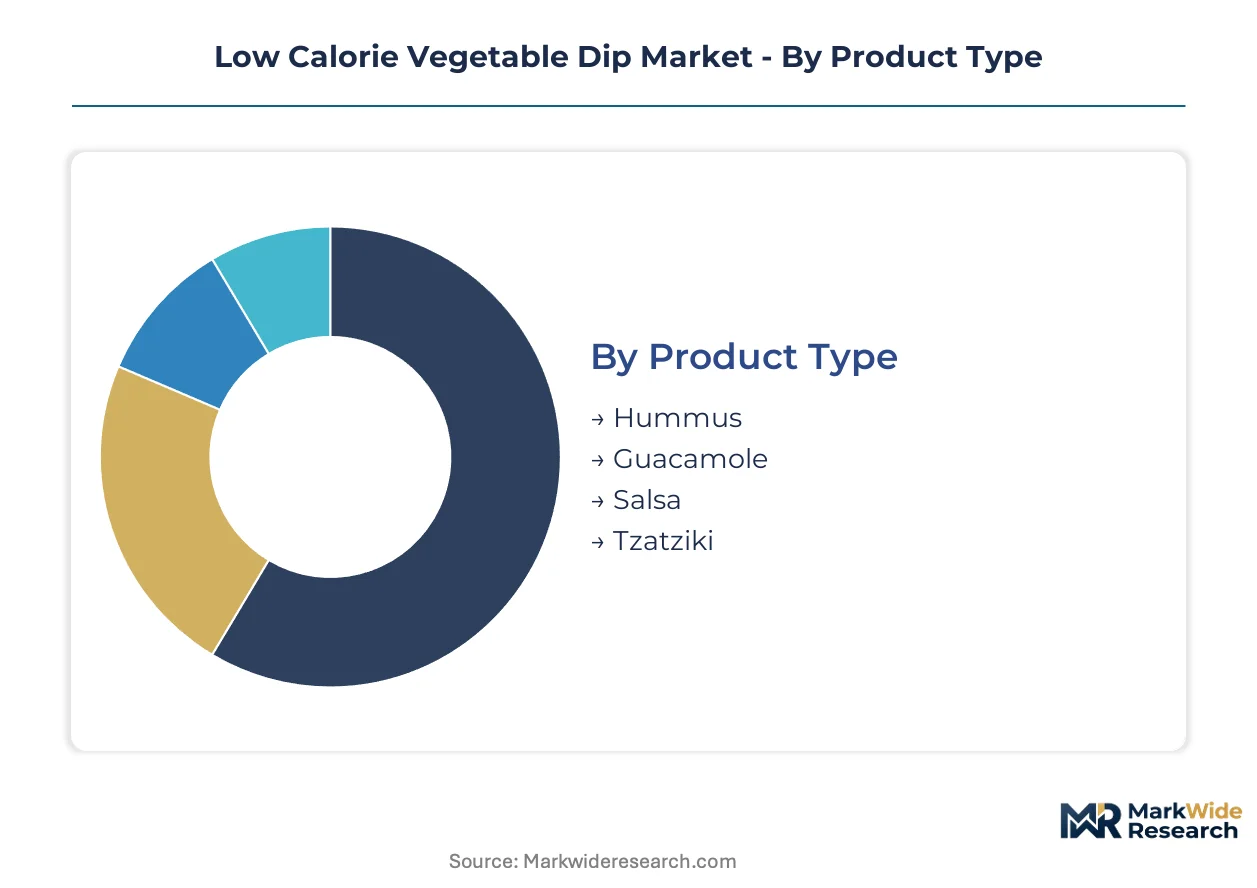
Segmentation in low calorie vegetable dips reveals how formulation chemistry, portion geometry, and channel economics fragment demand across distinct purchase occasions. Understanding these divides exposes where margin concentrates and which configurations face shelf-life or logistics constraints.
Product Type:
Cost tier separates mass-market volume drivers from premium positioning plays in this category.
- Hummus:Chickpea-tahini emulsions deliver shelf-stable protein density with established consumer recognition. United States refrigerated perimeter placement concentrates demand here, though chickpea supply volatility from Middle Eastern growing regions compresses manufacturing margins.
- Guacamole:Avocado-based formulations achieve premium pricing through fresh-perception and controlled oxidation packaging. Convenience retailers in California and Texas metropolitan corridors drive velocity through grab-and-go vegetable programs with portion-controlled formats.
- Salsa:Tomato-pepper blends occupy entry price tiers with extended ambient shelf stability.
- Tzatziki:Greek yogurt-cucumber recipes serve Mediterranean-positioned premium channels with shorter distribution radii.
Hummus commands the established base. The steepest expansion runs through Guacamole.
Ingredient Type:
Application context determines whether protein claims, fat reduction, or allergen avoidance drives formulation selection.
- Legume-Based:Chickpea and lentil purees satisfy FDA protein content thresholds for front-of-pack labeling advantages. Corporate wellness procurement managers prioritize these formulations for employer-subsidized snacking programs.
- Dairy:Greek yogurt bases deliver protein fortification with controlled fat content. Premium supermarket channels in the Northeast United States concentrate demand where Chobani LLC has established refrigerated deli placement.
- Avocado:Monounsaturated fat positioning targets cardiovascular health claims.
- Nut-Based:Almond and cashew purees serve paleo and keto diet adherents through specialty grocers.
Dairy commands the established base. The steepest expansion runs through Legume-Based.
Packaging Type:
Volume scale and consumption occasion fragment procurement authority across retail formats.
- Single-Serve Packs:Portion-controlled formats reduce food waste and labor costs for convenience retailers expanding fresh perimeter offerings. Foodservice operators at corporate cafeterias standardize these configurations for grab-and-go vegetable programs.
- Tubs:Multi-serve containers retain household penetration in club stores and mass retail channels. Midwest United States distribution centers prioritize these formats for cost-efficient case picking and pallet optimization.
- Pouches:Flexible formats reduce shipping cube for e-commerce cold-chain delivery.
- Jars:Glass packaging serves premium positioning in specialty shops with sustainability credentials.
Tubs command the established base. The steepest expansion runs through Single-Serve Packs.
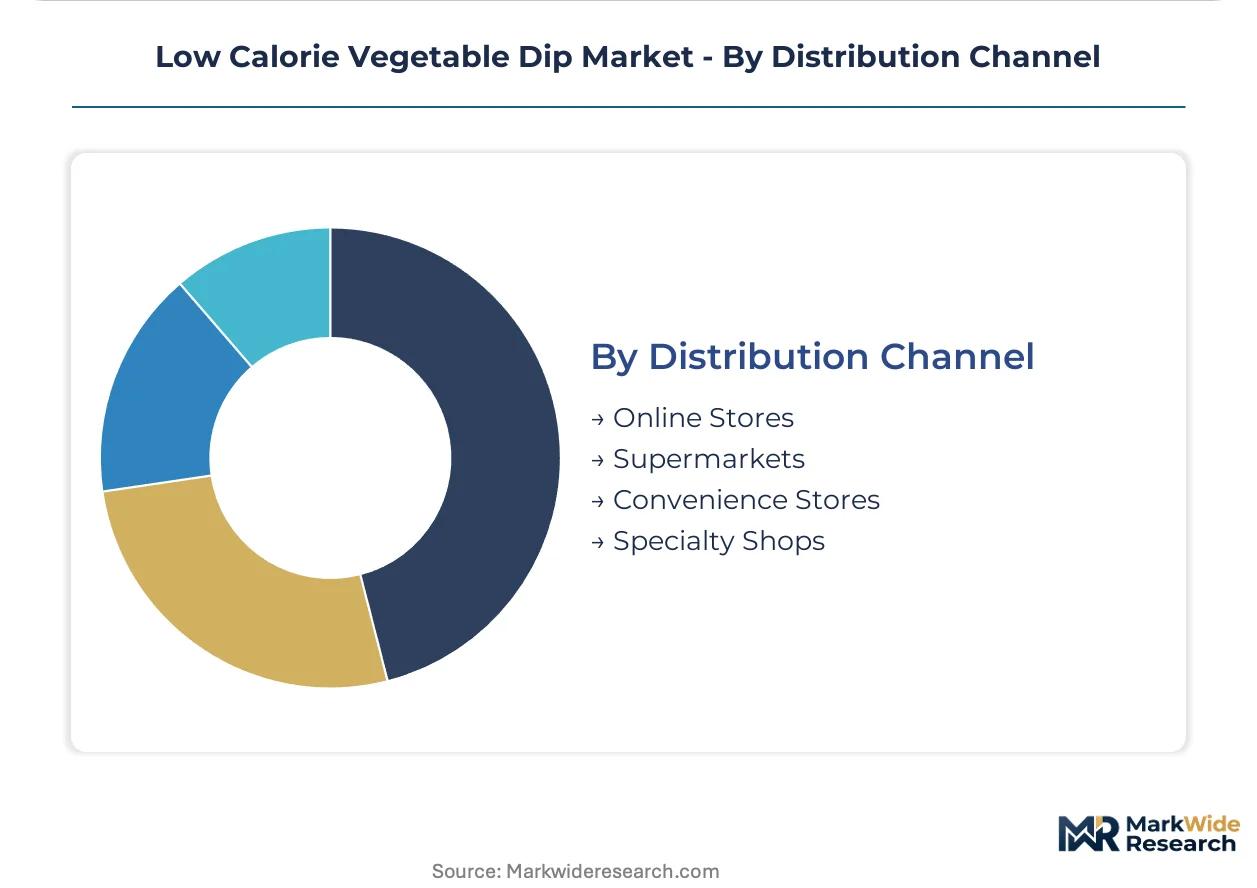
Distribution Channel:
Customer type and purchase urgency determine cold-chain investment requirements and slotting fee economics.
- Supermarkets:Refrigerated deli placement concentrates volume through direct store delivery networks controlled by incumbent brands. USDA organic certification creates premium tiers that reward domestic supply chain investments here.
- Online Stores:Insulated last-mile delivery partnerships with meal-kit providers open direct-to-consumer channels. Specialty grocers in dense United States metropolitan corridors prioritize these formats for subscription vegetable box programs.
- Convenience Stores:Impulse purchase velocity depends on single-serve pack availability at refrigerated checkout.
- Specialty Shops:Curated assortments serve dietary-specific consumers with clean-label verification.
Supermarkets command the established base. The steepest expansion runs through Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in low calorie vegetable dip formulations favor net-importing European markets against North American production surplus, with refrigerated logistics networks determining viable trade corridors and shelf-life-constrained distribution radii.
United States
Refrigerated perimeter expansion at Kroger, Albertsons, and Walmart supercenters drives single-serve pack velocity through direct store delivery networks. FDA nutrition labeling requirements and USDA organic certification standards govern formulation claims, creating compliance barriers for imported alternatives. California's Central Valley anchors domestic avocado supply chains that feed guacamole production clusters around Los Angeles and San Diego metropolitan corridors.
Germany
Discounter penetration at Aldi and Lidl prioritizes private-label hummus and tzatziki formats with compressed price points versus branded alternatives. ECHA REACH chemical safety protocols systematically eliminate synthetic preservatives from approved additive lists, forcing reformulation with cultured dextrose or high-pressure processing. The Rhine-Ruhr industrial corridor hosts cold-chain distribution hubs serving Benelux re-export demand for clean-label Mediterranean dips.
United Kingdom
Meal-kit subscription services and specialty grocer partnerships expand e-commerce cold-chain penetration for premium legume-based formulations. Food Standards Agency front-of-pack labeling mandates accelerate sodium reduction timelines across existing product lines. Greater London concentrates demand density for grab-and-go fresh programs at corporate cafeterias and convenience retailers along the M25 logistics ring.
France
Mediterranean-adjacent consumption habits in Provence-Alpes-Côte d'Azur and Occitanie sustain above-average per-capita hummus penetration versus Northern European benchmarks. ANSM food contact material regulations constrain packaging substrate selection for extended shelf-life products. The Île-de-France region around Paris generates disproportionate velocity for premium dairy-based vegetable dips through Monoprix and Bio c' Bon specialty channels.
Spain
Underpenetrated hummus markets relative to Northern Europe present expansion targets where Mediterranean dietary patterns align with legume-based nutrition positioning. Spanish Agency for Food Safety and Nutrition (AESAN) clean-label guidance accelerates elimination of artificial colorants from traditional gazpacho and romesco adjacent categories. Catalonia's Barcelona metropolitan area hosts emerging co-manufacturing capacity serving pan-European private-label demand.
Low Calorie Vegetable Dip Market Competitive Landscape
On the supply side, the industry is consolidating around refrigerated distribution scale and captive agricultural supply chains, with incumbent players leveraging direct store delivery networks to lock out regional entrants lacking temperature-controlled logistics infrastructure. Three strategic archetypes dominate: diversified food conglomerates with cross-category refrigerated platforms, dairy-forward specialists exploiting protein fortification claims, and plant-based pure-plays anchored to clean-label positioning. Competitive intensity concentrates on M&A activity targeting regional organic brands and strategic partnerships with meal-kit providers seeking exclusive formulation supply.
Within the diversified conglomerate tier, Nestle S.A. and PepsiCo Inc. occupy positions defined by cross-category refrigerated infrastructure and global procurement scale. Chobani LLC exemplifies the dairy-specialist archetype through Greek yogurt-based formulation expertise. Sabra Dipping Co. LLC anchors the legume-based pure-play segment with established refrigerated deli placement networks. These three entities collectively represent the competitive frontier where protein claim differentiation and cold-chain reach determine shelf access.
| Leading Market Players |
|---|
| Bolthouse Farms |
| Chobani LLC |
| General Mills Inc. |
| Nestle S.A. |
| PepsiCo Inc. |
| Sabra Dipping Co. LLC |
| Good Foods Group LLC |
| Kite Hill |
| Hain Celestial Group Inc. |
| Others |
Value Network & Pricing Analysis
The I-5 corridor connecting California's Central Valley avocado orchards to Los Angeles processing clusters concentrates cost dynamics that ripple through guacamole pricing tiers and compress margins for regional brands lacking captive supply arrangements.
Pricing Analysis
Corporate cafeteria procurement managers anchor a three-tier pricing structure across premium USDA Organic, standard clean-label, and economy conventional levels. Price differentiation rests on certification grade and volume scale, with organic legume-based formulations commanding shelf-space premiums in Northeast supermarket channels. Cost compression in economy tiers is intensifying because chickpea supply volatility from Middle Eastern growing regions transmits directly to hummus manufacturing margins. Convenience retailers exhibit highest price sensitivity due to thin per-unit margins, while specialty grocers absorb premium positioning with lower volume elasticity.
Supply Chain Analysis
Tariff exposure between the United States and Middle Eastern tahini-producing regions dominates supply chain risk assessment for hummus manufacturers. Raw material sourcing draws from California avocados, Turkish chickpeas, and domestic Greek yogurt production facilities. Single-source vulnerability in tahini supply creates formulation bottlenecks with limited near-term substitution options. Distribution runs through direct store delivery networks controlled by incumbent brands with refrigerated fleet infrastructure, locking out capital-constrained entrants from mainstream retail placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low calorie vegetable dip market functions as a defensive-moat business where refrigerated distribution scale creates network effects that compound shelf-access advantages faster than new capital can replicate them.
For Market Incumbents: Entrench position through backward integration into captive avocado and chickpea supply chains that insulate margins from commodity volatility. Expand direct store delivery fleet capacity in underpenetrated Sun Belt metropolitan corridors before regional challengers secure refrigerated logistics partnerships. Lock in multi-year exclusive supply agreements with meal-kit providers seeking differentiated protein-forward formulations. For New Entrants and Emerging Players: Pursue white-space opportunities in Spain and Italy where Mediterranean dietary alignment meets underdeveloped hummus penetration relative to Northern European benchmarks. Target corporate wellness procurement managers with single-serve clean-label formats that satisfy centralized sustainability scorecard requirements. Enter through co-manufacturing partnerships that bypass capital-intensive production facility investments. For Investors and Strategic Acquirers: USDA Organic certification timelines extending product development cycles reshapes the acquisition landscape toward brands with verified supply chains already past regulatory gates. Five-to-ten year viability favors refrigerated distribution platforms with density economics in multiple United States census regions over pure-play formulation specialists. Monitor ECHA REACH chemical safety protocol amendments as the signal indicating which preservative-free formulation portfolios will retain European market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Agriculture | Bolthouse Farms controls California carrot supply chains that feed guacamole and hummus production with input cost stability. |
| Direct Store Delivery Network Expansion | Sabra Dipping Co. LLC leverages refrigerated fleet density to lock incumbent shelf placement against regional challengers. |
| Co-Manufacturing Partnership Formation | Asset-light production arrangements allow emerging brands to scale without capital-intensive facility investments. |
| USDA Organic Certification Investment | Federal standards create premium pricing tiers that reward domestic supply chain verification and exclude uncertified imports. |
| E-Commerce Cold-Chain Partnership Development | Insulated last-mile delivery with meal-kit providers opens channels bypassing traditional retail slotting fee structures. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with refrigerated logistics directors, category buyers at convenience retailers, corporate wellness procurement managers, and plant-based formulation R&D leads; and secondary validation through FDA nutrition labeling guidance documents, USDA organic certification databases, Nielsen retail audit data, and customs import records for chickpea and tahini shipments. Bottom-up volume modeling triangulated against top-down category expenditure estimates produced convergent market sizing.
Forecast inputs include formulation chemistry segmentation, packaging geometry economics, channel cold-chain requirements, and regional regulatory cluster adoption patterns across the projection horizon. CAGRs were derived from segment-level growth rate assumptions weighted by base-year revenue contribution. Industry-specific forecast inputs incorporate refrigerated perimeter expansion rates at major United States retailers and corporate wellness program procurement consolidation timelines.
Macroeconomic conditions sit as an overlay; deviation in foodservice labor costs, diesel fuel pricing, and refrigerated logistics wage inflation would shift the trajectory. Forecasts reflect documented assumptions about clean-label regulatory enforcement intensity and plant-based protein claim threshold evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Low Calorie Hummus Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Cat and Dog Food Toppers Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Moringa Products Market
Specialty Foods
Middle East and Africa Free-From Food Market
Specialty Foods
Reishi Mushroom Market
Specialty Foods
Natto Market
Specialty Foods
Kelp Noodles Market
Specialty Foods
Vegan Dressing Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
Fruit Dessert Market
Specialty Foods
Natural Honey Market
Specialty Foods
North America Hummus Market
Specialty Foods
Gluten-Free Oats Market