
 Aloe Butter Market | 2026-2036
Aloe Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Aloe Butter Market Outlook
Clean-label cosmetics manufacturers is rotating demand away from conventional emollients toward plant-derived alternatives with traceable supply chains. Texas Natural Supply leverages its vertical integration from aloe cultivation to finished butter to control quality consistency. Sunaroma anchors its position through specialized organic certification that commands premium placement in specialty retail channels.
Aloe butter is a lipid-rich emollient produced by blending aloe vera extract with hydrogenated vegetable oils, typically containing 15-20% aloe solids by weight and melting between 38-42°C for topical stability. Its primary commercial purpose centers on delivering moisturizing and soothing properties in skin and hair formulations without petrochemical bases. Organic aloe butter leads product type margins due to certification scarcity and clean-label premiums, while gel form applications in cosmetics represent the fastest-expanding consumption segment as brands seek lightweight, non-greasy textures. Direct sales channels capture disproportionate value in pharmaceutical-grade aloe butter where buyer-seller technical collaboration determines specification compliance.
FDA cosmetic labeling requirements and REACH substance restrictions in Europe jointly determine market access thresholds for aloe butter importers and domestic producers. ISO 16128 natural origin standards and ECHA guidance on plant-derived cosmetic ingredients create additional compliance layers that favor suppliers with documented extraction methodologies. Stakeholders must monitor evolving bioprospecting regulations in aloe source countries and adapt procurement strategies to emerging traceability mandates before compliance gaps harden into supply exclusions.
Market Dynamics
Clean-label procurement mandates from cosmetics formulators are compressing aloe butter supply chains toward certified organic sources with documented provenance, forcing processors to consolidate backward into cultivation or risk exclusion from premium formulations.
Growth Catalysts
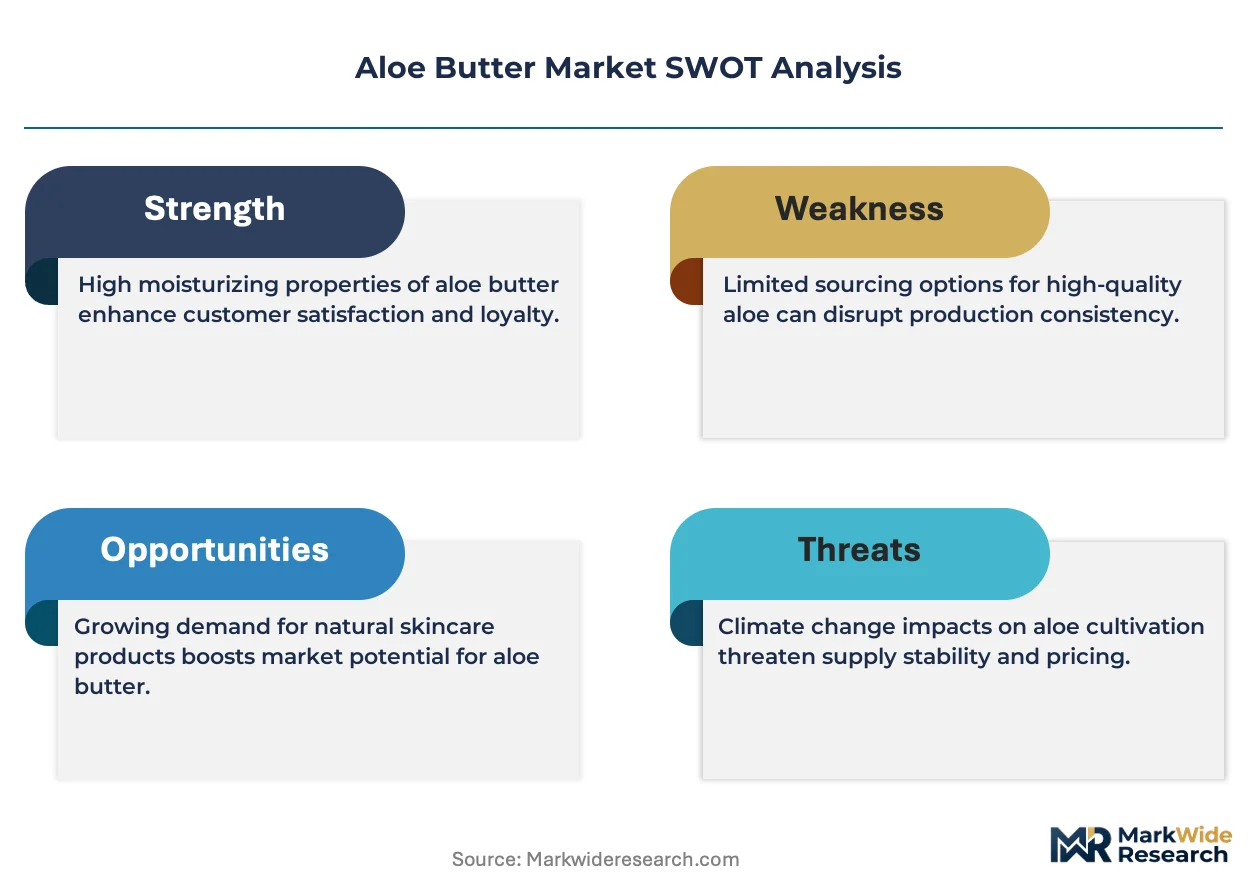
- REACH substance restrictions:European formulators face tightened disclosure requirements for plant-derived cosmetic ingredients, accelerating replacement of petrochemical emollients with traceable aloe butter alternatives.
- ISO 16128 natural origin standards:Certification to this framework unlocks placement in prestige skincare lines where consumers scrutinize ingredient sourcing claims.
- German natural personal care cluster:Concentrated demand from Hamburg and Munich-based brands creates pull-through for certified organic butter volumes.
Market Restraints
- Aloe vera cultivation concentration:Dependence on water-intensive farming regions in Mexico and the Dominican Republic exposes processors to climate volatility and irrigation cost spikes.
- Hydrogenated oil input costs:Vegetable oil price swings directly compress aloe butter margins, particularly for non-organic grades competing on cost.
- Shea and mango butter substitution:These established emollients command lower price points and deeper distribution in mass-market personal care, limiting aloe butter penetration.
Strategic Opportunities
- Pharmaceutical-grade direct sales:Technical collaboration channels for wound-care and dermatological formulations capture value through specification compliance rather than commodity trading.
- India BIS natural cosmetics standards:Emerging regulatory clarity creates first-mover positioning for certified suppliers in a market pivoting toward Ayurveda-aligned personal care.
- Gel-form texture innovation:Lightweight, non-greasy cosmetic applications represent white space where aloe butter differentiates against heavier lipid alternatives.
Industry Challenges
- ECHA documentation timelines:REACH compliance for novel extraction methodologies requires 18-24 month submission cycles that delay market entry.
- Organic certification backlogs:Accredited body capacity constraints extend audit waiting periods, freezing supply expansion for premium grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aloe Butter Market |
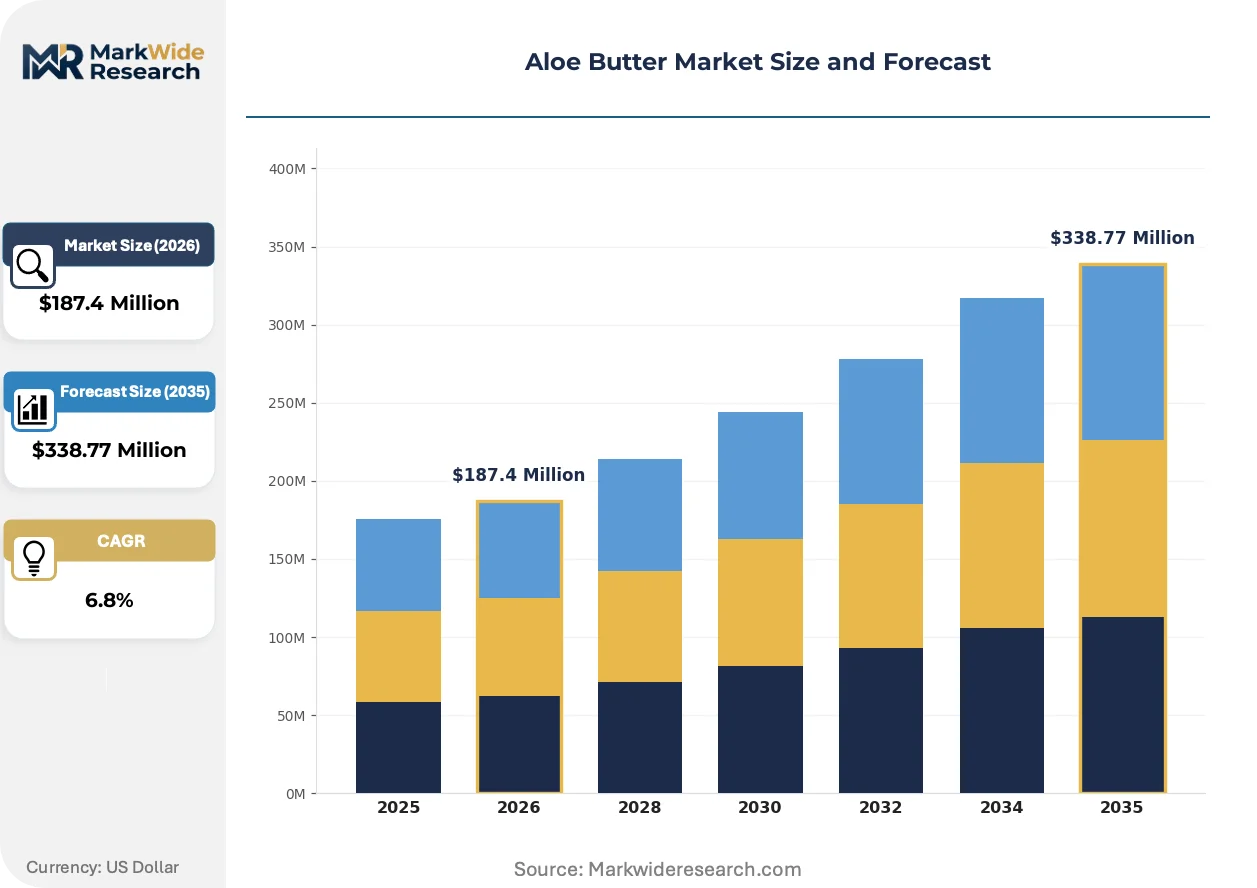
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Aloe Butter, Synthetic Aloe Butter, Crude Aloe Butter, Refined Aloe Butter Application: Cosmetics, Personal Care, Pharmaceuticals, Food Additives Form: Solid, Liquid, Cream, Gel Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | The Hallstar Company, Texas Natural Supply, Sunaroma, Camden-Grey Essential Oils Inc, Madina Industrial Corp, Natural Sourcing, Premier Specialties Inc, Organic Creations, Chagrin Valley Soap & Salve, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aloe Butter Market Strategic Shifts
Extraction technology advances and regulatory disclosure mandates are reshaping how aloe butter processors compete, with differentiation shifting from commodity supply to provenance verification and formulation performance.
Supercritical CO2 extraction is fragmenting conventional solvent-based processing by preserving heat-sensitive aloe polysaccharides that degrade in traditional methods. Specialty cosmetics laboratories in France and Switzerland are adopting these systems to produce clinical-grade butter for dermocosmetic applications. The technology is fragmenting processor tiers into equipment-capable specialists versus commodity blenders facing margin compression.
REACH Annex XVII updates on plant-derived cosmetic substances are forcing importers to reconstruct supply chain documentation from farm to finished butter. German and Dutch customs authorities now reject shipments lacking ECHA-aligned substance characterization data. Organic-certified suppliers with pre-existing extraction methodology files capture disproportionate placement in EU prestige channels.
Formulator technical audits are displacing arm's-length commodity purchasing as cosmetics brands internalize supply chain risk management. Procurement teams from Los Angeles and Seoul skincare houses now conduct on-site verification of aloe cultivation and hydrogenation protocols. This behavioral shift concentrates volume with processors offering open-facility inspection rights rather than lowest-unit-cost bidding.
Aloe Butter Market Segmentation
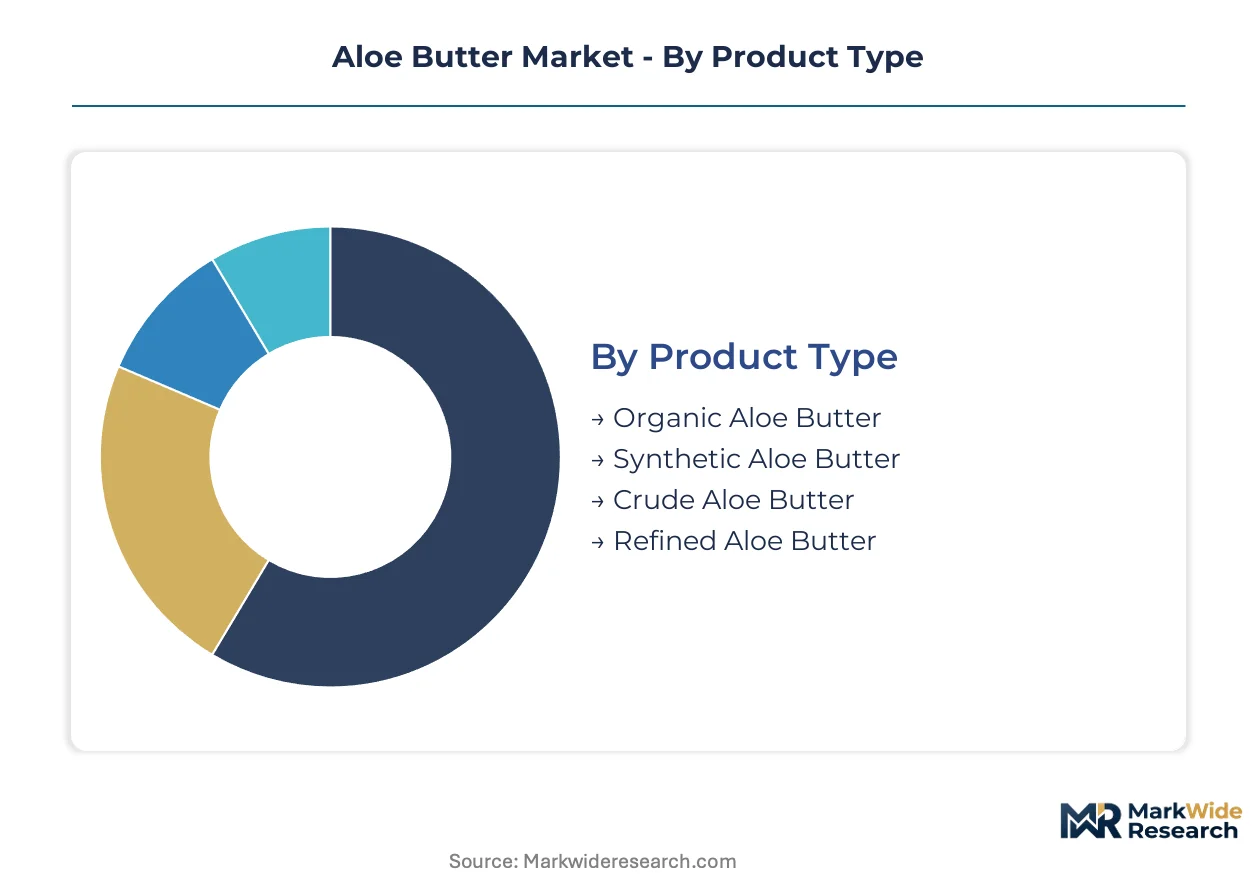
Aloe butter procurement splits across certification tiers, formulation requirements, and channel access rules. Each segmentation axis carries distinct compliance burdens and margin structures that determine supplier viability.
Product Type:
Regulatory differentiation separates certified organic grades from conventional alternatives through ISO 16128 documentation and ECHA substance characterization requirements.
- Organic Aloe Butter:Contains 15-20% aloe solids by weight with full cultivation-to-processing traceability mandated by REACH Annex XVII. German natural personal care brands in Hamburg and Munich concentrate procurement here, paying premiums for pre-filed extraction methodology documentation that accelerates customs clearance.
- Refined Aloe Butter:Hydrogenated vegetable oil blends undergo additional purification to remove color and odor for prestige skincare formulations. Los Angeles and Seoul-based cosmetics houses specify this grade for gel-form texture innovations requiring lightweight, non-greasy performance.
- Crude Aloe Butter:Unprocessed lipid base retains natural color variation and stronger botanical scent; processors in Mexico and the Dominican Republic ship this grade to regional compounders.
- Synthetic Aloe Butter:Petrochemical-derived emollient mimics aloe butter sensorial properties at lower cost points; mass-market personal care brands source this where clean-label positioning is not required.
Organic aloe butter handles the majority of throughput; refined aloe butter is expanding most quickly as gel-form applications gain formulation share.
Application:
End-use concentration varies by specification intensity and buyer-seller technical collaboration requirements.
- Cosmetics:Prestige skincare and color cosmetics demand clinical-grade butter with supercritical CO2 extraction preserving heat-sensitive polysaccharides. French and Swiss dermocosmetic laboratories specify this processing method for dermocosmetic placement.
- Pharmaceuticals:Wound-care and dermatological formulations require pharmaceutical-grade direct sales channels where technical audits verify hydrogenation protocols and aloe vera cultivar consistency. FDA cosmetic labeling rules govern US market access for these applications.
- Personal Care:Hair conditioners and body lotions absorb volume across price tiers, with shea and mango butter substitution limiting aloe butter penetration in mass-market channels.
- Food Additives:Edible-grade aloe butter serves functional food applications with FSSAI and FDA food additive compliance requirements determining supplier qualification.
Cosmetics commands the largest application share; pharmaceuticals delivers the steepest expansion trajectory through specification-driven procurement.
Form:
Texture engineering drives form selection as brands balance stability, spreadability, and sensory profile.
- Gel:Lightweight, non-greasy vehicle represents white-space differentiation against heavier lipid alternatives; fastest-climbing consumption segment as Korean and US skincare houses pursue novel textures.
- Solid:Melting point of 38-42°C ensures topical stability in stick balms and bar formulations; established base for conventional emollient applications.
- Cream:Intermediate viscosity suits body butters and rich moisturizers; processors blend with complementary butters to optimize cost-performance.
- Liquid:Reduced viscosity enables spray and serum delivery systems; requires additional stabilization against separation.
Solid form handles baseline volume; gel form is gaining share fastest through texture innovation pipelines.
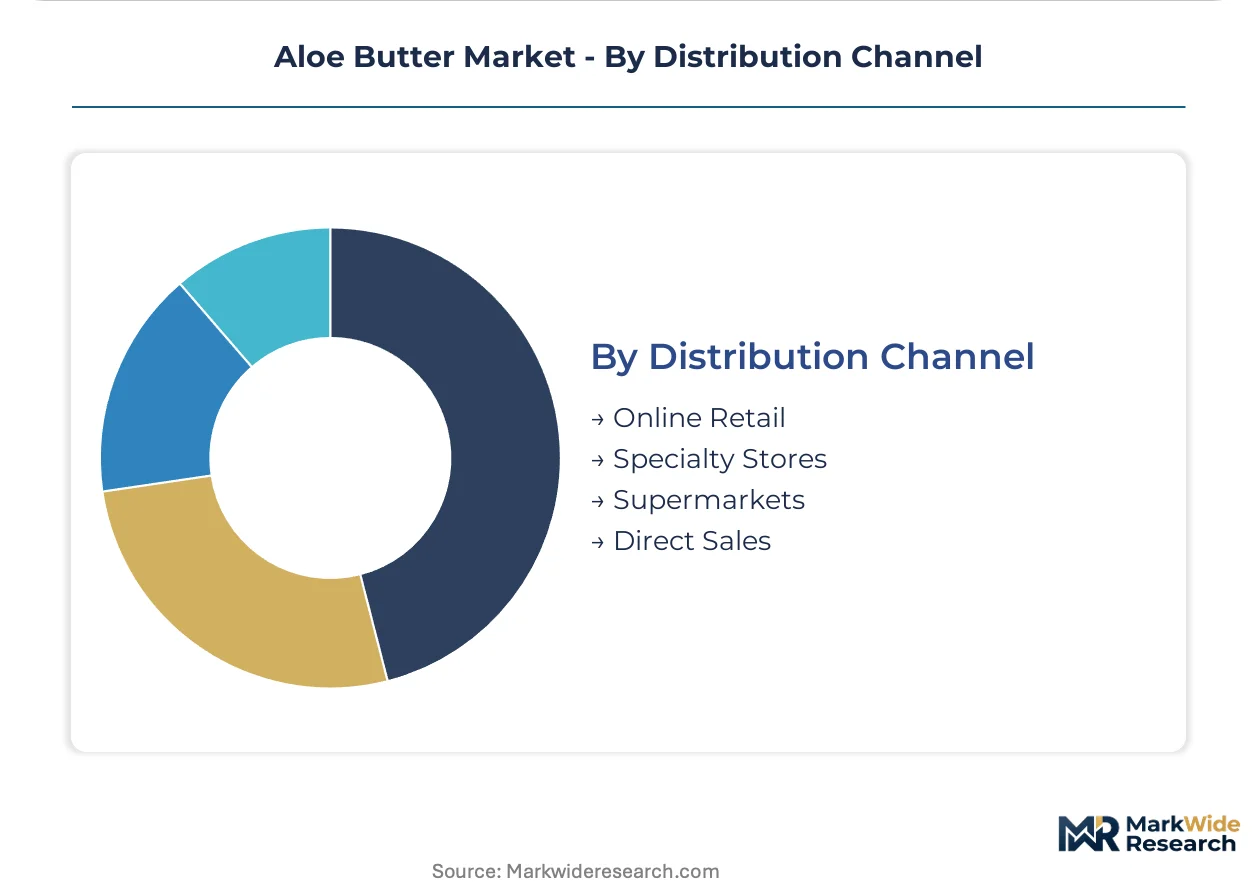
Distribution Channel:
Channel selection determines margin capture and compliance verification depth.
- Direct Sales:Pharmaceutical-grade and certified organic volumes flow through technical collaboration channels where buyer teams conduct on-site cultivation and processing audits. German customs authorities now require ECHA-aligned documentation for all plant-derived cosmetic ingredient shipments.
- Specialty Stores:Premium organic certification commands placement in natural personal care retail; Sunaroma anchors positioning here through dedicated organic certification.
- Online Retail:Clean-label cosmetics manufacturers accelerate procurement through digital channels with documented provenance requirements.
- Supermarkets:Mass-market personal care penetration remains limited by shea and mango butter price competition.
Direct sales captures disproportionate value in premium grades; online retail is climbing fastest as procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aloe butter supply chains concentrate cultivation capacity in water-intensive farming zones across Mexico and the Dominican Republic, while downstream formulation demand clusters in Germany, the United States, and South Korea where clean-label cosmetics manufacturers enforce traceability mandates.
United States
FDA cosmetic labeling requirements tighten ingredient disclosure standards for plant-derived emollients entering personal care formulations. Los Angeles-based skincare houses conduct on-site technical audits of aloe cultivation and hydrogenation protocols to verify supply chain integrity. Texas Natural Supply leverages its vertical integration from aloe farming to finished butter production to control quality consistency for domestic pharmaceutical-grade buyers.
Germany
REACH Annex XVII substance restrictions accelerate replacement of petrochemical emollients with traceable aloe butter alternatives in prestige skincare lines. ECHA-aligned documentation requirements now govern customs clearance for all plant-derived cosmetic ingredient shipments entering Hamburg and Munich ports. German natural personal care brands concentrate procurement of certified organic butter grades with pre-filed extraction methodology files.
South Korea
MFDS cosmetic safety regulations establish compliance thresholds for imported botanical ingredients used in dermocosmetic applications. Seoul-based skincare houses drive gel-form texture innovation, sourcing lightweight aloe butter vehicles for non-greasy serum and spray delivery systems. Korean formulators prioritize supercritical CO2 processed grades to preserve heat-sensitive polysaccharides for clinical-grade positioning.
India
BIS natural cosmetics standards create emerging regulatory clarity for Ayurveda-aligned personal care markets pivoting toward plant-derived emollients. Mumbai and Bangalore-based formulators accelerate procurement of certified organic aloe butter with documented provenance to satisfy clean-label mandates. Domestic processors face pressure to consolidate backward into cultivation or risk exclusion from premium export channels serving European buyers.
Switzerland
Swissmedic oversight of cosmetic-medical border products elevates documentation requirements for aloe butter entering wound-care and dermatological formulations. French and Swiss dermocosmetic laboratories specify supercritical CO2 extraction methods to produce clinical-grade butter with preserved bioactive compounds. Geneva and Basel-based specialty chemicals distributors capture value through technical collaboration channels rather than commodity trading.
Aloe Butter Market Competitive Environment
Concentration sits with vertically integrated processors and certified organic specialists who control cultivation-to-finished-product traceability. The vendor base separates into three strategic archetypes: farm-integrated processors securing raw material consistency, certification-focused suppliers capturing clean-label premiums, and regional compounders serving price-sensitive mass-market channels. Competitive dynamics revolve around backward integration into aloe farming and acquisition of accredited organic certification to bypass audit backlogs.
Among North American suppliers, Texas Natural Supply exemplifies the farm-integrated archetype through its captive cultivation operations, while Sunaroma anchors the certification-specialist tier with dedicated organic credentials. The Hallstar Company occupies a position representing scale-driven chemical processors with cross-emollient portfolios. These three patterns illustrate how market positioning depends on controlling either upstream supply security or downstream regulatory compliance rather than commodity cost leadership.
| Leading Market Players |
|---|
| The Hallstar Company |
| Texas Natural Supply |
| Sunaroma |
| Camden-Grey Essential Oils Inc |
| Madina Industrial Corp |
| Natural Sourcing |
| Premier Specialties Inc |
| Organic Creations |
| Chagrin Valley Soap & Salve |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XVII compliance gates both supply qualification and price differentiation simultaneously, forcing processors to absorb documentation costs that stratify organic-certified grades from conventional alternatives while German customs authorities reject shipments lacking ECHA-aligned substance characterization data.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across the aloe butter market, separating certified organic grades with pre-filed extraction methodology documentation from refined and crude alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 16128 certification status, cultivation traceability depth, and hydrogenation protocol verification. Cost compression in non-organic grades is intensifying because vegetable oil price swings directly compress margins for commodity-competing processors. Mass-market personal care brands show highest price sensitivity, while pharmaceutical-grade buyers prioritize specification compliance over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate pharmaceutical-grade procurement, with German and US buyers maintaining six-month coverage against aloe vera cultivation volatility in Mexico and the Dominican Republic. Hydrogenated vegetable oil inputs, accredited organic certification audits, and supercritical CO2 extraction equipment constitute critical dependencies. Single-source vulnerability concentrates in water-intensive farming regions exposed to climate volatility and irrigation cost spikes. Distribution runs through direct technical collaboration channels for premium grades, with specialty retail and online platforms handling certified organic volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction technology is disrupting conventional solvent-based processing, creating acceleration windows for equipment-capable specialists while fragmenting commodity blenders into margin-compressed tiers.
For Market Incumbents: Shield market position by deepening backward integration into aloe cultivation in Mexico and the Dominican Republic to secure raw material consistency against climate volatility. Accelerate organic certification investment to bypass accredited body audit backlogs that freeze supply expansion for premium grades. These moves counter shea and mango butter substitution threats in mass-market channels. For New Entrants and Emerging Players: ISO 16128 fast-track certification unlocks placement in prestige skincare lines where Hamburg and Munich-based brands concentrate procurement. Target gel-form texture innovation for Korean and US skincare houses pursuing lightweight, non-greasy serum delivery systems. Pursue supercritical CO2 processing partnerships with French and Swiss dermocosmetic laboratories as the go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical CO2 extraction infrastructure as clinical-grade butter demand climbs. Five-to-ten year viability favors processors with documented cultivation-to-finished-product traceability and pre-filed ECHA documentation. Watch for organic certification audit queue lengths as the inflection signal indicating supply-constrained premium pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive aloe farming in Mexico and the Dominican Republic secures raw material consistency against climate volatility. |
| Supercritical CO2 Extraction Adoption | Preserves heat-sensitive aloe polysaccharides for clinical-grade positioning in French and Swiss dermocosmetic laboratories. |
| ISO 16128 Certification Investment | Unlocks placement in prestige skincare lines where Hamburg and Munich-based brands scrutinize ingredient sourcing claims. |
| Pharmaceutical-Grade Direct Sales Channel | Technical collaboration with wound-care formulators captures value through specification compliance rather than commodity trading. |
| Gel-Form Texture Innovation | Lightweight vehicle differentiation targets Korean and US skincare houses pursuing non-greasy serum delivery systems. |
Study Parameters
Initial hypotheses were tested against primary input from cosmetics formulators, aloe butter processors, organic certification auditors, and specialty retail buyers and refined through secondary validation against customs/trade data, ECHA substance registration filings, ISO 16128 documentation databases, and SEC filings of publicly traded personal care ingredients suppliers. Bottom-up volume estimates from cultivation capacity and processing throughput triangulated against top-down demand aggregation from cosmetics brand procurement disclosures.
Variance-decomposition framing separates volume drivers across certification tier, extraction methodology, end-use application, and regional regulatory cluster throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Hydrogenated vegetable oil price trajectories and organic certification audit queue dynamics served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity and stable aloe vera cultivation yields would require recalibration. Forecasts reflect documented assumptions about regulatory compliance timelines and input cost trajectories. Revision becomes warranted when ECHA documentation backlogs or climate-induced cultivation disruptions cross thresholds that alter supply availability for premium grades.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Healthy Low-Fat Desserts Market
Specialty Foods
Foie Gras Market
Specialty Foods
Zhacai Market
Specialty Foods
Cat Food Toppings Market
Specialty Foods
Asia Pacific Pet Milk Replacers Market
Specialty Foods
Super Foods Market
Specialty Foods
Curculin Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Global Sauerkrauts Market
Specialty Foods
Wheatgrass Products Market
Specialty Foods
Free-From Food Market
Specialty Foods
Middle East and Africa Free-From Food Market
Specialty Foods
High Protein Cat Food Market
Specialty Foods
Dill Juice Market
Specialty Foods
Soft Tofu Market
Specialty Foods
Organic Skin Care Market