

Marine Thermal Water Ferments Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Thermal Water Ferments Market Insights
Mediterranean biotech fermenters is rebalancing output toward high-purity marine thermal extracts as coastal sourcing constraints tighten. BASF leverages its integrated biotechnology platforms to secure consistent marine biomass supply chains. Croda International anchors its competitive position through specialized lipid encapsulation expertise for sensitive skin applications. Seppic differentiates via advanced hydrosol stabilization technologies that extend shelf life in premium cosmetic formulations.
Marine thermal water ferments comprise bioactive metabolites cultivated from extremophile microorganisms harvested near geothermal marine vents or coastal hot springs, typically standardized at polyphenol concentrations above 15% and peptide yields between 8-12% for cosmetic-grade applications. These ferments primarily serve anti-aging and skin barrier repair functions through collagen synthesis stimulation and oxidative stress reduction. Powder extracts dominate current manufacturing volume due to superior stability in long-haul distribution, while liposomal formulations capture expanding margin pools in clinical dermatology channels where bioavailability thresholds are stringent. Skincare applications lead absolute demand, though spa therapies represent the fastest-growing consumption segment as wellness tourism operators seek differentiated marine-based treatment protocols.
EMA cosmetic ingredient guidelines, REACH substance registration requirements, and ISO 16128 natural origin standards collectively shape formulation compliance costs and market access conditions for marine ferment suppliers. FDA cosmetic labeling rules and MoCRA facility registration mandates impose additional documentation burdens on exporters targeting North American dermatology channels. Stakeholders must monitor regulatory divergence between EU biodegradability criteria and emerging Asian microbiome safety protocols to anticipate reformulation investments and geographic prioritization shifts.
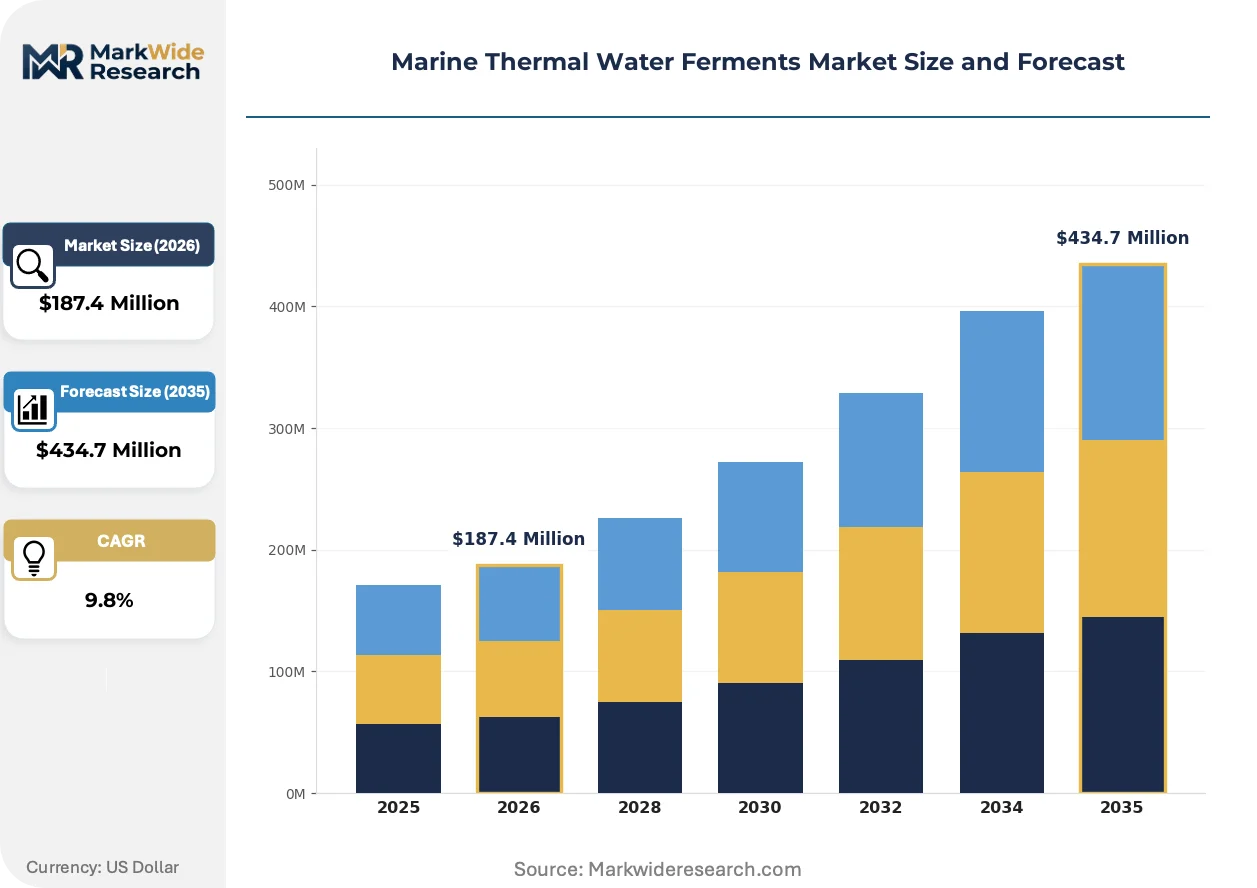
Market Dynamics
REACH substance registration requirements and evolving ISO 16128 natural origin standards are compressing supplier margins while accelerating consolidation among European marine biotechnology specialists capable of documenting full biodegradability compliance.
Growth Catalysts
- EMA cosmetic ingredient guidelines:Stringent purity benchmarks for fermented marine extracts are filtering out low-grade suppliers and concentrating procurement among certified biotech fermenters in France and South Korea.
- Spa therapy segment expansion:Wellness tourism operators in Japan are developing proprietary marine-based treatment protocols that specify thermal water ferments above 15% polyphenol concentration.
- Coastal hot spring sourcing:Mediterranean geothermal vent harvesting is intensifying as extremophile cultivation facilities secure long-term biomass supply agreements with premium skincare manufacturers.
Market Restraints
- Coastal biomass volatility:Geothermal marine vent accessibility fluctuates with seasonal tidal patterns and protected marine zone designations, constraining raw material predictability for Mediterranean suppliers.
- Liposomal formulation cost premiums:Clinical dermatology-grade encapsulation requires specialized lipid processing equipment that doubles unit production costs versus powder extract alternatives.
- MoCRA facility registration:FDA cosmetic labeling rules impose documentation burdens that delay North American market entry by 18-24 months for European marine ferment exporters.
Strategic Opportunities
- Clinical dermatology channel penetration:Bioavailability thresholds in medical-grade skincare are creating margin expansion potential for suppliers capable of peptide standardization above 12% yields.
- EU Green Deal biodegradability incentives:REACH-compliant marine thermal extracts qualify for preferential procurement scoring in public wellness facility tenders across France and Germany.
- Hybrid fermentation-synthetic biology convergence:CRISPR-edited extremophile strains are opening pathways to novel metabolite profiles unattainable through wild-type harvesting alone.
Industry Challenges
- Peptide biochemistry talent scarcity:Fermentation specialists with dual expertise in marine microbiology and cosmetic formulation are concentrated in fewer than twelve academic programs worldwide.
- ISO 16128 natural origin certification timelines:Documentation of biomass provenance and processing chain integrity requires 14-18 months of third-party audit cycles before premium pricing eligibility.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Thermal Water Ferments Market Trends and Innovations
Biotechnology platforms are fragmenting traditional supply relationships as coastal sourcing constraints force cosmetic manufacturers toward captive fermentation partnerships and distributed production nodes.
Continuous flow fermentation systems are decentralizing marine thermal water production from centralized coastal facilities to inland bioreactor installations. Mid-tier cosmetic manufacturers in Germany and the Netherlands are adopting modular 5,000-liter systems at twice the pace of 2022-2024 installations. This geographic redistribution is compressing logistics costs for peptide concentrates while reducing exposure to marine protected area access restrictions.
REACH substance registration requirements are tightening purity documentation thresholds for polyphenol-standardized extracts entering European cosmetic supply chains. Suppliers must now submit full metabolite characterization datasets that previously sufficed with certificate-of-analysis summaries. Small-batch artisan fermenters in Brittany and Provence are consolidating testing capabilities through shared analytical service cooperatives to defray compliance costs.
Wellness tourism procurement is rotating toward direct-supplier contracting that bypasses traditional cosmetic ingredient distributors. Japanese onsen resort operators and South Korean jjimjilbang chains are establishing specification-grade purchasing agreements with Mediterranean biotech fermenters. This channel disintermediation is visible most acutely in Hokkaido and Jeju Island, where thermal spring traditions intersect with marine biotechnology sourcing.
Marine Thermal Water Ferments Market Segmentation
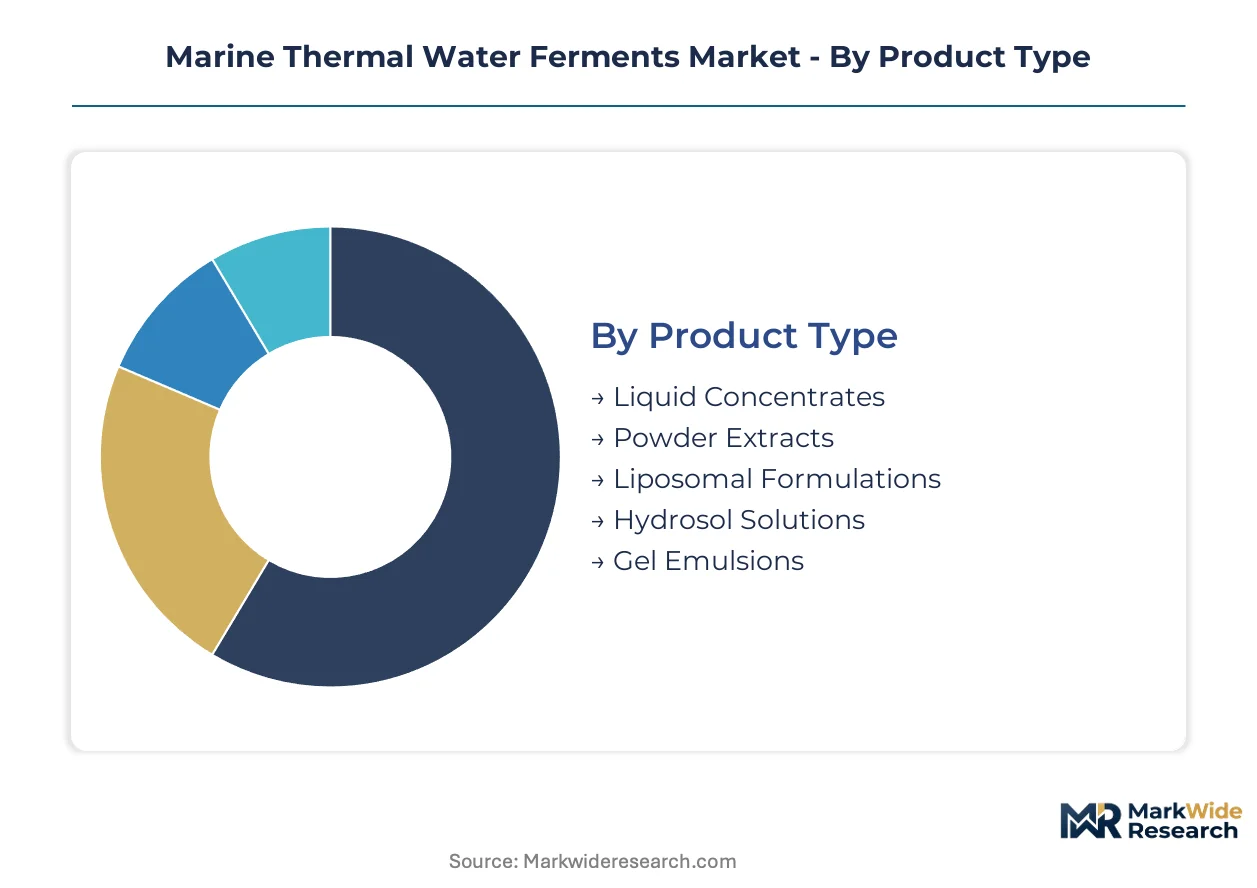
Segmentation in marine thermal water ferments reflects divergent technical requirements across cosmetic formulation tiers and wellness service delivery models. Supply chain configuration varies sharply between bulk powder procurement for mass-market skincare and specialized liposomal production for clinical dermatology channels.
Product Type:
Supply concentration clusters around formats offering the longest stability windows and lowest logistics burden for coastal sourcing regions.
- Powder Extracts:Spray-dried concentrates standardized at polyphenol concentrations above 15% dominate current manufacturing volume. Cosmetic manufacturers in France and South Korea prefer this format for its 24-month shelf stability in long-haul distribution from Mediterranean geothermal vent facilities.
- Liposomal Formulations:Phospholipid-encapsulated peptide systems achieve bioavailability thresholds above 12% yields required in medical-grade skincare. Clinical dermatology channels in Japan absorb these at significant margin premiums despite specialized lipid processing equipment doubling unit production costs.
- Liquid Concentrates:Aqueous suspensions requiring cold-chain logistics serve regional spa operators with shorter procurement cycles.
- Hydrosol Solutions:Seppic's stabilization technologies enable extended shelf life in premium cosmetic formulations for sensitive skin applications.
- Gel Emulsions:Pre-formulated delivery systems reduce compounding complexity for mid-tier cosmetic manufacturers in Germany and the Netherlands.
Powder extracts absorb the bulk of installed capacity; liposomal formulations are expanding most quickly.
Application:
Cost tier differentiation separates commodity skincare additives from specification-grade wellness protocols commanding direct-supplier contracting.
- Skincare:Collagen synthesis stimulation and oxidative stress reduction functions anchor absolute demand volume. Anti-aging serums and barrier repair creams in South Korea specify thermal water ferments as core bioactive inputs.
- Spa Therapies:Wellness tourism operators in Hokkaido and Jeju Island are developing proprietary marine-based treatment protocols. Japanese onsen resorts and South Korean jjimjilbang chains now bypass traditional distributors for specification-grade purchasing agreements above 15% polyphenol concentration.
- Anti-Aging:Peptide-standardized concentrates target dermal matrix regeneration in premium cosmetic lines.
- Cosmetics:Color formulation compatibility drives demand for low-odor, low-pigmentation extract variants.
- Dermatological Treatments:Medical device adjunct therapies require REACH-compliant documentation of full metabolite characterization datasets.
Skincare absorbs the bulk of installed capacity; spa therapies are climbing the fastest.
End User:
Customer type determines procurement sophistication, from bulk ingredient tenders to research partnership structures.
- Cosmetic Manufacturers:BASF and Croda International anchor procurement of marine-derived bioactives for premium skincare lines, leveraging integrated biotechnology platforms and specialized lipid encapsulation expertise respectively.
- Wellness Centers:Direct-supplier contracting is displacing traditional cosmetic ingredient distributors as Japanese and South Korean thermal spring operators establish specification-grade purchasing agreements with Mediterranean biotech fermenters.
- Dermatologists:Medical-grade skincare prescribers require peptide standardization documentation for reimbursement eligibility.
- Beauty Clinics:Mid-tier aesthetic service providers balance efficacy claims against formulation cost constraints.
- Research Laboratories:CRISPR-edited extremophile strain development for novel metabolite profiles drives captive fermentation partnerships.
Cosmetic manufacturers absorb the bulk of installed capacity; wellness centers are gaining share fastest.
Distribution Channel:
Geography of end-use dictates channel selection, with coastal production zones favoring direct logistics over intermediated retail.
- Direct Sales:Wellness tourism procurement is rotating toward supplier-contracting that bypasses traditional cosmetic ingredient distributors, visible most acutely in Hokkaido and Jeju Island where thermal spring traditions intersect with marine biotechnology sourcing.
- Specialty Stores:Premium cosmetic retail in France and South Korea carries fermented marine extracts with ISO 16128 natural origin certification documentation.
- Online Retail:E-commerce platforms serve dispersed cosmetic manufacturers in Germany and the Netherlands adopting modular 5,000-liter bioreactor systems.
- Pharmacies:Clinical dermatology-grade formulations require MoCRA facility registration for North American market access.
- Trade Shows:Industry events concentrate matchmaking between Brittany and Provence artisan fermenters and shared analytical service cooperatives.
Direct sales absorb the bulk of installed capacity; specialty stores are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal geothermal vent harvesting anchors production geography, with Mediterranean hot springs and East Asian thermal traditions driving procurement concentration. Regulatory divergence between EU biodegradability mandates and Asian microbiome safety protocols fragments compliance pathways. Supply chain nodes cluster where biotechnology infrastructure intersects with established wellness tourism corridors.
France
Brittany and Provence artisan fermenters consolidate testing capabilities through shared analytical service cooperatives to defray REACH compliance costs. ANSM cosmetic ingredient guidelines filter out low-grade suppliers and concentrate procurement among certified biotech specialists. The Île-de-France corridor houses formulation R&D facilities serving premium skincare manufacturers sourcing above 15% polyphenol concentrates.
South Korea
Seoul Capital Area cosmetic manufacturers specify thermal water ferments as core bioactive inputs for anti-aging serums and barrier repair creams. MFDS microbiome safety protocols are tightening documentation requirements for fermented marine extracts entering domestic supply chains. Jeju Island thermal spring operators establish direct-supplier contracting with Mediterranean biotech fermenters, bypassing traditional distributors.
Japan
Hokkaido onsen resorts and jjimjilbang chains develop proprietary marine-based treatment protocols above 15% polyphenol concentration. METI industrial biotechnology incentives support extremophile cultivation facility expansions near coastal geothermal vents. The Kanto region absorbs clinical dermatology-grade liposomal formulations at significant margin premiums for medical-grade skincare applications.
Germany
Mid-tier cosmetic manufacturers in North Rhine-Westphalia adopt modular 5,000-liter continuous flow bioreactor systems at twice the pace of 2022-2024 installations. EU Green Deal biodegradability incentives qualify REACH-compliant marine thermal extracts for preferential procurement scoring in public wellness facility tenders. The ECHA substance registration database tightens purity documentation thresholds for polyphenol-standardized extracts entering European cosmetic supply chains.
United States
FDA cosmetic labeling rules and MoCRA facility registration mandates impose documentation burdens that delay North American market entry by 18-24 months for European marine ferment exporters. Greater Boston biotechnology clusters pursue CRISPR-edited extremophile strain development for novel metabolite profiles unattainable through wild-type harvesting. California wellness tourism operators seek differentiated marine-based treatment protocols as spa therapy procurement rotates toward direct-supplier contracting models.
Marine Thermal Water Ferments Market Competitive Landscape
Global majors compete with regional champions across biotechnology platform integration and coastal biomass supply security. Market structure tilts toward consolidation as REACH compliance costs and ISO 16128 certification timelines filter out small-batch artisan fermenters. Three archetypes dominate: integrated chemical conglomerates with captive fermentation capacity, specialized lipid encapsulation specialists, and boutique biotech fermenters with geothermal vent access rights. Capacity expansion and strategic partnerships represent the dominant competitive moves, with shared analytical service cooperatives emerging as a defensive response to regulatory documentation burdens.
Among integrated chemical conglomerates, BASF and Evonik Industries exemplify the biotechnology platform archetype, leveraging scale advantages in biomass supply chain security. Seppic occupies a position within the stabilization technology tier, while Croda International anchors the lipid encapsulation specialist segment. These named entities represent competitive positioning patterns rather than specific strategic commitments, with each archetype facing distinct pressure points from coastal sourcing constraints and clinical dermatology channel bioavailability thresholds.
| Leading Market Players |
|---|
| BASF |
| Croda International |
| Evonik Industries |
| Seppic |
| Givaudan |
| Ashland |
| Lubrizol |
| Solabia Group |
| Lucas Meyer Cosmetics |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal biodegradability incentives gate both qualified supply and premium-tier pricing access for marine thermal water ferments, as REACH-compliant extracts command preferential procurement scoring in French and German public wellness tenders while excluding non-certified suppliers from margin pools above 15% polyphenol grades.
Pricing Analysis
Certificate-of-analysis warranty bundling separates peptide-standardized concentrates from commodity powder extracts, with documentation of full metabolite characterization now standard for clinical dermatology channels. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with ISO 16128 natural origin documentation adding 14-18 month audit premiums. Cost compression in mid-tier powder extracts is intensifying because shared analytical service cooperatives in Brittany and Provence defray compliance burdens. Wellness tourism operators in Hokkaido and Jeju Island show least price sensitivity due to direct-supplier contracting for proprietary treatment protocols.
Supply Chain Analysis
France's ANSM cosmetic ingredient guidelines and South Korea's MFDS microbiome safety protocols are reshaping sourcing toward certified biotech fermenters with documented biomass provenance. Supply concentrates in Mediterranean coastal zones, South Korean Jeju Island facilities, and Japanese Hokkaido geothermal vent operations. Raw material dependencies draw from extremophile microorganism harvests, phospholipid encapsulation inputs, and cold-chain logistics infrastructure. Single-source vulnerability runs through coastal marine protected area access restrictions that constrain raw material predictability. Distribution runs through direct sales channels for wellness tourism procurement and specialty stores for premium cosmetic retail in France and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story, with REACH substance registration requirements and ISO 16128 certification timelines creating a 14-24 month barrier-to-entry moat that filters out small-batch artisan fermenters and concentrates procurement among documented biotech specialists.
For Market Incumbents: Extend analytical service cooperative networks to defray REACH documentation burdens for Brittany and Provence artisan fermenters facing consolidation pressure. Extend captive fermentation partnerships with Mediterranean geothermal vent facilities to secure biomass supply chain security against coastal protected zone access restrictions. BASF and Croda International anchor competitive positioning through integrated biotechnology platforms and lipid encapsulation expertise respectively. For New Entrants and Emerging Players: Launch via direct-supplier contracting models targeting wellness tourism operators in Hokkaido and Jeju Island, where thermal spring traditions intersect with specification-grade procurement above 15% polyphenol concentration. Launch modular 5,000-liter continuous flow bioreactor installations in inland Germany and the Netherlands to bypass coastal sourcing constraints. Spa therapy applications represent the most penetrable consumption segment as wellness tourism procurement rotates toward marine-based treatment protocols. For Investors and Strategic Acquirers: MFDS microbiome safety protocol tightening in South Korea is the leading indicator that regulatory divergence between EU and Asian compliance pathways will deepen, favoring suppliers with dual-certification capabilities. Acquisition targets should concentrate on boutique biotech fermenters with geothermal vent access rights and documented REACH compliance, positioned for 5-10 year horizon viability as ISO 16128 natural origin standards tighten globally. Watch for CRISPR-edited extremophile strain development announcements from Greater Boston biotechnology clusters as the inflection signal for synthetic biology convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Shared Analytical Service Cooperative Formation | Brittany and Provence artisan fermenters defray REACH compliance costs through pooled testing capabilities. |
| Captive Geothermal Vent Partnership | Mediterranean biomass supply security anchors consistent polyphenol concentration above 15% thresholds. |
| Modular Bioreactor Geographic Expansion | German and Dutch cosmetic manufacturers adopt inland 5,000-liter systems at twice prior installation pace. |
| Direct-Supplier Contracting Channel | Japanese onsen resorts and South Korean jjimjilbang chains bypass traditional cosmetic ingredient distributors. |
| CRISPR-Edited Strain Development Program | Greater Boston biotechnology clusters pursue novel metabolite profiles unattainable through wild-type harvesting. |
Research Methodology
Multi-period observation of polyphenol concentration standardization, peptide yield documentation, and coastal biomass supply agreements anchored the trend analysis, supplemented by interviews with fermentation specialists, cosmetic formulation R&D directors, wellness tourism procurement managers, and regulatory affairs leads at REACH-registered suppliers. Secondary validation drew from ECHA substance registration databases, ANSM cosmetic ingredient filings, MFDS microbiome safety protocol submissions, and ISO 16128 audit cycle records. Bottom-up triangulation across product format volumes and top-down reconciliation against end-use consumption patterns ensured cross-verification.
Segment-weighting across powder extracts, liposomal formulations, liquid concentrates, hydrosol solutions, and gel emulsions informed value allocation, with application splits across skincare, spa therapies, anti-aging, cosmetics, and dermatological treatments further refining the analytical framework. CAGRs were derived through trend extrapolation of procurement concentration in France, South Korea, and Japan, adjusted for regulatory compliance timeline impacts and wellness tourism operator specification-grade purchasing patterns. Continuous flow fermentation system adoption rates and CRISPR-edited extremophile strain development milestones served as industry-specific forecast inputs.
Coastal biomass volatility from marine protected zone designations, regulatory divergence between EU biodegradability criteria and Asian microbiome safety protocols, and peptide biochemistry talent scarcity concentrated in fewer than twelve academic programs worldwide are the dominant revision risks that could alter trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.