
 Curculin Market | 2026-2036
Curculin Market Size, Share, and Industry Trends Forecast 2026-2036
Curculin Market Outlook
Health-conscious consumers are rotating toward natural protein sweeteners in home kitchens and commercial foodservice. SweetGenics Inc. leverages proprietary extraction methods to secure premium positioning in specialty retail channels. BioFlavor Solutions anchors its competitive stance through deep partnerships with Japanese ingredient distributors. Curculin Biotech differentiates by concentrating on pharmaceutical-grade purity standards for nutraceutical clients.
Curculin is a sweet protein extracted from the fruit of Curculigo latifolia, composed of two distinct subunits that create both sweetness and a taste-modifying effect that makes sour flavors taste sweet at concentrations near 0.1 mg/mL. Its primary commercial purpose is to serve as a zero-calorie, heat-stable sweetening agent in reduced-sugar food and beverage formulations. Powder formulations currently dominate manufacturing throughput due to superior shelf stability and ease of bulk handling. Liquid curculin extracts are gaining traction in beverage manufacturing lines seeking direct-pump integration. Nutraceutical applications in tablet and capsule formats command premium positioning among health enthusiasts pursuing clean-label supplement regimens.
FDA GRAS status determinations and EFSA novel food consultations shape market access timelines for curculin suppliers targeting North America and Europe. Japan's Ministry of Health, Labour and Welfare maintains established approval pathways for protein-based sweeteners that reduce regulatory friction for domestic producers. Stakeholders must monitor fermentation yield improvements and evolving clean-label certification standards to capture margin expansion in this niche protein sweetener category.
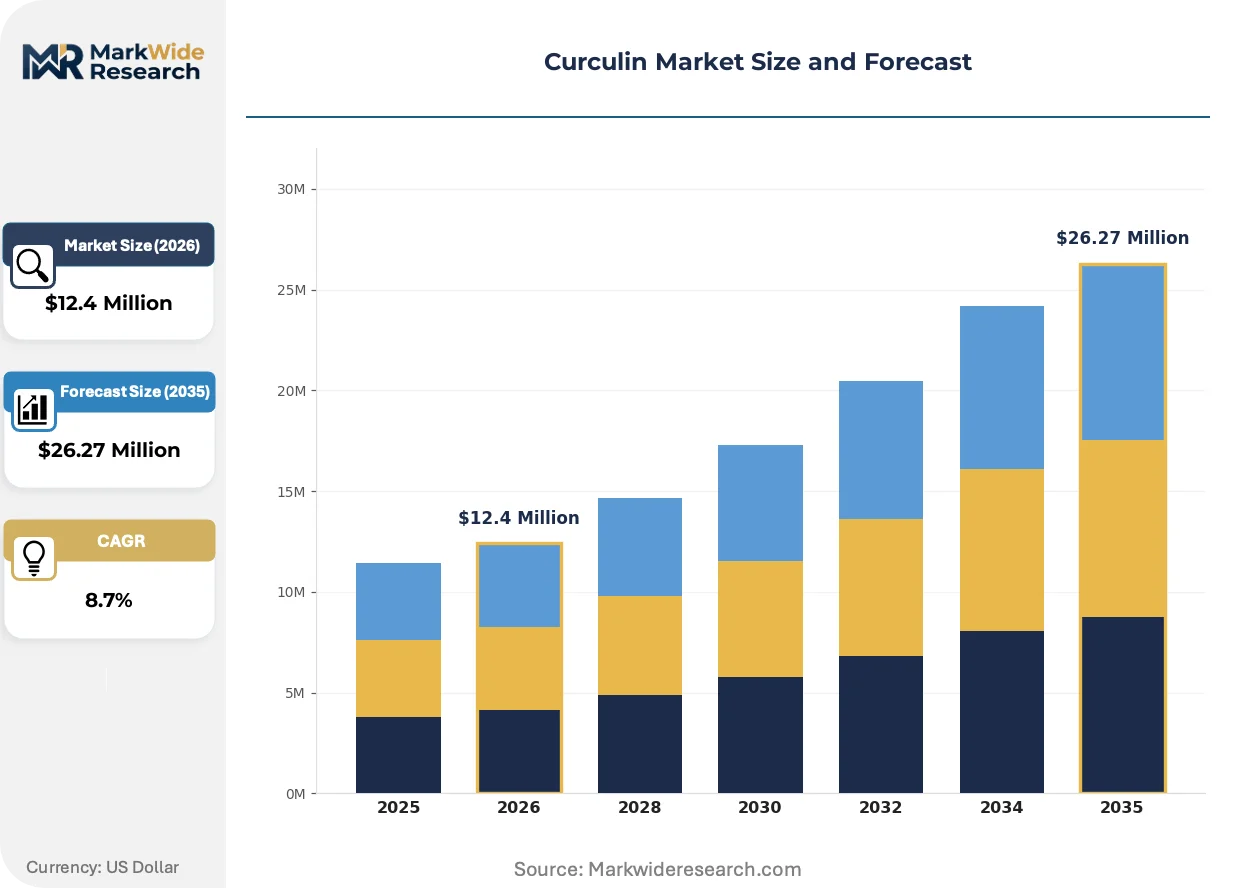
Market Dynamics
Microbial fermentation platforms are compressing production economics for curculin suppliers, enabling price parity with plant-derived sweeteners while expanding addressable formulation applications beyond premium beverage niches.
Growth Catalysts
- Clean-label mandates:EFSA novel food consultation pathways are accelerating regulatory clarity for protein sweeteners in European reduced-sugar product lines.
- Fermentation yield advances:Yeast-based expression systems now achieve titers above 5 g/L, collapsing unit economics for industrial-scale curculin production.
- Beverage manufacturer procurement:Japanese soft drink producers are qualifying curculin for heat-treated carbonated formulations previously restricted to synthetic sweeteners.
Market Restraints
- Input cost volatility:Pharmaceutical-grade nitrogen sources and defined growth media constitute 60% of variable fermentation costs, exposing margins to agricultural commodity swings.
- Supply concentration risk:Over 80% of research-grade curculin originates from Japanese biotech suppliers, creating single-source vulnerability for Western formulation houses.
- Thermal stability ceiling:Curculin denatures above 80°C, excluding its use from ultra-high-temperature processed dairy and retort-pouched meals.
Strategic Opportunities
- Underpenetrated confectionery channels:German chocolate manufacturers are piloting curculin in bean-to-bar formulations targeting diabetic-friendly premium segments.
- Regulatory tailwind:Japan's Ministry of Health, Labour and Welfare is streamlining FOSHU (Foods for Specified Health Uses) approvals for protein-based sweeteners with documented glycemic benefits.
- Technology convergence:Encapsulation with modified starch matrices is masking curculin's lingering aftertaste, opening savory sauce applications where sweetness modulation was previously impossible.
Industry Challenges
- Fermentation specialist scarcity:Qualified bioprocess engineers with protein purification expertise command 40% salary premiums, constraining capacity expansion timelines.
- GRAS self-determination complexity:FDA notification pathways require 180-day safety dossier reviews that delay North American commercial launches by 12-18 months versus Japanese domestic timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Curculin Market |
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $26.27 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Tablets, Capsules Application: Food Industry, Beverage Manufacturing, Nutraceuticals, Culinary Arts Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale End User: Consumers, Food Manufacturers, Chefs, Health Enthusiasts |
| Companies Covered | SweetGenics Inc., BioFlavor Solutions, Nature's Protein, Curculin Biotech, FlavorSweet Labs, NeoTaste Innovations, ProteinSweet Dynamics, BioSweet Extracts, TasteGenix Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Curculin Market Strategic Shifts
Curculin production technology is bifurcating between precision fermentation startups and established extraction houses, with each pathway pursuing distinct purity grades and cost structures.
Precision fermentation using engineered Komagataella pastoris strains is fragmenting the supplier base. Contract development and manufacturing organizations in South Korea and Singapore are commissioning dedicated sweet-protein suites. This technology is enabling pharmaceutical-grade purity at commodity price points, compressing margins for legacy Malaysian extraction operations.
EFSA's 2023 guidance on protein sweetener allergenicity assessments is reshaping dossier requirements. Manufacturers must now submit IgE-binding studies and cross-reactivity data for novel protein structures. European beverage formulators are responding by sequencing curculin variants with reduced immunogenic epitopes before commercial submission.
Direct-to-manufacturer ingredient sourcing is displacing traditional distributor intermediaries in North America. Large beverage conglomerates are establishing preferred supplier agreements with fermentation houses, bypassing regional ingredient brokers. This pattern is most visible in California and Texas, where clean-label beverage startups are consolidating procurement under single-source contracts with yield guarantees.
Curculin Market Segmentation
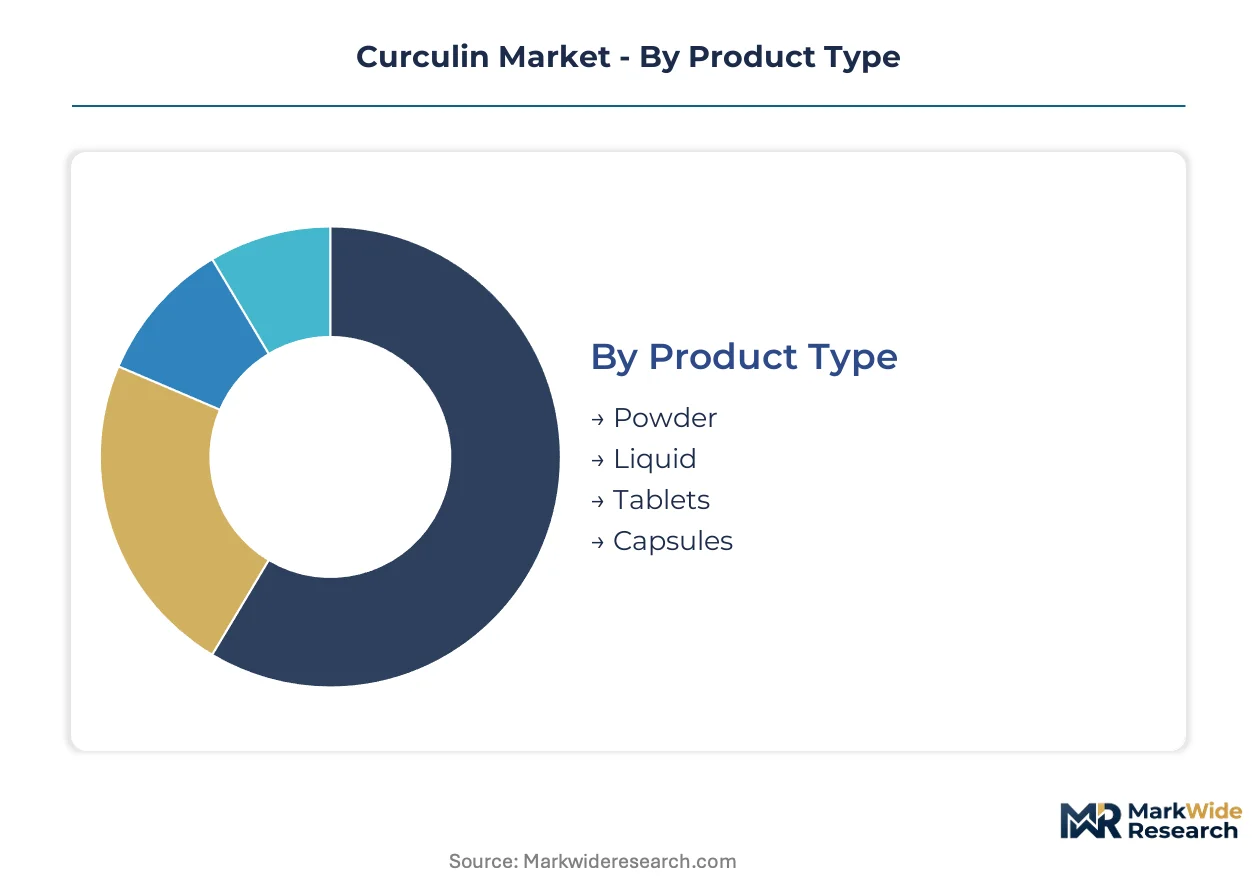
Curculin's commercial trajectory hinges on matching formulation formats to channel economics and end-use thermal requirements. Powder and liquid variants serve divergent manufacturing footprints, while application segments split between industrial procurement and direct consumer access.
Product Type:
Powder formulations flow through wholesale and bulk ingredient channels to food manufacturers, while liquid extracts integrate directly into beverage production lines with pump-compatible dosing systems.
- Powder:Composed of spray-dried curculin protein with moisture content below 5% for extended shelf stability. Food manufacturers in Japan and South Korea dominate procurement for reduced-sugar confectionery and baked goods, driven by clean-label reformulation mandates from retail chains.
- Liquid:Aqueous extracts standardized to 0.1-0.5 mg/mL protein concentration with preservative systems for refrigerated distribution. Beverage manufacturers in California and Texas are qualifying liquid curculin for direct-injection sweetening in cold-filled functional drinks, constrained by thermal denaturation limits below 80°C.
- Tablets:Compressed curculin with excipient binders for precise dosing in supplement regimens, distributed through online retail and specialty nutrition stores.
- Capsules:Gelatin or plant-based shell encapsulation masking protein aftertaste, targeting health enthusiasts via direct-to-consumer subscription channels.
Powder dominates installed base. Liquid is where expansion concentrates.
Application:
Cost tiers separate commodity-scale industrial procurement from premium-positioned nutraceutical and culinary segments, with thermal processing requirements determining viable entry points.
- Food Industry:Industrial bakeries and sauce manufacturers incorporate curculin into heat-stable formulations below 80°C, with German chocolate producers piloting bean-to-bar diabetic-friendly lines. EFSA novel food consultation timelines shape European adoption velocity.
- Beverage Manufacturing:Japanese soft drink producers lead qualification for carbonated and still beverages, leveraging established Ministry of Health, Labour and Welfare approval pathways for protein sweeteners. Heat-treated applications remain restricted by denaturation thresholds.
- Nutraceuticals:Tablet and capsule formats command premium positioning among supplement brands pursuing pharmaceutical-grade purity certifications for glycemic management claims.
- Culinary Arts:Specialty retail channels supply molecular gastronomy practitioners and home kitchens with small-format powders for taste-modifying applications.
Beverage Manufacturing anchors procurement volume. Nutraceuticals is climbing the fastest.
Distribution Channel:
Customer type dictates channel selection, with food manufacturers bypassing intermediaries through direct fermentation house contracts while consumers access curculin through fragmented retail and digital pathways.
- Online Retail:Direct-to-consumer platforms serve health enthusiasts and home cooks with subscription models for powder and capsule formats, bypassing traditional ingredient brokers.
- Specialty Stores:Nutrition retailers and culinary supply shops curate premium-positioned curculin for clean-label adherents and professional chefs seeking taste-modifying ingredients.
- Supermarkets:Mass retail placement remains limited to blended sweetener products where curculin appears as a secondary ingredient, constrained by consumer education gaps.
- Wholesale:Bulk ingredient distributors supply food and beverage manufacturers with powder and liquid formats, though direct sourcing is displacing regional brokers in North America.
Wholesale captures industrial volume. Online Retail is gaining share fastest.
End User:
Volume concentration sits with industrial procurement, while margin expansion concentrates in specialized professional and enthusiast segments with technical sophistication and price tolerance.
- Consumers:Home kitchen users access curculin through online retail and specialty stores, primarily for low-temperature applications like smoothies and no-bake desserts where taste-modifying effects are most pronounced.
- Food Manufacturers:Industrial procurement from Japanese, South Korean, and North American production facilities drives bulk demand, with fermentation yield improvements compressing unit economics for large-scale formulation.
- Chefs:Professional culinary practitioners in premium foodservice leverage curculin for innovative menu applications, sourcing through specialty distributors with technical support for optimal dosing protocols.
- Health Enthusiasts:Supplement-focused consumers pursuing clean-label regimens drive capsule and tablet demand, with glycemic benefit documentation influencing purchase decisions.
Food Manufacturers dominate procurement scale. Health Enthusiasts is where premium positioning concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Yokohama's cold-chain infrastructure underwrites Japan's dominance in curculin research-grade supply, while the Trans-Pacific fiber links connecting California fermentation houses to Asian bioprocess engineering talent reshape procurement geography.
Japan
Established FOSHU approval pathways and Ministry of Health, Labour and Welfare regulatory familiarity accelerate domestic adoption. Tokyo and Osaka biotech clusters concentrate precision fermentation capacity for pharmaceutical-grade production. Kansai region extraction houses maintain legacy supply relationships with Malaysian Curculigo latifolia cultivators.
United States
California beverage startups and Texas functional drink manufacturers drive liquid curculin qualification for cold-filled applications. FDA GRAS self-determination timelines extend North American commercial launches 12-18 months versus Japanese benchmarks. San Diego and Austin fermentation facilities anchor preferred supplier agreements with direct-to-manufacturer procurement models.
Germany
Bean-to-bar chocolate manufacturers in Cologne and Hamburg pilot diabetic-friendly formulations using heat-stable curculin below 80°C thresholds. EFSA novel food consultation requirements for IgE-binding studies reshape dossier preparation. Bavarian ingredient distributors serve as European entry points for Japanese research-grade supply.
South Korea
Contract development and manufacturing organizations in Incheon and Songdo commission dedicated sweet-protein fermentation suites. MFDS regulatory alignment with protein-based sweetener safety assessments supports faster qualification than European timelines. Seoul-based bioprocess engineers command salary premiums that constrain capacity expansion velocity.
Singapore
Strategic positioning as ASEAN bioprocess hub attracts precision fermentation investments targeting pharmaceutical-grade purity at commodity economics. Jurong Island industrial infrastructure supports scale-up from pilot to commercial titers above 5 g/L. Government-backed food technology accelerators reduce capital barriers for curculin startup formation.
Curculin Market Competitive Environment
Concentration sits with fermentation technology specialists and established extraction houses, creating a bifurcated supplier base. Tier-one players leverage proprietary yeast expression systems, while legacy operators defend Malaysian agricultural supply relationships. Strategic archetypes include precision fermentation startups, Curculigo latifolia extraction specialists, and contract manufacturing organizations with dedicated sweet-protein capacity. Competitive moves center on yield improvement patent filings and direct preferred supplier agreements with North American beverage conglomerates.
Within the fermentation technology tier, SweetGenics Inc. and Curculin Biotech exemplify divergent purity-grade positioning, while BioFlavor Solutions anchors distributor partnership strategies. SweetGenics occupies a position among extraction-method innovators targeting specialty retail channels. Curculin Biotech represents pharmaceutical-grade purity concentration for nutraceutical clientele. BioFlavor Solutions exemplifies geographic anchoring through Japanese distributor relationships. These three archetypes illustrate how competitive positioning fragments across technical sophistication, regulatory navigation capability, and channel access depth.
| Leading Market Players |
|---|
| SweetGenics Inc. |
| BioFlavor Solutions |
| Nature's Protein |
| Curculin Biotech |
| FlavorSweet Labs |
| NeoTaste Innovations |
| ProteinSweet Dynamics |
| BioSweet Extracts |
| TasteGenix Corp. |
| Others |
Value Chain & Pricing Dynamics
FDA GRAS self-determination pathways gate both supply qualification timelines and price differentiation between Japanese-origin and North American-produced curculin. This regulatory filter compresses margins for entrants facing extended safety dossier reviews while rewarding incumbent fermentation houses with established compliance track records.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade purity certifications from commodity food-grade batches. Pharmaceutical-grade curculin commands substantial premia due to IgE-binding documentation requirements under EFSA novel food consultations. Cost compression in standard-grade powder runs through microbial fermentation yield improvements exceeding 5 g/L. Beverage manufacturers exhibit highest price sensitivity due to direct-injection dosing economics, while nutraceutical brands absorb premia for documented glycemic benefit substantiation.
Supply Chain Analysis
Inbound logistics costs from Yokohama cold-chain infrastructure elevate landed costs for Western formulation houses sourcing research-grade material. Supply concentrates in Japan, South Korea, and Singapore, with Malaysian Curculigo latifolia cultivators feeding legacy extraction operations. Pharmaceutical-grade nitrogen sources and defined growth media constitute critical input dependencies. Single-source vulnerability pervades the research-grade segment where Japanese biotech suppliers dominate. Distribution runs through direct preferred supplier agreements displacing regional ingredient brokers in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified bioprocess engineers with protein purification expertise command substantial salary premiums, constraining capacity expansion timelines for fermentation houses and creating persistent bottlenecks in scaling pharmaceutical-grade production.
For Market Incumbents: Compound yield improvement advantages through proprietary Komagataella pastoris strain development and patent filings on modified starch encapsulation matrices. Defend position against precision fermentation startups by securing long-term offtake agreements with Japanese beverage conglomerates. Vertical integration into Malaysian agricultural supply relationships insulates against raw material cost volatility. For New Entrants and Emerging Players: Differentiate on regulatory navigation speed by pre-submission engagement with EFSA novel food consultation pathways before commercial scale-up. Target German bean-to-bar chocolate manufacturers as the most penetrable confectionery segment given pilot program momentum. Pursue direct-to-manufacturer ingredient sourcing models bypassing traditional distributor intermediaries in California and Texas beverage clusters. For Investors and Strategic Acquirers: FDA GRAS determination timelines reshaping the acquisition landscape toward fermentation technology specialists with established safety dossiers rather than extraction legacy operators. Five-to-ten year viability favors precision fermentation platforms achieving pharmaceutical-grade purity at commodity economics. Monitor EFSA protein sweetener allergenicity guidance implementation as the critical inflection signal for European market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Komagataella pastoris titers above 5 g/L collapse unit economics for industrial production. |
| Regulatory Dossier Advancement | FDA GRAS notifications and EFSA novel food consultations determine market access timelines. |
| Encapsulation Technology Development | Modified starch matrices masking aftertaste open savory sauce applications previously inaccessible. |
| Direct Supplier Agreement Formation | Preferred contracts with North American beverage conglomerates displace regional ingredient brokers. |
| FOSHU Approval Pathway Navigation | Japan's Ministry of Health, Labour and Welfare streamlining accelerates protein sweetener commercialization. |
Study Parameters
Operator-level perspectives from bioprocess engineers, fermentation facility managers, regulatory affairs specialists at sweetener houses, and beverage manufacturer procurement leads anchored the qualitative base. Primary interview data combined with secondary validation from FDA GRAS notification filings, EFSA novel food consultation records, Japanese Ministry of Health FOSHU approval databases, and South Korean MFDS regulatory guidance documents. Bottom-up capacity estimates from identified fermentation facilities triangulated against top-down demand projections from beverage and nutraceutical formulation pipelines.
Sensitivity analysis tested forecast robustness across fermentation yield improvement scenarios and regulatory approval timeline variations over the projection horizon. Segmentation modeling incorporated product type, application vertical, distribution channel structure, and geographic regulatory cluster dimensions. CAGRs derived from slope-log regression on normalized capacity expansion and demand uptake curves. Industry-specific inputs included pharmaceutical-grade purity certification penetration rates and direct-to-manufacturer procurement displacement patterns.
Material uncertainties — fermentation specialist wage inflation, nitrogen source commodity price swings, and EFSA allergenicity assessment requirement changes — sit outside the modeled envelope. Forecasts reflect documented assumptions about yield improvement trajectories and regulatory consultation durations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Soft Tofu Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Cannabis Infused Drinks Market
Specialty Foods
Acacia Honey Market
Specialty Foods
Human Grade Pet Food Market
Specialty Foods
Halal Products Market
Specialty Foods
Silver Food Market
Specialty Foods
Algeria Couscous Market
Specialty Foods
High Protein Cat Food Market
Specialty Foods
Asia Pacific Pet Milk Replacers Market
Specialty Foods
Halal Market
Specialty Foods
Kelp Noodles Market
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Low Fat and Low Carb Foods Market
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market