
 US Jam Jelly and Preserves Market | 2026-2036
US Jam Jelly and Preserves Market Size, Share, and Industry Trends Forecast 2026-2036
US Jam Jelly and Preserves Market Insights
Subscription-based replenishment models for pantry staples is hardening into a core revenue stream for established brands. The J.M. Smucker Company leverages its direct-to-consumer platform to secure recurring household orders. Welch Foods sustains regional dominance through deep retail partnerships in the Great Lakes and Pacific Northwest. Kraft Heinz competes on manufacturing scale, operating multi-product condiment facilities that spread fixed costs across jam, jelly, and adjacent categories.
Jam, jelly, and preserves constitute shelf-stable fruit spreads produced by cooking fruit pulp or juice with sugar and pectin to achieve gel formation, with final soluble solids typically measured at 65-68 degrees Brix to ensure microbial stability and spreadable texture. These products serve commercial bakeries, food service operators, and retail households as flavor carriers, filling agents, and breakfast accompaniments. Fruit jam occupies the largest volume share among product types, while marmalade commands premium pricing in specialty channels due to bitter-orange sourcing constraints. Glass jar packaging retains preference among premium-positioned brands despite higher logistics costs, whereas plastic containers dominate institutional food service procurement where breakage risk and unit economics drive selection.
The FDA enforces standards of identity under 21 CFR 150 that distinguish jam from jelly based on fruit content thresholds, directly shaping product formulation decisions and label claims across the industry. USDA organic certification and state-level cottage food laws in California, Texas, and New York create parallel compliance pathways that smaller producers navigate for market access. Stakeholders must monitor evolving added-sugar disclosure requirements and state plastic packaging mandates to anticipate reformulation and packaging investment cycles.
Market Dynamics
The FDA's updated Nutrition Facts labeling requirements are forcing mass-market brands toward reduced-sugar reformulation while artisanal producers exploit cottage food law exemptions to bypass scale economies. This regulatory divergence splits competitive strategy between compliance-heavy reformulation and small-batch premium positioning.
Growth Catalysts
- Food service menu expansion:Operators in the Northeast corridor are integrating preserves into savory applications, dessert glazes, and cocktail programs beyond traditional breakfast service.
- 21 CFR 150 standards of identity:FDA enforcement distinguishes jam from jelly based on fruit content thresholds, creating clear formulation guardrails that reduce label claim disputes.
- Subscription replenishment platforms:Direct-to-consumer infrastructure is automating recurring household orders for pantry staples, locking in predictable revenue streams.
Market Restraints
- Bitter-orange sourcing constraints:Marmalade production faces concentrated supply risk from Mediterranean and Florida groves, limiting premium segment expansion.
- Glass jar logistics costs:Premium brands retain breakable packaging despite 15-20% higher freight and damage rates versus plastic alternatives.
- Added-sugar disclosure requirements:Evolving federal and state-level mandates create reformulation uncertainty and label redesign cycles.
Strategic Opportunities
- Reduced-sugar recipe innovation:Reformulation using alternative sweeteners and high-methoxyl pectin systems opens shelf space in health-positioned retail channels.
- Institutional food service procurement:Plastic container formats with superior unit economics are penetrating K-12, healthcare, and contract catering segments.
- USDA organic certification:Premium price realization in specialty retail justifies compliance investment for mid-scale producers.
Industry Challenges
- Pectin chemistry expertise gap:Reformulating for reduced-sugar gels requires specialized food science talent scarce outside established R&D centers.
- Multi-state cottage food compliance:California, Texas, and New York operate divergent exemption thresholds, creating operational fragmentation for small producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Jam Jelly and Preserves Market |
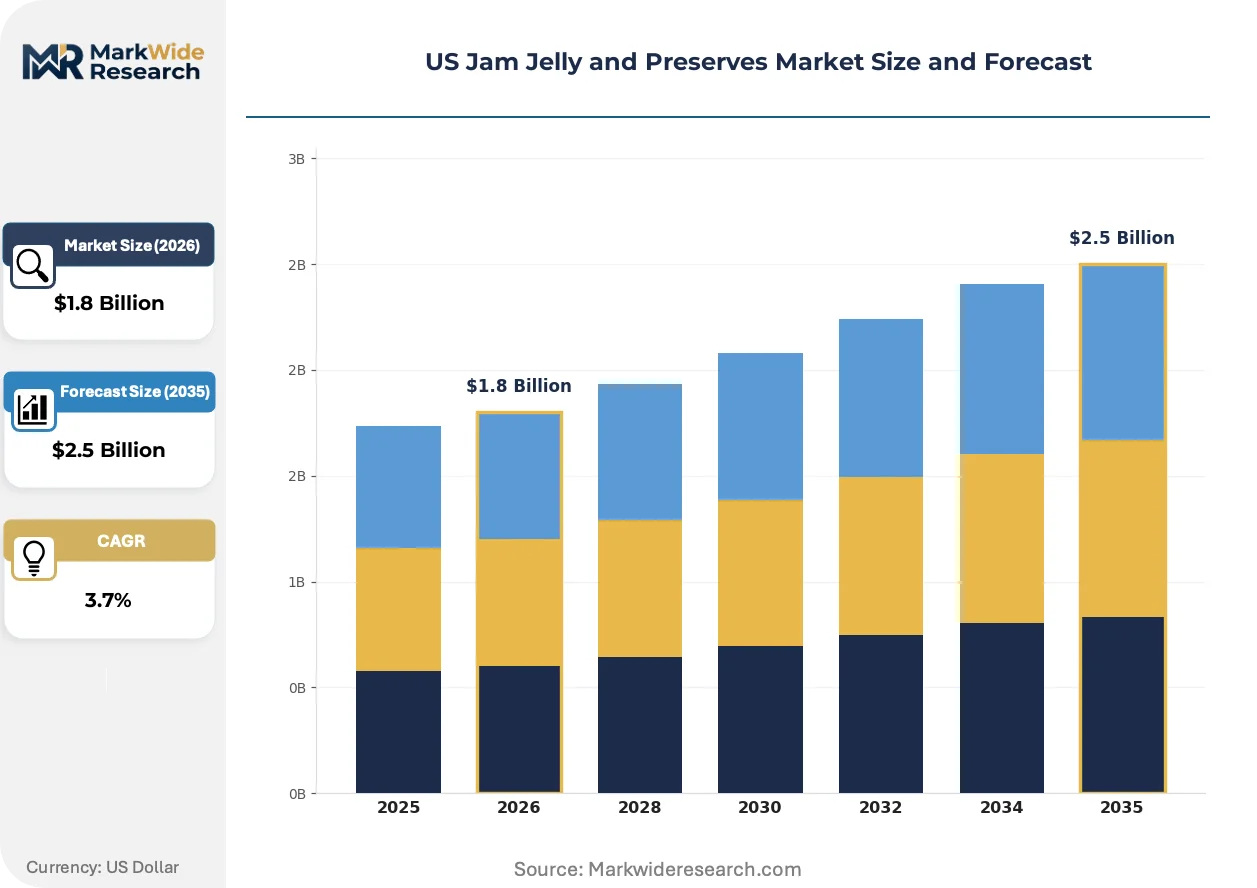
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Jam, Fruit Jelly, Fruit Preserves, Marmalade Packaging Type: Glass Jar, Plastic Container, Sachets, Pouches Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Stores End User: Households, Food Service, Retail, Manufacturers |
| Companies Covered | The J.M. Smucker Company, B&G Foods, Conagra Brands, Kraft Heinz, Andros Group, F. Duerr & Sons, Hero Group, Unilever, Welch Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Jam Jelly and Preserves Market Trends and Innovations
Automation in production monitoring and high-pressure processing is compressing batch variability while regulatory pressure on added-sugar disclosure accelerates clean-label formulation investment.
High-pressure processing technology is automating cold-fill pasteurization for reduced-sugar preserves, eliminating thermal degradation of fruit volatiles. Mid-scale producers in the Pacific Northwest and New England are adopting systems at 12-18 month payback cycles. The technology is automating quality consistency previously requiring senior batch operators, flattening labor cost curves.
FDA enforcement of 21 CFR 150 standards of identity is tightening fruit content verification and label claim scrutiny. Manufacturers must maintain 45-55% soluble fruit solids for jam versus 25-50% for jelly, driving analytical testing investment. Mass-market brands are responding with dual-SKU strategies separating compliant core lines from stretched-identity value tiers.
Pantry replenishment via direct subscription is displacing conventional grocery aisle discovery for repeat purchases. Specialty retailers in the Northeast corridor are unbundling assortment depth to compete, curating local producer rotations. The shift concentrates most visibly among dual-income households in urban coastal markets.
US Jam Jelly and Preserves Market Segmentation
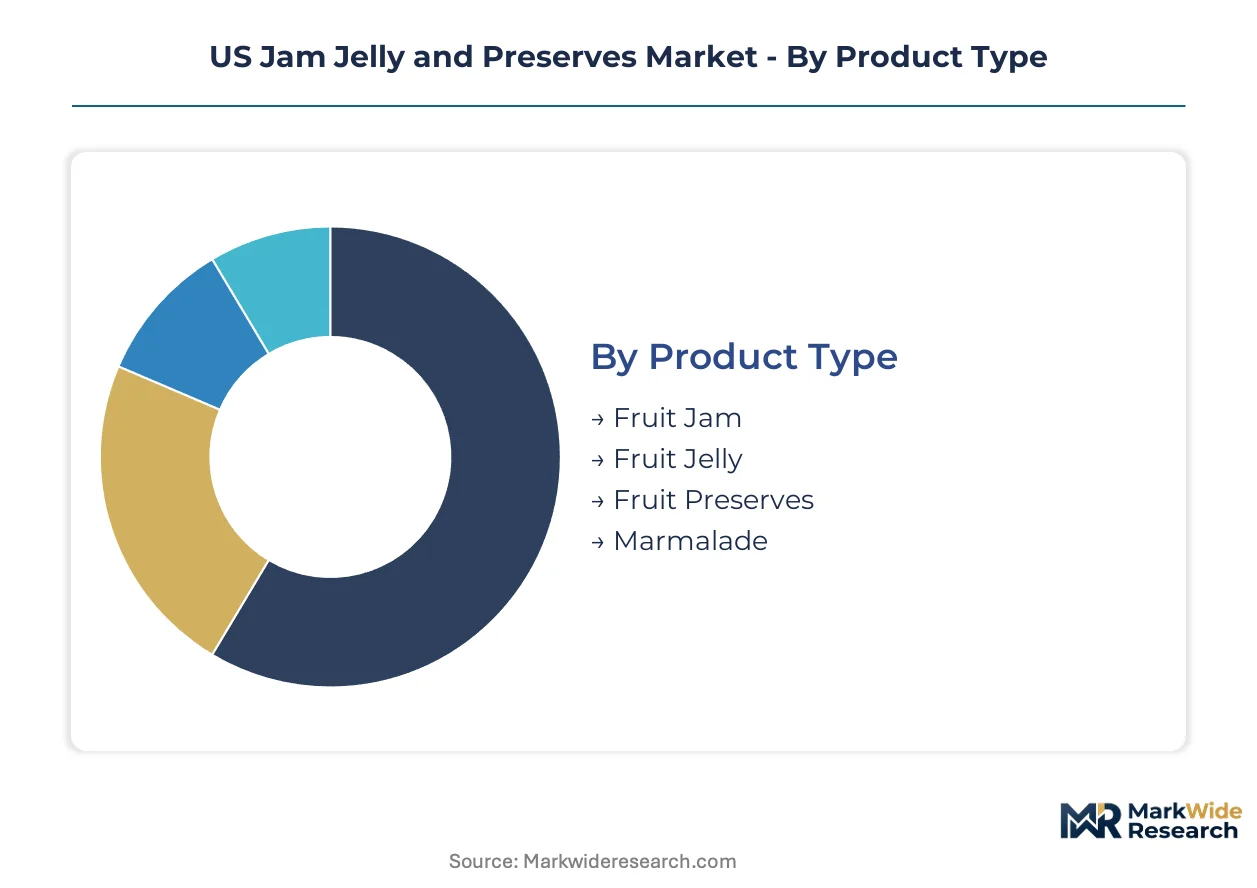
Segmentation in the US jam, jelly, and preserves market reveals how formulation standards, packaging economics, and channel access create distinct competitive arenas. Buyers sort across these dimensions based on price sensitivity, volume requirements, and regulatory compliance burdens.
Product Type:
Buyers in this category differentiate primarily by fruit content thresholds and viscosity specifications that determine end-use versatility.
- Fruit Jam:Contains 45-55% soluble fruit solids per 21 CFR 150, delivering thick, spreadable consistency with visible fruit pieces. Northeast corridor households and commercial bakeries drive demand for this workhorse category, though added-sugar disclosure pressures are forcing reformulation investment.
- Fruit Jelly:Filters out fruit pulp to achieve 25-50% fruit content, yielding clear, firm gels prized for glazing and filling applications. Food service operators in institutional settings favor jelly for its uniform texture and lower cost per serving.
- Fruit Preserves:Maintains whole fruit or large pieces suspended in syrup, commanding premium positioning in specialty retail channels where texture authenticity justifies higher price points.
- Marmalade:Citrus-based spreads with bitter-orange peel inclusions face concentrated Mediterranean and Florida sourcing constraints that limit production scale and geographic expansion.
Fruit jam leads volumes today; marmalade is gaining share fastest in coastal urban markets.
Packaging Type:
Unit economics and breakage risk separate procurement decisions across institutional versus premium retail buyers.
- Glass Jar:Premium-positioned brands retain breakable packaging despite 15-20% higher freight costs and damage rates, leveraging perceived quality cues in Northeast corridor specialty retail.
- Plastic Container:Polypropylene formats dominate K-12, healthcare, and contract catering procurement where drop resistance and lighter shipping weights flatten total delivered cost curves.
- Sachets:Single-serve portions penetrate airline, hotel, and grab-and-go food service channels where portion control and waste reduction outweigh per-unit premium.
- Pouches:Flexible formats with spouts or tear-notches are expanding in online retail and subscription replenishment models where dimensional weight savings reduce last-mile delivery costs.
Glass jar formats anchor revenue per unit; plastic containers are expanding most quickly into institutional segments.
Distribution Channel:
Channel selection determines assortment depth, price transparency, and replenishment velocity for different buyer profiles.
- Supermarkets:Mass-market retailers in the Great Lakes and Pacific Northwest sustain volume throughput via deep promotional calendars and private-label penetration, though shelf space is compressing for mid-tier brands.
- Online Retailers:Direct-to-consumer platforms automate recurring household orders, concentrating among dual-income urban households seeking pantry replenishment without store visits.
- Convenience Stores:Grab-and-go locations capture impulse purchases and travel-oriented demand, typically stocking single-serve and small-format SKUs with higher margins.
- Specialty Stores:Curated assortments in the Northeast corridor emphasize local producer rotations and USDA organic certifications, unbundling depth to compete with subscription platforms.
Supermarkets retain the largest transaction volumes; online retailers are climbing the fastest as replenishment habits shift.
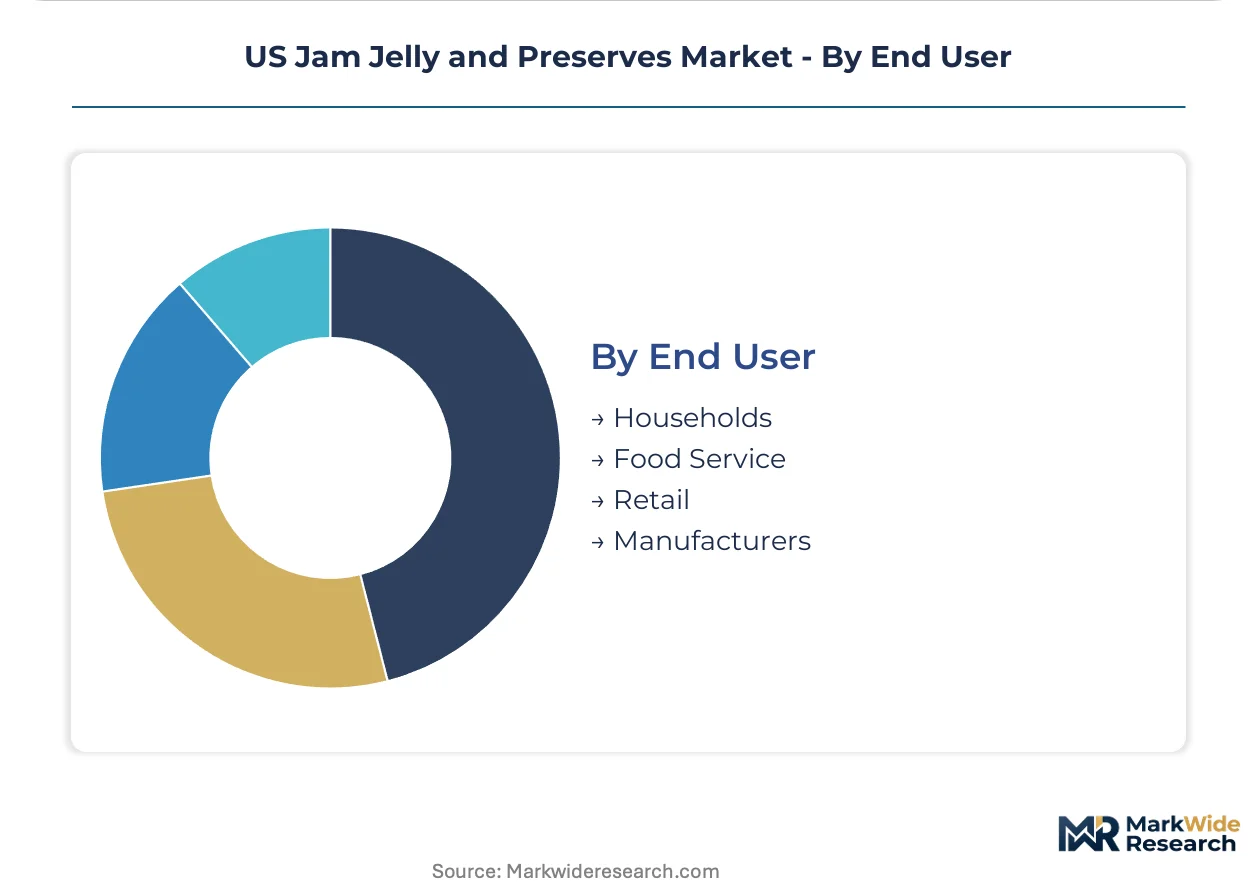
End User:
Volume scale and specification stringency divide this category between household discretionary purchases and commercial procurement with compliance requirements.
- Households:Urban coastal markets concentrate demand for premium artisanal and reduced-sugar varieties, with subscription platforms capturing recurring pantry replenishment.
- Food Service:Operators from quick-service chains to fine-dining establishments integrate preserves into savory applications, dessert glazes, and cocktail programs beyond traditional breakfast service.
- Retail:Private-label programs and store-brand development at major chains create captive demand for co-manufactured products meeting specific price-positioning requirements.
- Manufacturers:Commercial bakeries and processed food producers purchase industrial-scale volumes for use as filling agents, flavor carriers, and ingredient inputs with strict specification tolerances.
Households generate the highest transaction frequency; food service is expanding most quickly as menu applications diversify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northeast corridor commands premium shelf space for artisanal preserves, while Pacific Northwest operators leverage deep fruit sourcing networks to supply private-label programs.
Northeast Corridor
Urban households in Boston and New York Metro drive demand for reduced-sugar and USDA organic certified varieties. FDA enforcement of 21 CFR 150 standards shapes label claims across Massachusetts and Connecticut production facilities. Specialty retailers in Vermont and Maine curate local producer rotations to compete with subscription replenishment platforms.
Pacific Northwest
Washington and Oregon berry growers supply raw material to co-manufacturers serving retail private-label programs. State-level cottage food laws in Oregon enable small-batch producers to access farmers' market channels without commercial kitchen investment. Seattle-based operators are adopting high-pressure processing systems for cold-fill pasteurization of reduced-sugar lines.
Great Lakes
Michigan and Wisconsin fruit processors concentrate on institutional food service procurement for K-12 and healthcare segments. The FDA's updated Nutrition Facts labeling requirements are pushing reformulation toward lower Brix formulations in Chicago-area production facilities. Welch Foods maintains regional dominance through established retail partnerships across Illinois and Ohio.
California
Central Valley fruit processors supply industrial-scale volumes to commercial bakeries and processed food manufacturers. California's cottage food law creates parallel compliance pathways for small producers navigating direct-to-consumer sales. Los Angeles and San Francisco Bay Area operators are expanding into savory application preserves for food service menu innovation.
Southeast
Florida citrus groves face concentrated supply risk for bitter-orange marmalade production. The state's food manufacturing corridor from Tampa to Orlando hosts co-packing facilities serving national retail brands. Georgia and North Carolina processors are expanding plastic container production for contract catering and hospitality procurement.
US Jam Jelly and Preserves Market Competitive Landscape
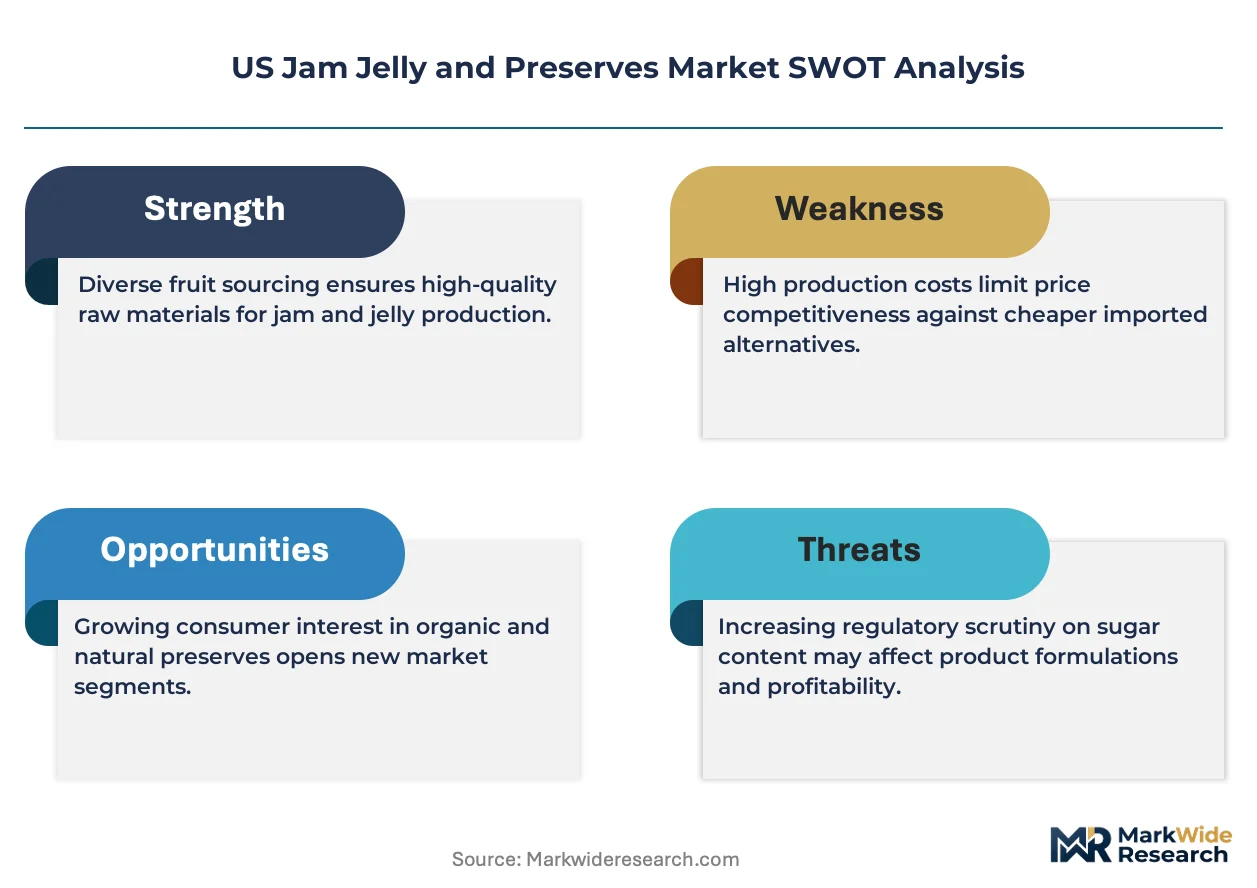
Top-tier vendors anchor mass-market scale, while mid-tier regional specialists and cottage-law exempt artisanal producers fragment the long tail. The market exhibits tiered concentration with three to four national brands controlling supermarket shelf space alongside hundreds of small-batch operators. Strategic archetypes separate into scale-driven condiment conglomerates, regional fruit processors with deep agricultural ties, and direct-to-consumer subscription platforms. Competitive moves center on reduced-sugar reformulation investment and direct-to-consumer infrastructure buildout.
Among scale-driven manufacturers, The J.M. Smucker Company, Kraft Heinz, and Welch Foods occupy positions representing distinct competitive vectors. Smucker exemplifies the subscription-platform archetype through direct-to-consumer replenishment automation. Kraft Heinz represents manufacturing-scale efficiency through multi-product condiment facility operations. Welch Foods anchors regional dominance through agricultural integration in the Great Lakes and Pacific Northwest.
| Leading Market Players |
|---|
| The J.M. Smucker Company |
| B&G Foods |
| Conagra Brands |
| Kraft Heinz |
| Andros Group |
| F. Duerr & Sons |
| Hero Group |
| Unilever |
| Welch Foods |
| Others |
Pricing and Supply Chain Analysis
Bitter-orange procurement costs cascade through marmalade production tiers, concentrating pricing power among Florida and Mediterranean grove operators while forcing reformulation trade-offs in reduced-sugar segments downstream.
Pricing Analysis
Capacity additions in Pacific Northwest berry processing are reshaping price floors for fruit jam inputs. Three-tier pricing structure across premium artisanal, standard retail, and economy private-label levels stratifies by USDA organic certification and glass jar packaging. Pricing pressure stems from FDA-mandated added-sugar disclosure compliance costs. Institutional food service buyers exhibit highest price sensitivity; Northeast corridor specialty retailers show lowest.
Supply Chain Analysis
Return flows of damaged glass jars from retail channels feed regional recycling networks that supply packaging back to co-manufacturers. Raw material sourcing draws from Washington and Oregon berry growers, Florida citrus groves, and Central Valley fruit processors. Pectin supply rests on citrus peel extraction concentrated in California and Texas facilities. Single-source vulnerability runs through Mediterranean bitter-orange imports for marmalade. Distribution runs through multi-product condiment facilities spreading fixed costs across jam, jelly, and adjacent categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity as FDA's updated Nutrition Facts labeling requirements drive reformulation investment cycles that favor compliance-capable scale operators.
For Market Incumbents: Extend reduced-sugar R&D capabilities to capture shelf space in health-positioned retail channels before cottage food law exempt producers consolidate. Threaten margin compression from high-pressure processing technology adoption by Pacific Northwest mid-scale competitors. Leverage vertical integration into berry sourcing networks to secure input cost stability. For New Entrants and Emerging Players: The mid-tier price gap between premium artisanal and mass-market economy tiers offers white-space entry through subscription-based replenishment models targeting dual-income urban households. Penetrate Pacific Northwest farmers' market channels enabled by Oregon cottage food law exemptions. Deploy direct-to-consumer infrastructure to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where cottage food law exempt producers face multi-state compliance fragmentation that exceeds operational bandwidth. Five-to-ten year viability favors acquisition targets with USDA organic certification and established direct-to-consumer platforms. Monitor FDA enforcement intensity on 21 CFR 150 fruit content verification as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Reduced-Sugar Reformulation Investment | Captures shelf space in health-positioned Northeast corridor specialty retail channels. |
| Direct-to-Consumer Platform Buildout | Locks in recurring revenue from dual-income urban households via subscription automation. |
| High-Pressure Processing Adoption | Enables cold-fill pasteurization for reduced-sugar lines without thermal degradation. |
| USDA Organic Certification Pursuit | Commands premium price realization in curated specialty store rotations. |
| Plastic Container Format Expansion | Penetrates K-12 and healthcare institutional procurement with superior unit economics. |
Research Methodology
Coverage spans Northeast corridor, Pacific Northwest, Great Lakes, California, and Southeast regions, with primary inputs from each. The analysis combines interviews with brand managers, category buyers at supermarkets, supply planners at co-manufacturers, and regulatory affairs specialists with secondary validation from FDA 21 CFR 150 filings, USDA organic certification databases, Nielsen retail audit data, and state cottage food law statutes. Bottom-up volume modeling and top-down value triangulation reconcile segment outputs.
Granularity-level framing models product type, packaging format, distribution channel, and end user at the SKU level across the projection horizon. CAGRs derive from trend extrapolation of subscription platform adoption rates, food service menu expansion velocity, and reformulation cost pass-through elasticity. Forecast inputs include high-pressure processing equipment installation cycles and FDA enforcement intensity indices.
Caveats apply where bitter-orange supply disruptions or state-level plastic packaging mandates could materially shift the outlook. Forecasts reflect assumptions on cottage food law stability and pectin chemistry talent availability. Practitioners should monitor FDA added-sugar disclosure rulemaking and Pacific Northwest high-pressure processing adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Cat Food Flavors Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Natto Market
Specialty Foods
Asia-Pacific Tofu Market
Specialty Foods
Wheatgrass Products Market
Specialty Foods
Asia Pacific Cat Food Market
Specialty Foods
North America Popping Boba/Juice Balls Market
Specialty Foods
Low Calorie Diet Meal Plan Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Areca Bowl Market
Specialty Foods
Low Calorie Hummus Market
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
Hairball Cat Food Market
Specialty Foods
Halal Products Market
Specialty Foods
Grain-Free Pet Food Market
Specialty Foods
Global Ethnic Foods Market