
 North America Hummus Market | 2026-2036
North America Hummus Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hummus Market Analytics
The U.S. Food and Drug Administration's updated Nutrition Facts labeling requirements is decoupling consumer preference from legacy formulations built on preservatives and artificial stabilizers. Sabra Dipping Company, LLC leverages its refrigerated distribution network to sustain national retail penetration. Cedar's Mediterranean Foods anchors its position through regional manufacturing scale in the Northeast corridor. Tribe Mediterranean Foods differentiates via flavor innovation pipelines targeting younger demographics.
Hummus is a chickpea-based spread or dip produced by cooking, grinding, and blending chickpeas with tahini, lemon juice, garlic, and olive oil to a smooth or textured consistency with a shelf life typically ranging from thirty to sixty days under refrigeration. The product serves as a protein-rich alternative to dairy-based dips in both retail and food service channels. Traditional formulations currently occupy the largest volume share within Product Type segments, though Organic variants are capturing margin pools as certification premiums widen. Single-Serve packaging within the Packaging Type dimension is expanding fastest, driven by grab-and-go consumption patterns in urban convenience retail.
The U.S. Food and Drug Administration enforces nutrition labeling and allergen disclosure standards that directly shape ingredient sourcing and front-of-package claims across the category. Health Canada and the Canadian Food Inspection Agency impose parallel requirements that condition cross-border product standardization for manufacturers operating in both markets. The U.S. Department of Agriculture's organic certification framework creates tiered market access costs that favor scaled processors with dedicated supply chain compliance teams. Stakeholders must monitor evolving plant-based protein labeling standards as regulatory definitions tighten and competitor positioning shifts accordingly.
Market Dynamics
The U.S. Food and Drug Administration's updated Nutrition Facts labeling requirements are compressing formulation timelines and forcing ingredient deck simplification across refrigerated and shelf-stable hummus portfolios. Manufacturers must now reconcile legacy preservative systems with clean-label mandates while maintaining sixty-day refrigerated shelf stability.
Growth Catalysts
- West Coast metropolitan corridor demand:Los Angeles, San Francisco, and Seattle food service channels are normalizing hummus as a protein-forward menu staple, pulling volume through restaurant supply chains into retail awareness.
- USDA organic certification tiering:The certification framework creates margin expansion pathways for processors with dedicated compliance infrastructure, widening price realization gaps between conventional and certified organic SKUs.
- Single-serve packaging automation:High-speed portioning and sealing equipment is reducing unit economics for grab-and-go formats, accelerating placement in urban convenience retail.
Market Restraints
- Tahini input cost volatility:Sesame seed supply concentration in East African and Middle Eastern origins exposes margin structures to climate-driven harvest variability and currency fluctuation.
- Refrigerated last-mile density thresholds:Cold chain infrastructure gaps in secondary U.S. metropolitan markets limit distribution radius expansion without co-manufacturing partnerships.
- Chickpea protein substitution elasticity:Greek yogurt and nut-based spreads compete for the same refrigerated dip occasion, constraining price elasticity in conventional product tiers.
Strategic Opportunities
- Canadian regulatory harmonization:Health Canada and the Canadian Food Inspection Agency standards alignment with U.S. FDA frameworks reduces cross-border SKU complexity for integrated North American production.
- Food service bulk format penetration:Institutional and college dining channels represent under-tapped volume pools for neutral-base hummus as a recipe ingredient rather than finished dip.
- High-pressure processing convergence:Cold pasteurization technology paired with modified atmosphere packaging extends shelf life without thermal degradation, enabling clean-label positioning at conventional price points.
Industry Challenges
- Food safety culture capability gaps:Mid-tier processors face talent scarcity in preventive controls qualified individual (PCQI) certification required under FDA Food Safety Modernization Act enforcement.
- Legacy ERP integration friction:Lot traceability and recall management systems require capital-intensive upgrades to meet electronic record-keeping mandates for supply chain transparency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hummus Market |
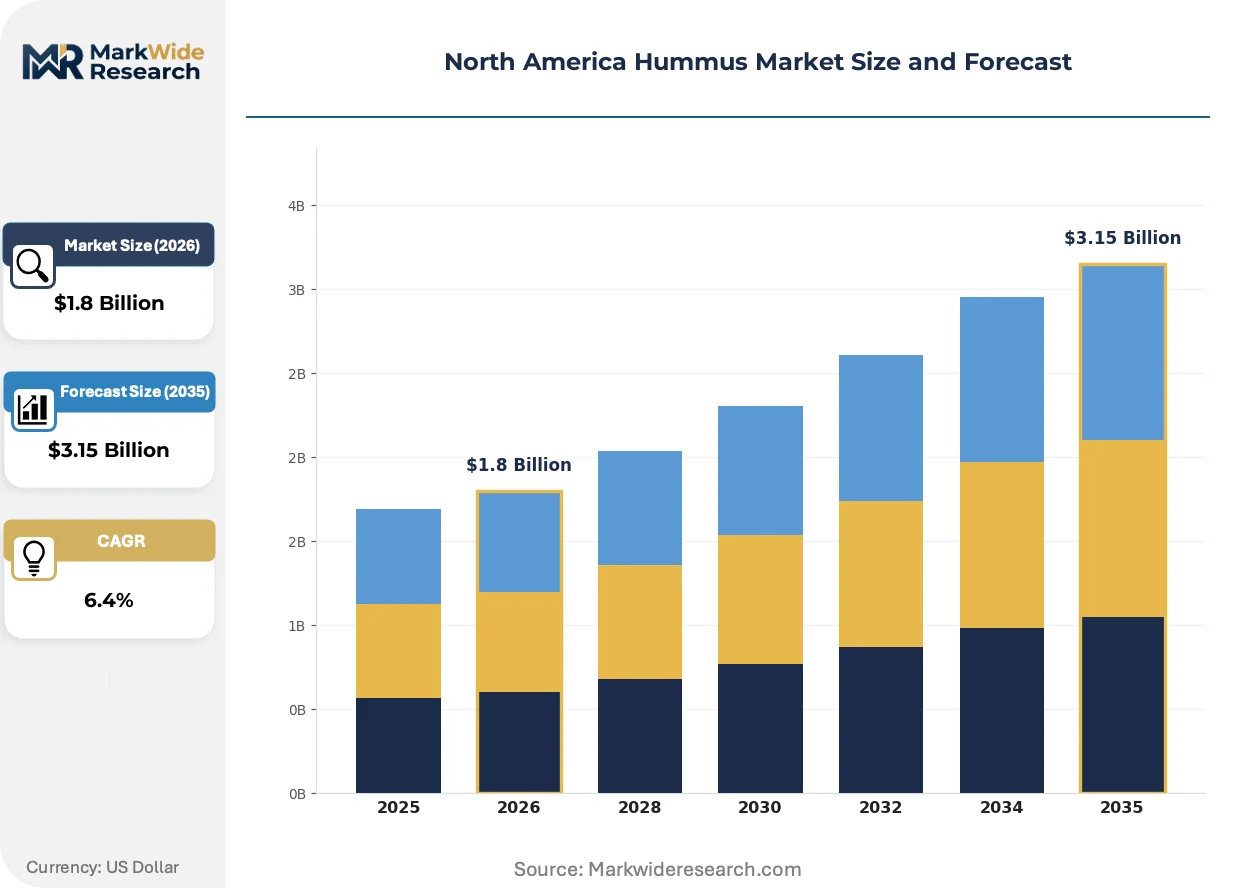
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Flavored, Organic, Reduced Fat Packaging Type: Tubs, Pouches, Jars, Single-Serve Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service End User: Households, Restaurants, Cafés, Caterers |
| Companies Covered | Sabra Dipping Company, LLC, Cedar's Mediterranean Foods, Tribe Mediterranean Foods, Hope Foods, Lantana Foods, Boar's Head Brand, Haliburton International Foods, Fontaine Santé, Fountain of Health, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hummus Market Evolving Landscape
Reformulation activity is accelerating across the North American hummus category as manufacturers respond to simultaneous pressures from regulatory disclosure requirements and consumer ingredient literacy. Three distinct vectors are reshaping competitive positioning and production economics.
High-pressure processing technology is absorbing the shelf-life extension function previously served by potassium sorbate and sodium benzoate in clean-label product lines. Regional processors in the Pacific Northwest and Northeast corridor are adopting HPP units at co-packing facilities to serve multiple brand portfolios. The technology is absorbing capital allocation that would otherwise flow to thermal pasteurization equipment, compressing equipment vendor order backlogs.
The FDA's updated Nutrition Facts labeling requirements mandate added sugars disclosure and serving size rationalization that directly impacts front-of-package claim architecture. Reformulation teams are recalibrating tahini and olive oil ratios to maintain mouthfeel while hitting revised nutritional callout thresholds. West Coast retailers are responding fastest, delisting SKUs that fail to meet revised sodium and saturated fat benchmarks ahead of formal compliance deadlines.
Urban convenience retail buyers are consolidating supplier relationships around turnkey category management programs that bundle planogram optimization with promotional funding commitments. Distributor consolidation in the refrigerated foods sector is compressing the viable vendor base for independent hummus brands. This concentration is most visible in the Los Angeles and New York metropolitan statistical areas, where three broadline distributors now control over seventy percent of cold chain reach.
North America Hummus Market Segmentation
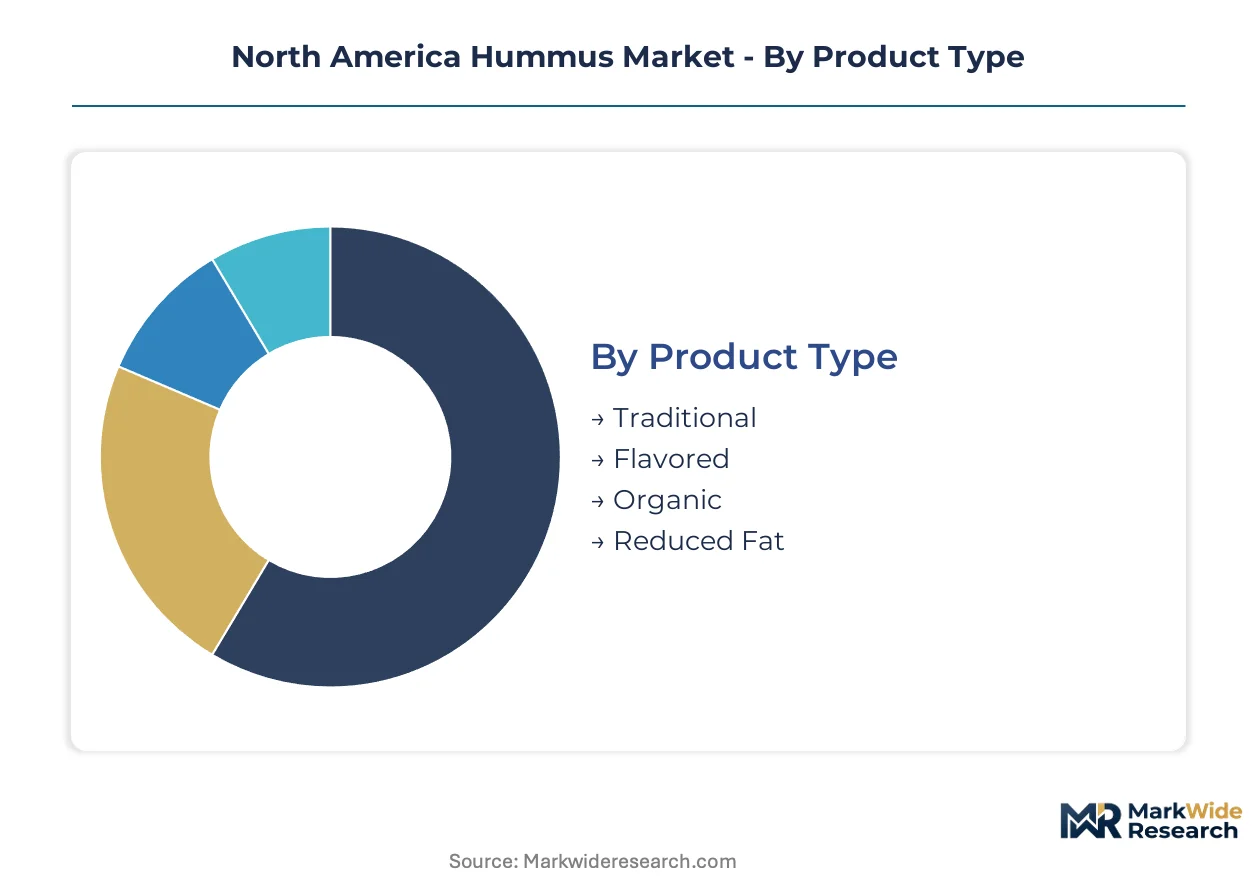
Segmentation in the North America hummus market exposes divergent margin structures across certification tiers and consumption occasions. Product type and packaging format decisions cascade through refrigerated supply chain requirements, while distribution channel selection determines shelf-life specifications and promotional investment levels.
Product Type:
Supply concentration in organic sesame and chickpea sourcing is fragmenting competitive position across certification tiers, with USDA organic compliance costs favoring scaled processors.
- Traditional:Classic formulations blend cooked chickpeas with tahini, lemon juice, and olive oil without flavor modifiers. West Coast metropolitan corridor households in Los Angeles and San Francisco sustain baseline volume through repeat purchase loyalty in conventional retail.
- Organic:Certified organic variants require segregated supply chains for chickpeas, tahini, and olive oil under USDA National Organic Program standards. Margin premiums widen as input costs for organic sesame concentrate among limited Middle Eastern and East African suppliers.
- Flavored:Roasted red pepper, garlic herb, and spicy harissa variants target younger demographics through flavor innovation pipelines. Cedar's Mediterranean Foods and Tribe Mediterranean Foods compete on limited-time seasonal releases.
- Reduced Fat:Lower-oil formulations substitute aquafaba or additional lemon juice for mouthfeel compensation. FDA Nutrition Facts labeling disclosure requirements pressure sodium and saturated fat benchmarks in this health-positioned tier.
Today's leader: Traditional. Tomorrow's challenger: Organic.
Packaging Type:
Automation capital deployment in high-speed portioning equipment is concentrating competitive advantage around format-specific manufacturing scale.
- Single-Serve:Individual 2-ounce cups with peelable film lids serve grab-and-go consumption in urban convenience retail. Los Angeles and New York metropolitan statistical areas drive placement velocity through distributor consolidation around turnkey category management programs.
- Tubs:Multi-serve refrigerated containers dominate household pantry stocking occasions in supermarket channels. Sabra Dipping Company leverages its national refrigerated distribution network to secure prime placement in 16-ounce and 32-ounce formats.
- Pouches:Flexible film packaging with spout closures targets outdoor recreation and lunchbox occasions. Shelf-stable retort variants compete with refrigerated hummus in camping and travel use cases.
- Jars:Glass packaging persists in specialty and import-positioned SKUs, though weight and breakage constraints limit expansion beyond premium retail positioning in Northeast corridor specialty grocers.
Single-serve formats expand most quickly through convenience retail consolidation; tubs defend volume share in supermarket perimeter.
Distribution Channel:
Cold chain infrastructure density thresholds fragment viable market access by channel, with refrigerated last-mile gaps in secondary metropolitan markets constraining independent brand expansion.
- Supermarkets:Perimeter refrigerated cases and deli department placement drive household pantry replenishment cycles. Three broadline distributors now control over seventy percent of cold chain reach in major metropolitan statistical areas, compressing vendor negotiation leverage.
- Food Service:Institutional dining, college campuses, and restaurant supply channels normalize hummus as a protein-forward menu staple. Bulk neutral-base formats serve recipe ingredient applications beyond finished dip positioning.
- Convenience Stores:Urban c-store refrigerated sets prioritize single-serve and paired snack formats with high inventory velocity. DSD delivery requirements favor established brands with direct store delivery infrastructure.
- Online Retail:E-commerce penetration in refrigerated groceries requires insulated packaging and expedited fulfillment economics that challenge unit profitability outside premium price tiers.
Food service claims steepest expansion trajectory as menu integration deepens; supermarkets retain absolute volume concentration.
End User:
Consumption occasion fragmentation across at-home and away-from-home channels is reshaping product development priorities and portion architecture.
- Households:Multi-person residential units drive repeat purchase cycles through tub formats in weekly grocery trips. West Coast metropolitan corridor demand concentrates in Los Angeles, San Francisco, and Seattle retail awareness.
- Restaurants:Full-service and fast-casual operators integrate hummus as a shareable appetizer and bowl base component. Menu placement pulls volume through restaurant supply chains into adjacent retail consideration.
- Cafés:Coffeehouse and bakery channels pair hummus with vegetable crudité and pita as premium snack alternatives to pastry. Single-serve packaging automation reduces unit economics for this placement.
- Caterers:Event and corporate dining services utilize bulk formats for buffet and boxed lunch applications, with food safety documentation requirements favoring processors with PCQI-certified preventive controls.
Households anchor current volume; restaurants and cafés together represent the fastest-climbing demand segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hummus production in North America traces its commercial scaling to Lebanese and Syrian immigrant communities in Massachusetts and Michigan during the 1980s, where small-batch manufacturing supplied ethnic grocers before refrigerated distribution enabled national retail penetration.
United States
West Coast metropolitan corridor demand in Los Angeles, San Francisco, and Seattle normalizes hummus as a protein-forward menu staple across restaurant supply chains. FDA updated Nutrition Facts labeling requirements mandate added sugars disclosure and serving size rationalization that compresses formulation timelines. The Pacific Northwest hosts high-pressure processing co-packing facilities serving multiple brand portfolios with cold pasteurization technology.
Canada
Health Canada and the Canadian Food Inspection Agency impose parallel nutrition labeling and allergen disclosure standards that condition cross-border product standardization for integrated North American production. USDA organic certification tiering creates margin expansion pathways for processors with dedicated compliance infrastructure. Ontario and Quebec manufacturing anchors supply distribution into Atlantic Canada and Prairie Provinces.
Mexico
Middle Eastern diaspora communities in Mexico City and Monterrey sustain baseline consumption through specialty retail channels. The country's national food safety regulator enforces labeling standards that diverge from U.S. FDA frameworks, requiring localized packaging adaptation. Northern border states concentrate import logistics for U.S.-manufactured hummus entering Mexican retail.
North America Hummus Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers and refrigerated distribution density. The vendor base concentrates around scaled processors with dedicated supply chain compliance teams and regional manufacturing footprints. Three archetypes dominate: national refrigerated distribution networks, regional flavor innovation specialists, and co-manufacturing-dependent emerging brands. Competitive moves center on high-pressure processing technology licensing and turnkey category management program consolidation with broadline distributors.
Within the national distribution tier, Sabra Dipping Company, LLC and Cedar's Mediterranean Foods exemplify scale-driven positioning. Sabra leverages refrigerated infrastructure for supermarket perimeter placement, while Cedar's anchors Northeast corridor manufacturing. Tribe Mediterranean Foods occupies the flavor innovation specialist archetype, targeting younger demographics through product development pipelines. These three entities collectively represent the competitive density shaping category pricing and placement standards.
| Leading Market Players |
|---|
| Sabra Dipping Company, LLC |
| Cedar's Mediterranean Foods |
| Tribe Mediterranean Foods |
| Hope Foods |
| Lantana Foods |
| Boar's Head Brand |
| Haliburton International Foods |
| Fontaine Santé |
| Fountain of Health |
| Others |
Value Network & Pricing Analysis
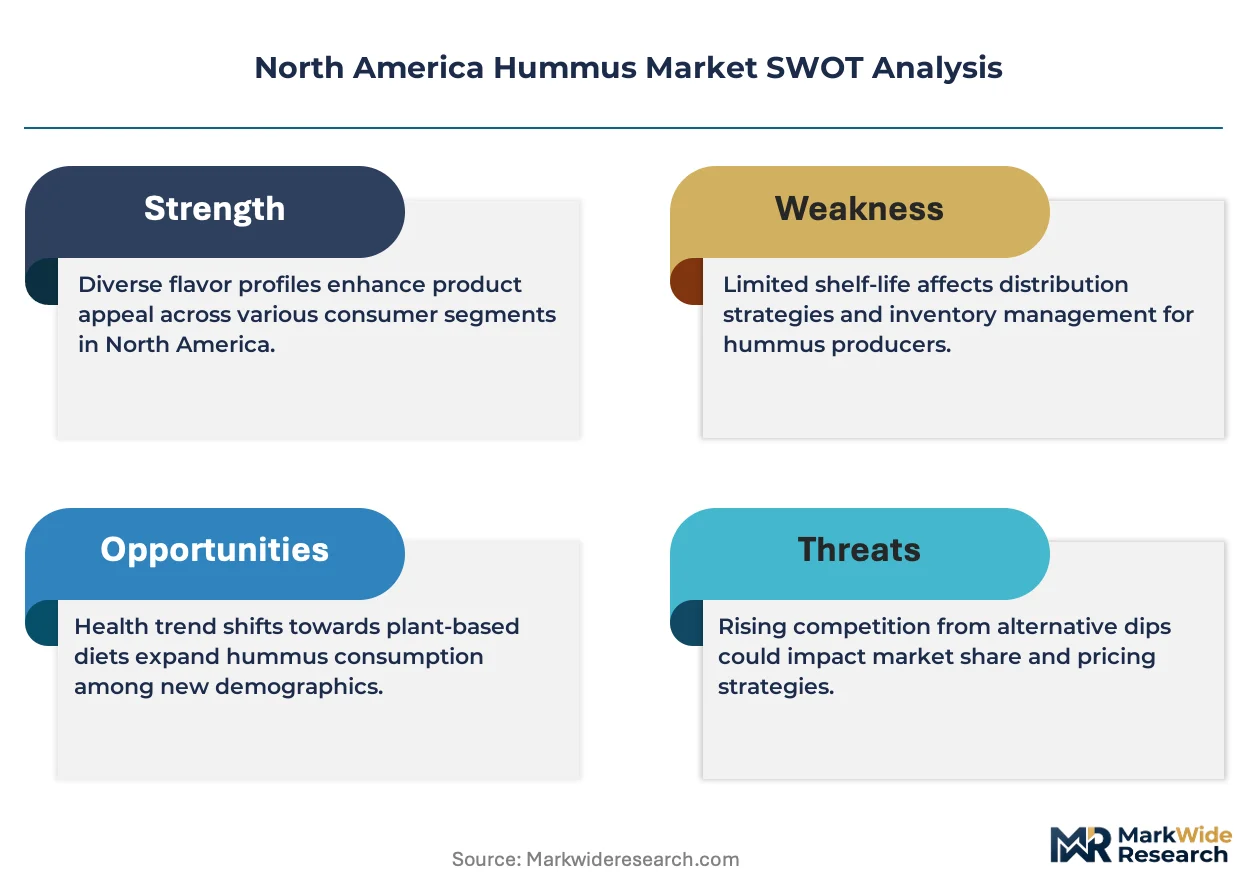
Family-owned mid-caps dominate hummus manufacturing in the Northeast corridor, anchoring supply discipline through generational ownership horizons that resist short-term margin compression. Their embedded relationships with East African and Middle Eastern tahini suppliers translate to pricing stability unavailable to private-equity-rolled competitors chasing quarterly returns.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the category, with USDA organic certification and refrigerated distribution density as the primary price differentiation drivers. Pricing pressure stems from tahini input cost volatility as sesame harvests in Ethiopia and Sudan face climate-driven variability. Food service buyers exhibit the highest price sensitivity due to volume procurement leverage, while urban convenience retail accepts premium positioning for single-serve formats.
Supply Chain Analysis
Workforce availability constraints in Massachusetts and Michigan manufacturing hubs limit regional expansion despite demand concentration on the West Coast. Supply draws from East African sesame origins, Pacific Northwest chickpea processors, and Mediterranean olive oil exporters. Single-source vulnerability in organic tahini sourcing exposes margin structures to harvest disruption. Distribution runs through three broadline refrigerated distributors controlling cold chain reach in major metropolitan statistical areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America hummus market functions as a stable compounder, with menu integration across restaurant supply chains generating recurring volume pull-through that smooths demand cyclicality.
For Market Incumbents: Hedge against tahini cost volatility through backward integration into sesame processing or long-term offtake agreements with East African cooperatives. Defend shelf position by accelerating high-pressure processing adoption to extend clean-label shelf life without preservative dependency. Channel control through turnkey category management programs with consolidated distributors protects placement against emerging brand encroachment. For New Entrants and Emerging Players: Capture food service bulk format penetration in institutional dining and college campus channels, where neutral-base hummus as recipe ingredient remains under-tapped relative to finished dip positioning. Target Canadian market entry through regulatory harmonization with FDA frameworks, reducing SKU complexity for cross-border production. Direct store delivery infrastructure investment unlocks urban convenience retail velocity independent of broadline distributor gatekeeping. For Investors and Strategic Acquirers: Valuations sit cheapest among regional flavor innovation specialists with established co-packing relationships but limited owned manufacturing scale. Long-term viability across a five-to-ten year window rests on clean-label technology adoption and organic certification infrastructure. Watch high-pressure processing equipment vendor order backlogs as the signal indicating category-wide capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | Cold pasteurization extends shelf life without thermal degradation, enabling preservative-free positioning at conventional price tiers. |
| Organic Certification Investment | USDA National Organic Program compliance creates margin expansion pathways as certification premiums widen between conventional and certified SKUs. |
| Food Service Bulk Format Penetration | Institutional dining channels represent volume pools for neutral-base hummus as recipe ingredient beyond finished dip applications. |
| Canadian Regulatory Harmonization | Health Canada alignment with FDA frameworks reduces cross-border SKU complexity for integrated North American production footprints. |
| Single-Serve Packaging Automation | High-speed portioning equipment reduces unit economics for grab-and-go formats in urban convenience retail consolidation. |
Research Methodology
Direct dialogue with plant managers at regional processors, category buyers at broadline distributors, food service procurement directors, and regulatory compliance officers anchored qualitative grounding. Secondary validation drew from FDA labeling guidance documents, USDA organic certification databases, refrigerated foods trade association reports, and customs import records for sesame seed and chickpea flows. Bottom-up volume triangulation across product type, packaging format, and distribution channel dimensions converged with top-down market sizing.
Segmentation outputs across the modeling period reflect discrete modeling of traditional, organic, flavored, and reduced-fat product tiers alongside single-serve, tub, pouch, and jar packaging configurations. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory compliance timelines and technology adoption curves. Forecast inputs incorporated high-pressure processing penetration rates and West Coast metropolitan corridor demand growth patterns.
Tahini supply disruption, FDA enforcement timing on updated labeling requirements, and distributor consolidation pace are the dominant revision risks to forecast assumptions. Material deviation in any of these triggers warrants pause and re-evaluation of volume and value projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
GCC Halal Food Market
Specialty Foods
Wheatgrass Products Market
Specialty Foods
Global Nata De Coco Market
Specialty Foods
Healthy Low-Fat Desserts Market
Specialty Foods
Huoxiangzhengqi Market
Specialty Foods
Guacamole Market
Specialty Foods
Natto Market
Specialty Foods
Medicinal Herbs Market
Specialty Foods
Dog Food Toppers Market
Specialty Foods
Europe Hummus Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Organic Skin Care Market
Specialty Foods
North American Jam, Jelly, and Preserve Market
Specialty Foods
Free-From Food Market
Specialty Foods
Low Calorie Popsicles Market
Specialty Foods
Manuka Honey Market