
 Low Calorie Hummus Market | 2026-2036
Low Calorie Hummus Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Hummus Market Analytics
EU Green Deal nutrition labeling requirements is hardening standards for reduced-calorie prepared foods across European retail channels. Cedar's Mediterranean Foods, Inc. anchors its position through authentic Mediterranean recipes adapted for calorie-conscious buyers. Hope Foods, LLC differentiates via organic ingredient sourcing and transparent supply chain communication. Lantana Foods competes through bold flavor innovation in the low-calorie segment, extending its shelf presence in premium grocery locations.
Low calorie hummus denotes a chickpea- or legume-based spread formulated with reduced fat and calorie density, typically achieved through modified tahini ratios, alternative oil profiles, or vegetable base substitutions such as cauliflower or pea protein, serving as a functional dip or sandwich component for weight-management and diabetic-friendly diets. Roasted red pepper and garlic variants capture margin premiums through flavor complexity that justifies higher price positioning against plain formulations. Single-serve packaging emerges as the fastest-growing format, driven by portion-control demand from workplace and on-the-go consumption occasions.
The FDA governs nutritional labeling claims in the United States, while the USDA Organic certification shapes ingredient sourcing requirements for premium positioning. EFSA front-of-pack labeling initiatives in Europe pressure reformulation toward cleaner ingredient decks. Stakeholders must monitor evolving sodium and additive thresholds as regulators tighten health-claim substantiation standards across multiple jurisdictions.
Market Dynamics
Clean-label formulation requirements are compressing margins across the low-calorie hummus sector as manufacturers reformulate to eliminate stabilizers and artificial preservatives while maintaining shelf stability. Reformulation costs cascade through ingredient sourcing and processing equipment upgrades.
Growth Catalysts
- EU Green Deal nutrition labeling:The EU Green Deal mandates front-of-pack calorie disclosure, compelling retailers to expand reduced-calorie prepared food assortments and creating shelf-space pull for compliant hummus formulations.
- Single-serve packaging technology:Modified atmosphere packaging advances enable 30-day ambient shelf life for portion-controlled hummus cups without potassium sorbate, unlocking workplace and travel consumption channels.
- Diabetic-friendly diet expansion:Endocrinology clinics in the United States now recommend legume-based spreads as glycemic-control snacks, embedding hummus into medical nutrition therapy protocols.
Market Restraints
- Tahini cost volatility:Ethiopian sesame seed harvest fluctuations transmit directly to hummus input costs, compressing gross margins when combined with clean-label reformulation expenses.
- Chickpea supply concentration:Canadian prairie drought risk concentrates global kabuli chickpea sourcing, exposing processors to protein content variability that disrupts texture consistency in reduced-fat formulations.
- Texture degradation in fat reduction:Removing tahini below 12% by weight produces grainy mouthfeel that triggers consumer rejection, limiting calorie reduction potential without emulsifier alternatives.
Strategic Opportunities
- German convenience channel underpenetration:Discounter chains Aldi and Lidl in Germany allocate minimal chilled-dip shelf space to low-calorie variants, presenting first-mover positioning for compliant entrants.
- Vegetable-base substitution convergence:Cauliflower and white bean hybrid formulations paired with high-pressure processing technology enable 40% calorie reduction while preserving creamy texture.
- USDA Organic certification tailwind:The USDA Organic seal commands 23% price premiums in US natural grocery channels, incentivizing ingredient traceability investments that differentiate commodity hummus.
Industry Challenges
- Food technologist talent scarcity:Formulation chemists with expertise in clean-label emulsification systems command premium compensation, elongating R&D timelines for mid-tier manufacturers.
- High-pressure processing capex requirements:Cold-pasteurization equipment for extended-shelf-life clean-label hummus demands $2-4 million facility investments, favoring scaled players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Hummus Market |
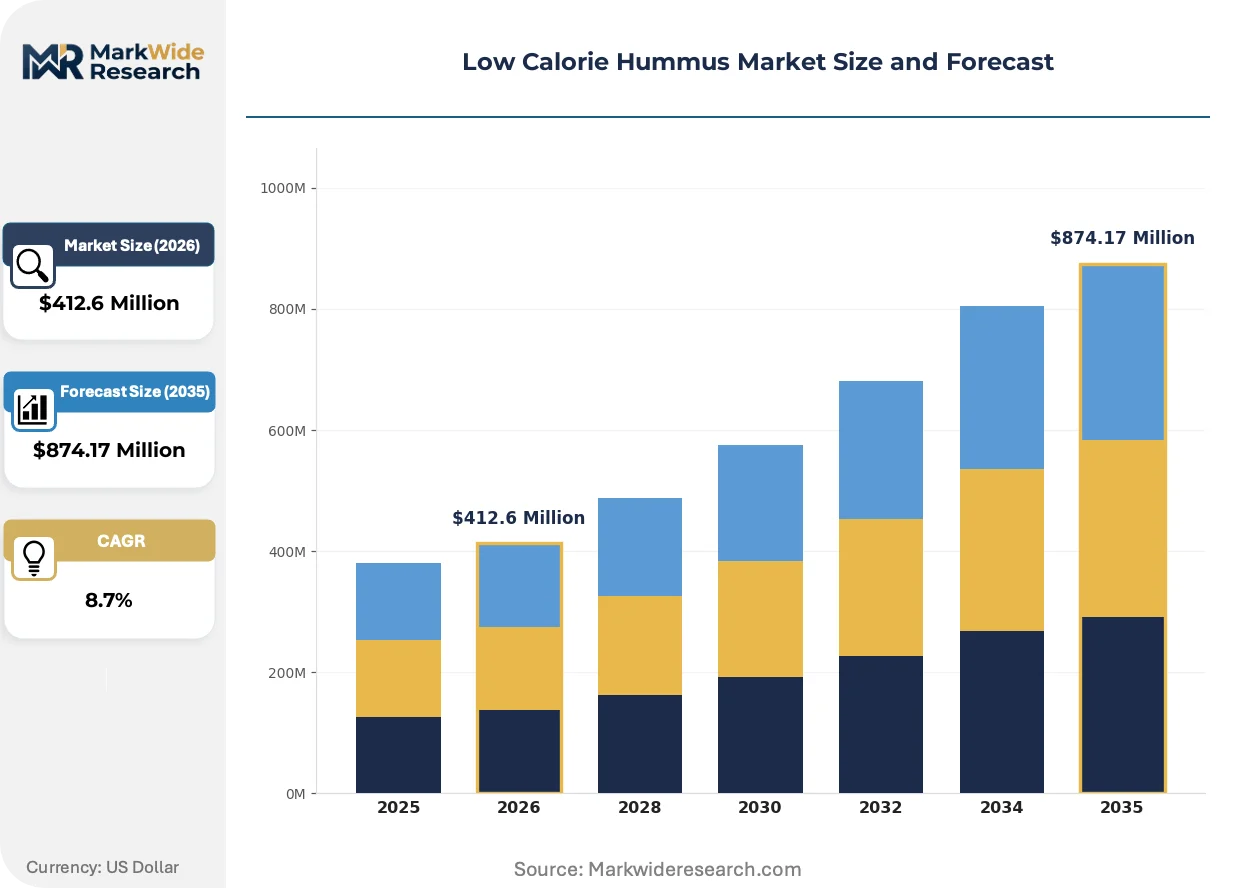
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain, Spicy, Roasted Red Pepper, Garlic Ingredient Type: Chickpeas, Peas, Lentils, Cauliflower Packaging Type: Tub, Pouch, Jar, Single-Serve Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Shops |
| Companies Covered | Sabra Dipping Company, LLC, Cedar’s Mediterranean Foods, Inc., Hope Foods, LLC, Lantana Foods, Roots Hummus, Esti Foods, Cava, Ithaca Hummus, Good Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Hummus Market Evolving Landscape
Reformulation science and packaging engineering are converging to redefine competitive advantage in reduced-calorie spreads. Manufacturers now compete on ingredient transparency rather than price alone.
High-pressure processing is decentralizing pasteurization economics for clean-label hummus. Small-batch producers in urban markets adopt HPP tolling services rather than investing in captive equipment. This technology is decentralizing shelf-life extension capability away from national brands toward regional craft processors.
EFSA front-of-pack labeling initiatives are tightening additive thresholds across European retail. Manufacturers face reformulation deadlines to eliminate modified food starch and citric acid from reduced-calorie lines. German and French supermarket buyers now require clean-ingredient-deck certification as a listing prerequisite.
Workplace snacking patterns are fragmenting bulk purchasing into individual occasion-based buying. Corporate micro-market operators replace communal tubs with single-serve SKUs to reduce contamination liability. This shift concentrates in United States coastal metropolitan office districts where hybrid work schedules sustain grab-and-go demand.
Low Calorie Hummus Market Segmentation
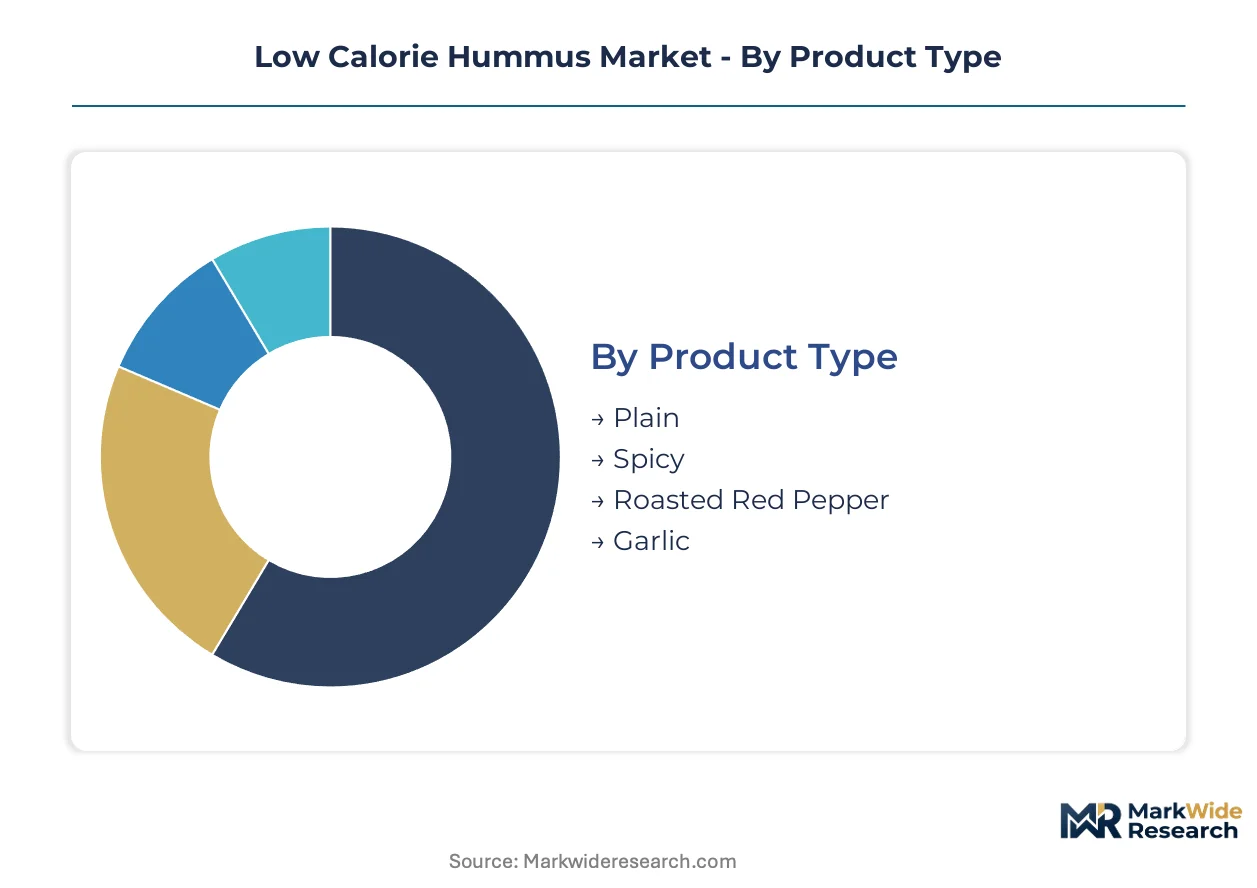
Segmentation in low calorie hummus reveals how formulation choices, portion formats, and retail channels align with distinct consumer health priorities and usage occasions. Manufacturers calibrate positioning across these dimensions to capture shelf space and price premiums.
Product Type:
Flavor preferences in this category separate routine household purchasers from premium-seeking buyers willing to pay for complexity.
- Plain:Unflavored formulations with minimal tahini reduction serve as the baseline for calorie-conscious households seeking versatile sandwich spreads. Demand concentrates in United States suburban supermarkets where parents prioritize clean ingredient decks for children's lunches.
- Roasted Red Pepper:Smoky-sweet vegetable infusions justify 15-20% price premiums through perceived artisanal positioning and visual differentiation on shelf. Growth tilts toward urban millennial households in coastal metropolitan areas seeking Instagram-worthy meal components.
- Spicy:Chili-forward variants targeting heat-seeking consumers in Southwestern US states and Mexican-influenced culinary regions.
- Garlic:Pungent formulations appealing to Mediterranean diet adherents and savory flavor profile enthusiasts.
Volume sits with Plain; growth tilts toward Roasted Red Pepper.
Ingredient Type:
Base ingredient selection determines protein content, glycemic index positioning, and supply chain exposure to commodity volatility.
- Chickpeas:Traditional kabuli chickpea formulations dominate manufacturing scale and consumer recognition, though drought vulnerability in Canadian prairie growing regions creates input cost instability. United States retail buyers specify minimum protein content thresholds that exclude lower-grade harvests.
- Cauliflower:Vegetable-base substitutions enable 35-40% calorie reduction while leveraging existing clean-label consumer acceptance of cruciferous ingredients. High-pressure processing technology preserves creamy mouthfeel without emulsifier additives.
- Peas:Yellow pea protein bases offering allergen-friendly positioning for legume-sensitive consumers.
- Lentils:Smaller-seed legume alternatives with distinct earthy flavor profiles and shorter cooking requirements.
Chickpeas anchor current volume; cauliflower-base formulations are climbing the fastest as processing technology matures.
Packaging Type:
Format choice reflects consumption occasion fragmentation between household stock-up and individual on-the-go purchasing.
- Single-Serve:Portion-controlled cups with modified atmosphere packaging enable 30-day ambient shelf life without potassium sorbate, unlocking workplace micro-markets and travel retail channels. Corporate foodservice operators in United States coastal office districts replace communal tubs to reduce contamination liability.
- Tub:Multi-serve containers dominate household pantry stocking in suburban and rural markets with lower per-ounce packaging costs.
- Pouch:Flexible formats targeting outdoor recreation and lunchbox convenience with reduced shipping weight.
- Jar:Premium glass packaging for specialty retail positioning and gift-oriented purchasing.
Household penetration remains tub-dependent; single-serve formats gain share fastest through channel expansion.
Distribution Channel:
Channel strategy determines margin structure, velocity requirements, and compliance with retailer-specific ingredient certifications.
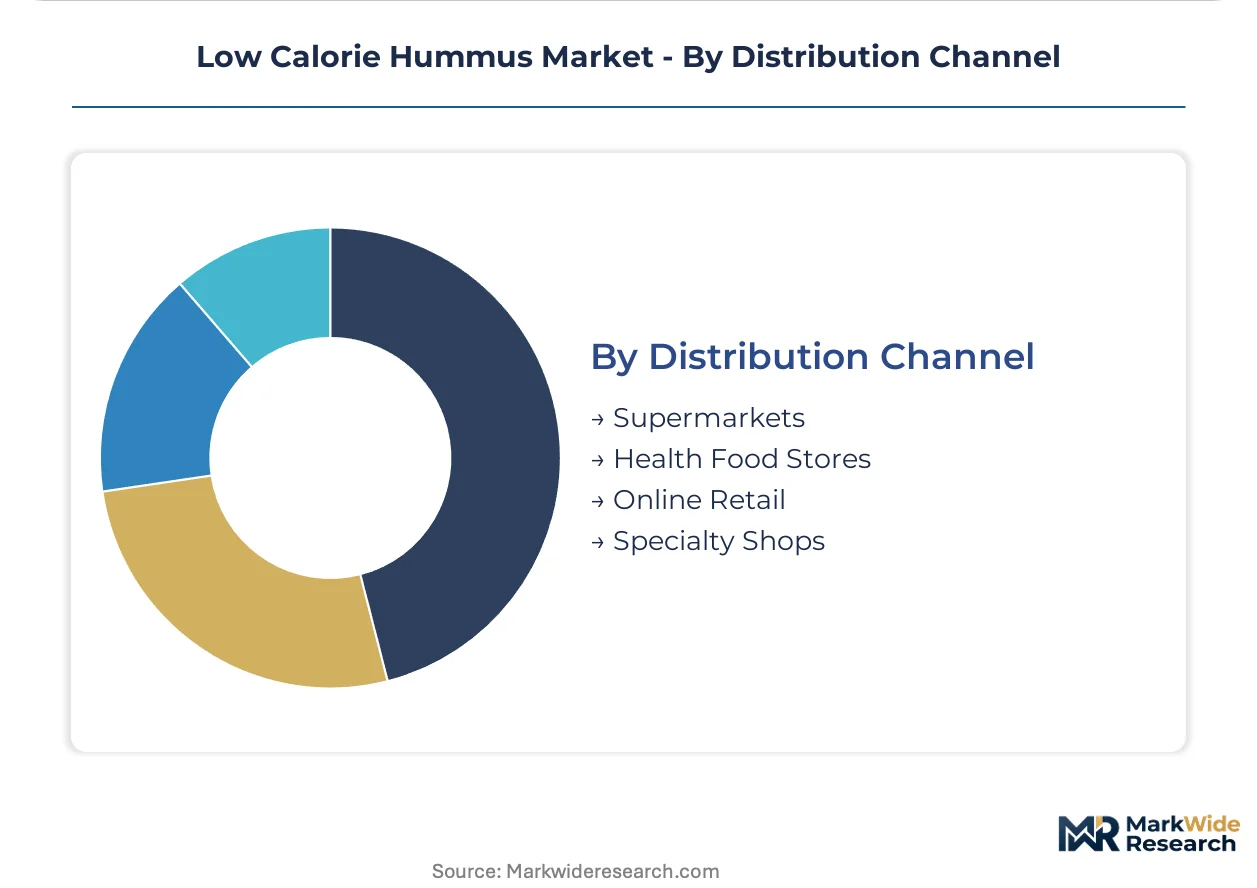
- Supermarkets:Mass-market retail chains in the United States and European Union require clean-label certification and front-of-pack calorie disclosure compliance. EU Green Deal nutrition labeling mandates are hardening listing standards for reduced-calorie prepared foods.
- Online Retail:Direct-to-consumer and third-party marketplace channels enable subscription-based replenishment and variety pack offerings for trial-driven purchasers.
- Health Food Stores:Natural grocery channels command USDA Organic certification premiums and transparent supply chain documentation.
- Specialty Shops:Mediterranean ethnic retailers and gourmet food purveyors emphasizing authentic recipe provenance.
Supermarkets capture the volume base; online retail shows steepest expansion trajectory as subscription models reduce customer acquisition costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Mediterranean-adjacent processing clusters while consumption tilts toward North American and European urban centers. The United States absorbs the largest trade volumes, though domestic manufacturing scales in California and New York industrial parks.
United States
Urban millennial households in coastal metropolitan areas drive clean-label hummus adoption through premium grocery channels. The FDA governs nutritional labeling claims and front-of-pack calorie disclosure standards for reduced-fat spreads. California's Central Valley hosts chickpea processing facilities supplying West Coast co-manufacturers with ingredient traceability systems.
Germany
Discounter chains Aldi and Lidl underpenetrate the low-calorie chilled-dip category, leaving shelf-space vacancies for compliant entrants. The EU Green Deal mandates front-of-pack nutrition labeling that hardens standards for reduced-calorie prepared foods across German retail. Berlin's food-tech incubators pilot high-pressure processing tolling services for regional craft hummus producers.
United Kingdom
Health-conscious consumers in London and Southeast England supermarkets demand organic certification and transparent supply chain documentation. EFSA front-of-pack labeling initiatives pressure reformulation toward cleaner ingredient decks without modified food starch. The Midlands food manufacturing corridor hosts co-packing facilities serving private-label hummus programs for major retail chains.
France
Mediterranean diet adherence in Provence-Alpes-Côte d'Azur sustains authentic recipe demand among calorie-conscious households. ANSM nutrition claim substantiation requirements tighten additive thresholds for reduced-fat spreads sold in French hypermarkets. Parisian urban foodservice operators replace communal hummus tubs with single-serve portions in corporate micro-markets.
Canada
Prairie drought risk in Saskatchewan and Alberta concentrates global kabuli chickpea sourcing, exposing processors to protein content variability. Health Canada and PMRA regulate organic certification and food additive approvals for clean-label hummus formulations. Toronto's Greater Golden Horseshoe hosts cold-chain distribution hubs serving cross-border retail channels into the United States.
Low Calorie Hummus Market Competitive Landscape
The competitive structure tilts toward regional craft specialists competing against scaled national brands with co-manufacturing networks. Mid-tier players face margin compression from clean-label reformulation costs and high-pressure processing equipment investments. Three archetypes dominate: Mediterranean-heritage recipe purists, organic-certified premium positioning specialists, and flavor-innovation-focused challengers. Portfolio diversification and geographic expansion through retail channel penetration represent the dominant competitive moves.
Within the Mediterranean-heritage tier, Cedar's Mediterranean Foods, Inc. and Esti Foods occupy positions anchored in authentic recipe provenance. Hope Foods, LLC exemplifies the organic-certified premium archetype through transparent supply chain positioning. Lantana Foods sits within the flavor-innovation vector, representing challengers competing through bold variant development. These three companies collectively illustrate how formulation philosophy and channel strategy segment competitive positioning in reduced-calorie spreads.
| Leading Market Players |
|---|
| Sabra Dipping Company, LLC |
| Cedar's Mediterranean Foods, Inc. |
| Hope Foods, LLC |
| Lantana Foods |
| Roots Hummus |
| Esti Foods |
| Cava |
| Ithaca Hummus |
| Good Foods |
| Others |
Value Network & Pricing Analysis
Backward integration into Ethiopian sesame seed sourcing anchors both supply security and pricing power for scaled hummus manufacturers facing tahini cost volatility. This captive supply strategy insulates processors from harvest-driven input spikes while supporting premium positioning through traceability claims demanded by USDA Organic-certified retail channels.
Pricing Analysis
Margin tightening in clean-label tiers reflects reformulation costs for emulsifier elimination and high-pressure processing equipment amortization. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified products from conventional formulations and private-label alternatives. Price differentiation hinges on certification grade and volume scale. Cost-down pressure on mid-tier SKUs accelerates because discounter chains are hardening clean-ingredient prerequisites without absorbing supplier cost increases. Workplace micro-market operators show least price sensitivity; suburban household purchasers in multi-serve tub formats demonstrate highest.
Supply Chain Analysis
Food technologist scarcity in California and New York industrial parks constrains regional craft processor expansion despite tolling service availability. Kabuli chickpea sourcing draws from Canadian prairie growing regions, Ethiopian sesame seed harvests, and domestic organic acreage in California's Central Valley. Supply chain risk centers on single-source vulnerability for high-grade chickpea protein specifications required by reduced-fat formulations. Distribution runs through chilled retail networks serving supermarket chains, natural grocery channels, and corporate foodservice micro-markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal nutrition labeling mandate erects a compliance moat that favors incumbent processors with established clean-label formulation capabilities and regulatory affairs infrastructure.
For Market Incumbents: Cement shelf-space dominance through high-pressure processing capacity additions in California and New York industrial corridors. Secure backward integration into organic chickpea acreage to defend against Canadian drought-driven protein variability. Channel control through direct-retailer category captaincy agreements repels emerging craft entrants lacking velocity guarantees. For New Entrants and Emerging Players: Direct-to-consumer subscription routes bypass supermarket listing barriers and enable trial-driven sampling of cauliflower-base hybrid formulations. German discounter chains Aldi and Lidl present underpenetrated white-space for compliant low-calorie entrants. Target workplace micro-market operators in United States coastal office districts with single-serve SKUs emphasizing contamination-liability reduction. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by scaled CPG platforms seeking clean-label hummus capability. Long-term viability frames around regulatory compliance infrastructure rather than flavor differentiation alone. Watch EFSA additive threshold tightening as inflection signal for accelerated industry consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | Eliminates potassium sorbate and modified food starch to meet EU Green Deal and EFSA listing prerequisites. |
| High-Pressure Processing Capacity Expansion | Extends ambient shelf life to 30 days for single-serve cups without artificial preservatives. |
| USDA Organic Certification Acquisition | Unlocks 23% price premiums in natural grocery channels and supports supply chain traceability claims. |
| Single-Serve Packaging Format Launch | Captures workplace micro-market and travel retail channels driven by portion-control demand. |
| Cauliflower-Base Hybrid Formulation Development | Enables 40% calorie reduction while preserving creamy texture through vegetable substitution. |
Research Methodology
Trade databases, customs records, and retail audit data formed the secondary backbone, cross-referenced with primary interviews across food manufacturing executives, category buyers at supermarket chains, clean-label R&D directors, and high-pressure processing equipment suppliers. Bottom-up and top-down triangulation validated volume estimates against ingredient throughput data and channel shipment records.
Bottom-up modeling built from SKU-level velocity through supermarket scanner data and online marketplace transaction records, aggregated across flavor variants, packaging formats, and ingredient-type segments. Top-down constraints applied from tahini input cost trajectories and chickpea harvest forecasts. CAGRs derived from regression against diabetic-friendly diet expansion rates and workplace snacking pattern shifts. Industry-specific inputs included EFSA regulatory timeline assumptions and HPP equipment adoption curves.
The model holds under stable regulatory enforcement timelines; deviation in EU Green Deal implementation pace or Ethiopian sesame harvest conditions would shift volume trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Almond-Based Spreads Market
Specialty Foods
Hot Pot Market
Specialty Foods
Dong Quai Market
Specialty Foods
Halal Market
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market
Specialty Foods
GCC Halal Food Market
Specialty Foods
Free-From Food Market
Specialty Foods
Cannabis Infused Drinks Market
Specialty Foods
Middle East and Africa Free-From Food Market
Specialty Foods
Liquid Mushroom Market
Specialty Foods
Medicinal Herbs Market
Specialty Foods
Asia-Pacific Free from Food Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Wheatgrass Products Market
Specialty Foods
Aloe Vera Gel Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market