
 T-Piece Resuscitator Market | 2026-2036
T-Piece Resuscitator Market Size, Share, and Industry Trends Forecast 2026-2036
T-Piece Resuscitator Market Insights
Integrated pressure monitoring and closed-loop feedback control is rewriting how T-piece resuscitators deliver consistent tidal volumes during neonatal stabilization. Ambu A/S leverages its disposable portfolio to capture high-turnover clinical environments where infection control protocols dominate purchasing criteria. Laerdal Medical sustains deep channel relationships with emergency medical services through training-integrated product ecosystems. Drägerwerk AG & Co. KGaA anchors the premium segment with ventilator platforms that incorporate T-piece modules into broader critical care architectures.
A T-piece resuscitator is a manual or pneumatically assisted breathing device consisting of a T-shaped valve assembly that delivers controlled positive pressure ventilation without interrupting spontaneous respiratory effort, typically engineered with precision-manufactured silicone or medical-grade plastic components and adjustable positive end-expiratory pressure valves for neonatal and adult applications. The device serves primarily to provide emergency respiratory support during delivery room resuscitation, anesthesia induction, and inter-facility patient transport where mechanical ventilator availability remains limited. Disposable T-pieces command the dominant revenue share as hospital infection prevention committees mandate single-patient-use policies across perinatal and emergency departments. Neonatal T-pieces represent the fastest-expanding product category as survival rates for extremely low birth weight infants improve and delivery room protocols standardize gentle ventilation approaches.
The FDA enforces 510(k) premarket notification requirements for T-piece resuscitators classified as Class II respiratory devices, while ISO 10651-4 specifies performance and safety testing protocols for manually operated resuscitators used in emergency and transport settings. The EU Medical Device Regulation imposes stricter clinical evidence requirements and unique device identification mandates that extend compliance timelines for manufacturers seeking CE marking renewal. Stakeholders must monitor evolving neonatal resuscitation program guidelines from the American Academy of Pediatrics and equivalent bodies, as protocol revisions directly alter device specification requirements and training-driven replacement cycles.
Market Dynamics
Integrated pressure monitoring is collapsing the traditional gap between manual resuscitation and mechanical ventilation precision, forcing manufacturers to embed sensors and feedback loops into T-piece architectures that previously relied on clinician skill alone.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's premarket notification framework for Class II respiratory devices accelerates product iterations for neonatal applications, reducing time-to-market for manufacturers with predicate device strategies.
- Level IV NICU expansion:United States tertiary hospitals are building specialized neonatal units that mandate pressure-controlled resuscitation equipment for extremely low birth weight infant protocols.
- Silicone component precision manufacturing:Advances in medical-grade silicone molding enable tighter pressure tolerance specifications that meet ISO 10651-4 performance standards for manually operated resuscitators.
Market Restraints
- Medical-grade polymer supply concentration:Specialty silicone and thermoplastic elastomer feedstock production clusters in Germany and Japan, exposing device manufacturers to input cost volatility and geographic supply risk.
- EU MDR clinical evidence requirements:The European Medical Device Regulation imposes extended compliance timelines and unique device identification mandates that delay CE marking renewal for existing product portfolios.
- Mechanical ventilator substitution:Portable ventilator platforms with integrated neonatal modes capture stabilization scenarios that previously defaulted to manual T-piece resuscitation in transport settings.
Strategic Opportunities
- Indian perinatal care infrastructure:Government-funded maternal health programs and medical college hospital upgrades create procurement volume for disposable resuscitation devices in tier-2 and tier-3 cities.
- Closed-loop feedback convergence:Integration of pressure sensors with real-time tidal volume calculation algorithms enables semi-automated T-piece operation that bridges manual and mechanical ventilation workflows.
- Emergency medical services channel expansion:Pre-hospital care systems in Australia and Canada are standardizing T-piece resuscitators for inter-facility neonatal transport where mechanical ventilator backup remains unavailable.
Industry Challenges
- Neonatal resuscitation program certification alignment:Training curriculum revisions by the American Academy of Pediatrics force device manufacturers to synchronize product specifications with evolving protocol requirements.
- Legacy equipment interoperability:T-piece modules must interface with existing hospital gas delivery infrastructure and monitoring systems that lack standardized connector specifications across manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | T-Piece Resuscitator Market |
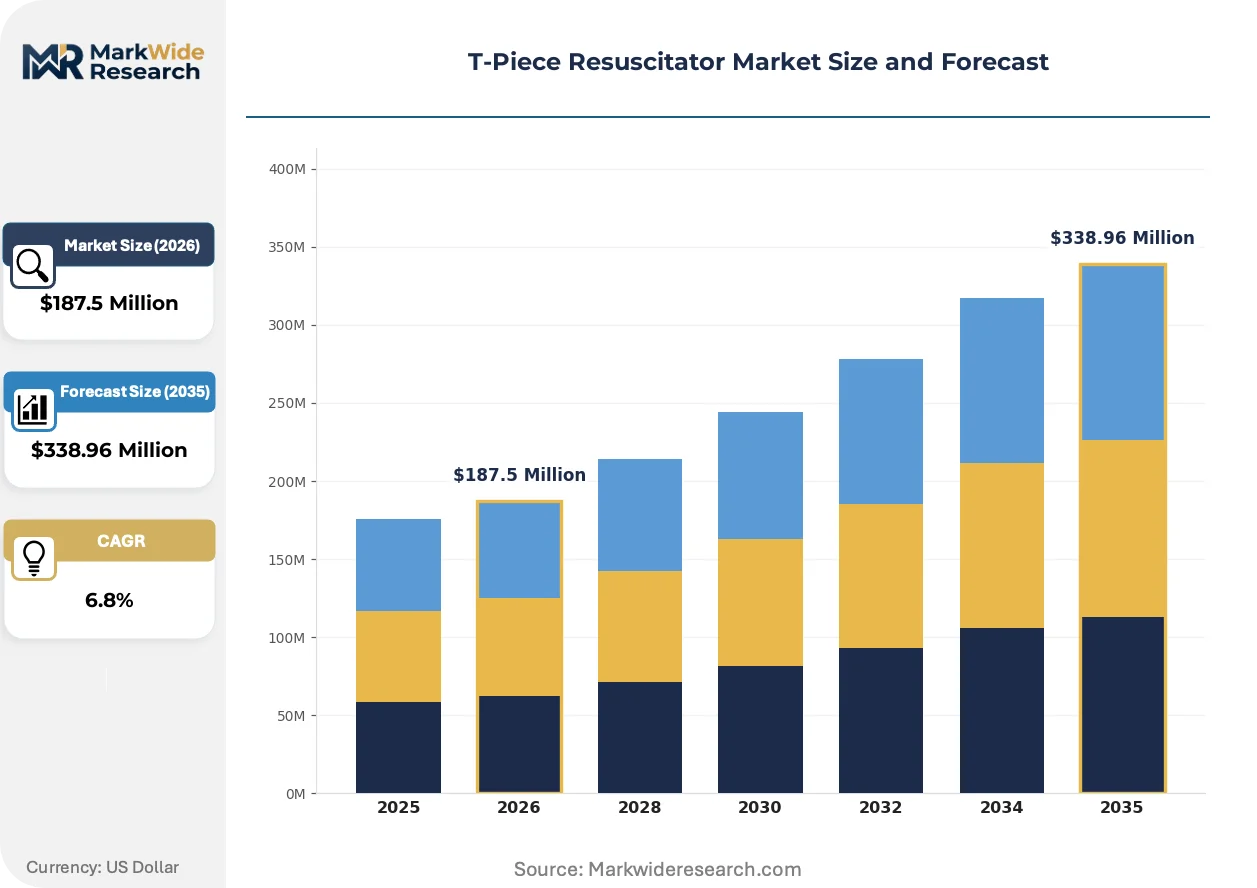
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $338.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable T-Pieces, Reusable T-Pieces, Neonatal T-Pieces, Adult T-Pieces End User: Hospitals, Clinics, Emergency Services, Homecare Application: Emergency Resuscitation, Anesthesia Delivery, Patient Transport, Neonatal Care Material: Plastic, Silicone, Rubber, Metal |
| Companies Covered | Ambu A/S, Laerdal Medical, Fisher & Paykel Healthcare, Flexicare (Group) Limited, Vyaire Medical, Medtronic, Drägerwerk AG & Co. KGaA, Neotech Medical Systems, Mercury Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
T-Piece Resuscitator Market Trends and Innovations
Sensor miniaturization and algorithmic pressure control are compressing the functional boundary between manual resuscitation devices and full mechanical ventilators, creating hybrid categories that challenge traditional procurement classifications.
Disposable pressure transducer integration is collapsing the cost barrier between basic T-piece designs and precision ventilation systems. Level IV NICU departments in the United States are adopting these sensor-embedded disposables within 18-month replacement cycles. The technology is collapsing the historical trade-off between infection control mandates and ventilation accuracy, enabling single-patient-use policies without clinical performance sacrifice.
The EU Medical Device Regulation's post-market surveillance requirements are extending clinical evidence obligations for CE-marked resuscitation devices. Manufacturers must now maintain active safety monitoring systems and periodic safety update reports that increase regulatory affairs staffing. Neonatal product lines face the steepest compliance burden due to the vulnerable patient population and heightened scrutiny from notified bodies.
Hospital infection prevention committees are mandating single-patient-use policies across perinatal and emergency departments regardless of initial acquisition cost. This behavioral shift compresses device lifecycles from multi-year durable equipment to consumable supply chain management. The United States exhibits the most pronounced transition, with bundled payment models for perinatal care aligning financial incentives around standardized disposable protocols rather than capital equipment amortization.
T-Piece Resuscitator Market Segmentation
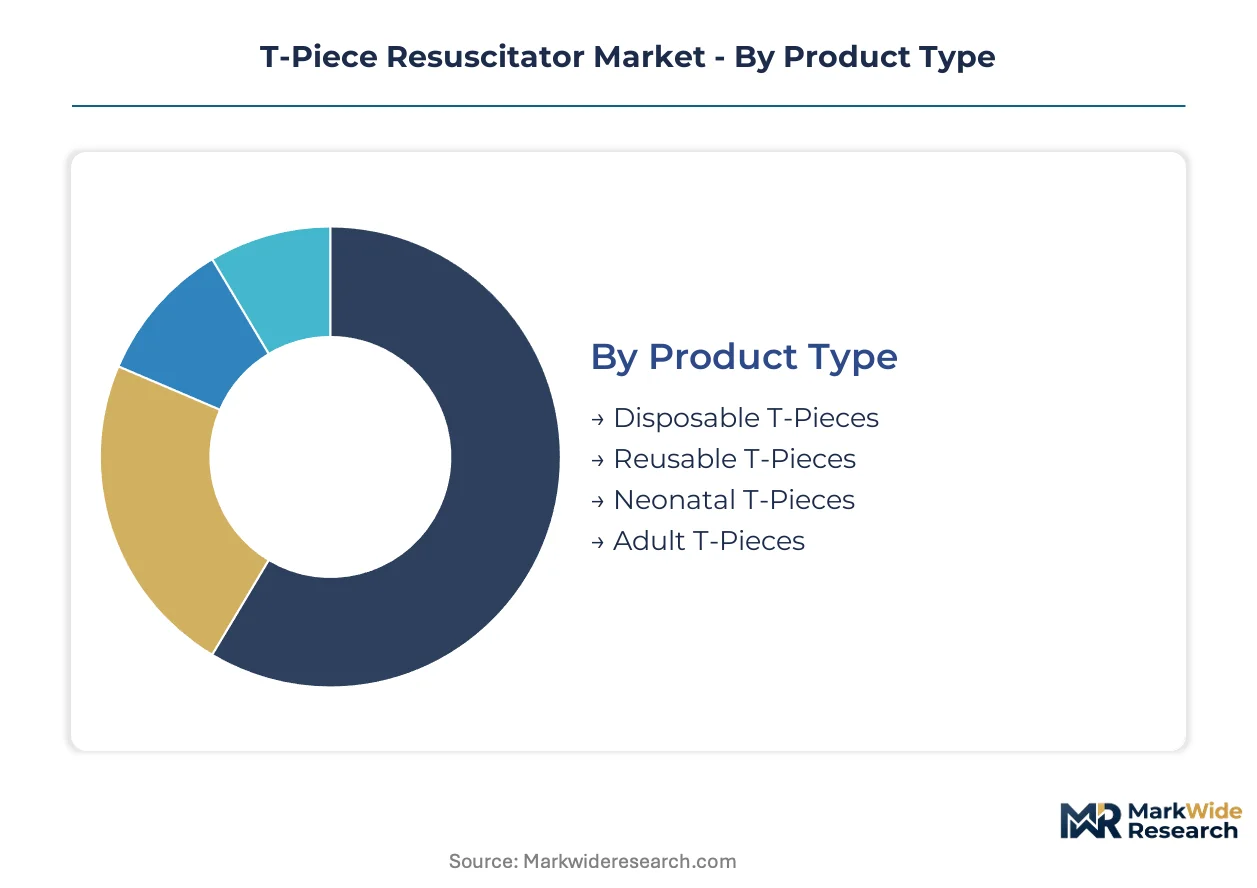
T-piece resuscitator procurement splits sharply between infection-control mandates in tertiary hospitals and cost constraints in emerging perinatal systems. Material selection and product architecture determine whether devices qualify for Level IV NICU protocols or basic emergency transport applications.
Product Type:
Use cases span from single-patient disposables in infection-sensitive neonatal units to durable equipment for resource-limited settings.
- Disposable T-Pieces:Single-patient-use devices constructed from medical-grade polymers with integrated pressure monitoring sensors. United States Level IV NICU departments mandate these for extremely low birth weight infant protocols under bundled payment models that prioritize infection prevention over capital equipment amortization.
- Neonatal T-Pieces:Precision-engineered variants with calibrated pressure limits and tidal volume ranges suited for fragile respiratory systems. Demand concentrates in tertiary hospitals where delivery room protocols standardize gentle ventilation approaches for improved survival rates among preterm infants.
- Reusable T-Pieces:Autoclavable silicone assemblies designed for multi-patient use with sterilization validation.
- Adult T-Pieces:Higher-volume ventilation systems for emergency and anesthesia applications outside perinatal specialization.
Established volume favors disposable T-pieces; emerging adoption favors neonatal T-pieces.
End User:
Customer archetypes range from capital-intensive hospital systems to distributed pre-hospital networks with intermittent mechanical ventilator backup.
- Hospitals:Tertiary medical centers with dedicated NICU infrastructure and standardized resuscitation protocols. Procurement committees in these facilities prioritize FDA-cleared devices with closed-loop feedback capabilities that align with American Academy of Pediatrics training curricula.
- Emergency Services:Pre-hospital and inter-facility transport teams operating where mechanical ventilator availability remains constrained. Australian and Canadian ambulance systems are standardizing T-piece resuscitators for neonatal transfers requiring portable pressure-controlled ventilation.
- Clinics:Outpatient and community birthing centers with limited critical care escalation pathways.
- Homecare:Rare domestic applications for chronic respiratory support with caregiver training requirements.
Procurement concentration sits with hospitals; channel expansion is accelerating fastest through emergency services.
Application:
Clinical workflows differentiate between acute stabilization scenarios and controlled anesthesia environments.
- Emergency Resuscitation:Delivery room and crash-cart deployment requiring immediate pressure-controlled ventilation without mechanical ventilator setup time. ISO 10651-4 performance standards govern these manually operated devices for emergency and transport settings.
- Neonatal Care:Specialized stabilization protocols for preterm infants with surfactant-deficient lungs. This segment climbs the fastest as survival thresholds extend to earlier gestational ages and gentle ventilation approaches displace historical bag-valve-mask techniques.
- Anesthesia Delivery:Induction and maintenance support in operating suites with backup mechanical ventilation readily available.
- Patient Transport:Inter-facility transfer applications where device portability and gas independence matter more than precision.
Protocol standardization anchors emergency resuscitation; technology convergence is reshaping neonatal care.
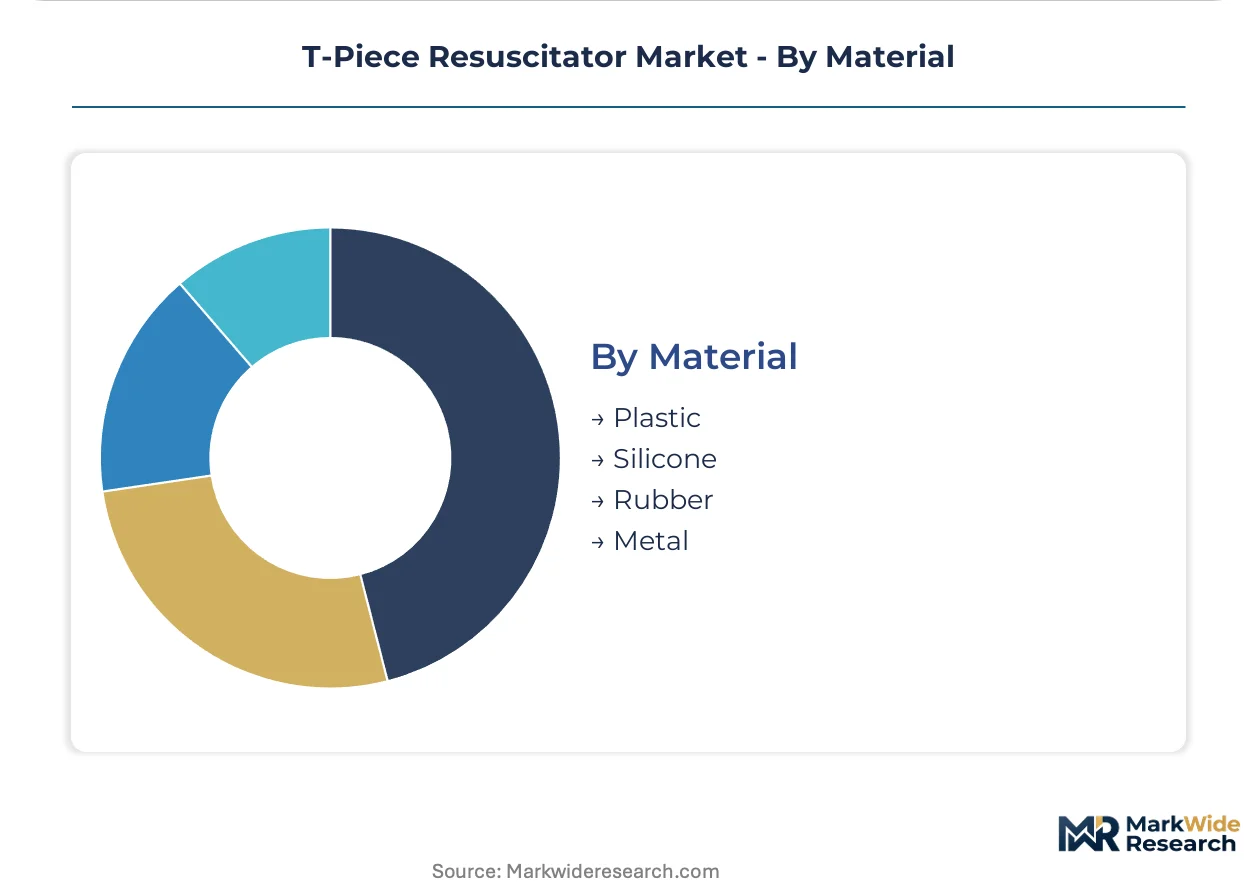
Material:
Supply geography and sterilization compatibility drive material selection across product tiers.
- Silicone:Medical-grade elastomer enabling tight pressure tolerances and biocompatibility for neonatal contact applications. German and Japanese feedstock concentration exposes manufacturers to input cost volatility despite superior performance characteristics.
- Plastic:Thermoplastic polymers dominating disposable manufacturing with lower per-unit cost and simplified sterilization-free workflows.
- Rubber:Legacy elastomer formulations with declining share due to latex sensitivity concerns and shorter service life.
- Metal:Structural components for valve assemblies and pressure regulators in reusable device architectures.
Performance requirements favor silicone; cost and infection control favor plastic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Level IV NICU departments in tertiary hospitals concentrate procurement volume for pressure-controlled resuscitation equipment. Bundled payment models for perinatal care in the United States align financial incentives around standardized disposable protocols. Emerging perinatal systems in Asia-Pacific and Latin America present channel expansion opportunities for manufacturers with cost-optimized product architectures.
United States
FDA 510(k) premarket notification requirements govern Class II respiratory device approvals, accelerating product iterations for neonatal applications. Bundled payment models for perinatal care concentrate procurement authority within hospital value analysis committees. Texas Medical Center in Houston and Boston's Longwood Medical Area anchor demand clusters where Level IV NICU expansion mandates pressure-controlled resuscitation equipment.
Germany
EU Medical Device Regulation imposes extended clinical evidence timelines and unique device identification mandates for CE marking renewal. Medical-grade silicone and thermoplastic elastomer feedstock production clusters in the industrial regions of Bavaria and Baden-Württemberg expose device manufacturers to input cost volatility. Berlin and Munich tertiary hospitals drive adoption of precision-engineered neonatal T-pieces with integrated pressure monitoring.
India
Government-funded maternal health programs and medical college hospital upgrades create procurement volume for disposable resuscitation devices. CDSCO medical device regulations establish quality standards for imported and domestically manufactured respiratory equipment. Tier-2 and tier-3 cities in Maharashtra and Gujarat represent the fastest-expanding demand nodes as perinatal care infrastructure extends beyond metropolitan centers.
Australia
TGA therapeutic goods administration enforces conformity assessment procedures for manually operated resuscitators used in emergency and transport settings. Pre-hospital care systems standardize T-piece resuscitators for inter-facility neonatal transport where mechanical ventilator backup remains unavailable. Melbourne and Sydney anchor procurement concentration for emergency medical services channel expansion.
Japan
PMDA pharmaceutical and medical device agency reviews premarket applications for neonatal respiratory devices under risk-based classification frameworks. METI industrial policy supports domestic manufacturing of medical-grade silicone components with tight pressure tolerance specifications. Tokyo and Osaka metropolitan areas concentrate tertiary hospital demand for precision-engineered resuscitation equipment.
T-Piece Resuscitator Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments where hospital value analysis committees, emergency medical services directors, and government health ministries exercise divergent purchasing criteria. The vendor base organizes around three strategic archetypes: disposable portfolio specialists capturing high-turnover clinical environments, training-integrated platform providers sustaining emergency medical services relationships, and premium ventilator manufacturers embedding T-piece modules into critical care architectures. Dominant competitive moves include geographic expansion into Indian perinatal care infrastructure and technology licensing for closed-loop feedback sensor integration.
Within the premium-tier vector, Drägerwerk AG & Co. KGaA and Fisher & Paykel Healthcare occupy positions anchoring ventilator-integrated product ecosystems. Ambu A/S exemplifies the disposable portfolio specialist archetype, while Laerdal Medical represents the training-integrated platform provider model. These three entities collectively illustrate how competitive positioning fragments across infection control mandates, emergency services channel depth, and critical care architecture integration.
| Leading Market Players |
|---|
| Ambu A/S |
| Laerdal Medical |
| Fisher & Paykel Healthcare |
| Flexicare (Group) Limited |
| Vyaire Medical |
| Medtronic |
| Drägerwerk AG & Co. KGaA |
| Neotech Medical Systems |
| Mercury Medical |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-to-Singapore container freight corridors transmit medical-grade silicone cost volatility directly into T-piece resuscitator landed prices, concentrating margin pressure on manufacturers without captive polymer sourcing while enabling tiered pricing separation between sensor-embedded premium disposables and basic transport-grade devices.
Pricing Analysis
Cost-plus contracts with medical-grade silicone indexation dominate procurement between German feedstock suppliers and device manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared sensor-integrated disposables from basic ISO 10651-4 compliant transport units and unmonitored emergency variants. Pricing pressure stems from hospital value analysis committee consolidation under bundled perinatal payment models. Emergency medical services exhibit highest price sensitivity due to constrained capital budgets, while Level IV NICU departments prioritize infection control compliance over unit cost.
Supply Chain Analysis
Export control restrictions on precision pressure sensor technology limit component flows from Japanese and German suppliers to non-aligned manufacturing jurisdictions. Medical-grade silicone production concentrates in Bavaria and Baden-Württemberg, with thermoplastic elastomer feedstock clustering in Osaka and Nagoya industrial corridors. Component sourcing draws from specialty polymer compounders, miniature sensor foundries, and medical device contract manufacturers. Single-source vulnerability pervades high-tolerance silicone molding capacity. Distribution runs through hospital GPO contracts, emergency services procurement consortiums, and government health ministry tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital system mergers and GPO consolidation, shifting procurement leverage toward value analysis committees with standardized disposable mandates.
For Market Incumbents: Pre-empt portable ventilator substitution by embedding closed-loop feedback algorithms that narrow the precision gap with mechanical ventilation. Secure backward integration into medical-grade silicone compounding to insulate margin structures from feedstock volatility. Anchor hospital system relationships through training-integrated product ecosystems that synchronize with American Academy of Pediatrics curriculum revisions. For New Entrants and Emerging Players: Pursue tier-2 and tier-3 Indian city hospital procurement through cost-optimized disposable architectures that meet CDSCO quality standards without premium sensor integration. Target government-funded maternal health program tenders where price-performance thresholds favor simplified designs. Establish channel partnerships with domestic Indian distributors possessing existing relationships with medical college hospital procurement committees. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates with underoptimized neonatal respiratory portfolios lacking integrated software companion development. Long-term viability hinges on regulatory moat depth and recurring revenue from disposable replacement cycles rather than capital equipment placement. Watch FDA 510(k) clearance velocity for sensor-integrated disposables as inflection indicator for premium tier competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Accelerates predicate device strategies for sensor-embedded neonatal disposables in tertiary hospitals. |
| Closed-Loop Feedback Integration | Collapses precision gaps between manual T-pieces and mechanical ventilators in delivery room protocols. |
| Indian Distribution Partnership | Unlocks government-funded maternal health program procurement in tier-2 and tier-3 cities. |
| Silicone Feedstock Integration | Captures margin protection from German and Japanese polymer supply concentration. |
| Emergency Services Channel Expansion | Standardizes T-piece deployment for inter-facility neonatal transport in Australian and Canadian systems. |
Research Methodology
The analysis maps disposable T-piece, neonatal T-piece, reusable T-piece, and adult T-piece sub-sectors, each validated through neonatologists, hospital purchasing committee directors, biomedical engineers, and emergency medical services procurement leads. Primary interview data triangulates against FDA 510(k) premarket notification databases, ISO 10651-4 compliance registries, hospital GPO contract repositories, and EU MDR notified body documentation. Bottom-up unit demand modeling reconciles with top-down tertiary hospital infrastructure expansion trajectories.
Assumption sets held FDA 510(k) clearance timelines and EU MDR transition deadlines fixed while varying Level IV NICU bed expansion rates and bundled payment model adoption curves across the projection horizon. Segmentation dimensions include product architecture, patient population vulnerability tier, end-user capital intensity, and regional regulatory cluster. CAGRs derive from installed base replacement cycle analysis and perinatal protocol standardization velocity. Forecast inputs incorporate medical-grade silicone price index movements and neonatal resuscitation program certification revision schedules.
Sensitivities concentrate around EU MDR clinical evidence requirement stringency and FDA predicate device pathway modifications. Forecasts reflect documented assumptions regarding hospital infection prevention committee mandate propagation. Material shifts in medical-grade polymer supply geography or neonatal ventilation protocol standardization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Nerve Monitoring System Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Asia-Pacific Ultrasound Devices Market
Medical Devices
Lacrimal Devices Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Prosthetic Liners Market
Medical Devices
Laparoscopic Devices Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
India Diabetes Devices Market
Medical Devices
Solar Surgical Light Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Transportable Ventilator Market
Medical Devices
Global Gastric Balloons Market
Medical Devices
Sleep Apnea Implants Market
Medical Devices
Anti-Decubitus Dynamic Mattress Market
Medical Devices
Keratoprosthesis (Kpro) Market