
 Global Artificial Skin Market | 2026-2036
Global Artificial Skin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Skin Market Foresight
Collagen-based matrices are restructuring product economics across the artificial skin landscape as clinicians seek biocompatible alternatives to synthetic polymers. MiMedx Group leverages its placental tissue platform to dominate the chronic wound segment. Integra LifeSciences anchors its position through deep specialization in bilayer matrix technology for burn reconstruction. Smith & Nephew competes on manufacturing scale, extending its hospital distribution network across North America and Europe.
Artificial skin comprises engineered biological or synthetic membranes designed to replicate human epidermal and dermal functions, typically incorporating collagen, silicone, or polyurethane layers with pore sizes ranging from 20 to 120 microns to facilitate gas exchange and cellular infiltration. These constructs serve primarily to accelerate wound closure, reduce infection risk, and restore barrier function in patients with partial- or full-thickness skin loss. Collagen-based products command the largest revenue share due to established reimbursement pathways and proven clinical outcomes in burn centers. 3D bioprinting represents the fastest-expanding technology segment as scaffold engineering advances enable patient-specific graft geometries with vascular channel integration.
The FDA's regenerative medicine advanced therapy pathway compresses approval timelines for cell-cultured artificial skin products, while the EU Medical Device Regulation imposes stricter clinical evidence requirements on silicone-based permanent implants. Health Canada's PMRA aligns with FDA precedents for biologic-synthetic combination products, creating a harmonized North American access corridor. Stakeholders must monitor evolving reimbursement codes for bioengineered skin substitutes as payers scrutinize cost-effectiveness against standard of care.
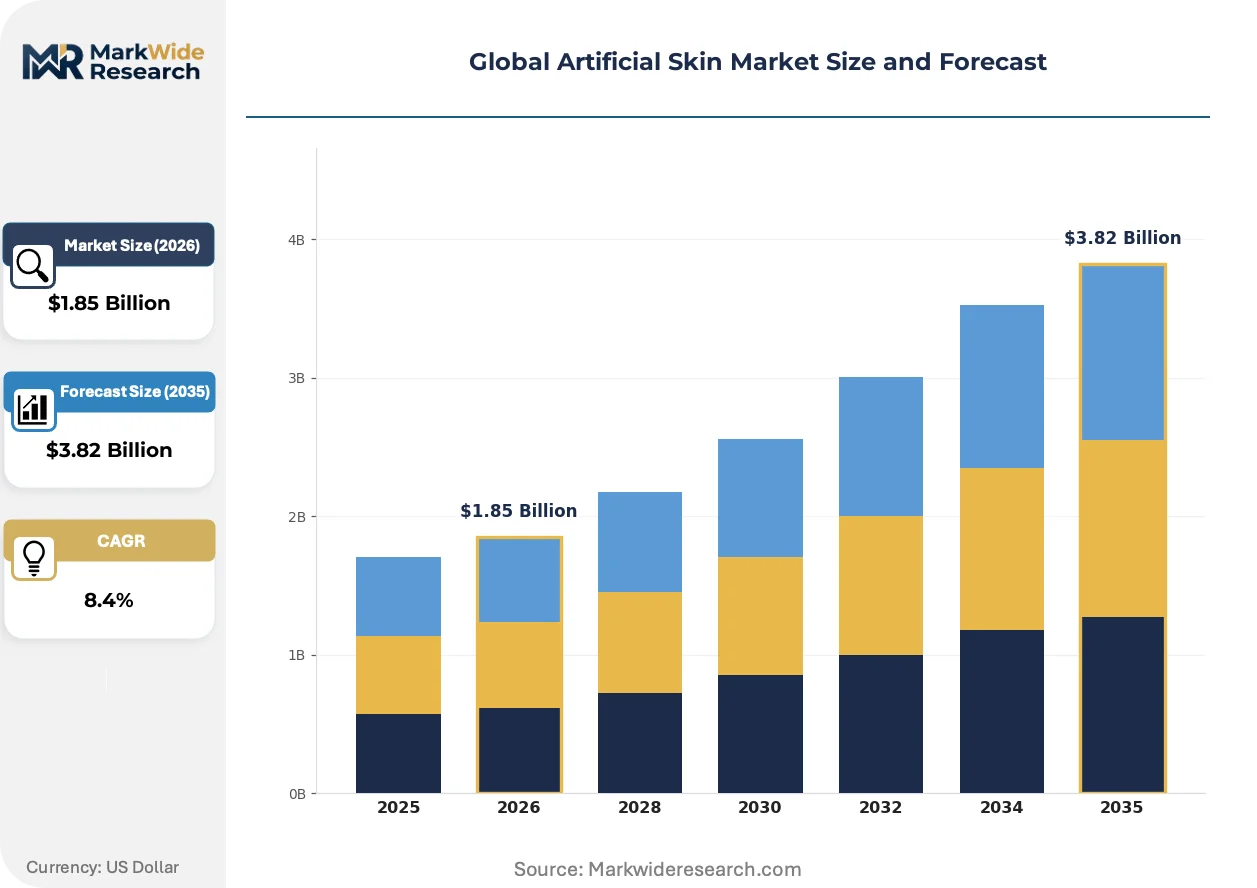
Market Dynamics
3D bioprinting is compressing development cycles for patient-specific grafts while FDA regenerative medicine pathways accelerate commercialization timelines for cell-cultured substitutes.
Growth Catalysts
- Regenerative Medicine Advanced Therapy (RMAT) Designation:The FDA's expedited review pathway for cell-based artificial skin products compresses approval timelines from years to months. Burn centers in the United States are prioritizing RMAT-designated products in procurement protocols.
- Collagen Matrix Biocompatibility:Clinicians in Germany's specialized burn care hospital network are standardizing collagen-based matrices as first-line therapy for partial-thickness wounds. Established reimbursement codes in the German healthcare system support this transition.
- Silicone-Polyurethane Hybrid Engineering:Advances in bilayer membrane fabrication are enabling simultaneous moisture retention and gas exchange in chronic wound applications. Wound care specialists are adopting these constructs for diabetic ulcer management.
Market Restraints
- Bovine Collagen Supply Concentration:Over 70% of medical-grade collagen derives from herds in the United States and Brazil, creating geographic supply risk. Tissue processing capacity constraints in these regions limit production scaling.
- EU Medical Device Regulation (MDR) Clinical Evidence Burden:The MDR's stricter requirements for permanent silicone-based implants demand extensive long-term safety data. Small manufacturers lack capital to generate this evidence, consolidating market access.
- Autologous Skin Graft Substitution:Split-thickness autografting remains the gold standard for full-thickness burns in resource-constrained settings. Harvest site morbidity trade-offs are increasingly acceptable where artificial skin costs exceed reimbursement ceilings.
Strategic Opportunities
- India's Underpenetrated Chronic Wound Segment:Diabetic foot ulcer prevalence in India exceeds 15 million cases annually, yet bioengineered skin substitute penetration remains below 5%. The country's PLI scheme for medical device manufacturing offers production incentives for domestic fabrication.
- 3D Bioprinting-Vascular Channel Convergence:Integration of sacrificial hydrogel printing with endothelial cell seeding is enabling prevascularized grafts thicker than 200 microns. Research hospitals in Japan are piloting these constructs for deep dermal reconstruction.
- Direct-to-Hospital Distribution Platforms:Specialized wound care distributors are bypassing traditional medical-surgical wholesalers to deliver temperature-controlled biologics. This channel innovation reduces cold-chain breakage rates for cell-cultured products.
Industry Challenges
- Scaffold Bioprinting Talent Scarcity:The intersection of biomaterials science, tissue engineering, and computational design requires rare hybrid expertise. Universities in Germany and the United States are struggling to graduate sufficient specialists.
- Good Manufacturing Practice (GMP) Facility Capex:Cell-cultured artificial skin production requires ISO 14644 Class 7 cleanrooms and automated bioreactor systems. Facility construction costs exceed $50 million, excluding validation timelines.
- Biologic-Synthetic Combination Product Classification:Regulatory uncertainty at the FDA and EMA regarding whether products containing both cellular components and synthetic scaffolds should follow drug, device, or biologic pathways creates submission delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Skin Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen-Based, Silicone-Based, Polyurethane-Based, Composite Membranes Technology: 3D Bioprinting, Electrospinning, Cell Culture, Scaffold Engineering Application: Burn Treatment, Chronic Wound Healing, Cosmetic Surgery, Dermatological Research End User: Hospitals, Research Laboratories, Cosmetic Clinics, Pharmaceutical Companies |
| Companies Covered | MiMedx Group, Inc., Avita Medical Limited, Integra LifeSciences Corporation, Molnlycke Health Care AB, Medtronic plc, Smith & Nephew plc, Vericel Corporation, Johnson & Johnson Services, Inc., Organogenesis Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Skin Market Shifts & Advancements
Biofabrication technologies are converging with digital health infrastructure to enable real-time graft monitoring, while regulatory harmonization efforts across North America and Europe are streamlining multi-jurisdictional product launches.
Multimaterial 3D bioprinting is unifying spatially patterned collagen deposition with embedded growth factor gradients in single fabrication runs. Burn reconstruction centers in the United States are piloting these constructs for complex facial wound geometries. The technology is unifying previously separate scaffold manufacturing and bioactive loading steps into integrated production workflows.
The EU Medical Device Regulation's 2021 implementation is forcing silicone-based permanent implant manufacturers to generate post-market clinical follow-up data. German and French notified bodies are prioritizing reviews for products with existing FDA 510(k) clearance. Cell-cultured substitutes with limited long-term implantation history face extended conformity assessment timelines.
Hospital procurement departments are consolidating artificial skin purchasing through value-analysis committees rather than individual physician preference. Integrated delivery networks in the United States are negotiating system-wide contracts with manufacturers offering outcome guarantees. This concentration is most visible in California and Texas, where large health systems command 40% of state-level burn center volume.
Global Artificial Skin Market Segmentation
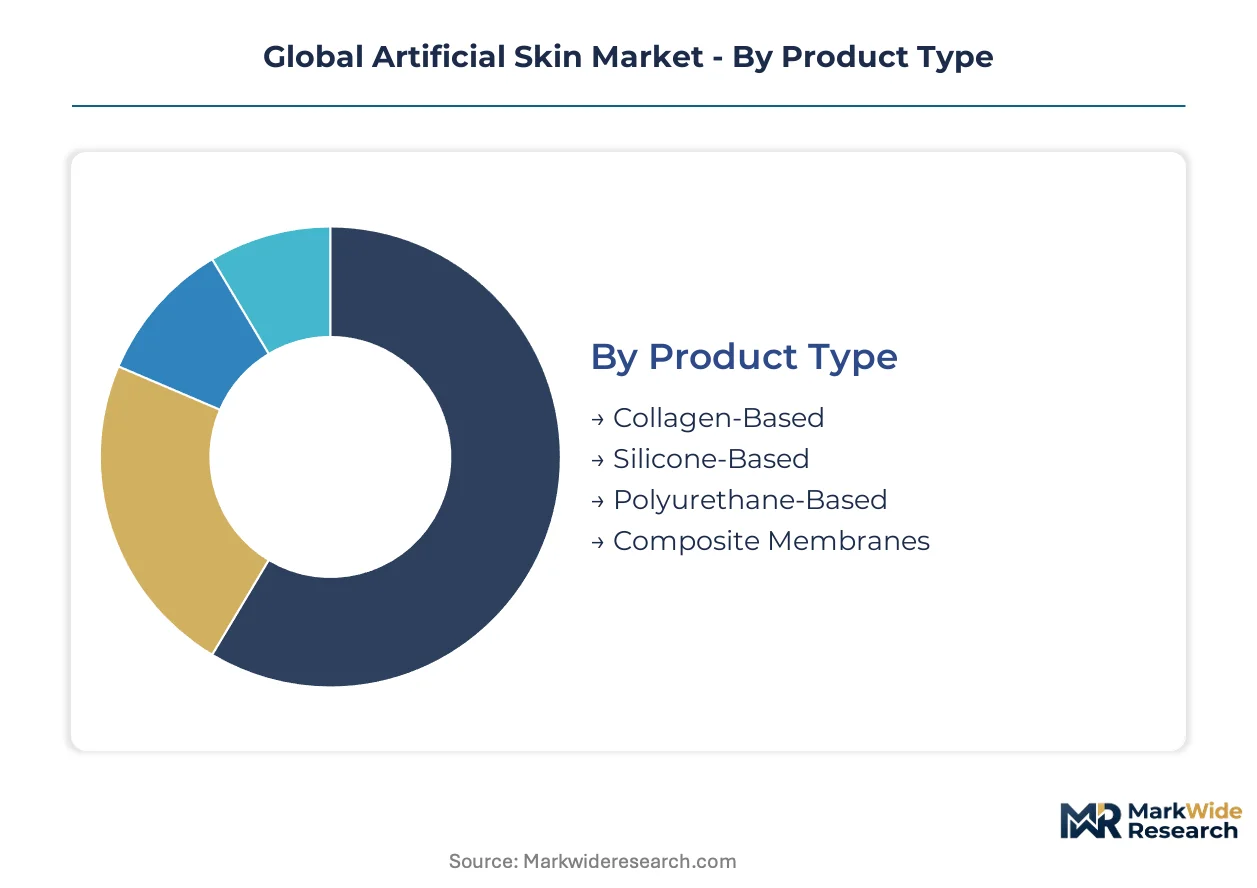
Artificial skin segmentation reflects divergent manufacturing economics across biologic and synthetic platforms. Product type determines raw material sourcing complexity, while technology choice governs capital deployment intensity and regulatory pathway selection.
Product Type:
Capital requirements vary sharply across this category, with biologic extraction and purification demanding specialized tissue processing infrastructure that synthetic polymer lines avoid entirely.
- Collagen-Based:Derived from bovine or porcine dermal tissue through enzymatic extraction and crosslinking protocols. Demand concentrates in Germany's specialized burn care hospital network where established reimbursement codes support first-line therapy adoption for partial-thickness wounds.
- Silicone-Based:Manufactured through platinum-catalyzed addition curing of polydimethylsiloxane precursors into bilayer membranes with controlled pore architecture. Burn centers in the United States prioritize these constructs for moisture retention in chronic wound management, though EU MDR compliance costs now favor larger manufacturers with post-market surveillance capacity.
- Polyurethane-Based:Thermoplastic elastomer formulations offering tunable degradation profiles for temporary wound coverage applications.
- Composite Membranes:Hybrid constructs integrating collagen matrices with synthetic polymer backbones for combined biocompatibility and mechanical strength.
Collagen-based products absorb the bulk of installed capacity; composite membranes are expanding most quickly as clinicians seek optimized performance profiles.
Technology:
Process scalability separates segments here, with cell culture requiring ISO Class 7 cleanrooms and bioreactor automation that electrospinning equipment avoids.
- 3D Bioprinting:Multimaterial deposition systems spatially pattern collagen with embedded growth factor gradients and sacrificial hydrogel channels for prevascularization. Research hospitals in Japan are piloting patient-specific graft geometries exceeding 200 microns thickness for deep dermal reconstruction.
- Cell Culture:Autologous or allogeneic keratinocyte and fibroblast expansion on biodegradable scaffolds under GMP conditions. The FDA's RMAT designation compresses approval timelines for these products, accelerating procurement prioritization in United States burn centers.
- Electrospinning:High-voltage fiber drawing from polymer solutions produces nanofibrous matrices with high surface-area-to-volume ratios.
- Scaffold Engineering:Decellularized tissue matrices and synthetic porous structures providing architectural templates for cellular infiltration.
Cell culture commands the highest facility investment per square meter; 3D bioprinting shows the steepest expansion trajectory as computational design capabilities mature.
Application:
Reimbursement density determines segment economics, with burn treatment offering established payment pathways that cosmetic surgery lacks.
- Burn Treatment:Full-thickness and partial-thickness thermal injury coverage using temporary or permanent skin substitutes. United States burn centers are expanding adoption of advanced wound care solutions as specialized treatment networks consolidate procurement.
- Chronic Wound Healing:Diabetic foot ulcer and venous leg ulcer management with bioengineered constructs. India's underpenetrated market exceeds 15 million annual diabetic foot ulcer cases, yet bioengineered substitute penetration remains minimal.
- Cosmetic Surgery:Aesthetic reconstruction and scar revision applications with premium pricing structures.
- Dermatological Research:In vitro disease modeling and pharmaceutical testing platforms using engineered skin equivalents.
Burn treatment absorbs the bulk of installed capacity; chronic wound healing is gaining share fastest as diabetic prevalence rises in emerging markets.
End User:
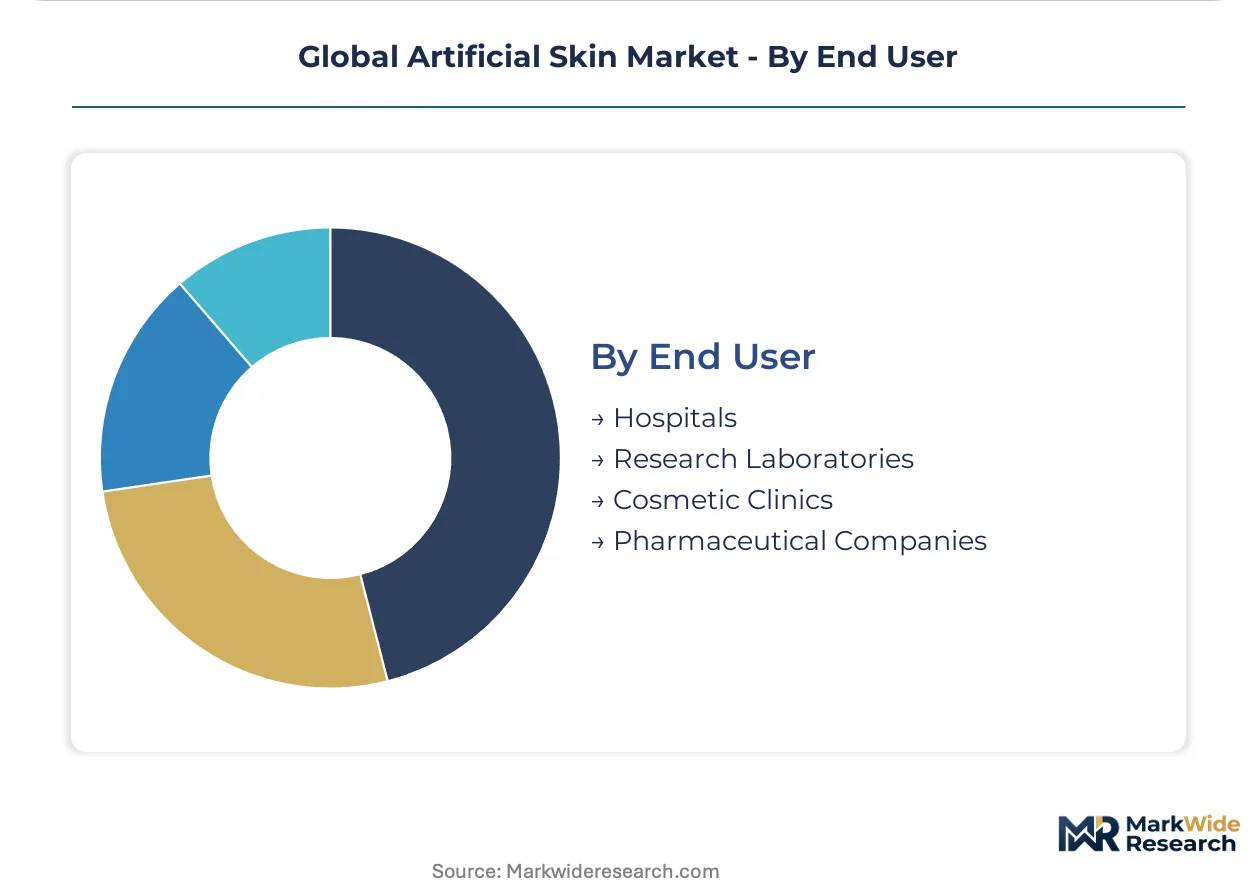
Purchasing sophistication varies across this category, with hospital value-analysis committees imposing outcome guarantees that research laboratories escape.
- Hospitals:Integrated delivery networks in California and Texas command 40% of state-level burn center volume and negotiate system-wide contracts with manufacturers. Temperature-controlled logistics requirements favor distributors with direct-to-hospital platforms over traditional medical-surgical wholesalers.
- Research Laboratories:Academic and commercial facilities developing next-generation constructs through scaffold engineering and bioprinting innovation. Universities in Germany and the United States struggle to graduate sufficient hybrid specialists spanning biomaterials science, tissue engineering, and computational design.
- Cosmetic Clinics:Outpatient aesthetic practices with physician-directed purchasing and limited bulk procurement leverage.
- Pharmaceutical Companies:Contract research and toxicology testing operations utilizing engineered skin equivalents for regulatory submission support.
Hospitals absorb the bulk of installed capacity; research laboratories are climbing the fastest as public and private funding flows into biofabrication innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for artificial skin concentrates in specialized burn treatment networks across Germany and the United States, where reimbursement density supports advanced wound care adoption. Regulatory acceleration through FDA's RMAT pathway and Germany's established hospital procurement systems create divergent access corridors. Manufacturing clusters in Japan and India are emerging as complementary supply nodes.
United States
Burn centers in California and Texas command 40% of national treatment volume and negotiate system-wide procurement contracts. The FDA's Regenerative Medicine Advanced Therapy designation compresses approval timelines for cell-cultured products from years to months. Boston's research corridor anchors 3D bioprinting innovation for patient-specific graft geometries.
Germany
Specialized burn care hospitals standardize collagen-based matrices as first-line therapy for partial-thickness wounds. The EU Medical Device Regulation imposes stricter clinical evidence requirements on silicone-based permanent implants. Munich's medical technology cluster hosts notified bodies prioritizing reviews for products with existing FDA clearance.
Japan
Research hospitals pilot prevascularized grafts exceeding 200 microns thickness for deep dermal reconstruction. METI funding flows into biofabrication innovation at academic medical centers. Osaka-Kobe's biomedical corridor concentrates scaffold engineering expertise and hybrid specialist training programs.
India
Diabetic foot ulcer prevalence exceeds 15 million cases annually yet bioengineered substitute penetration remains below 5%. The PLI scheme for medical device manufacturing offers production incentives for domestic fabrication. Maharashtra's pharmaceutical corridor is attracting contract manufacturers seeking cost-advantaged cleanroom capacity.
Canada
Health Canada's PMRA aligns with FDA precedents for biologic-synthetic combination products, creating harmonized North American access. Toronto's hospital networks participate in integrated delivery network procurement alongside US systems. Vancouver's regenerative medicine cluster specializes in cold-chain logistics for temperature-controlled biologics distribution.
Global Artificial Skin Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated wound care companies commanding hospital procurement channels while tissue processors supply raw biologic materials. The market structures around three tiers: multinational medical device conglomerates with system-wide distribution agreements, mid-cap regenerative medicine specialists with RMAT-designated portfolios, and regional tissue processors serving single-country reimbursement systems. Consolidation pressure intensifies as GMP facility capex requirements exceed $50 million, favoring players with captive capital or strategic partnerships.
Within the regenerative medicine specialist tier, MiMedx Group exemplifies placental tissue platform dominance in chronic wound segments, while Integra LifeSciences anchors bilayer matrix specialization for burn reconstruction. Smith & Nephew occupies a position defined by manufacturing scale and hospital distribution network extension across North America and Europe.
| Leading Market Players |
|---|
| MiMedx Group, Inc. |
| Avita Medical Limited |
| Integra LifeSciences Corporation |
| Molnlycke Health Care AB |
| Medtronic plc |
| Smith & Nephew plc |
| Vericel Corporation |
| Johnson & Johnson Services, Inc. |
| Organogenesis Inc. |
| Others |
Supply & Pricing Matrix
Hospital value-analysis committee consolidation in California and Texas health systems is compressing supplier margins and forcing manufacturers toward outcome-guarantee contracting models that favor scaled players with captive GMP facilities.
Pricing Analysis
Volume concentration in integrated delivery networks splits the market between high-margin specialty contracts and commoditized standard-tier supply. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by FDA RMAT designation status and GMP certification tier. Pricing pressure stems from Medicare reimbursement code scrutiny on bioengineered skin substitutes versus standard wound care. Research laboratories exhibit lowest price sensitivity due to grant-funded procurement, while cosmetic clinics face highest sensitivity from out-of-pocket patient payment constraints.
Supply Chain Analysis
Temperature-controlled reverse logistics for expired or compromised cell-cultured grafts remains underdeveloped, with most manufacturers absorbing total loss rather than refurbishment. Raw material supply concentrates in the United States and Brazil for bovine collagen, Japan for precision bioreactor components, and Germany for crosslinking reagents. Production draws from medical-grade herd certification programs, platinum-catalyzed silicone precursors, and sacrificial hydrogel formulations. Single-source vulnerability runs through the concentrated bovine tissue processing infrastructure. Distribution runs through direct-to-hospital specialty platforms bypassing traditional medical-surgical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as GMP facility capex exceeding $50 million pushes mid-cap specialists toward captive bioreactor construction or strategic partnerships with contract manufacturers.
For Market Incumbents: Deepen backward integration into bovine tissue processing to secure collagen supply against geographic concentration risk in the United States and Brazil. Expand GMP cleanroom capacity in low-cost manufacturing corridors to offset facility construction cost inflation. Defend against autologous skin graft substitution in resource-constrained settings by embedding outcome guarantees in IDN procurement contracts. For New Entrants and Emerging Players: Enter via India's underpenetrated chronic wound segment where diabetic foot ulcer prevalence exceeds 15 million cases annually yet bioengineered substitute penetration remains minimal. Target Maharashtra's pharmaceutical corridor for contract manufacturing partnerships leveraging PLI scheme incentives. Pursue direct-to-hospital distribution platforms to bypass established wholesaler relationships controlled by incumbents. For Investors and Strategic Acquirers: The window for entry favors mid-cap regenerative medicine specialists with RMAT-designated portfolios and existing hospital procurement relationships over de novo platform development. Long-term viability centers on convergence of 3D bioprinting capabilities with prevascularized graft manufacturing. Monitor FDA RMAT designation velocity and EU MDR conformity assessment timelines as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| RMAT Designation Pursuit | FDA's expedited pathway compresses approval timelines from years to months for cell-cultured products. |
| GMP Facility Expansion | ISO 14644 Class 7 cleanroom construction exceeds $50 million, favoring capitalized players. |
| Direct-to-Hospital Distribution | Temperature-controlled logistics platforms reduce cold-chain breakage for cell-cultured substitutes. |
| Prevascularized Graft Development | Sacrificial hydrogel printing with endothelial seeding enables grafts thicker than 200 microns. |
| EU MDR Conformity Preparation | German and French notified bodies prioritize reviews for products with existing FDA 510(k) clearance. |
Research Methodology
FDA 510(k) filings, EMA submission databases, and CMS Medicare reimbursement code records formed the secondary backbone for market sizing validation. Primary interviews with burn center procurement directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists at regenerative medicine companies provided demand-side calibration. Bottom-up facility capacity modeling and top-down health system expenditure analysis were triangulated against hospital procurement database trends.
Historical trendline analysis of collagen matrix adoption in German burn care networks and silicone-based implant utilization in United States chronic wound centers established baseline penetration curves. Segmentation modeling spanned product type, technology platform, application severity, and end-user purchasing sophistication across the projection horizon. CAGRs were derived from facility capacity expansion announcements, regulatory approval velocity, and reimbursement code evolution rather than extrapolation of historical growth rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR implementation delays or bovine collagen supply disruptions from herd health events. Practitioners should monitor FDA RMAT designation grant rates, German hospital procurement consolidation patterns, and India's PLI scheme disbursement velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Personal-Use Facial and Skin Therapy Devices Market
Medical Devices
Home-Use Water Flosser Market
Medical Devices
Pen Injectors Market
Medical Devices
Global Spinal Motion Preservation Device Market
Medical Devices
Allografts Market
Medical Devices
US Clear Aligners Market
Medical Devices
Lacrimal Duct Stent Tube Market
Medical Devices
Flow Diverters Market
Medical Devices
Spherical IOL Market
Medical Devices
Smart Stairlift Market
Medical Devices
Wireless Neurostimulator Market
Medical Devices
United Kingdom Respiratory Devices Market
Medical Devices
Stimulation Therapies Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
Airway Clearance Systems Market
Medical Devices
Knee Braces Market