
 Solar Panel Lights Market | 2026-2036
Solar Panel Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Panel Lights Market Insights
Lithium iron phosphate is decoupling solar panel lights from the shorter replacement cycles that plagued earlier nickel-metal hydride generations. Signify Holding leverages its LED heritage to dominate premium architectural and street-lighting segments across European and North American municipalities. Sunna Design anchors its competitive position through integrated lithium battery management systems designed specifically for equatorial and subtropical deployment conditions. Greenshine New Energy competes on manufacturing scale, sustaining cost advantages in bulk government tenders for highway and perimeter illumination.
Solar panel lights are photovoltaic-powered illumination systems converting solar radiation into stored electrical energy for autonomous operation, typically incorporating monocrystalline or polycrystalline silicon cells with efficiencies between 18% and 22%, paired with solid-state LED emitters rated for 50,000 to 100,000 hours of service. Their primary purpose is to deliver off-grid lighting for infrastructure, residential, and commercial applications where grid extension proves uneconomical or unreliable. Street lights command the dominant share of public-sector procurement volumes, while portable lights represent the fastest-expanding category as outdoor recreation and emergency preparedness segments accelerate adoption. LED technology leads across all product categories, displacing legacy CFL and halogen architectures due to superior luminous efficacy and compatibility with low-voltage DC photovoltaic systems.
FCC certification governs radio-frequency components in smart solar luminaires sold in the United States, while the EU Green Deal and F-Gas Regulation are accelerating phase-outs of mercury-containing lamps that indirectly bolster solid-state solar lighting demand. India's BIS mandates product safety and performance standards for solar photovoltaic systems, including luminaires procured under government rural electrification schemes. Stakeholders must monitor how evolving battery safety standards and circular-economy mandates for photovoltaic waste reshape component sourcing and end-of-life liability across their supply bases.
Market Dynamics
Lithium iron phosphate battery chemistry is compressing replacement cycles and redirecting procurement budgets toward longer-horizon infrastructure planning across municipal and rural electrification programs.
Growth Catalysts
- Rural Electrification Mandates:India's Saubhagya scheme and state-level solar street-lighting tenders are absorbing inventory from domestic manufacturers and tightening cell supply chains.
- F-Gas Phase-Out Trajectory:The EU Green Deal's mercury lamp restrictions are accelerating solid-state retrofits in European municipal infrastructure, eliminating incumbent CFL maintenance contracts.
- Monocrystalline Efficiency Gains:Passivated emitter and rear contact cell architectures are pushing commercial module efficiency above 21%, reducing panel area requirements for equivalent lumen output.
Market Restraints
- Lithium Carbonate Volatility:Raw material price swings for battery-grade lithium salts are compressing margin structures for integrated luminaire assemblers without captive chemical supply.
- Southeast Asian Manufacturing Concentration:Vietnam and Thailand host over 70% of regional LED driver and battery pack assembly, exposing procurement timelines to monsoon logistics disruptions.
- Photovoltaic Degradation Floor:Silicon cell output decay of 0.5-0.8% annually creates performance guarantee liabilities that extend 15-20 years, straining warranty reserves.
Strategic Opportunities
- Portable Recreation Segment:Camping and emergency preparedness buyers in Australia and Japan are absorbing premium-priced all-in-one solar lantern units with USB power bank functionality.
- Smart City Integration:LoRaWAN and NB-IoT connectivity modules enable remote dimming and fault detection, opening recurring SaaS revenue streams from municipal maintenance contracts.
- Circular Economy Mandates:India's E-Waste Management Rules are creating certified recycling channel requirements that favor domestic manufacturers with established take-back infrastructure.
Industry Challenges
- Electrochemical Safety Certification:UN 38.3 lithium battery transport testing and IEC 62133 cell safety approvals are extending product launch timelines by 4-6 months for new entrants.
- Legacy Grid Integration Friction:Hybrid solar-grid luminaires require bidirectional inverters and net-metering compliance that municipal engineering departments lack technical capacity to evaluate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Panel Lights Market |
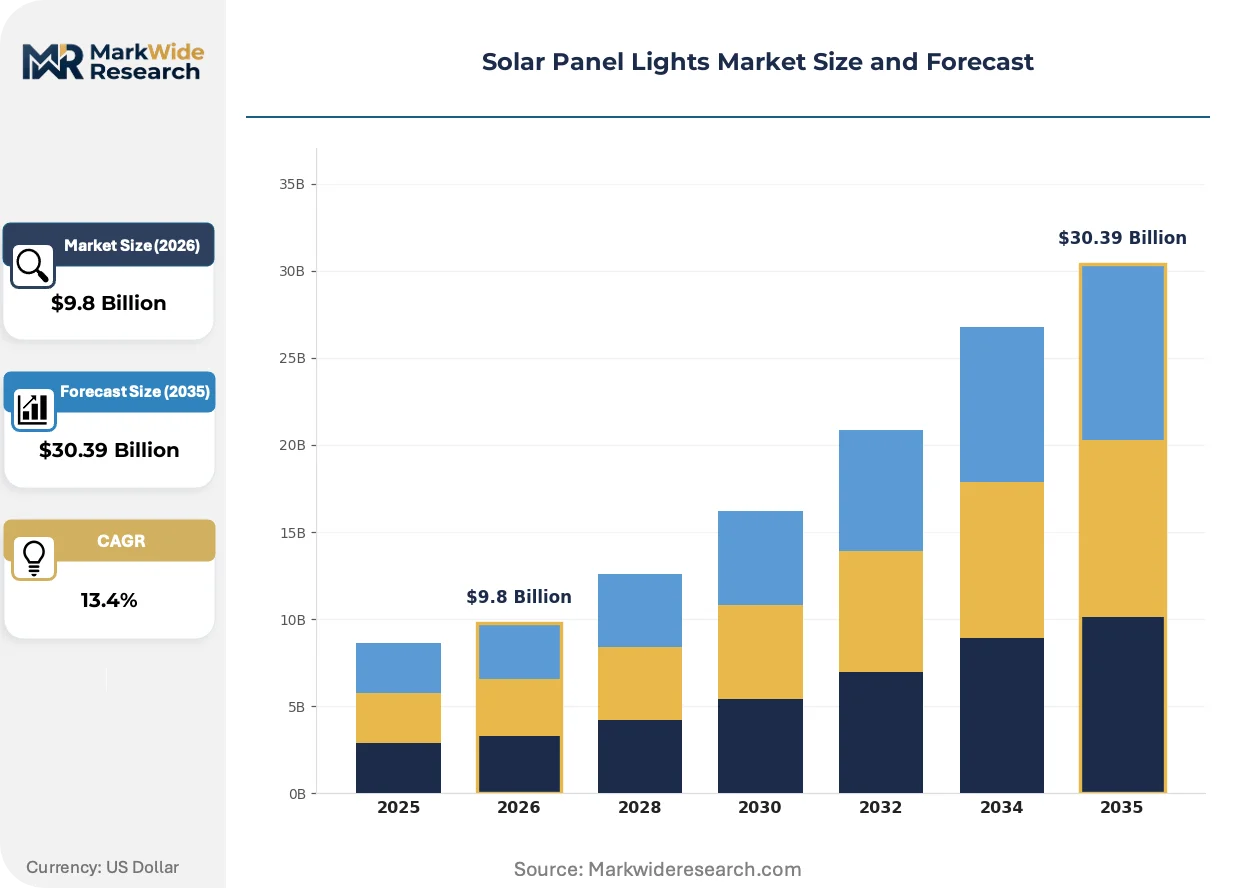
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $30.39 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Lights, Garden Lights, Street Lights, Flood Lights Technology: CFL, LED, Halogen, Solar Thermal End User: Residential, Commercial, Industrial, Government Application: Outdoor Lighting, Emergency Lighting, Landscape Lighting, Security Lighting |
| Companies Covered | Signify Holding (Philips), Sunna Design, Greenshine New Energy, Solar Electric Power Company (SEPCO), Solar Street Lights USA, Jinhua Sunmaster Lighting, Fonroche Lighting America, Gama Sonic, Sokoyo Solar Lighting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Panel Lights Market Trends and Innovations
Convergence between solid-state lighting and photovoltaic power electronics is collapsing the traditional separation between energy generation and consumption hardware in outdoor infrastructure.
Integrated maximum power point tracking controllers are unifying battery charging logic with LED driver electronics into single printed circuit board assemblies. Commercial street-lighting OEMs in Germany and California are adopting these consolidated architectures to reduce component count and field failure rates. This unification is compressing bill-of-material costs and accelerating the displacement of discrete charge controller suppliers from luminaire supply chains.
The EU F-Gas Regulation's mercury lamp prohibitions are forcing municipal maintenance departments to retire high-pressure sodium and metal halide inventories before end-of-design-life. Solid-state solar retrofits are capturing these accelerated replacement budgets across French and Italian provincial road networks. Street-lighting procurement specifications are tightening luminous efficacy minimums to 130 lumens per watt, effectively excluding legacy fluorescent and induction technologies from competitive tendering.
Municipal buyers are consolidating vendor relationships around full-service maintenance contracts that bundle installation, remote monitoring, and battery replacement into per-lumen-hour pricing. This reconfiguration is displacing transactional equipment-only sales channels across Indian smart city tenders and Indonesian district-level road projects. Procurement officers in Maharashtra and Gujarat are now requiring 10-year performance guarantees with escrowed warranty deposits, favoring established domestic assemblers over import-dependent trading houses.
Solar Panel Lights Market Segmentation
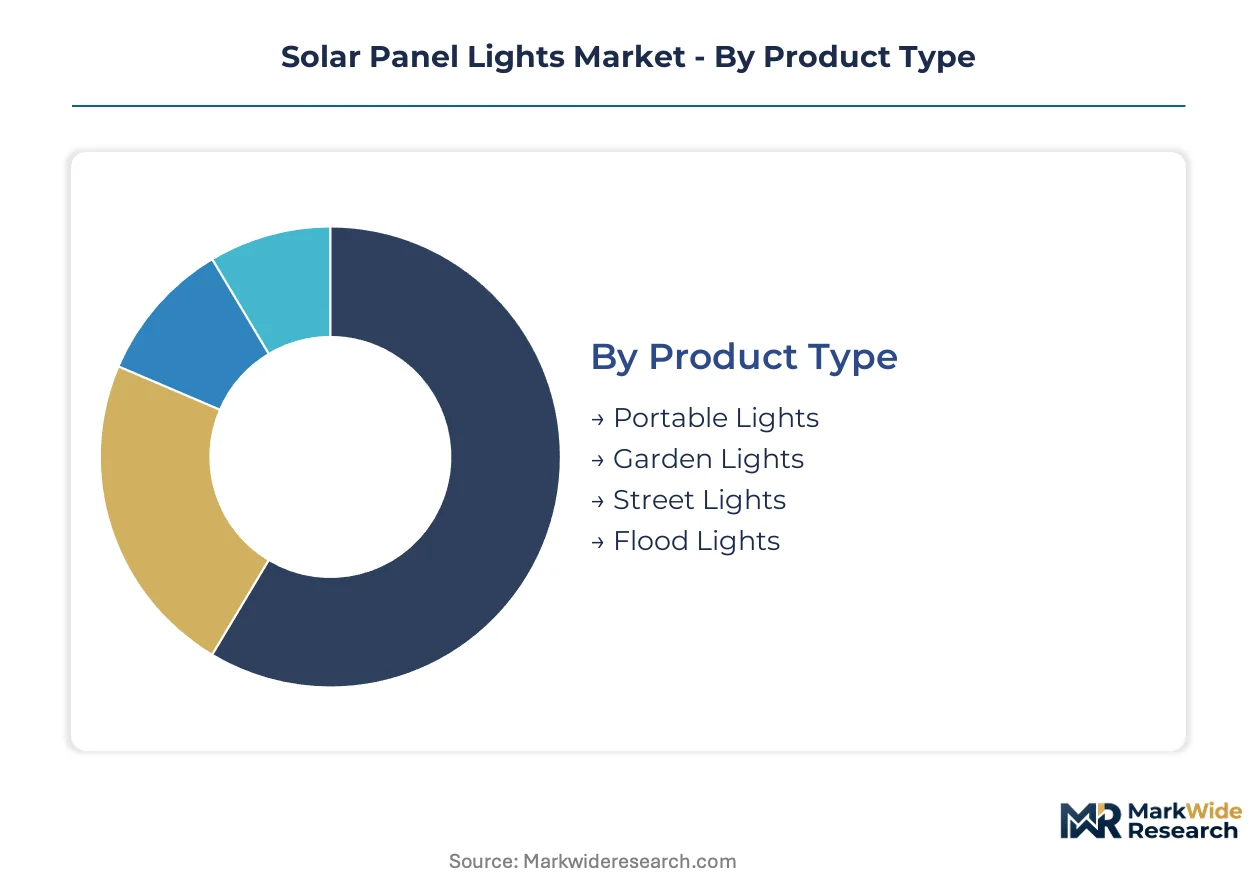
Solar panel lights span divergent performance requirements across portable consumer units and fixed infrastructure installations. Segment boundaries reflect competing pressures between luminous efficacy targets, battery chemistry durability, and procurement channel structures. Manufacturers configure product architectures around these divides to optimize margin capture and warranty liability exposure.
Product Type:
Specifications range from pocket-scale USB-chargeable units to pole-mounted municipal arrays with integrated lithium iron phosphate storage.
- Street Lights:Pole-mounted systems with 30-150 watt LED arrays and 200-1000 watt-hour battery banks serve highway and municipal road networks. India's state-level tenders under Saubhagya and smart city programs absorb the dominant procurement volumes, with Maharashtra and Gujarat requiring decade-long performance guarantees.
- Portable Lights:All-in-one lantern units with monocrystalline panels and USB power bank functionality target camping and emergency preparedness buyers. Australia and Japan absorb premium-priced inventory as outdoor recreation participation climbs and grid resilience concerns mount.
- Garden Lights:Low-voltage stake and bollard fixtures with 5-20 watt-hour nickel-metal hydride or lithium iron phosphate storage illuminate residential pathways. European consumer channels favor decorative form factors with dusk-to-dawn photocell activation.
- Flood Lights:High-output perimeter security fixtures with motion detection and 500+ lumen outputs protect commercial and industrial perimeters. Southeast Asian manufacturing clusters in Vietnam and Thailand concentrate assembly for bulk export to African and Latin American distributors.
Street lights lead on scale; portable lights lead on momentum.
Technology:
Cost tiers separate legacy discharge lamps from solid-state architectures with superior DC photovoltaic compatibility.
- LED:Solid-state emitters rated for 50,000-100,000 hours deliver 130+ lumens per watt efficacy, displacing all competing technologies across new installations. The EU F-Gas Regulation's mercury lamp prohibitions accelerate retrofit demand across French and Italian provincial networks.
- CFL:Compact fluorescent tubes with 8,000-12,000 hour lifespans and mercury content persist in budget residential garden fixtures. Circular-economy mandates under India's E-Waste Management Rules constrain import channels for mercury-containing inventories.
- Halogen:Tungsten-halogen incandescent sources with 2,000-hour lifespans and poor luminous efficacy survive only in ultra-low-cost portable accent lighting. Southeast Asian trading houses liquidate remaining inventory into price-sensitive African markets.
- Solar Thermal:Concentrating collector systems with molten salt storage serve niche industrial process heat applications, not illumination. This technology sits outside competitive lighting procurement channels entirely.
LED dominates installed value; CFL retains residual volume in price-sensitive replacement cycles.
End User:
Customer type determines procurement modality, warranty duration, and technical specification rigor.
- Government:Municipal and national agencies tender for street and perimeter lighting under 10-15 year performance contracts with escrowed warranty deposits. Indian state electricity boards and Indonesian district road departments consolidate vendor relationships around full-service maintenance agreements.
- Residential:Individual consumers purchase garden and portable units through retail and e-commerce channels with 1-3 year limited warranties. Japanese households absorb premium all-in-one solar lanterns with integrated smartphone charging.
- Commercial:Property developers and facility managers specify flood and landscape lighting for parking structures, campuses, and hospitality venues. Australian mining operations deploy autonomous solar perimeter arrays where grid extension proves uneconomical.
- Industrial:Heavy manufacturing and logistics sites require high-lumen security lighting with motion detection and remote monitoring integration. German industrial parks adopt LoRaWAN-connected luminaires for predictive maintenance workflows.
Government procurement anchors volume; residential channels expand most quickly.
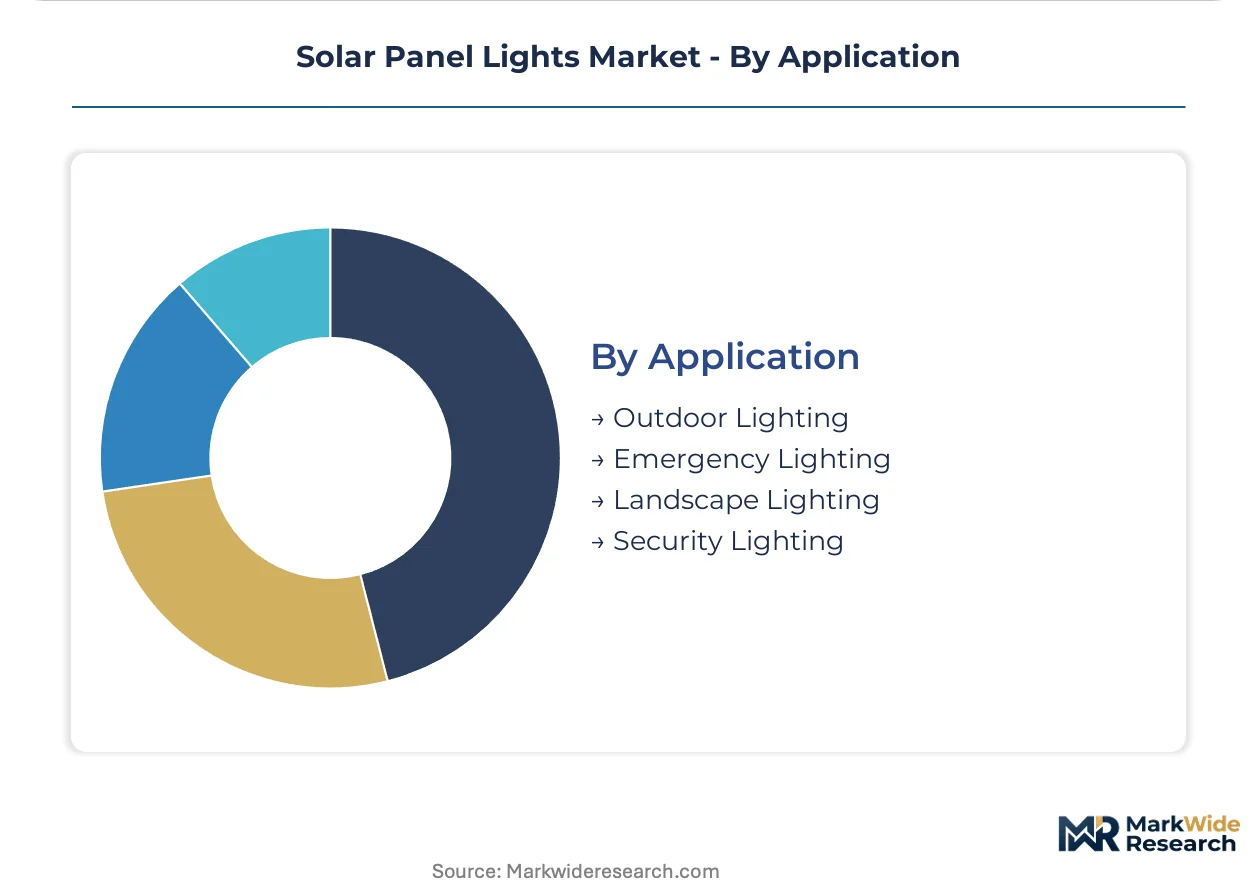
Application:
Use case dictates optical distribution patterns, ingress protection ratings, and control system complexity.
- Outdoor Lighting:Street, pathway, and area illumination with IP65+ weatherproofing and wide beam angles constitutes the foundational demand segment. Monocrystalline panel efficiency gains above 21% reduce mounting structure costs for equivalent lumen output.
- Security Lighting:Motion-activated flood fixtures with instant-on LED response and 500-2,000 lumen burst outputs protect perimeters against intrusion. Commercial and industrial buyers in Brazil and South Africa prioritize this category for off-grid facility protection.
- Emergency Lighting:Battery-backed portable and fixed units with manual activation or grid-failure automatic switchover serve disaster preparedness mandates. Japanese regulatory requirements under METI standards drive premium product development for seismic resilience.
- Landscape Lighting:Decorative accent fixtures with warm color temperatures and concealed panel integration enhance aesthetic outdoor environments. European residential consumers favor this segment for heritage garden illumination.
Outdoor lighting commands installed base; security lighting climbs fastest on commercial perimeter hardening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam and Thailand host over 70% of regional LED driver and battery pack assembly, exposing procurement timelines to monsoon logistics disruptions while anchoring Southeast Asian manufacturing gravity.
India
Maharashtra and Gujarat state electricity boards tender for solar street lighting under decade-long performance contracts with escrowed warranty deposits. BIS mandates product safety standards for photovoltaic luminaires procured through Saubhagya rural electrification schemes. Domestic assemblers in Pune and Ahmedabad consolidate vendor relationships around full-service maintenance agreements.
United States
FCC certification governs radio-frequency components in smart solar luminaires sold across municipal infrastructure programs. The IRA extends investment tax credit eligibility to standalone energy storage paired with solar lighting installations. California and Texas municipalities lead procurement volumes for autonomous highway and perimeter illumination arrays.
Germany
The EU Green Deal's F-Gas Regulation accelerates mercury lamp phase-outs across provincial road networks, eliminating incumbent CFL maintenance contracts. Industrial parks in Bavaria and North Rhine-Westphalia adopt LoRaWAN-connected luminaires for predictive maintenance workflows. German OEMs integrate maximum power point tracking controllers into consolidated printed circuit board assemblies.
Japan
METI regulatory requirements under seismic resilience standards drive premium product development for emergency lighting and grid-failure automatic switchover systems. Households in Tokyo and Osaka absorb premium all-in-one solar lanterns with integrated smartphone charging functionality. Kanto region electronics clusters specialize in monocrystalline panel efficiency optimization above 21%.
Australia
Outdoor recreation participation climbs across Queensland and New South Wales, absorbing premium-priced portable solar lantern units with USB power bank functionality. Mining operations in Western Australia deploy autonomous solar perimeter arrays where grid extension proves uneconomical. TGA-equivalent electrical safety certifications govern product entry into commercial channels.
Solar Panel Lights Market Competitive Landscape
Global majors compete with regional champions across battery chemistry integration and municipal procurement channel access. The vendor base stratifies between LED heritage conglomerates, equatorial-condition specialists, and scale-driven government tender competitors. Three archetypes dominate: technology licensors with semiconductor legacy, climate-adaptive engineering houses, and vertically integrated domestic assemblers. Competitive moves concentrate on long-term performance guarantee escrow structures and smart city connectivity module integration.
Among European lighting conglomerates, Signify Holding anchors premium architectural and street-lighting positioning across municipal segments. Sunna Design occupies the climate-specialist tier with integrated lithium battery management systems engineered for equatorial deployment. Greenshine New Energy exemplifies the scale-driven archetype, sustaining cost advantages in bulk government tenders for highway and perimeter illumination. These three represent divergent strategic paths: heritage brand leverage, environmental adaptation, and manufacturing scale.
| Leading Market Players |
|---|
| Signify Holding (Philips) |
| Sunna Design |
| Greenshine New Energy |
| Solar Electric Power Company (SEPCO) |
| Solar Street Lights USA |
| Jinhua Sunmaster Lighting |
| Fonroche Lighting America |
| Gama Sonic |
| Sokoyo Solar Lighting |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap assemblers across Vietnam and Thailand anchor regional supply capacity, compressing procurement timelines for municipal buyers while limiting pricing power for integrated luminaire OEMs without captive battery cell production.
Pricing Analysis
Input-cost pass-through from lithium carbonate volatility is compressing margin structures for non-integrated assemblers lacking captive chemical supply. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales bundling. Cost compression in economy-tier garden fixtures is intensifying because Southeast Asian trading houses liquidate nickel-metal hydride inventory. Government procurement under decade-long performance contracts shows lowest price sensitivity; residential retail channels exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with monocrystalline silicon wafer production concentrated in China, South Korea, and Japan. LED driver ICs and lithium iron phosphate cells draw from Chinese chemical processing and Taiwanese semiconductor foundries. Tariff exposure on battery-grade lithium salts creates procurement timeline risk. Distribution runs through municipal tender aggregators in India, government procurement portals in the EU, and outdoor recreation retail chains in Australia and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where the EU F-Gas Regulation's mercury lamp prohibitions are accelerating solid-state retrofit budgets across municipal infrastructure programs.
For Market Incumbents: Deepen backward integration into lithium iron phosphate cell supply to offset raw material volatility. Escrowed warranty deposits required by Maharashtra and Gujarat electricity boards favor domestic assemblers with balance sheet depth. Certification investment in BIS and IEC 62133 standards creates defensive moats against import-dependent trading houses.
For New Entrants and Emerging Players: Launch via direct-to-consumer channels targeting Australian and Japanese outdoor recreation buyers with premium all-in-one solar lantern units. Portable lighting with USB power bank functionality represents the most penetrable white-space segment. Municipal smart city tenders in Indonesia offer project-based entry points for connectivity-integrated luminaires.
For Investors and Strategic Acquirers: LED heritage conglomerates are the most active acquirer in this space, consolidating climate-adaptive engineering capabilities. Five-to-ten year viability hinges on battery chemistry transition completion and circular-economy compliance infrastructure. Monitor lithium carbonate price stabilization as inflection indicator for margin recovery in integrated assembly.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cells | Captive lithium iron phosphate supply insulates margin structures from carbonate volatility. |
| Smart City Connectivity Module Integration | LoRaWAN and NB-IoT enable recurring SaaS revenue from municipal maintenance contracts. |
| Circular Economy Certification Program | India's E-Waste Management Rules favor domestic assemblers with established take-back infrastructure. |
| Equatorial Climate Engineering Specialization | Battery management systems designed for subtropical conditions capture Southeast Asian procurement. |
| Long-term Performance Guarantee Escrow | Ten-year warranties with deposited reserves consolidate vendor relationships in Indian state tenders. |
Research Methodology
Direct dialogue with municipal procurement officers, lithium battery system engineers, LED driver IC procurement leads, and outdoor recreation retail category managers grounded qualitative findings. Secondary validation drew from BIS certification registries, EU F-Gas Regulation implementation reports, Indian state electricity board tender databases, and customs trade data for photovoltaic luminaire imports. Bottom-up unit economics triangulated against top-down addressable infrastructure spend estimates.
Segment-level outputs across product type, battery chemistry, end-user procurement modality, and regional regulatory cluster fed into the analytical framework. CAGRs were derived from installed base replacement cycles, rural electrification program budget trajectories, and solid-state lighting penetration curves. Forecast inputs incorporated monocrystalline efficiency improvement trajectories and lithium iron phosphate cost decline curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged lithium carbonate price volatility or accelerated EU mercury lamp phase-out timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
India Solar Tracker Market
Solar Power Systems
Commercial Solar Panel Market
Solar Power Systems
Solar Polysilicon Ingot Wafer Cell Module Market
Solar Power Systems
Israel Solar Energy Market
Solar Power Systems
Argentina Solar Energy Market
Solar Power Systems
France Solar Energy Market
Solar Power Systems
Asia-Pacific Solar Concentrator Market
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
Solar Photovoltaic (PV) Market
Solar Power Systems
Portable Solar Charger Market
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
On-Site Photovoltaic Solar Power for Data Centers Market
Solar Power Systems
Solar Cell (Photovoltaic) Module Market