
 Italy Big Data Analytics in Energy Market | 2026-2036
Italy Big Data Analytics in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Big Data Analytics in Energy Market Insights
The EU AI Act is hardening compliance thresholds for algorithmic energy trading and grid optimization platforms in Italy. Siemens AG leverages deep domain expertise in industrial automation to sustain competitive positioning in predictive maintenance solutions. Palantir Technologies Inc. anchors its presence through government and utility partnerships focused on data integration platforms. Enel SpA dominates the domestic landscape by controlling proprietary grid data streams that feed operational analytics engines.
Big Data Analytics in Energy encompasses the collection, processing, and statistical modeling of high-velocity sensor streams, SCADA telemetry, and consumer usage patterns to optimize generation, transmission, and consumption decisions. Machine learning pipelines typically process time-series data at sub-second intervals to forecast demand fluctuations and detect asset degradation before failure. Predictive Maintenance applications command the largest current revenue share as aging infrastructure across Italian utilities requires condition-based intervention schedules. Real-time Analytics is expanding fastest at the margin as distributed renewable generation from solar and wind assets creates intermittency management challenges. Cloud Computing infrastructure underpins both segments but faces data sovereignty constraints under Italian and European frameworks.
ARERA, Italy's energy regulator, shapes pricing transparency rules that compel utilities to invest in consumption forecasting platforms. The EU Green Deal and CSRD disclosure requirements are forcing energy firms to deploy carbon accounting analytics across their operational footprints. GSE, the national energy services manager, administers incentive schemes that reward grid digitalization investments. Stakeholders must monitor how forthcoming EU electricity market reforms recalibrate the value of demand-response data relative to traditional supply-side forecasting.
Market Dynamics
Italy's National Recovery and Resilience Plan (PNRR) mandates digital infrastructure upgrades for energy utilities, creating a structural pull for analytics platforms across transmission and distribution networks. This regulatory compulsion is reshaping procurement timelines and vendor selection criteria.
Growth Catalysts
- EU AI Act:Compliance thresholds for algorithmic energy trading and grid optimization platforms are hardening, forcing utilities to invest in auditable analytics pipelines.
- Industrial energy consumption density:Lombardy and Emilia-Romagna drive concentrated deployment of consumption forecasting and demand-response systems.
- Distributed renewable intermittency:Solar and wind asset proliferation creates real-time balancing challenges that only sub-second telemetry analytics can address.
Market Restraints
- Cloud data sovereignty constraints:Italian and European frameworks limit cross-border data flows, fragmenting platform architecture and raising compliance costs.
- SCADA system heterogeneity:Legacy telemetry infrastructure across regional utilities resists standardized integration, prolonging deployment cycles.
- Carbon accounting analytics mandate:CSRD disclosure requirements force parallel investments in emissions tracking, diverting capital from core grid optimization.
Strategic Opportunities
- GSE incentive schemes:The national energy services manager rewards grid digitalization investments, subsidizing analytics platform adoption for mid-sized utilities.
- Condition-based intervention:Aging infrastructure across Italian utilities creates white space for predictive maintenance solutions that compress outage durations.
- Edge-to-cloud convergence:Federated learning architectures enable localized model training on proprietary grid data without centralizing sensitive telemetry.
Industry Challenges
- SCADA-to-analytics integration:Time-series data pipelines must reconcile sub-second sensor streams with batch-processed enterprise systems, creating latency mismatches.
- ARERA pricing transparency enforcement:Consumption forecasting platforms face audit scrutiny that extends deployment validation timelines.
- Machine learning operations talent:Utilities compete with financial services and technology vendors for scarce MLOps engineers capable of productionizing grid models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Big Data Analytics in Energy Market |
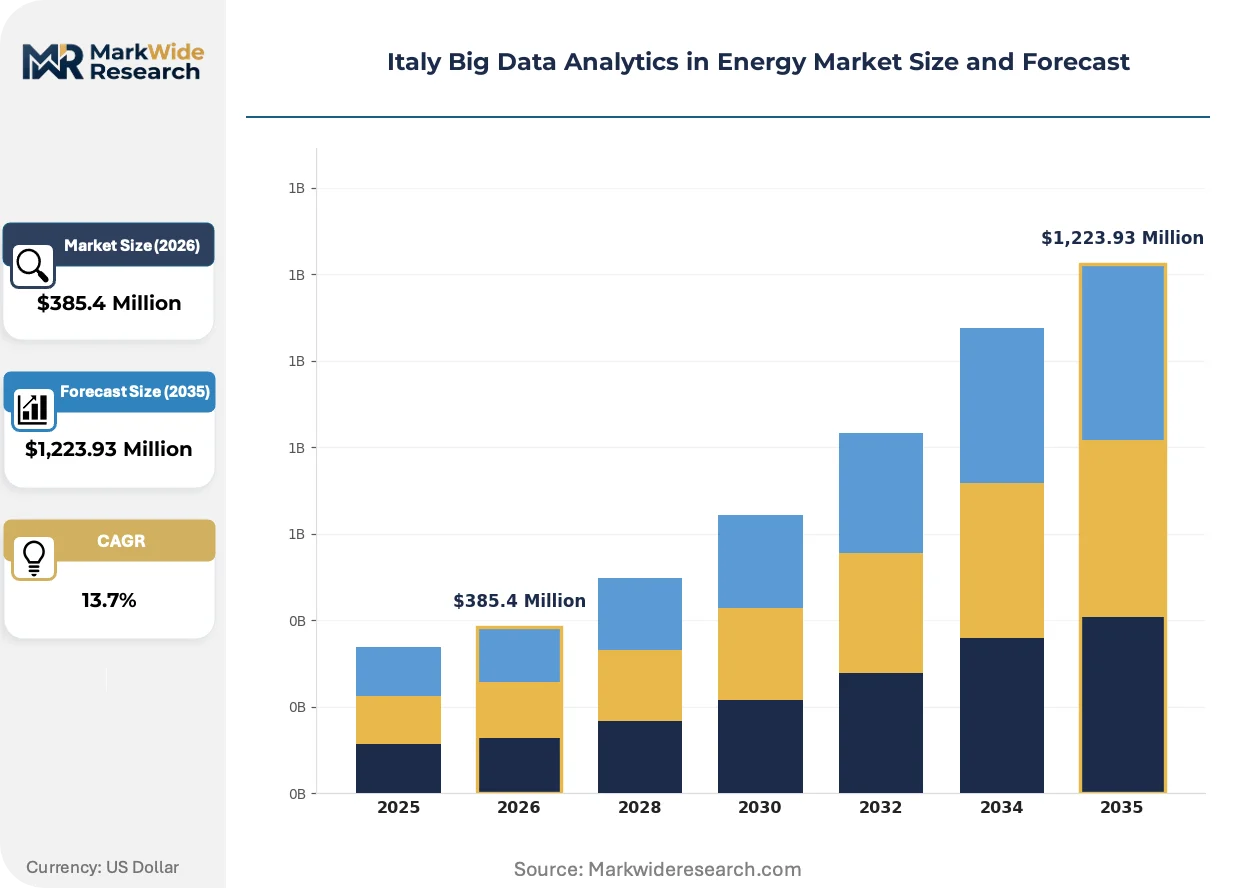
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,223.93 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Grid Management, Predictive Maintenance, Energy Consumption Forecasting, Asset Optimization End User: Utilities, Government Agencies, Renewable Energy Firms, Industrial Manufacturers Solution: Data Visualization, Predictive Analytics, Operational Analytics, Real-time Analytics Technology: Machine Learning, IoT Sensors, Cloud Computing, Data Warehousing |
| Companies Covered | IBM Corporation, Siemens AG, SAP SE, Microsoft Corporation, Accenture PLC, Infosys Limited, Intel Corporation, Palantir Technologies Inc., Enel SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Big Data Analytics in Energy Market Trends and Innovations
Machine learning operations are absorbing capital and engineering resources as utilities race to productionize models for demand forecasting and asset degradation detection. The competitive frontier has shifted from algorithm development to reliable deployment at scale.
Federated learning architectures are absorbing the constraints of Italian data sovereignty frameworks. Terna SPA and regional utilities are adopting edge-trained models that keep proprietary SCADA telemetry within national borders. This distributed approach is compressing the advantage of centralized cloud-native platforms while raising the bar for vendor interoperability standards.
The EU AI Act is hardening documentation requirements for algorithmic systems used in energy trading and grid optimization. Platform providers must now maintain model cards, risk registers, and human oversight protocols that extend sales cycles but create compliance moats against unqualified entrants. Italian utilities are prioritizing vendors with pre-certified governance frameworks.
Energy procurement teams are unbundling analytics services from hardware supply contracts. Large industrial consumers in Lombardy now source consumption forecasting software separately from metering infrastructure, forcing meter vendors to open APIs and accept third-party algorithm integration. This disintermediation is most visible among automotive and pharmaceutical manufacturers with dedicated energy management functions.
Italy Big Data Analytics in Energy Market Segmentation
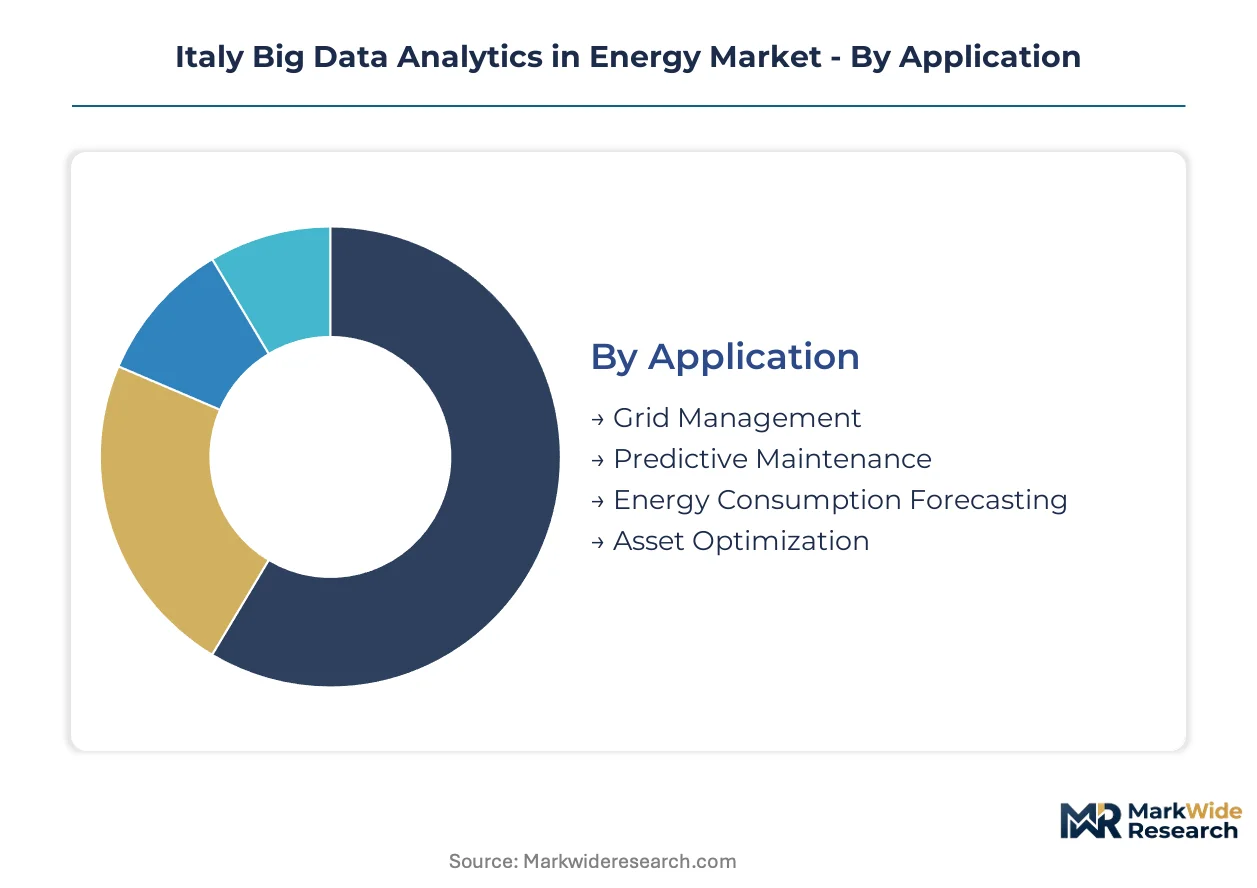
Segmentation reveals how procurement decisions fragment across regulatory mandates, infrastructure maturity, and data sovereignty requirements. Italian utilities prioritize segments with pre-certified compliance frameworks under EU AI Act and ARERA transparency rules.
Application:
Certification burdens vary sharply across applications, with algorithmic trading and grid optimization facing EU AI Act documentation requirements while asset monitoring falls under lighter industrial safety standards.
- Grid Management:Platforms process SCADA telemetry and distributed energy resource signals to balance load across transmission networks. Terna SPA deploys these systems across Italy's high-voltage backbone where renewable intermittency demands sub-second response protocols.
- Predictive Maintenance:Machine learning models analyze vibration, thermal, and electrical signature data to forecast transformer and cable failures before outage. Aging infrastructure across regional utilities in Campania and Sicily drives concentrated procurement of condition-based monitoring suites.
- Energy Consumption Forecasting:ARERA mandates transparent pricing methodologies that require auditable demand prediction pipelines.
- Asset Optimization:Generation and storage dispatch algorithms maximize revenue under fluctuating wholesale price signals.
Predictive Maintenance sits at the top of the volume ranking, with Grid Management climbing the fastest.
End User:
Cost tiers separate enterprise-grade deployments from subsidized mid-market adoption, with GSE incentives compressing price sensitivity for qualifying utilities.
- Utilities:Transmission and distribution operators command the largest analytics budgets, integrating multi-source telemetry across legacy SCADA and modern IoT endpoints. Enel SpA and Terna SPA anchor demand through proprietary data lake investments that resist third-party platform substitution.
- Industrial Manufacturers:Automotive and pharmaceutical clusters in Lombardy unbundle software procurement from metering hardware, sourcing standalone forecasting modules. Energy management functions at Fiat and Ferrari facilities mandate API-open architectures that accommodate algorithm swapping.
- Renewable Energy Firms:Solar and wind asset operators require intermittency forecasting to optimize grid connection bids.
- Government Agencies:GSE and regional administrations deploy analytics for incentive verification and carbon accounting disclosure.
Utilities capture the dominant spending share, with Industrial Manufacturers expanding most quickly.
Solution:
Application context determines solution selection, with operational control rooms prioritizing latency over statistical sophistication while planning functions favor predictive depth.
- Real-time Analytics:Stream processing engines ingest sub-second sensor feeds to trigger automated grid responses within milliseconds. Distributed solar proliferation across Apulia and Basilicata creates balancing emergencies that only immediate telemetry analytics can address.
- Predictive Analytics:Batch-processed models forecast demand curves and equipment degradation over days to months. ARERA audit requirements extend validation timelines for these deployments, favoring vendors with pre-documented risk registers.
- Operational Analytics:Dashboards consolidate KPIs for control room dispatchers and field maintenance crews.
- Data Visualization:Self-service interfaces enable non-technical stakeholders to explore consumption patterns and carbon footprints.
Real-time Analytics commands premium pricing, with Predictive Analytics gaining share fastest.
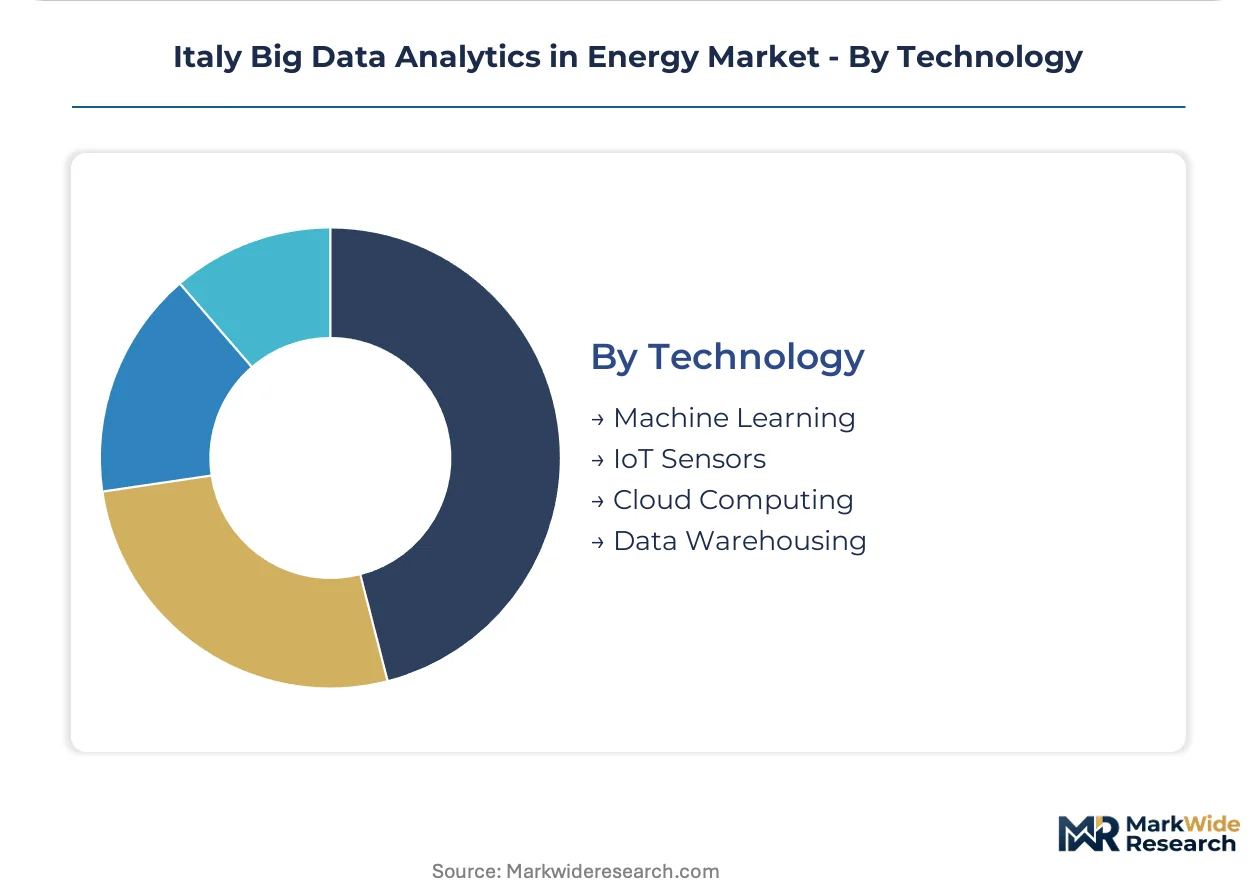
Technology:
Supply concentration clusters around cloud infrastructure providers and industrial automation specialists, with data sovereignty rules fragmenting platform architecture.
- Cloud Computing:Federated and edge-deployed architectures satisfy Italian data localization mandates while delivering scalable compute. European hyperscaler regions in Milan and Frankfurt compete for utility workloads against on-premise private cloud investments.
- Machine Learning:MLOps pipelines productionize forecasting and anomaly detection models for 24/7 grid operations. Talent scarcity for production-grade model deployment forces utilities into vendor-managed service arrangements.
- IoT Sensors:Smart meters and grid monitors generate the raw telemetry feeding upstream analytics layers.
- Data Warehousing:Time-series optimized storage reconciles high-velocity SCADA streams with historical enterprise records.
Cloud Computing underpins the broadest deployment base, with Machine Learning showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan's concentration of energy management talent and Turin's industrial automation expertise anchor Italy's analytics workforce. These clusters feed directly into utility procurement decisions across the peninsula.
Lombardy
Industrial energy density in Milan and Brescia drives concentrated demand for consumption forecasting and demand-response systems. ARERA pricing transparency mandates compel utilities here to maintain auditable prediction pipelines. Automotive and pharmaceutical manufacturers in the Milanese hinterland unbundle software procurement from metering hardware, sourcing standalone analytics modules.
Emilia-Romagna
Machine tool and packaging machinery clusters around Bologna and Modena generate high-resolution energy telemetry requirements. The region's manufacturing base funds dedicated energy management functions that specify API-open architectures. Industrial consumers here mandate algorithm-swapping capabilities in procurement tenders.
Piedmont
Turin's automotive heritage and industrial automation ecosystem sustain demand for predictive maintenance solutions. Aging grid infrastructure across the Alpine foothills creates procurement urgency for condition-based monitoring. Fiat and Ferrari facilities in the region exemplify the shift toward standalone software procurement.
Campania
Aging transmission assets across Naples and the surrounding provinces drive concentrated investment in transformer and cable monitoring systems. GSE incentive schemes subsidize grid digitalization for mid-sized utilities operating here. The region's infrastructure deficit creates white space for predictive maintenance vendors.
Sicily
Solar proliferation across the island generates intermittency management challenges that demand sub-second telemetry analytics. Distributed renewable assets create balancing emergencies requiring immediate grid response protocols. Regional utilities here prioritize real-time stream processing over batch-processed forecasting models.
Italy Big Data Analytics in Energy Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Italy's energy analytics landscape. The market exhibits moderate consolidation, with transmission operators and large industrial consumers favoring established vendors with pre-certified compliance frameworks. Three archetypes dominate: industrial automation specialists with deep SCADA integration expertise, cloud-native platform providers with federated learning capabilities, and utility-captive analytics divisions controlling proprietary data streams. Competitive rivalry centers on strategic partnerships with grid operators and portfolio diversification into edge computing architectures.
Within the industrial automation tier, Siemens AG exemplifies the archetype of deep domain expertise in predictive maintenance. Palantir Technologies Inc. occupies a position among government and utility partnership specialists focused on data integration platforms. Enel SpA anchors the utility-captive tier, representing the competitive advantage of proprietary grid data control. These three entities collectively illustrate how vendor selection in Italy increasingly prioritizes pre-certified governance frameworks under EU AI Act and ARERA transparency requirements.
| Leading Market Players |
|---|
| IBM Corporation |
| Siemens AG |
| SAP SE |
| Microsoft Corporation |
| Accenture PLC |
| Infosys Limited |
| Intel Corporation |
| Palantir Technologies Inc. |
| Enel SpA |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between EU AI Act-compliant analytics suites and legacy monitoring tools splits procurement budgets across Italian utilities. Premium vendors command sustained pricing power through pre-certified governance frameworks, while commodity sensor integration faces margin compression from standardized hardware sourcing.
Pricing Analysis
Bundled-vs-unbundled service splits reshape contract structures across Lombardy industrial zones. SaaS-tiered subscriptions dominate predictive maintenance deployments, with pricing differentiation driven by ARERA audit documentation depth and federated learning architecture sophistication. Cost compression intensifies in standalone metering hardware as automotive manufacturers mandate API-open procurement. Mid-sized utilities in Campania exhibit highest price sensitivity due to capital constraints, while Terna SPA anchors premium tier demand through proprietary data lake investments.
Supply Chain Analysis
Single-source vulnerability sits with German industrial automation specialists supplying SCADA integration layers. Hardware components draw from China, Taiwan, and South Korea for IoT sensors and edge computing modules. Cloud infrastructure rests on Milan and Frankfurt hyperscaler regions under data sovereignty constraints. Tariff exposure on semiconductor components creates procurement urgency for domestic warehousing. Distribution runs through systems integrators with ARERA certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's energy analytics market compounds steadily as PNRR-mandated digitalization creates structural demand pull through the analysis window.
For Market Incumbents: Deepen vertical integration into edge computing architectures to defend against cloud-native entrants exploiting federated learning standardization. Capture proprietary SCADA telemetry streams through long-term Terna SPA and Enel SpA partnership renewals. Prioritize MLOps talent retention as financial services competitors drain utility-sector engineering capacity. For New Entrants and Emerging Players: Capture white space in Campania and Sicily where aging infrastructure and solar proliferation outpace incumbent service coverage. Target predictive maintenance modules for regional utilities lacking in-house data science functions. Lead with GSE incentive scheme navigation as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where EU AI Act compliance costs exceed standalone vendor revenue bases. Frame long-term viability around utilities' irreversible shift from reactive maintenance to condition-based intervention protocols. Target acquisition archetypes with pre-certified risk registers and established ARERA audit relationships. Monitor GSE incentive allocation velocity as inflection signal for mid-market utility procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Deployment | Edge-trained models satisfy Italian data sovereignty while reducing cross-border telemetry transfer costs. |
| MLOps Platform Integration | Productionized grid models demand 24/7 reliability that vendor-managed pipelines increasingly guarantee. |
| SCADA System Modernization | Legacy telemetry heterogeneity across regional utilities prolongs deployment cycles without standardized APIs. |
| ARERA Compliance Certification | Pre-documented governance frameworks compress sales validation timelines under transparency enforcement. |
| Renewable Intermittency Forecasting | Sub-second analytics capabilities differentiate vendors in Apulia and Basilicata solar proliferation zones. |
Research Methodology
Multiple input streams — utility planning officers, IPP project developers, EPC contractors, and grid operators — were reconciled with secondary validation from ARERA regulatory filings, GSE incentive databases, Terna SPA infrastructure disclosures, and EU AI Act implementation guidance. Bottom-up segmentation modeling triangulated against top-down energy consumption density metrics across Lombardy and Emilia-Romagna industrial clusters.
Historical deployment trajectories cross-referenced against expert panel inputs shaped the analytical framework across the projection horizon. Modeled dimensions span application type, end-user archetype, solution architecture, and underlying technology stack. CAGRs derived from utility capital expenditure patterns and GSE incentive allocation velocities, with renewable intermittency forecasting penetration serving as primary expansion indicator.
Regulatory enforcement delays, SCADA integration bottlenecks, and MLOps talent scarcity are the dominant revision risks that could compress or extend forecast trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Europe Big Data Analytics in Energy Market
Energy Analytics and Software
Automated Power Generation Dispatch Software Market
Energy Analytics and Software
Oil and Gas Data Management Software Market
Energy Analytics and Software
Netherlands Big Data Analytics in Energy Market
Energy Analytics and Software
France Big Data Analytics in Energy Market
Energy Analytics and Software
Smart Grid Software Market
Energy Analytics and Software
Utility Analytics and Energy Analytics Market
Energy Analytics and Software
Big Data Analytics in Power Sector Market
Energy Analytics and Software
Smart Grid Data Analytics Market
Energy Analytics and Software
Global Geophysical Services and Equipment Market
Energy Analytics and Software
Solar Analyzer Market
Energy Analytics and Software
Power System Analysis Software Market
Energy Analytics and Software
Carbon and Energy Software Market
Energy Analytics and Software
Power Monitoring and Control Software Market
Energy Analytics and Software
Oil Condition Monitoring Market
Energy Analytics and Software
Big Data Analytics in Energy Market