
 Global Workflow Orchestration Market | 2026-2036
Global Workflow Orchestration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Workflow Orchestration Market Foresight
Asset-light subscription and consumption-based financing is narrowing the competitive barrier for mid-market enterprises to adopt enterprise-grade orchestration platforms. IBM Corporation leverages its hybrid cloud footprint to sustain mainframe-to-cloud workflow bridges for regulated industries. ServiceNow anchors its position through IT service management workflows that extend into cross-functional business process automation. Amazon Web Services competes on serverless compute primitives that lower infrastructure overhead for event-driven orchestration at scale.
Workflow orchestration denotes the algorithmic coordination of multi-step business processes across distributed systems, typically employing event-driven triggers, API choreography, and state-machine logic to enforce service-level agreements and failure recovery protocols. Cloud-native deployment configurations now dominate new implementations, though hybrid architectures retain substantial share among enterprises with data residency constraints in BFSI and government sectors. Process integration solutions command the largest solution-type revenue pool, while event-driven architecture segments exhibit the fastest expansion as real-time data pipelines displace batch-oriented workflows in telecommunications and e-commerce operations.
The EU AI Act and GDPR impose algorithmic transparency and data-processing accountability requirements that directly shape orchestration platform design, particularly for automated decision workflows in European financial services. In the United States, NIST cybersecurity frameworks and SEC disclosure rules for material operational incidents create compliance-driven demand for auditable, resilient orchestration stacks. Stakeholders must evaluate whether their current orchestration investments can accommodate emerging cross-border data governance requirements without fragmenting operational architecture.
Market Dynamics
Event-driven architecture is compressing batch-processing timelines across financial services and telecommunications, forcing infrastructure providers to reconfigure orchestration engines for sub-second latency requirements.
Growth Catalysts
- EU AI Act compliance mandates:Financial institutions in Frankfurt and Paris deploy auditable automation pipelines with embedded governance controls to satisfy algorithmic transparency requirements.
- Telecommunications edge computing expansion:5G network operators in South Korea and Japan integrate real-time workflow orchestration to manage distributed radio access network resources.
- Cloud-native platform maturation:Container orchestration and Kubernetes-native tooling lower deployment friction for mid-market enterprises migrating from legacy middleware.
Market Restraints
- Specialized talent scarcity:Shortages of Site Reliability Engineers with event-driven architecture expertise constrain implementation velocity in European banking hubs.
- Hybrid integration complexity:Enterprises with mainframe-dependent core systems face extended migration timelines when bridging COBOL workflows to cloud-native orchestration layers.
- Cross-border data governance fragmentation:Divergent interpretations of GDPR Article 44 transfer mechanisms create architectural uncertainty for US-based platforms serving EU financial clients.
Strategic Opportunities
- Brazilian BFSI modernization wave:ANVISA and BIS-aligned institutions seek compliant orchestration stacks for pharmaceutical supply chain and payment processing automation.
- Healthcare interoperability mandates:HIPAA-adjacent requirements for audit trails in clinical decision support create demand for governed workflow engines in US hospital networks.
- AI-agent orchestration convergence:Large language model inference pipelines combine with traditional API choreography to enable autonomous multi-step business processes.
Industry Challenges
- Observability toolchain fragmentation:Distributed tracing standards remain inconsistent across OpenTelemetry, Jaeger, and vendor-proprietary implementations, complicating root-cause analysis.
- State management at scale:Workflow engines handling millions of concurrent executions require sophisticated saga-pattern implementations to maintain consistency across microservices boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Workflow Orchestration Market |
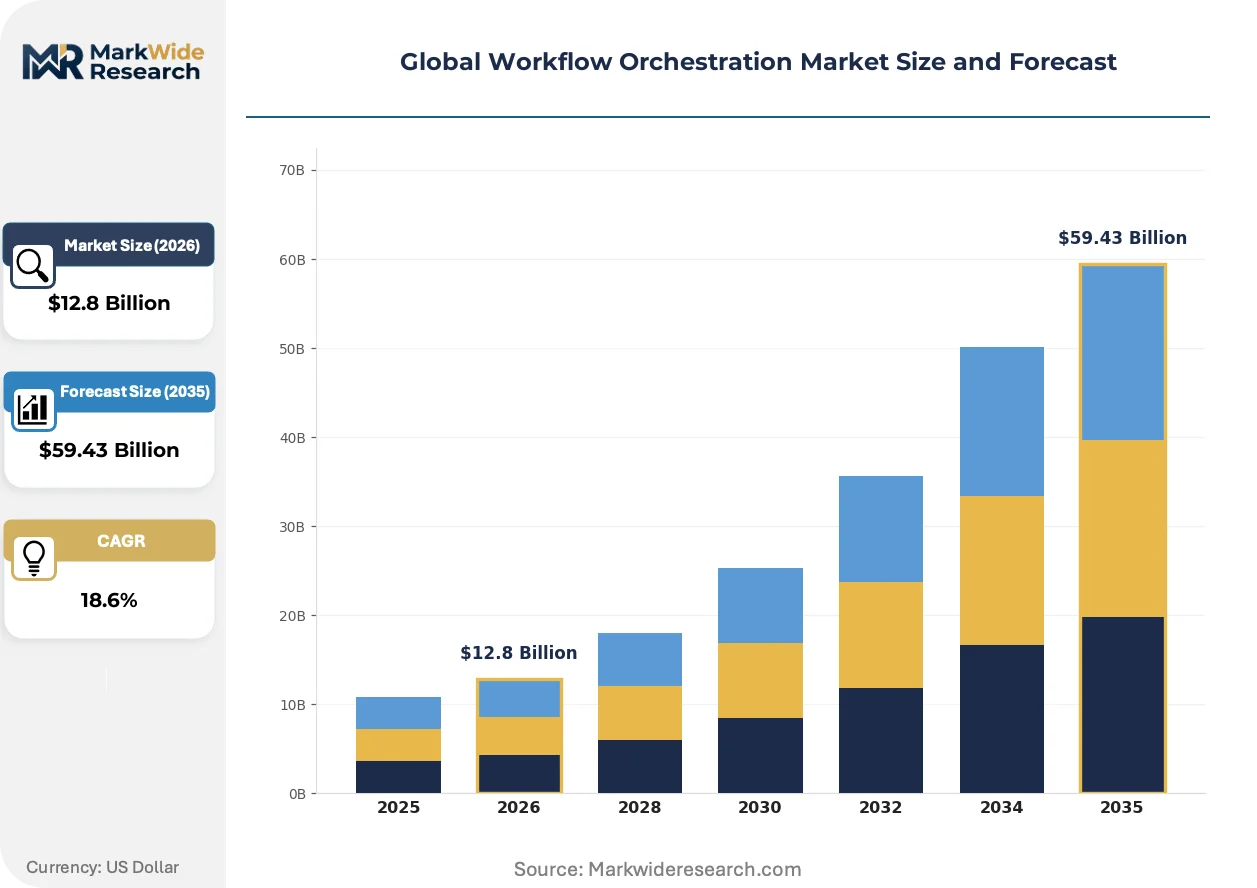
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $59.43 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Native, Hybrid, Edge Computing Solution Type: Automation Software, Process Integration, Data Orchestration, Event-Driven Architecture, API Management Application: IT Operations, Business Process Automation, Data Pipeline Management, Customer Experience Management, Supply Chain Coordination End User Industry: BFSI, Telecommunications, E-Commerce, Manufacturing, Government Agencies |
| Companies Covered | IBM Corporation, Oracle Corporation, Microsoft Corporation, SAP SE, ServiceNow, Amazon Web Services, BMC Software, Cisco Systems, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Workflow Orchestration Market Shifts & Advancements
Workflow orchestration is undergoing architectural compression as real-time requirements displace batch-oriented designs, with governance and observability capabilities becoming non-negotiable procurement criteria.
Serverless function orchestration is digitizing infrastructure provisioning for event-driven workloads. Capital markets firms in London and Singapore adopt AWS Step Functions and Azure Durable Functions to eliminate idle compute overhead. This shift is digitizing cost structures that previously required dedicated orchestration clusters.
CSRD sustainability reporting mandates in the European Union require automated data lineage and carbon footprint tracking across supply chain workflows. Manufacturing enterprises in Germany and the Netherlands embed emissions calculation nodes directly into production orchestration pipelines. Automotive suppliers face the steepest compliance burden as they trace tier-n component provenance.
Buyer procurement criteria now prioritize composable architecture over monolithic platform suites. Fortune 500 technology sourcing teams in the United States evaluate orchestration vendors on API interoperability and exit cost rather than feature breadth. This behavioral shift favors best-of-breed tooling strategies over single-vendor consolidation in financial services and retail verticals.
Global Workflow Orchestration Market Segmentation
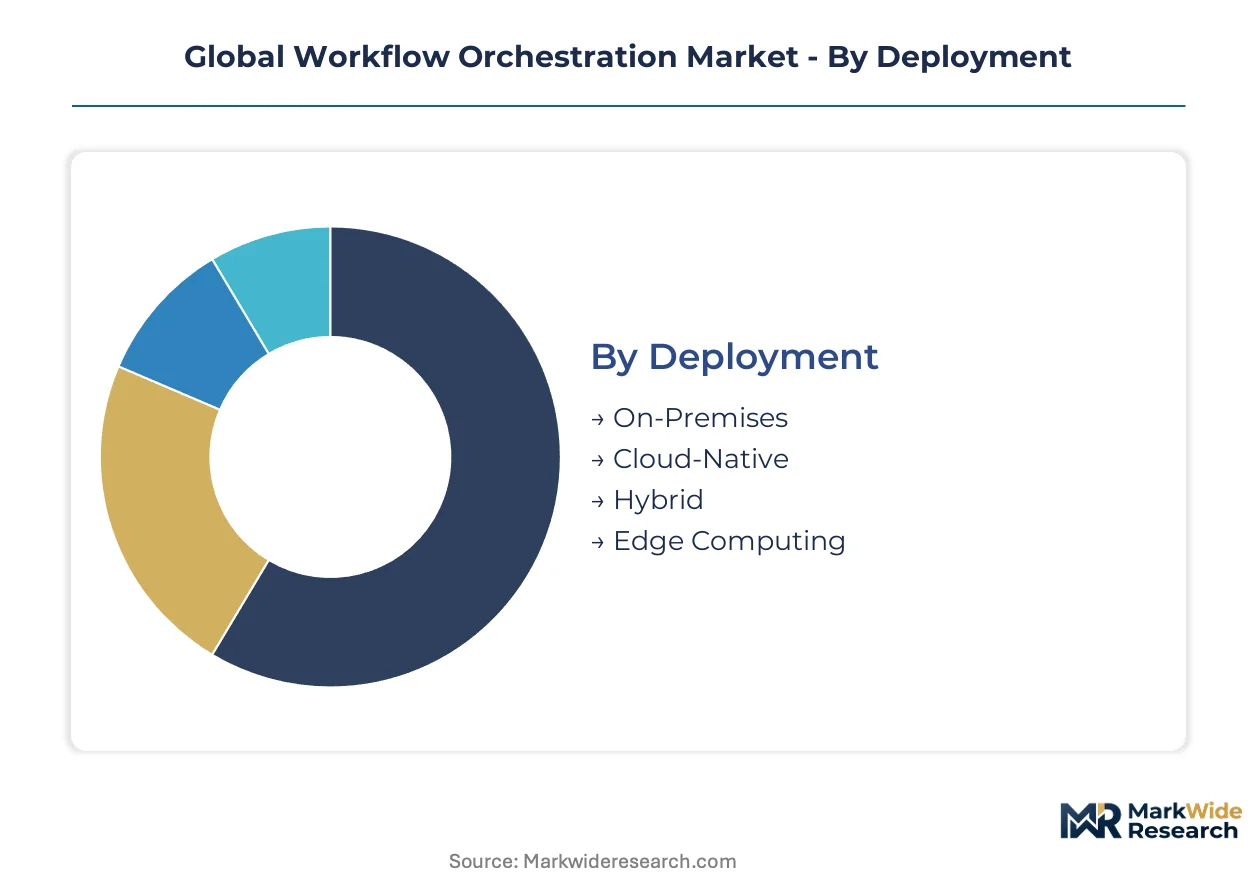
Workflow orchestration platforms serve divergent operational requirements across latency-sensitive edge deployments, compliance-heavy on-premises installations, and elastic cloud-native environments. Segmentation reveals how infrastructure choices, solution architectures, and industry-specific governance demands fragment procurement patterns across enterprise buyers.
Deployment:
Use-case spectrum spans high-frequency trading floors requiring microsecond determinism to distributed retail networks demanding elastic scale.
- On-Premises:Dedicated hardware installations within enterprise data centers enforce data residency for Frankfurt banking consortiums navigating GDPR Article 44 transfer restrictions. Frankfurt and Paris financial institutions favor these configurations for algorithmic audit trails mandated by the EU AI Act.
- Cloud-Native:Containerized orchestration layers leverage Kubernetes primitives for auto-scaling event-driven workloads. Singapore capital markets firms and Seoul telecommunications operators deploy these for serverless function chains eliminating idle compute overhead.
- Hybrid:Split-state orchestration bridges mainframe COBOL workflows to cloud-native microservices without full migration. German automotive suppliers and US federal agencies adopt these for phased legacy modernization preserving operational continuity.
- Edge Computing:Distributed orchestration nodes execute workflows proximate to 5G radio access networks and industrial IoT sensors. South Korean network operators and Japanese manufacturing plants integrate these for sub-50ms latency in predictive maintenance pipelines.
Established volume favors On-Premises; emerging adoption favors Edge Computing.
Solution Type:
Commercial significance concentrates in integration middleware and real-time event processing where differentiation determines architectural lock-in.
- Process Integration:Middleware platforms synchronize heterogeneous enterprise applications through API choreography and message queuing. BFSI institutions in London and Zurich deploy these for core banking system interoperability, though implementation timelines extend when bridging decades-old mainframe protocols.
- Event-Driven Architecture:Asynchronous workflow engines triggered by streaming data events enable real-time responsiveness. Telecommunications operators in Tokyo and e-commerce platforms in Seattle adopt these as batch-processing timelines compress toward sub-second requirements.
- Automation Software:Low-code workflow designers with visual process modeling accelerate citizen-developer adoption. Mid-market enterprises in Brazil and India favor these for rapid deployment without specialized Site Reliability Engineering talent.
- Data Orchestration:Pipeline management tools govern data lineage, quality validation, and cross-system synchronization. German automotive suppliers embed these for CSRD-mandated carbon footprint tracking across tier-n component provenance.
- API Management:Gateway and lifecycle tooling secures, monitors, and monetizes programmatic interfaces. US healthcare networks leverage these for HIPAA-compliant clinical data exchange with external research partners.
Process Integration commands current procurement budgets; Event-Driven Architecture climbs the fastest as real-time requirements displace batch orientation.
Application:
Functional deployment patterns reflect organizational maturity, with IT-centric automation preceding cross-functional business process expansion.
- IT Operations:Infrastructure provisioning, incident response, and change management automation reduce mean-time-to-resolution. ServiceNow-anchored deployments dominate Fortune 500 technology sourcing teams in the United States prioritizing composable architecture over monolithic suites.
- Business Process Automation:Cross-functional workflow digitization spans procurement, HR onboarding, and financial close processes. European manufacturing enterprises integrate CSRD emissions calculation nodes directly into production orchestration pipelines.
- Data Pipeline Management:ETL modernization and real-time stream processing governance ensures data quality across analytics workloads. Singapore capital markets firms adopt these for regulatory reporting automation.
- Customer Experience Management:Omnichannel journey orchestration unifies interaction histories across web, mobile, and contact center touchpoints. E-commerce platforms in Seattle and Berlin deploy these for personalized recommendation engines.
- Supply Chain Coordination:Multi-tier supplier synchronization and demand forecasting automation reduces inventory carrying costs. Brazilian pharmaceutical distributors seek ANVISA-aligned orchestration stacks for compliant cold-chain monitoring.
IT Operations retains deployment density; Business Process Automation gains share fastest as workflow scope expands beyond technical teams.
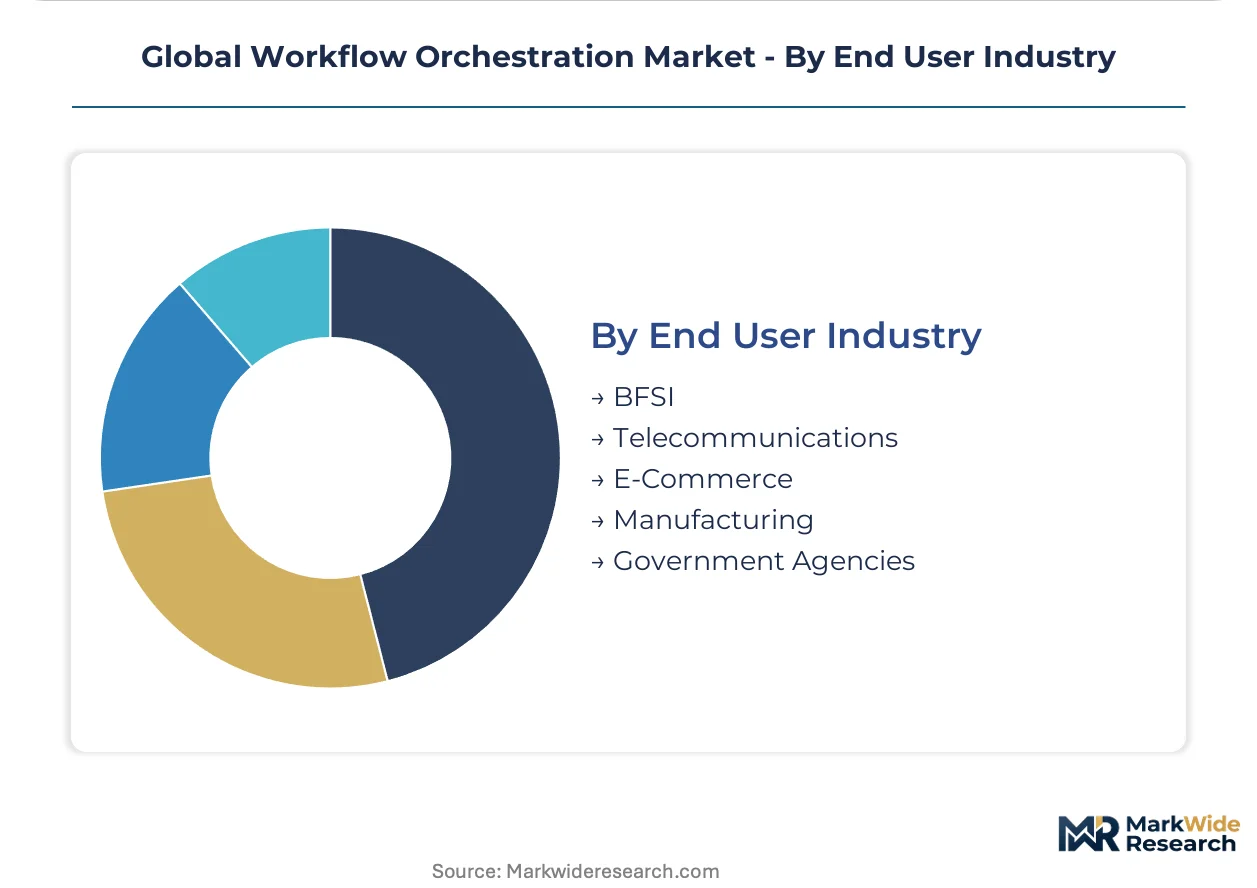
End User Industry:
Industry-specific regulatory density and operational complexity determine solution customization requirements and pricing tolerance.
- BFSI:Trading workflow automation, compliance reporting, and anti-money laundering transaction monitoring demand auditable governance controls. Frankfurt, London, and Singapore financial hubs drive premium procurement for algorithmic transparency features.
- Telecommunications:5G network slice orchestration and customer provisioning automation require sub-second latency guarantees. South Korean and Japanese operators lead edge-computing-integrated deployments.
- E-Commerce:Order fulfillment orchestration, payment processing, and returns management scale elastically with demand spikes. Seattle and Berlin platforms favor serverless configurations for seasonal capacity variation.
- Manufacturing:Production scheduling, quality control integration, and predictive maintenance workflows synchronize shop-floor systems with enterprise ERP. German and Dutch automotive suppliers face steepest CSRD compliance burden embedding sustainability tracking.
- Government Agencies:Citizen service delivery, inter-agency data sharing, and emergency response coordination require FedRAMP or equivalent security certifications. US federal and state governments prioritize hybrid architectures preserving classified data on-premises.
BFSI sustains premium pricing; Telecommunications represents the steepest expansion trajectory as 5G network investment accelerates globally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net services exports from the United States and Germany dominate cross-border orchestration platform licensing, while South Korea and Japan import edge-computing orchestration stacks for telecommunications infrastructure. Trade balances reflect intellectual property concentration in cloud-native tooling versus hardware-integrated deployment demand in Asia-Pacific markets.
United States
Hyperscale cloud providers and enterprise software vendors drive infrastructure investment across banking and telecommunications verticals. SEC disclosure rules for material operational incidents create compliance-driven demand for auditable orchestration stacks. New York and San Francisco financial technology clusters deploy serverless function chains for regulatory reporting automation.
Germany
Automotive suppliers and manufacturing enterprises embed CSRD-mandated carbon footprint tracking into production orchestration pipelines. The EU AI Act and GDPR impose algorithmic transparency requirements shaping platform design for automated decision workflows. Frankfurt banking consortiums favor on-premises configurations navigating GDPR Article 44 transfer restrictions.
United Kingdom
Capital markets firms in London adopt event-driven architecture for real-time trading workflow automation. The Financial Conduct Authority's operational resilience requirements pressure institutions toward resilient orchestration infrastructure. The City of London and Canary Wharf financial districts represent concentrated procurement for governance-embedded automation platforms.
Japan
Telecommunications operators integrate real-time workflow orchestration to manage distributed 5G radio access network resources. METI industrial policy supports edge-computing infrastructure deployment for manufacturing automation. Tokyo and Osaka industrial corridors lead predictive maintenance pipeline implementations with sub-50ms latency requirements.
South Korea
Network operators deploy edge-computing-integrated orchestration for 5G network slice management and customer provisioning automation. National digital infrastructure programs accelerate cloud-native platform adoption across mid-market enterprises. Seoul metropolitan area technology clusters concentrate demand for Kubernetes-native tooling and serverless configurations.
Global Workflow Orchestration Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in API management and event-streaming infrastructure. The vendor landscape organizes around three strategic archetypes: legacy enterprise software vendors with hybrid cloud footprints, hyperscale cloud providers with serverless-native offerings, and pure-play automation platforms with IT service management roots. Competitive moves concentrate on M&A for event-streaming capabilities and strategic partnerships bridging mainframe-to-cloud integration gaps.
Within the legacy platform tier, IBM Corporation and Oracle Corporation exemplify vendors sustaining mainframe-to-cloud workflow bridges for regulated industries. ServiceNow occupies a position anchoring IT service management workflows that extend into cross-functional business process automation. These three represent distinct strategic postures: hybrid infrastructure preservation, database-centric integration, and workflow-native platform expansion.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| Microsoft Corporation |
| SAP SE |
| ServiceNow |
| Amazon Web Services |
| BMC Software |
| Cisco Systems |
| Others |
Supply & Pricing Matrix
GDPR Article 44 transfer mechanism uncertainty compresses pricing tier spreads while fragmenting supply chain architecture for US-based platforms serving EU financial clients. Frankfurt banking consortiums and Paris financial institutions demand on-premises configurations that carry 40-60% deployment cost premiums over cloud-native alternatives, forcing vendors to maintain parallel infrastructure stacks.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in workflow orchestration procurement. Premium tiers bundle embedded governance controls for EU AI Act compliance and dedicated Site Reliability Engineering support, while economy tiers offer stripped-down automation software for mid-market Brazilian and Indian enterprises. Price differentiation centers on certification grade—FedRAMP-authorized deployments command substantial premiums—and customization level for mainframe-to-cloud bridge implementations. Pricing pressure stems from hyperscale cloud providers commoditizing serverless compute primitives, compressing margins for standalone orchestration vendors. Mid-market enterprises exhibit highest price sensitivity, deferring procurement until consumption-based financing narrows competitive barriers.
Supply Chain Analysis
Export-control regimes limiting semiconductor and cloud infrastructure flows constrain supply chain flexibility for orchestration platform providers. Software development concentrates in the United States, Germany, and India, with Indian engineering centers feeding cost-optimized automation software modules. Raw material dependencies center on specialized silicon for edge-computing nodes, enterprise-grade storage arrays for on-premises installations, and submarine cable capacity for cross-border data synchronization. Single-source vulnerability runs through Taiwan-manufactured advanced semiconductors essential for sub-50ms latency edge deployments. Distribution runs through direct enterprise sales forces for BFSI and telecommunications verticals, supplemented by systems integrator channels for mid-market manufacturing and government segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The workflow orchestration market sits in early-cycle recovery as 5G capital expenditure waves and EU regulatory compliance deadlines compress replacement timelines for legacy middleware. Cloud-native platform maturation and event-driven architecture adoption create cyclical uplift across telecommunications and financial services verticals.
For Market Incumbents: Build switching-cost moats through deep integration with mainframe COBOL workflows and embedded CSRD emissions-tracking nodes for German automotive suppliers. Incumbents should consolidate event-streaming capabilities through targeted capability acquisitions, while expanding Kubernetes-native tooling partnerships to neutralize hyperscale cloud provider serverless offerings. The priority defensive move centers on certifying hybrid architectures for FedRAMP and EU AI Act compliance ahead of mid-market competitors.
For New Entrants and Emerging Players: Brazilian BFSI modernization represents the most penetrable white-space target, with ANVISA-aligned pharmaceutical supply chain automation and BIS-compliant payment processing creating urgent unmet demand. Seoul and Singapore mid-market enterprises offer secondary entry points through consumption-based financing models that bypass incumbent direct sales dominance. New entrants should pursue channel partnerships with regional systems integrators possessing existing mainframe integration expertise rather than building captive sales forces.
For Investors and Strategic Acquirers: EU AI Act implementation deadlines reshape the acquisition landscape toward vendors with pre-built algorithmic audit trail capabilities and GDPR Article 44-compliant data residency architectures. Long-term viability favors platforms demonstrating event-driven architecture revenue mix expansion and healthcare interoperability certification progress. The signal to watch is Fortune 500 procurement team shifts toward composable architecture evaluations over monolithic platform suites, indicating preference for best-of-breed tooling strategies that favor specialist acquisitions.
| Strategic Initiative | Industry Significance |
|---|---|
| Event-Streaming Capability Acquisition | Fortifies real-time responsiveness for telecommunications 5G network slice orchestration demands. |
| EU AI Act Compliance Certification | Unlocks Frankfurt and Paris financial institution procurement budgets for algorithmic transparency. |
| Mainframe Integration Partnership | Bridges COBOL workflows to cloud-native layers for German automotive supplier modernization. |
| Edge Computing Node Deployment | Captures South Korean and Japanese telecommunications sub-50ms latency requirements. |
| CSRD Sustainability Tracking Integration | Embeds carbon footprint calculation into German and Dutch automotive production pipelines. |
Research Methodology
A standing panel of platform engineering directors, IT procurement officers at Fortune 500 enterprises, Site Reliability Engineering leads, and channel partner technical architects provided ongoing calibration for demand assumptions. Primary interviews combined with secondary validation against SEC filings from hyperscale cloud providers, hyperscaler capex disclosures, Kubernetes ecosystem contribution metrics, and EU regulatory implementation guidance documents. Bottom-up sizing triangulated against top-down addressable market estimates across deployment models and solution types.
Scenario-bracketing framed analytical approach across the analysis window, modeling demand trajectories under varying 5G deployment paces and EU AI Act enforcement intensity. Segmentation dimensions spanned deployment configuration, solution architecture, end-user industry vertical, and regional regulatory cluster complexity. CAGRs derived from fitted growth curves anchored to observed cloud-native platform maturation rates and historical middleware replacement cycles. Industry-specific inputs included telecommunications capital expenditure plans and BFSI compliance spending surveys.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by hyperscale cloud providers or accelerated EU regulatory enforcement would shift outcomes. Forecasts reflect documented assumptions about Site Reliability Engineering talent availability and mainframe modernization timelines. Material shifts in cross-border data governance interpretations or 5G network investment commitments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Poland ICT Market
Digital Solutions
Disaster Recovery As a Service (Draas) Market
Digital Solutions
Global E-Passport and E-Visa Market
Digital Solutions
North America 3D Rendering Services Market
Digital Solutions
India Digital Twin Market
Digital Solutions
Business Information Market
Digital Solutions
Global Digital Workplace Software Market
Digital Solutions
Global Insight As a Service Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
United States ICT Market
Digital Solutions
US Digital Twin Market
Digital Solutions
Product As a Service Market
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
Public Relations (PR) Tools Market
Digital Solutions
Media Asset Management (MAM) Solutions Market