
 Global Process Orchestration Market | 2026-2036
Global Process Orchestration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Process Orchestration Market Foresight
Mid-market enterprises are rotating toward cloud-native orchestration platforms as their primary buyer archetype, displacing earlier dominance by large enterprises with on-premises legacy investments. SAP SE leverages its ERP installed base to embed process orchestration into core financial and supply chain workflows. UiPath anchors its position through robotic process automation integration that extends into full orchestration capabilities. Microsoft Corporation competes by bundling orchestration tools within its broader cloud productivity ecosystem.
Process orchestration denotes the automated coordination of multiple business processes, applications, and human tasks through centralized workflow engines that enforce business rules, data transformations, and event-driven triggers across distributed systems. The technology integrates API gateways, message brokers, and low-code design surfaces to enable real-time synchronization between enterprise software assets. Cloud-based deployment is capturing the fastest expansion as organizations prioritize elastic scalability and reduced infrastructure overhead over fixed-capacity on-premises installations. Workflow automation solutions command the deepest margin pools where vendors bundle intelligent document processing and decision management capabilities.
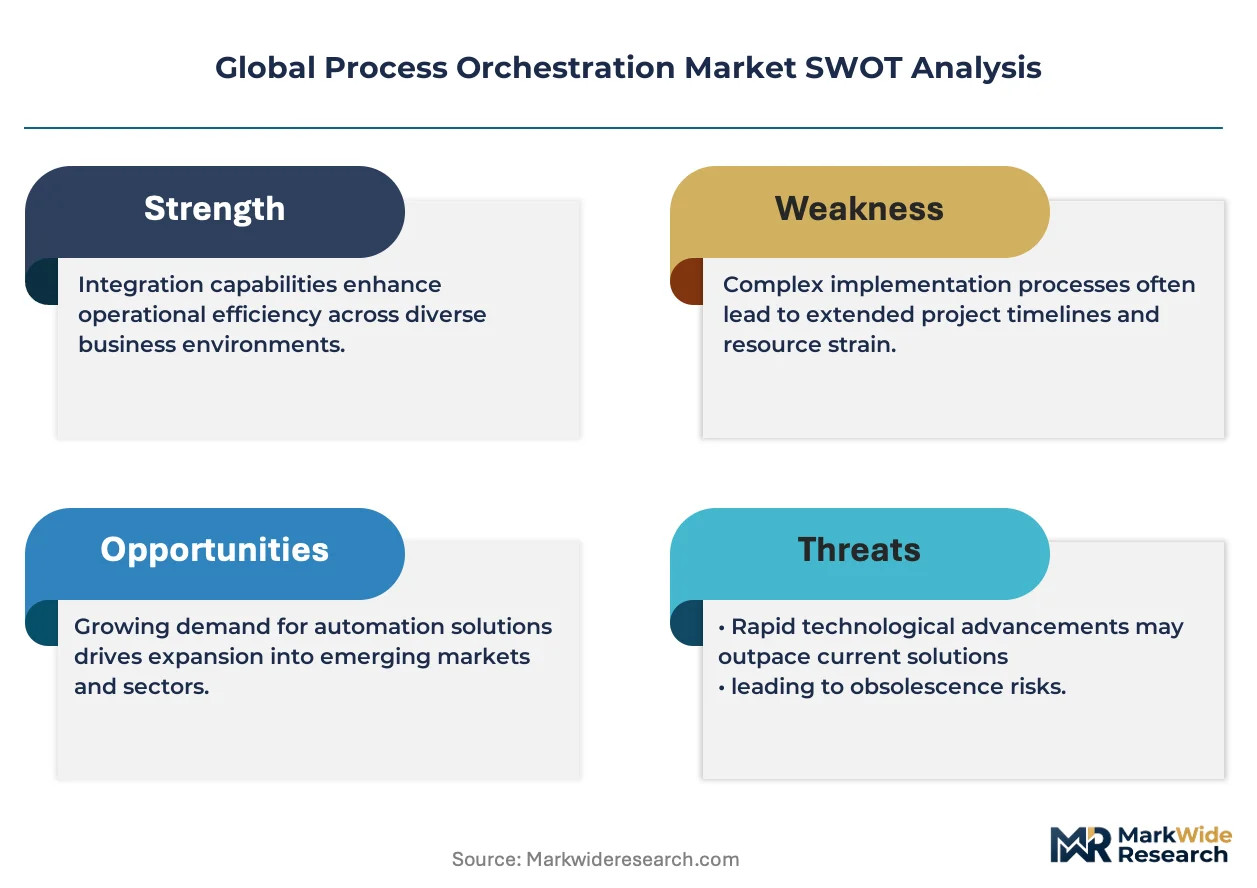
The EU AI Act and GDPR impose strict auditability and data lineage requirements that directly shape orchestration platform architecture, particularly for customer journey management applications in European banking. The US SEC and HIPAA frameworks similarly mandate traceable process records, driving demand for compliance-oriented orchestration in financial services and healthcare sectors. Stakeholders must evaluate whether their current orchestration investments can adapt to emerging algorithmic accountability standards without wholesale platform replacement.
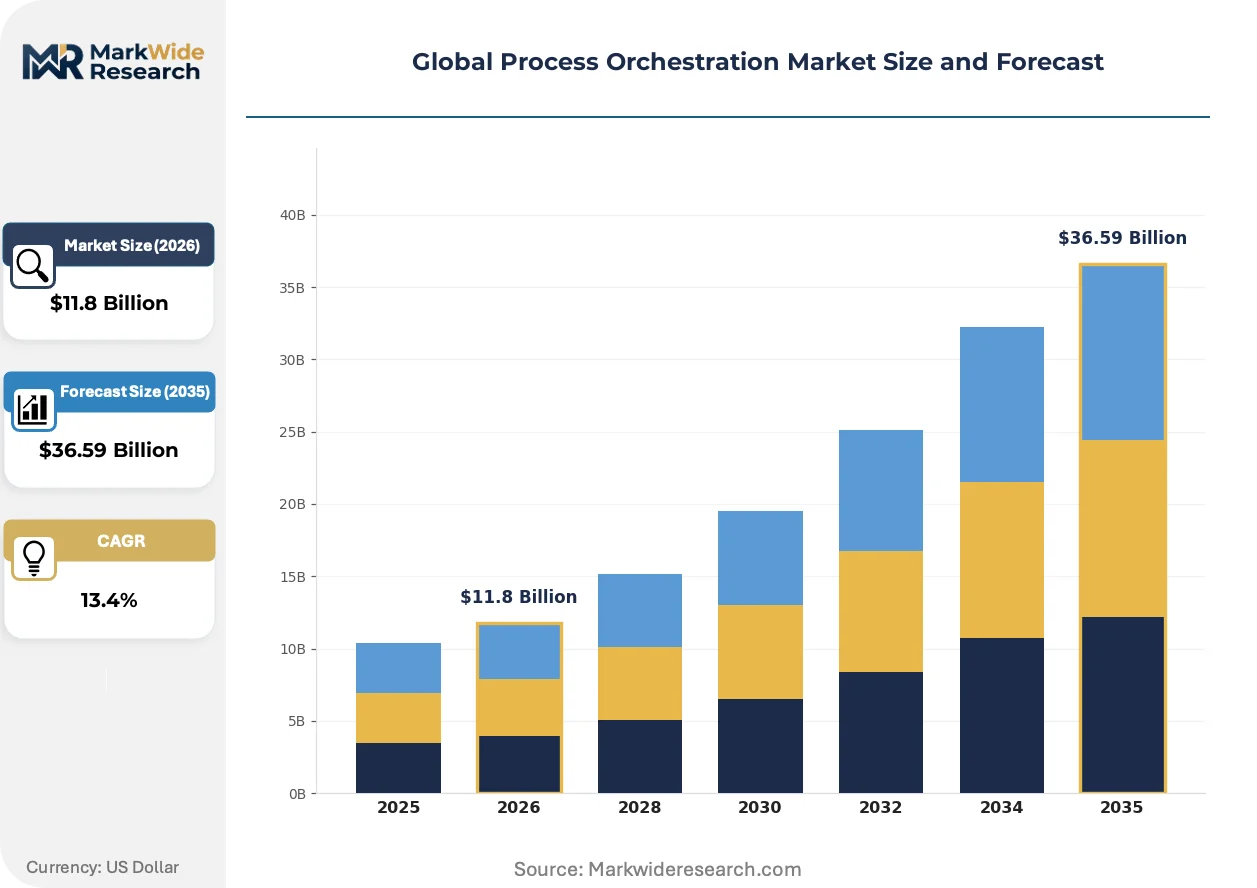
Market Dynamics
Mid-market enterprises are rotating toward cloud-native orchestration platforms as their primary buyer archetype, displacing earlier dominance by large enterprises with on-premises legacy investments. This structural shift compresses sales cycles while expanding addressable market volume.
Growth Catalysts
- EU AI Act:Auditable workflow automation mandates in European banking accelerate demand for compliance-oriented orchestration platforms with embedded data lineage capabilities.
- Industrial conglomerates:German manufacturing and supply chain operations are deploying end-to-end process orchestration to unify legacy core systems with digital channels.
- Cloud-native architectures:Elastic scalability requirements are pulling mid-market buyers away from fixed-capacity on-premises installations toward subscription-based deployment models.
Market Restraints
- Legacy integration costs:On-premises ERP systems require substantial middleware investment to connect with modern API-driven orchestration layers.
- Talent concentration:Skilled workflow architects and low-code platform specialists cluster in Western Europe and North American technology hubs.
- Data residency requirements:GDPR and HIPAA frameworks impose geographic constraints on cloud infrastructure placement, limiting vendor flexibility.
Strategic Opportunities
- Healthcare digitization:HIPAA-mandated traceable process records in US hospitals and insurance networks create demand for compliance-first orchestration suites.
- Intelligent document processing:Workflow automation solutions bundling IDP and decision management capabilities command premium positioning in financial services procurement.
- API gateway convergence:Message brokers and low-code design surfaces merging with orchestration engines open new architectural purchasing decisions.
Industry Challenges
- Skill scarcity:Shortage of professionals capable of bridging business process design with distributed systems engineering constrains implementation velocity.
- Multi-cloud complexity:Enterprises operating across AWS, Azure, and GCP environments face integration friction when standardizing orchestration governance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Process Orchestration Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $36.59 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud-based, Hybrid Cloud, Edge, Multi-cloud Solution Offering: Integration Platform, Workflow Automation, Business Process Management, API Management, Event Stream Processing Application: Supply Chain Coordination, Customer Journey Management, IT Operations, Regulatory Compliance, Product Lifecycle Management End User Industry: Telecommunications, Banking & Insurance, Government Agencies, Manufacturing, Media & Entertainment |
| Companies Covered | SAP SE, Microsoft Corporation, Oracle Corporation, IBM Corporation, ServiceNow, Pegasystems Inc., Salesforce Inc., UiPath, Appian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Process Orchestration Market Shifts & Advancements
Process orchestration technology is actively fragmenting across architectural philosophies, with divergent paths emerging between centralized workflow engines and event-driven mesh topologies. Vendors are forced to place bets on opposing infrastructure paradigms.
Event-driven orchestration is bifurcating the market between batch-process legacy buyers and real-time streaming adopters. Apache Kafka and cloud-native message brokers enable sub-second synchronization across distributed microservices. Capital markets and logistics operators in Singapore and Frankfurt are deploying these architectures for trade settlement and supply chain visibility.
GDPR's algorithmic accountability requirements are forcing European banks to rebuild customer journey orchestration with immutable audit trails. The EU AI Act extends these obligations to automated decision workflows, requiring explainable logic gates in credit and insurance underwriting processes. French and Dutch institutions are prioritizing vendors with pre-certified compliance modules.
Subscription-based consumption models are displacing perpetual license procurement in mid-market manufacturing and professional services. Buyers in India and Brazil now expect usage-based pricing tied to workflow execution volumes rather than seat counts. This shift compresses vendor revenue recognition while expanding land-and-expand opportunities.
Global Process Orchestration Market Segmentation
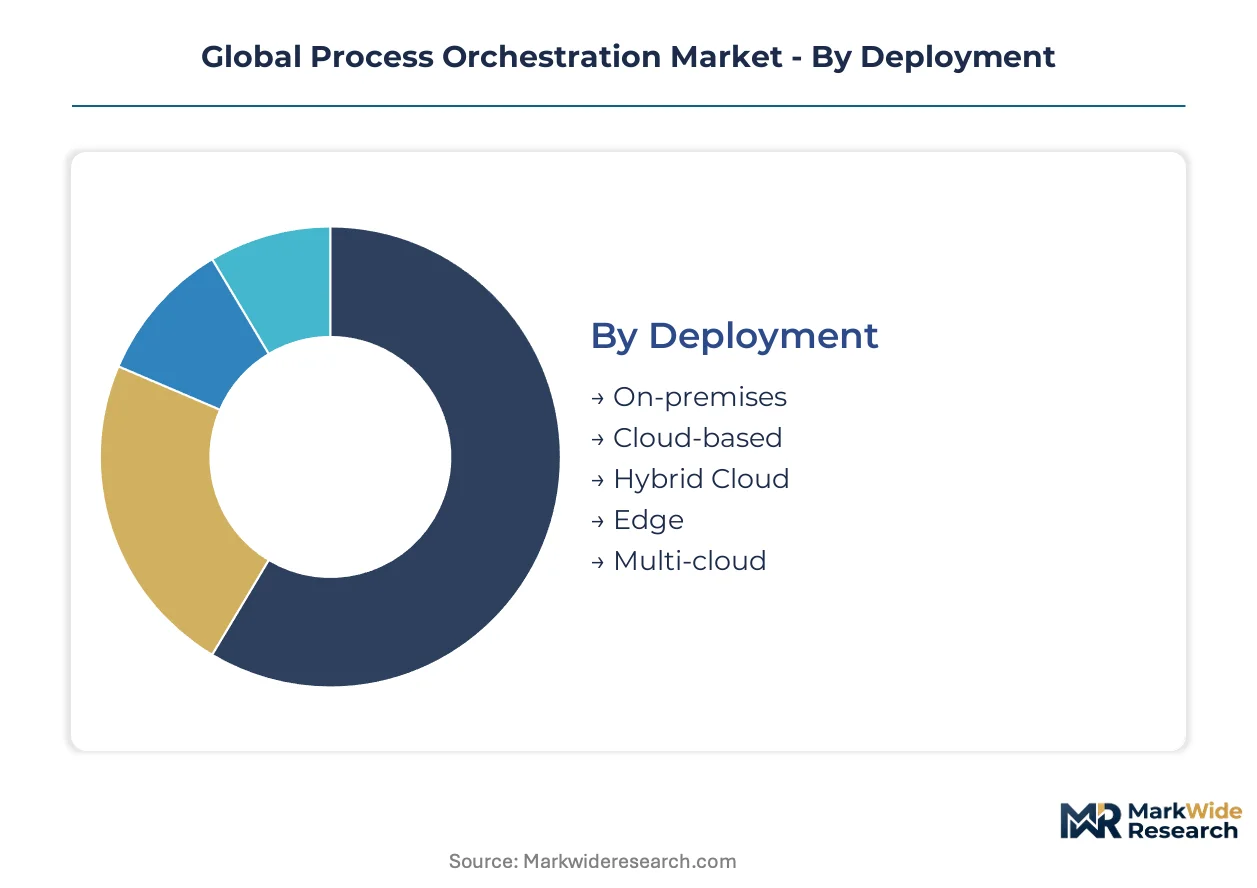
Process orchestration vendors structure their portfolios around deployment flexibility, solution depth, and industry-specific compliance requirements. Segmentation reveals where pricing power concentrates and which buyer archetypes drive platform roadmap priorities.
Deployment:
GDPR and HIPAA data residency mandates fragment deployment preferences across regulated industries, with auditability requirements favoring architectures that preserve geographic control over workflow execution.
- On-premises:Fixed-capacity installations within enterprise data centers maintain dominance in banking and insurance institutions managing core legacy systems. German industrial conglomerates and US healthcare networks prioritize these deployments for immutable audit trails required by HIPAA and the EU AI Act.
- Cloud-based:Elastic subscription models attract mid-market enterprises in India and Brazil seeking reduced infrastructure overhead. Usage-based pricing tied to workflow execution volumes displaces perpetual licenses in professional services and manufacturing procurement.
- Hybrid Cloud:Split architectures partition sensitive orchestration logic on-premises while bursting compute-intensive workloads to public infrastructure.
- Edge:Distributed execution nodes synchronize factory floor operations with centralized planning systems in real time.
- Multi-cloud:AWS, Azure, and GCP interoperability addresses vendor lock-in concerns among enterprises with existing cloud diversity.
Cloud-based handles the majority of new customer acquisition; Edge is gaining share fastest among manufacturing deployments.
Solution Offering:
Margin pools deepen where vendors bundle intelligent automation capabilities beyond basic workflow routing, with document processing and decision management commanding premium positioning.
- Integration Platform:Centralized middleware connecting ERP, CRM, and legacy databases through API gateways and message brokers. Banking institutions in France and the Netherlands deploy these for GDPR-compliant customer data synchronization across branch networks.
- Workflow Automation:Low-code design surfaces enabling business users to configure approval chains and exception handling without engineering resources. Mid-market professional services firms in Singapore and Frankfurt adopt these for rapid deployment of trade settlement and logistics visibility workflows.
- Business Process Management:End-to-end process modeling with simulation and optimization capabilities for complex multi-department orchestration.
- API Management:Gateway services governing authentication, rate limiting, and versioning for external partner integrations.
- Event Stream Processing:Sub-second pattern detection across high-volume message flows for capital markets and supply chain monitoring.
Integration Platform captures the deepest existing account value; Event Stream Processing shows the steepest expansion trajectory in capital markets procurement.
Application:
Regulatory pressure intensity varies sharply by use case, with customer-facing workflows facing stricter algorithmic accountability requirements than internal IT operations.
- Supply Chain Coordination:Multi-tier visibility across suppliers, manufacturers, and logistics providers with predictive exception management. German automotive and industrial conglomerates deploy these for end-to-end synchronization between legacy core systems and digital supplier portals.
- Customer Journey Management:Cross-channel orchestration of marketing, sales, and service touchpoints with real-time personalization. European banks rebuild these systems with immutable audit trails to satisfy GDPR and EU AI Act explainability mandates for credit and insurance underwriting decisions.
- IT Operations:Automated incident response and infrastructure provisioning with service desk integration.
- Regulatory Compliance:Pre-built workflow templates for SEC, HIPAA, and EU AI Act reporting with embedded data lineage tracking.
- Product Lifecycle Management:Stage-gate coordination across engineering, procurement, and manufacturing for discrete manufacturing verticals.
Supply Chain Coordination generates the largest deployment scale; Regulatory Compliance is climbing the fastest as institutions preempt enforcement deadlines.
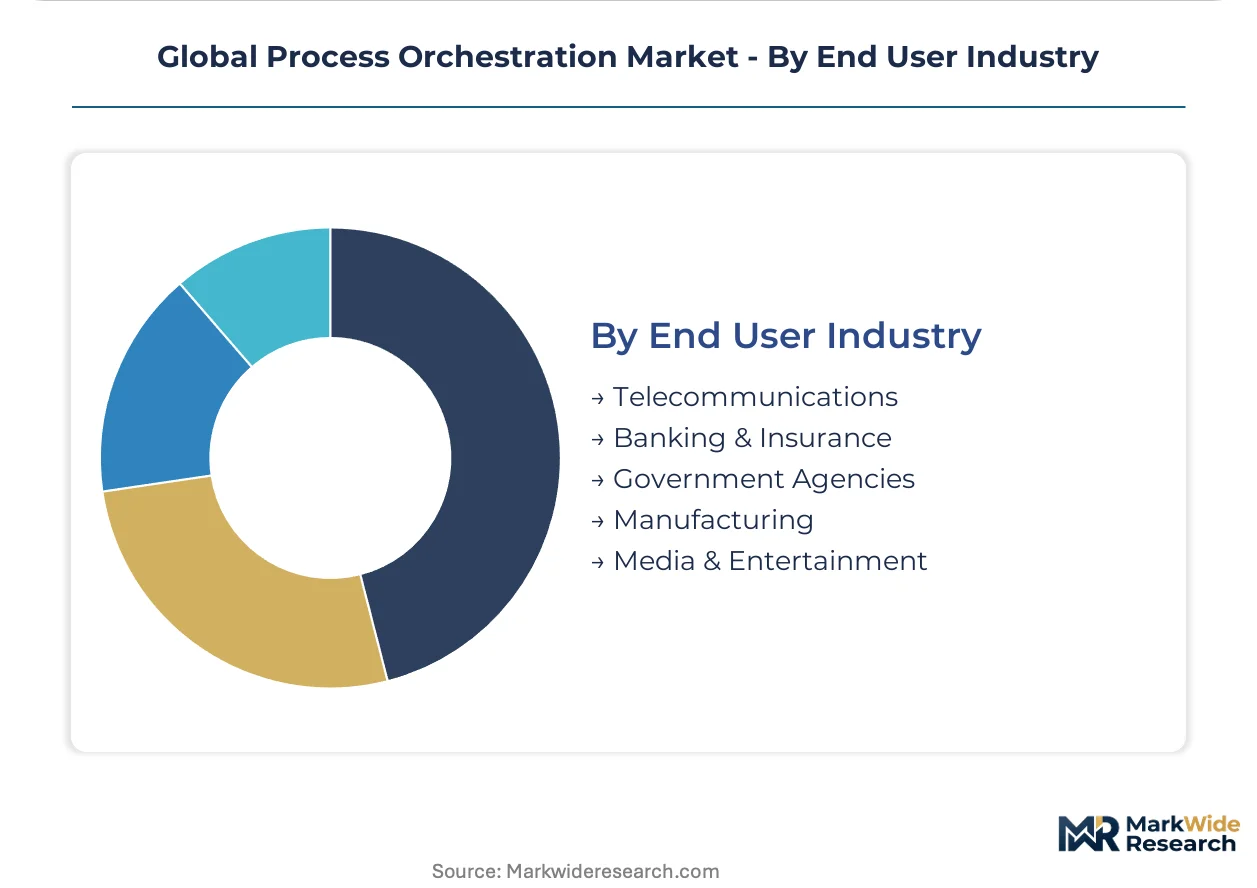
End User Industry:
Buyer sophistication and procurement cycle length diverge significantly, with government agencies imposing extended security certification requirements that filter vendor participation.
- Banking & Insurance:Core system modernization unifying legacy mainframes with digital channels, requiring strict auditability for SEC and EU AI Act compliance. French and Dutch institutions prioritize vendors with pre-certified compliance modules for automated decision workflows.
- Manufacturing:Shop-floor-to-enterprise synchronization with IoT integration and quality management system connectivity. German industrial operations lead deployment of edge-enabled orchestration for real-time production scheduling.
- Telecommunications:Network operations center automation and customer provisioning workflow management.
- Government Agencies:Citizen service delivery with multi-layer security clearances and inter-agency data sharing protocols.
- Media & Entertainment:Content supply chain coordination from production through distribution with rights management integration.
Banking & Insurance accounts for the largest current installed base; Manufacturing is expanding most quickly as Industry 4.0 investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial software exports flow into European banking modernization programs and North American healthcare digitization initiatives. Cross-border demand concentrates in workflow automation platforms with embedded compliance architectures.
United States
Healthcare networks and capital markets operators drive procurement of HIPAA-compliant orchestration suites with immutable audit trails. SEC disclosure mandates accelerate replacement of legacy batch systems with real-time workflow engines. New York and Chicago financial centers deploy event-stream processing for trade settlement synchronization.
Germany
Industrial conglomerates unify manufacturing execution systems with enterprise ERP through edge-enabled orchestration nodes. EU AI Act requirements reshape vendor selection criteria for automated decision workflows in automotive supply chains. Bavarian automotive clusters and North Rhine-Westphalian chemical operations lead Industry 4.0 deployments.
France
Banking institutions rebuild customer journey orchestration with explainable logic gates for credit underwriting decisions. CNIL enforcement of GDPR algorithmic accountability drives preference for pre-certified compliance modules. Parisian financial services and Lyon-based insurance operations prioritize auditable workflow platforms.
Singapore
Logistics operators and commodity trading houses adopt sub-second event streaming for supply chain visibility across Southeast Asian trade corridors. Monetary Authority of Singapore guidelines on operational resilience influence orchestration architecture specifications. Marina Bay financial district and Jurong Port logistics hubs anchor regional deployment.
India
Mid-market professional services firms and manufacturing SMEs shift from perpetual licenses to usage-based cloud orchestration pricing. RBI data localization requirements constrain cloud infrastructure placement for banking workflows. Bengaluru SaaS clusters and Mumbai financial technology operations expand regional delivery capabilities.
Global Process Orchestration Market Competitive Landscape
Listed leaders compete with private specialists across cloud-native deployment models and compliance certification depth. The vendor base stratifies between ERP-integrated incumbents, RPA-anchored automation platforms, and pure-play workflow specialists. Three archetypes dominate: enterprise software conglomerates extending orchestration into existing installed bases; automation-native vendors layering orchestration atop robotic process capabilities; and cloud-native specialists targeting mid-market elastic scalability requirements. Competitive moves concentrate on strategic partnerships for legacy system connectivity and geographic expansion through regional compliance certifications.
Within the ERP-integrated tier, SAP SE and Oracle Corporation exemplify incumbents leveraging core financial and supply chain workflow dominance. UiPath occupies a position representing the automation-native archetype, extending robotic capabilities into full orchestration stacks. Microsoft Corporation anchors the cloud productivity bundling strategy, embedding orchestration tools within broader enterprise software ecosystems.
| Leading Market Players |
|---|
| SAP SE |
| Microsoft Corporation |
| Oracle Corporation |
| IBM Corporation |
| ServiceNow |
| Pegasystems Inc. |
| Salesforce Inc. |
| UiPath |
| Appian |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day implementation cycles for cloud-native orchestration deployments concentrate vendor pricing power with platform providers holding certified compliance modules for EU AI Act and HIPAA mandates. German industrial buyers and US healthcare networks absorb premium positioning for on-premises installations with immutable audit trails, while mid-market SaaS procurement in India and Brazil compresses margins through usage-based consumption models.
Pricing Analysis
Current-generation cloud-native orchestration platforms command three-to-five-fold premiums over prior-generation on-premises perpetual licenses, with next-generation event-streaming architectures introducing additional performance-based tiers. Three-tier pricing structure across premium compliance-certified, standard cloud-native, and economy self-service levels dominates procurement in banking and insurance verticals. Cost compression in the economy tier is intensifying because low-code platform commoditization enables mid-market buyers to configure workflows without vendor professional services. Mid-market manufacturing and professional services firms in emerging markets exhibit highest price sensitivity, while German automotive conglomerates and US hospital networks demonstrate lowest sensitivity due to regulatory non-compliance penalties.
Supply Chain Analysis
Just-in-time delivery of orchestration platform updates via continuous deployment pipelines dominates cloud-native vendor operations, while strategic stockpiling of on-premises license inventory persists among legacy ERP-integrated providers serving regulated industries. Software development capacity concentrates in the United States, India, and Germany, with cloud infrastructure provisioning drawing from hyperscaler data center networks across Singapore, Ireland, and Virginia. The supply chain rests on specialized workflow architect talent pools concentrated in Western Europe and North American technology hubs. Single-source vulnerability in low-code platform component licensing creates concentration risk. Distribution runs through direct enterprise sales teams for large accounts and cloud marketplace listings for mid-market self-service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process orchestration sits in early-cycle expansion as EU AI Act enforcement deadlines accelerate replacement of non-compliant legacy workflow systems across European banking and insurance operations.
For Market Incumbents: Fortify competitive position by embedding pre-certified compliance modules for GDPR algorithmic accountability and EU AI Act explainability requirements directly into core platform offerings. Deepen vertical integration into intelligent document processing capabilities to capture premium positioning in financial services procurement. SAP SE and Oracle Corporation must defend against cloud-native specialists by accelerating edge-enabled orchestration node deployment for German manufacturing customers. For New Entrants and Emerging Players: EU AI Act certification fast-track programs for automated decision workflow modules open immediate white-space access in French and Dutch banking institutions rebuilding customer journey orchestration. Target mid-market professional services firms in Singapore and Frankfurt capitalizing on sub-second event streaming demand for trade settlement synchronization. Pursue usage-based pricing go-to-market angles in India and Brazil where perpetual license displacement creates land-and-expand opportunities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as subscription revenue recognition compresses upfront infrastructure investment recovery periods. Acquisition targets should display pre-certified compliance architectures for HIPAA and EU AI Act mandates alongside established channel partnerships with hyperscaler marketplaces. Monitor enforcement action velocity from CNIL and SEC as the signal indicating platform replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Pre-Certification | EU AI Act and GDPR mandates in European banking accelerate vendor selection toward pre-audited platforms. |
| Edge Orchestration Node Deployment | German automotive clusters demand real-time synchronization between factory floor systems and enterprise ERP. |
| Intelligent Document Processing Integration | Financial services procurement in the United States prioritizes bundled workflow automation with decision management. |
| Usage-Based Pricing Model Transition | Mid-market buyers in India and Brazil expect consumption tied to workflow execution volumes rather than seats. |
| Hyperscaler Marketplace Listing | AWS, Azure, and GCP distribution channels capture self-service procurement from cloud-native mid-market adopters. |
Research Methodology
Operator-level perspectives from chief technology officers, IT procurement officers, platform integration specialists, and workflow architects anchored the qualitative base for this study. Primary interviews across banking, manufacturing, and healthcare verticals combined with secondary validation from SEC filings, hyperscaler capex disclosures, EU regulatory enforcement databases, and cloud marketplace transaction data. Bottom-up deployment volume estimates triangulated against top-down market sizing from vendor revenue disclosures and channel partner surveys.
Sensitivity analysis across deployment model adoption curves, compliance deadline acceleration scenarios, and cloud infrastructure cost trajectories shaped the analytical framework. Segmentation dimensions modeled include deployment architecture, solution offering depth, end-user industry vertical, and regional regulatory cluster throughout the projection horizon. CAGRs derived from weighted average of historical vendor growth rates and forward-looking pipeline indicators from system integrator partners. Forecast inputs incorporated EU AI Act enforcement timelines and HIPAA audit frequency escalation patterns.
The analysis sits within stated boundaries; outcomes outside sustained cloud migration momentum or accelerated regulatory enforcement would require recalibration. Forecasts reflect assumptions regarding mid-market buyer archetype rotation and compliance module certification velocity. Revision becomes warranted when EU AI Act penalty implementation or HIPAA audit failure disclosure thresholds cross materiality levels for institutional procurement decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Email Deliverability Tools Market
Digital Solutions
AI Powered Home Solution Market
Digital Solutions
Germany Digital Twin Market
Digital Solutions
Crop Management Software Market
Digital Solutions
Asia-Pacific Digital Twin Market
Digital Solutions
Graph Technology Market
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
Data Marketplace Platform Market
Digital Solutions
IT Service Management Market
Digital Solutions
Car Wash Management System Market
Digital Solutions
Distributed Order Orchestration Market
Digital Solutions
Canada Digital Twin Market
Digital Solutions
Australia Digital Marketing Software Market
Digital Solutions
South Africa ICT Market
Digital Solutions
Electronic Document Management System (EDMS) Market
Digital Solutions
Messaging Platform Market