
 Global Sales Force Automation (SFA) Market | 2026-2036
Global Sales Force Automation (SFA) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sales Force Automation (SFA) Market Foresight
Buyer concentration in the pharmaceutical sector is shifting from fragmented field sales teams toward centralized procurement by multinational life sciences enterprises. Salesforce anchors its position through deep CRM-to-SFA integration and extensive healthcare vertical specialization. Cognizant competes by embedding SFA modules within broader enterprise transformation engagements for Fortune 500 manufacturers. Outreach differentiates through AI-driven sales engagement sequencing that extends native automation into predictive revenue intelligence.
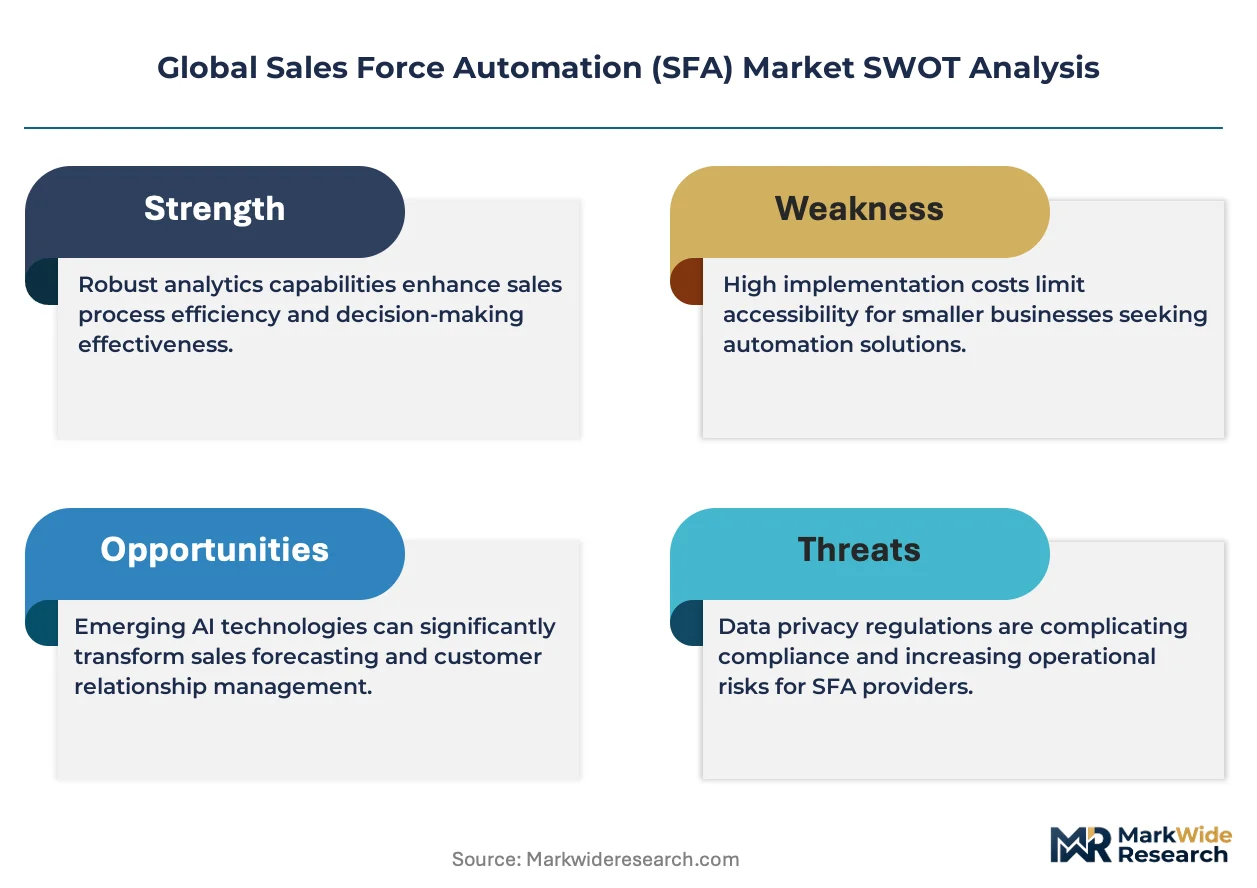
Sales force automation encompasses software systems that streamline field sales operations through lead routing algorithms, contact synchronization protocols, and territory optimization engines designed to reduce administrative overhead and accelerate revenue cycles. The primary commercial purpose centers on converting manual sales workflows into measurable, data-driven processes that improve rep productivity and forecast accuracy. Cloud-based deployment now leads solution type adoption as enterprises abandon capital-intensive on-premise infrastructure, while lead management and sales forecasting modules capture the deepest margin pools due to their direct linkage to revenue outcomes. Analytics capabilities within SFA platforms are expanding fastest as organizations demand real-time pipeline visibility and prescriptive selling recommendations.
The EU AI Act imposes algorithmic transparency requirements on predictive sales tools deployed across European enterprises, compelling vendors to document automated decision-making logic and maintain human oversight mechanisms. In the United States, HIPAA constrains how SFA platforms handle protected health information within pharmaceutical and medical device sales contexts, while SEC disclosure rules pressure publicly traded vendors to substantiate AI performance claims in sales automation products. Stakeholders must monitor evolving cross-border data localization mandates that threaten to fragment cloud-native SFA architectures and force region-specific compliance investments.
Market Dynamics
Cloud-native SFA architectures are displacing legacy on-premise deployments as pharmaceutical enterprises mandate field sales digitization under tightening data sovereignty frameworks. This infrastructure pivot concentrates procurement power among multinational life sciences buyers seeking unified compliance across jurisdictions.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:European enterprises must document automated decision-making in predictive sales tools, creating replacement demand for compliant SFA platforms with built-in audit trails.
- Life sciences field digitization:Pharmaceutical and medical device manufacturers are consolidating fragmented sales operations into centralized SFA systems to accelerate revenue cycle velocity.
- HIPAA-aligned data handling requirements:US healthcare sales contexts now require SFA vendors to engineer protected health information safeguards directly into platform architectures.
Market Restraints
- Cross-border data localization fragmentation:Divergent sovereignty mandates in Germany, India, and the United States force vendors to maintain region-specific infrastructure, elevating operational complexity.
- Legacy system integration technical debt:Established pharmaceutical CRM deployments resist seamless SFA module insertion, prolonging implementation timelines.
- Specialized compliance engineering talent scarcity:Shortage of professionals versed in both sales automation and multi-jurisdictional healthcare privacy law constrains vendor scaling.
Strategic Opportunities
- India's expanding enterprise software procurement budgets:Domestic pharmaceutical manufacturers and IT services exporters represent underpenetrated demand for cloud SFA with local data residency.
- Real-time prescriptive analytics convergence:Integration of AI-driven revenue intelligence with core SFA workflows creates premium pricing power in life sciences verticals.
- SEC disclosure pressure on AI performance claims:Publicly traded vendors face new substantiation requirements, favoring established platforms with documented algorithmic performance over emerging competitors.
Industry Challenges
- Multi-framework certification timeline compression:Vendors must simultaneously satisfy EU AI Act, HIPAA, and ISO 27001 audit cycles, straining quality assurance bandwidth.
- Terabyte-scale synchronization latency:Field sales teams in bandwidth-constrained regions experience degraded performance from real-time contact synchronization protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sales Force Automation (SFA) Market |
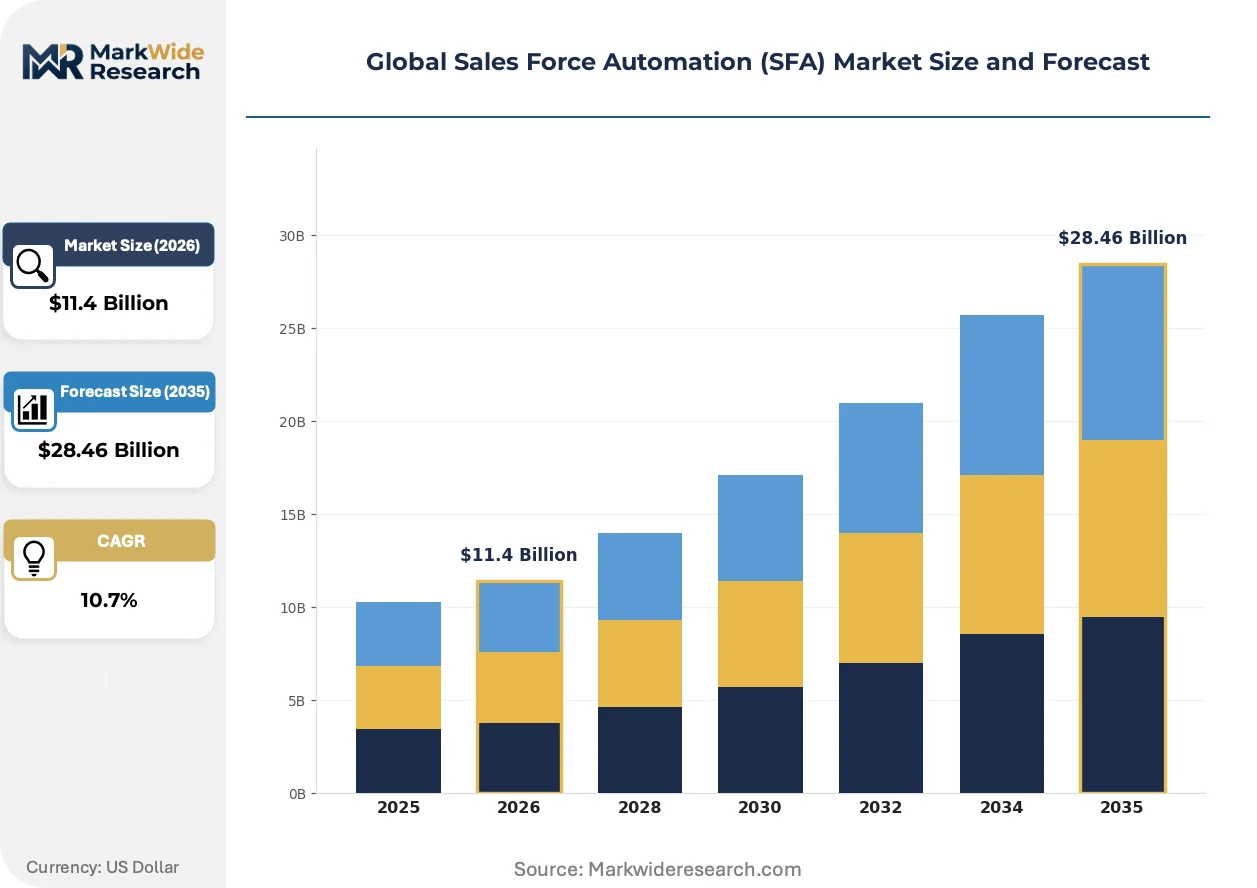
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $28.46 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Hosted Solution Type: Lead Management, Contact Management, Sales Forecasting, Analytics, Territory Management Industry Vertical: BFSI, Telecommunications, Consumer Goods, Pharmaceuticals, Information Technology End User: Small & Medium Enterprises, Large Enterprises, Distributors, Sales Representatives |
| Companies Covered | Cognizant, Outreach, Salesforce, Mobileforce Software, PandaDoc, SugarCRM, Capgemini, Freshworks, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sales Force Automation (SFA) Market Shifts & Advancements
Generative AI capabilities are embedding into SFA workflows, compressing the gap between raw customer data and actionable sales guidance. This technological infusion is reshaping competitive differentiation around predictive accuracy rather than feature breadth.
Predictive revenue intelligence engines are expanding into territory optimization and dynamic quota setting for pharmaceutical field forces. Life sciences enterprises in Germany and the United States are adopting these modules fastest, consolidating previously separate analytics point solutions. The technology is expanding into prescriptive selling recommendations that override rep intuition with data-driven next-best-action prompts.
The EU AI Act's algorithmic transparency requirements are forcing vendors to expose automated decision-making logic in lead-scoring and opportunity-ranking functions. European pharmaceutical sales operations face the steepest compliance burden, with France's CNIL and Germany's data protection authorities already issuing guidance on human oversight mechanisms. Vendors are responding by engineering "explainability" dashboards that satisfy auditor scrutiny without degrading user experience.
Centralized procurement by multinational life sciences enterprises is displacing fragmented field-team software selection. Regional sales managers in India and the United States now lack autonomy to choose point solutions, with headquarters IT mandating unified SFA stacks. This concentration is most visible among top-20 pharmaceutical manufacturers seeking global pipeline visibility.
Global Sales Force Automation (SFA) Market Segmentation
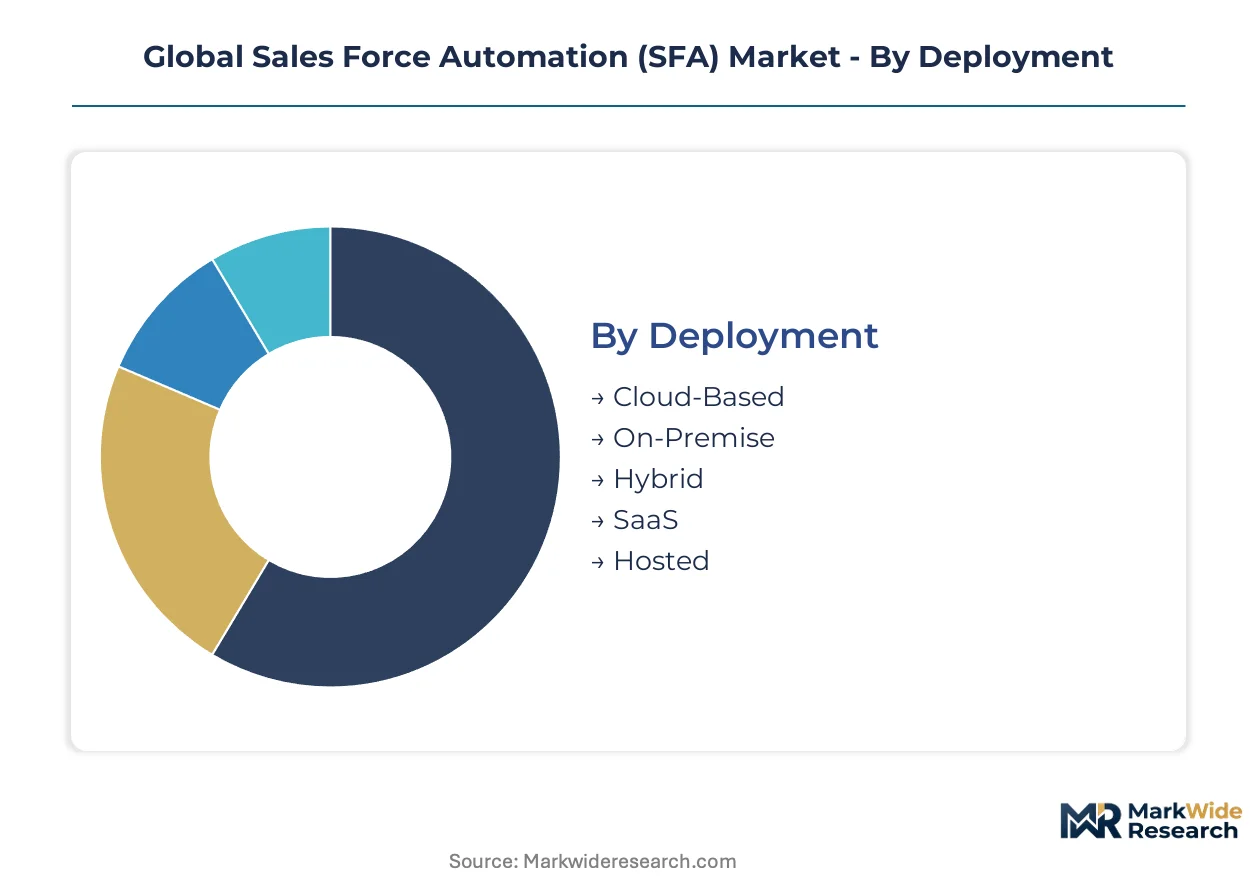
SFA procurement patterns diverge sharply across deployment architectures, solution modules, and buyer scale. Life sciences enterprises now drive premium segment growth as compliance mandates reshape vendor selection criteria.
Deployment:
Cloud-native architectures dominate enterprise procurement as data sovereignty frameworks eliminate on-premise flexibility.
- Cloud-Based:Multi-tenant architectures with automatic scaling and regional data residency options. Pharmaceutical manufacturers in Germany and the United States are mandating these deployments to satisfy EU AI Act documentation requirements and HIPAA audit trails simultaneously.
- SaaS:Subscription models with embedded compliance modules and API-first integration stacks. Indian IT services exporters and domestic pharmaceutical manufacturers are expanding fastest here due to predictable opex structures and rapid implementation timelines.
- On-Premise:Legacy single-tenant installations with full infrastructure control. Remains entrenched in highly regulated BFSI segments in Switzerland and Japan where national regulators impose strict data localization.
- Hybrid:Split architectures combining cloud scalability with on-premise sensitive data handling. Gaining traction among medical device manufacturers navigating dual jurisdiction sales operations.
- Hosted:Single-tenant managed services with vendor-operated infrastructure. Preferred by mid-market distributors in bandwidth-constrained Indian tier-2 cities requiring dedicated performance guarantees.
Cloud-Based leads volumes today; SaaS is gaining share fastest.
Solution Type:
Module selection tracks directly to revenue cycle touchpoints with the highest measurability.
- Lead Management:Automated routing algorithms and scoring engines that prioritize opportunity queues. Pharmaceutical field forces in the United States are consolidating previously manual physician targeting workflows here, driven by Sunshine Act disclosure precision requirements.
- Analytics:Real-time pipeline visibility dashboards with predictive forecasting and prescriptive next-action recommendations. Expanding most quickly in German life sciences enterprises where EU AI Act explainability mandates demand transparent algorithmic logic.
- Sales Forecasting:Statistical models projecting revenue closure probabilities across opportunity stages. BFSI institutions in India leverage these modules for quarterly regulatory reporting to SEBI and RBI.
- Contact Management:Centralized synchronization protocols for customer data across field devices. Critical infrastructure for telecommunications vendors maintaining subscriber relationships across fragmented Indian state-level markets.
- Territory Management:Geographic optimization engines balancing rep workload against market potential. Consumer goods distributors deploy these to align coverage with India's PLI scheme manufacturing clusters.
Lead Management anchors current procurement budgets; Analytics shows the steepest expansion trajectory.
Industry Vertical:
Vertical specialization determines compliance engineering depth and integration complexity.
- Pharmaceuticals:Field sales digitization with embedded HIPAA safeguards and physician interaction tracking. Multinational enterprises headquartered in the United States and Germany are consolidating fragmented regional deployments into unified global stacks.
- Information Technology:API-heavy configurations supporting complex solution sales cycles. Indian software exporters and domestic SaaS providers are expanding procurement fastest as they build direct enterprise sales capabilities.
- BFSI:Regulatory reporting integration with audit trail preservation. Swiss and Japanese institutions maintain the strictest requirements here.
- Telecommunications:High-velocity subscriber acquisition workflows with churn prediction. Indian operators leverage these for competitive intensity in metropolitan markets.
- Consumer Goods:Route-to-market optimization for distributor networks. German manufacturers prioritize these modules for retail coverage density.
Pharmaceuticals commands premium pricing today; Information Technology is climbing the fastest.
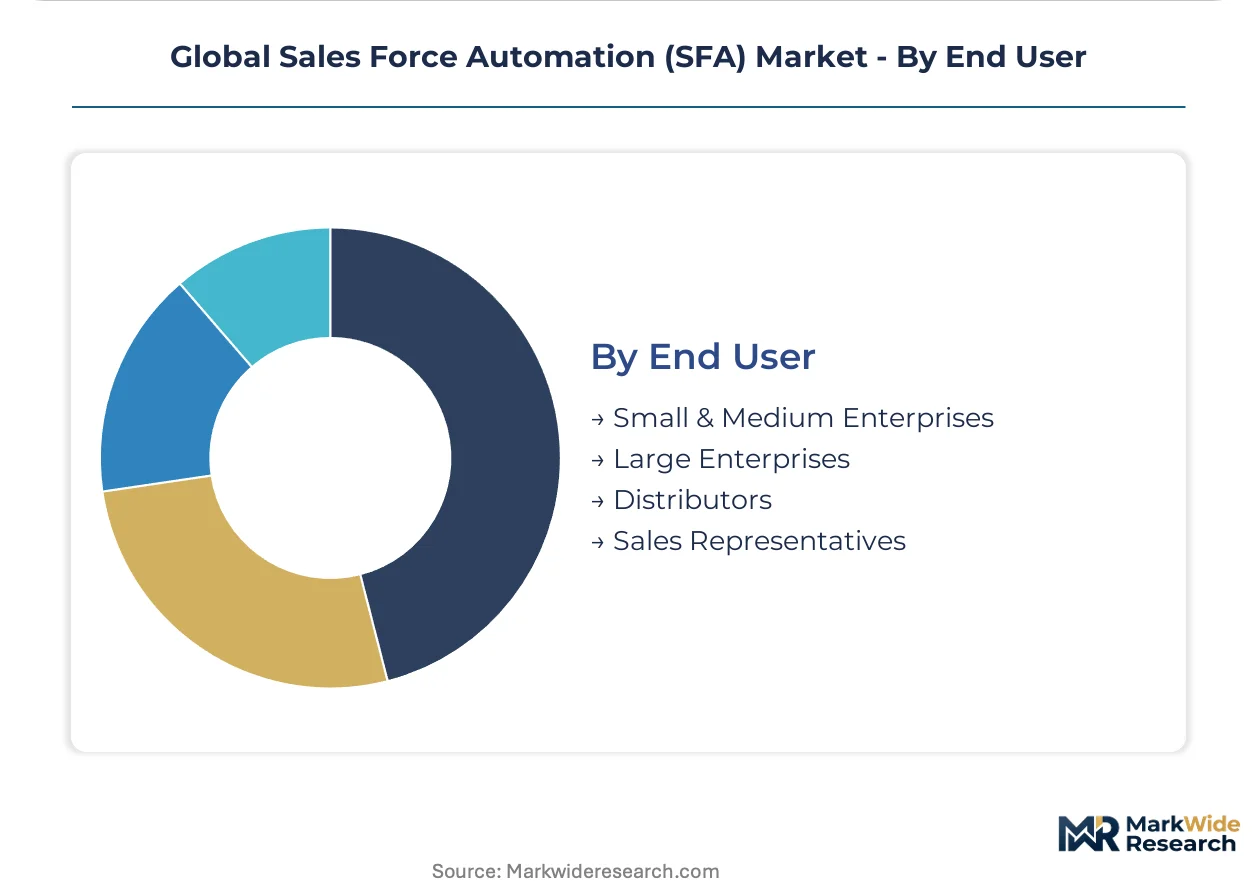
End User:
Scale determines implementation approach and customization tolerance.
- Large Enterprises:Global template deployments with centralized governance and regional localization. Top-20 pharmaceutical manufacturers mandate unified SFA stacks, stripping autonomy from country managers.
- Sales Representatives:Mobile-first interfaces with offline synchronization and voice-enabled data entry. Field forces in India's bandwidth-variable districts require these capabilities for reliable performance.
- Small & Medium Enterprises:Rapid-deployment configurations with pre-built vertical templates. Domestic pharmaceutical manufacturers in India represent underpenetrated demand here.
- Distributors:Multi-brand inventory visibility with order capture and fulfillment tracking. Consumer goods networks in Germany deploy these for retail execution monitoring.
Large Enterprises dominate absolute spend; Sales Representatives is expanding most quickly as mobile penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmaceutical SFA procurement outpaces India's domestic manufacturing demand, though both markets converge on cloud-native compliance architectures. The United States anchors enterprise software spend, while regulatory fragmentation across jurisdictions forces vendors into region-specific infrastructure investments.
United States
HIPAA-aligned field sales digitization drives pharmaceutical manufacturers toward centralized SFA procurement. SEC disclosure rules pressure publicly traded vendors to document AI performance claims in predictive sales tools. Boston and San Francisco Bay Area biotech clusters consolidate previously fragmented physician-targeting workflows into unified enterprise stacks.
Germany
EU AI Act algorithmic transparency mandates reshape vendor selection for life sciences enterprises. Germany's BfArM and regional data protection authorities issue guidance on human oversight mechanisms for automated lead-scoring. The Rhine-Ruhr pharmaceutical corridor accelerates replacement demand for SFA platforms with built-in audit trails and explainability dashboards.
India
Domestic pharmaceutical manufacturers and IT services exporters expand cloud SFA procurement under RBI data localization guidance. SEBI reporting requirements push BFSI institutions toward sales forecasting modules for quarterly regulatory disclosure. Mumbai-Pune and Hyderabad-Chennai pharma manufacturing belts represent underpenetrated demand for SaaS deployments with local data residency.
Switzerland
Swissmedic oversight and strict national data localization sustain on-premise SFA entrenchment among BFSI segments. Swiss pharmaceutical multinationals headquartered in Basel maintain hybrid architectures balancing cloud scalability with sovereign data control. The Zurich financial services cluster preserves legacy single-tenant installations where regulators impose infrastructure custody requirements.
Japan
METI industrial digitization incentives accelerate field sales automation among medical device manufacturers. PMDA documentation standards for sales representative interactions with healthcare providers elevate compliance-engineered platform demand. The Tokyo-Osaka pharmaceutical corridor adopts predictive revenue intelligence modules for territory optimization and dynamic quota setting.
Global Sales Force Automation (SFA) Market Competitive Landscape
United States software vendors anchor the premium tier; Indian IT services specialists hold mid-market implementation capacity. The vendor base stratifies around three strategic archetypes: CRM-native platforms with deep healthcare vertical integration, consulting-led systems integrators embedding SFA within enterprise transformation engagements, and AI-native engagement specialists extending automation into predictive intelligence. Dominant competitive moves include portfolio diversification into adjacent revenue intelligence modules and geographic expansion through regional data residency infrastructure.
Within the CRM-native tier, Salesforce exemplifies deep platform integration with healthcare compliance specialization. Cognizant and Accenture occupy positions as consulting-led integrators embedding SFA modules within broader Fortune 500 transformation programs. Outreach represents the AI-native archetype, anchoring predictive sales engagement sequencing that extends core automation into revenue intelligence workflows.
| Leading Market Players |
|---|
| Cognizant |
| Outreach |
| Salesforce |
| Mobileforce Software |
| PandaDoc |
| SugarCRM |
| Capgemini |
| Freshworks |
| Accenture |
| Others |
Supply & Pricing Matrix
Compliance engineering labor costs in Germany and the United States cascade through SaaS subscription tiers, compressing margins for vendors lacking automated audit trail architectures while enabling premium pricing for EU AI Act-certified platforms serving multinational pharmaceutical buyers.
Pricing Analysis
Capacity additions in India's cloud infrastructure are reshaping price floors for mid-market SaaS deployments as domestic pharmaceutical manufacturers and IT services exporters negotiate volume-based discounts. Pricing stratifies across enterprise-grade compliance bundles, standard multi-tenant subscriptions, and economy-tier hosted configurations differentiated by data residency guarantees and API integration depth. Cost compression in the economy tier is intensifying because bandwidth-constrained tier-2 deployments require dedicated single-tenant infrastructure. Small and medium enterprises in India's domestic pharmaceutical sector exhibit the highest price sensitivity, while large multinational life sciences enterprises in Germany and the United States prioritize compliance certification over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from multinational pharmaceutical buyers mandate multi-vendor qualification for cloud infrastructure providers across at least two of the United States, Germany, and India to satisfy cross-border data localization mandates. Platform engineering draws from specialized compliance talent pools in the United States and Germany, with implementation services anchored in India's IT services corridor. Single-source vulnerability concentrates in explainable AI algorithm development, where vendors rely on scarce machine learning engineers versed in both pharmaceutical sales workflows and EU AI Act documentation standards. Distribution runs through direct enterprise sales teams for large pharmaceutical manufacturers, supplemented by systems integrator partnerships for mid-market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Sales Force Automation Market compounds steadily as regulatory mandates across multiple jurisdictions perpetuate replacement cycles for non-compliant legacy deployments.
For Market Incumbents: Acquire specialized compliance engineering firms with EU AI Act implementation expertise to defend against emerging AI-native challengers lacking healthcare vertical depth. Expand data residency infrastructure into India's RBI-guided localization zones to preempt domestic vendor capture of IT services exporter demand. Certification investment in ISO 27001 and HIPAA-aligned architectures remains the critical lever for maintaining pharmaceutical procurement preference. For New Entrants and Emerging Players: The EU AI Act in Germany opens a window for explainable AI modules that retrofit incumbent platforms with algorithmic transparency dashboards. White-space targets include mid-market domestic pharmaceutical manufacturers in India's Hyderabad-Chennai belt and SaaS-native deployments for IT services exporters building direct enterprise sales capabilities. A channel partnership strategy with Mumbai-based systems integrators accelerates market entry without direct sales infrastructure investment. For Investors and Strategic Acquirers: Consolidation pressure builds where compliance engineering talent scarcity constrains vendor scaling velocity across European and North American markets. Long-term viability favors platforms with embedded healthcare vertical specialization and documented algorithmic performance under SEC disclosure scrutiny. The signal to watch is enforcement action intensity from France's CNIL and Germany's regional data protection authorities, which would accelerate replacement demand for audit-trail-equipped platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep CRM-to-SFA connectivity captures pharmaceutical procurement consolidation toward unified stacks. |
| Acquisition of Specialist Firm | Compliance engineering boutiques in Germany address EU AI Act explainability mandate execution gaps. |
| Geographic Expansion | India data residency infrastructure satisfies RBI localization guidance for domestic pharmaceutical demand. |
| Product Launch | Prescriptive analytics modules with territory optimization target German life sciences enterprise budgets. |
| Strategic Partnership | Systems integrator alliances in India accelerate mid-market SaaS penetration without direct sales buildout. |
Research Methodology
Bottom-up pharmaceutical and IT services modeling reconciled against top-down cloud infrastructure deployment tracking forms the analytical core of this study. Primary interviews with field sales operations directors, regulatory affairs leads at multinational life sciences enterprises, IT procurement officers, and systems integrator partners combined with secondary validation from SEC filings, EU AI Act implementation guidance documents, and RBI circulars on data localization. Triangulation across stakeholder perspectives and documentary sources ensures segment-level accuracy.
Input-output matrices map deployment architecture adoption, solution module procurement intensity, and vertical specialization depth across the projection horizon. Segmentation dimensions modeled include deployment model, organization scale, industry vertical, geographic regulatory cluster, and integration complexity tier. CAGRs derive from curve-fitting historical procurement patterns against mandate-driven replacement cycle assumptions, with pharmaceutical field digitization intensity and AI transparency enforcement timelines as industry-specific forecast inputs.
Revisions become necessary when EU AI Act enforcement intensity, HIPAA audit frequency, or RBI data localization scope materialize beyond baseline assumptions. Deviation in cross-border data sovereignty mandate fragmentation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
US Workload Scheduling and Automation Market
Automation
Indonesia Automation and Control System Market
Automation
Middle East and Africa Workforce Management Market
Automation
Automation Light Grids Market
Automation
Home Automation and Controls Market
Automation
Escalator Control Systems Market
Automation
Self Bag Drop Machine Market
Automation
Parcel Sorting System Market
Automation
Global Water Automation and Instrumentation Market
Automation
Laboratory Benchtop Automation Market
Automation
IoT Home Automation Market
Automation
CNC Controller Market
Automation
Global Form Automation Software Market
Automation
Universal Process Control Market
Automation
Marketing Automation Solutions Market
Automation
Asia-Pacific Automated Liquid Handling Market