
 Self Bag Drop Machine Market | 2026-2036
Self Bag Drop Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Self Bag Drop Machine Market Insights
The self bag drop equipment landscape is shifting between premium integrated systems and basic countertop models as capital deployment strategies diverge across airport tiers. Vanderlande Industries leverages its baggage handling integration expertise to anchor large-hub deployments. Daifuku Co., Ltd. sustains manufacturing scale across Asian airport expansions. Materna IPS competes through software-hardware convergence in European terminals.
Self bag drop machines are automated kiosks that combine passenger identification verification, baggage weighing, tag printing, and conveyor handoff into a single passenger-operated station, typically processing items up to 50 kg with dimensional scanning and security compliance checks. Floor-standing units dominate installed base volume due to their throughput capacity and compatibility with existing baggage conveyor infrastructure. RFID scanning technology leads growth trajectory as IATA mandate compliance deadlines approach, while optical character recognition retains strong positioning in retrofit installations where legacy infrastructure limits hardware replacement scope.
FAA Part 139 airport certification standards in the United States, EASA aerodrome design regulations across Europe, and IATA baggage handling guidelines collectively shape equipment specifications and interoperability requirements for self bag drop deployments. Terminal operators must evaluate technology refresh cycles against evolving biometric integration standards and carbon reduction commitments embedded in airport concession agreements. Stakeholders should monitor how passenger processing time metrics influence procurement scoring in upcoming terminal expansion tenders.
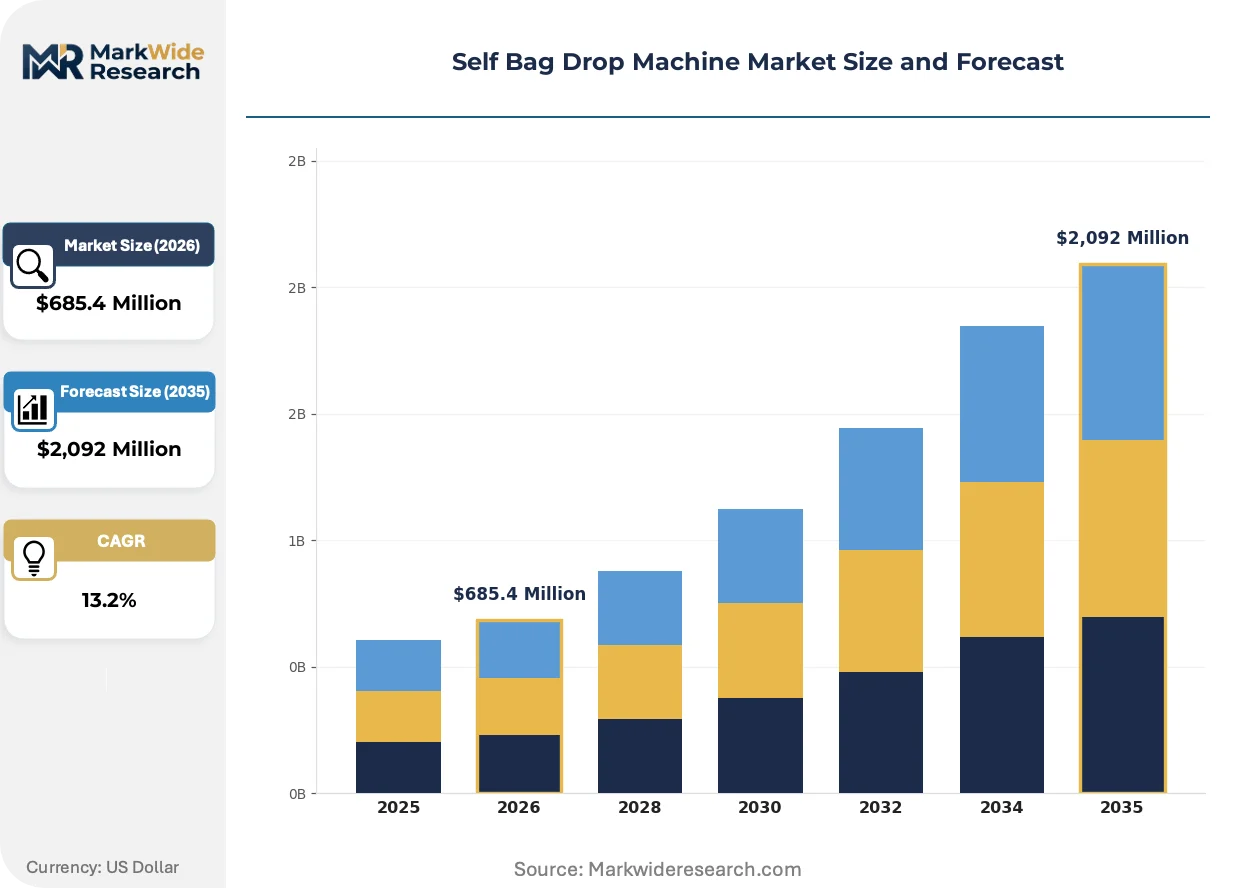
Market Dynamics
IATA Resolution 753 baggage tracking mandates are compressing procurement timelines as terminal operators race to deploy RFID-enabled self bag drop infrastructure before compliance deadlines. This regulatory pressure is forcing hardware refresh cycles that would otherwise span seven to ten years into three to five year windows.
Growth Catalysts
- RFID Mandate Compliance:IATA Resolution 753 requires end-to-end baggage tracking by June 2018, compelling airports to replace optical scanning systems with RFID-enabled self bag drop machines.
- United States Airport Modernization:FAA Part 139 certification standards and Bipartisan Infrastructure Law funding are accelerating terminal automation projects at congested hubs.
- Biometric Integration:Facial recognition and touchless passenger verification are converging with bag drop hardware, creating single-token journey capabilities that reduce processing times.
Market Restraints
- Steel and Aluminum Input Volatility:Conveyor chassis and structural components face commodity price swings that compress equipment margins during tender cycles.
- European Supplier Concentration:Critical RFID reader modules and industrial motion controllers source primarily from German and Dutch component specialists, creating single-source vulnerability.
- Legacy Conveyor Incompatibility:Existing baggage handling infrastructure at mid-tier airports lacks the data interfaces and physical clearances required for integrated self bag drop retrofits.
Strategic Opportunities
- India Greenfield Airports:Noida International Airport and Navi Mumbai International Airport are procuring fully automated terminals without legacy baggage system constraints.
- EU Green Deal Incentives:Carbon reduction commitments embedded in airport concession agreements favor energy-efficient self bag drop equipment in terminal expansion tenders.
- Biometric-RFID Convergence:One Identity platforms that fuse facial recognition with baggage tracking are creating premium pricing tiers for integrated hardware-software contracts.
Industry Challenges
- Mechatronics Talent Scarcity:The intersection of industrial automation, aviation security protocols, and passenger experience design requires specialized engineering profiles in short supply.
- Multi-Agency Certification Timelines:FAA, TSA, and airport authority approvals for new self bag drop deployments extend implementation schedules by twelve to eighteen months.
- Baggage Information Messaging Standard Delays:Incomplete adoption of IATA RP 1755 messaging protocols forces custom integration work between equipment vendors and legacy airport operational databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self Bag Drop Machine Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,092 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Countertop Models, Floor-Standing Units, Portable Versions, Integrated Systems Technology: RFID Scanning, Barcode Recognition, Weight Measurement, Optical Character Recognition, Touchscreen Interface Application: Airports, Rail Stations, Cruise Terminals, Toll Booths End User: Airline Operators, Terminal Authorities, Travel Agencies, Logistics Providers, Security Firms |
| Companies Covered | Amadeus IT Group, Vanderlande Industries, BEUMER Group, SITA, Materna IPS, Collins Aerospace, Daifuku Co., Ltd., Embross, ICM Airport Technics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self Bag Drop Machine Market Trends and Innovations
Edge computing architectures are migrating baggage processing intelligence from central terminal servers to distributed kiosk nodes. This shift is reducing network latency for real-time weight verification and security screening decisions while enabling offline operation during connectivity disruptions.
Computer vision-based bag dimensioning is decentralizing physical measurement tasks from centralized screening equipment to individual self bag drop stations. Low-cost depth cameras and neural network inference engines are enabling sub-centimeter accuracy for irregular luggage shapes. Low-cost carriers at secondary European airports are adopting these systems fastest, compressing passenger processing times from ninety seconds to under forty-five seconds per bag.
EU AI Act risk classification requirements are reshaping biometric verification deployments in self bag drop machines. High-risk AI systems for passenger identification now require conformity assessments, human oversight protocols, and algorithmic transparency documentation. German and French hub airports are front-loading compliance costs into procurement specifications, while retrofitting existing installations with audit trail capabilities.
Airline direct procurement of self bag drop equipment is displacing traditional airport authority capital ownership models. Carriers including Lufthansa and Delta are contracting directly with Vanderlande and Materna IPS for dedicated check-in zones, unbundling hardware costs from landing fee negotiations. This channel shift concentrates buying power with airline procurement teams and compresses vendor margins through volume commitments.
Self Bag Drop Machine Market Segmentation
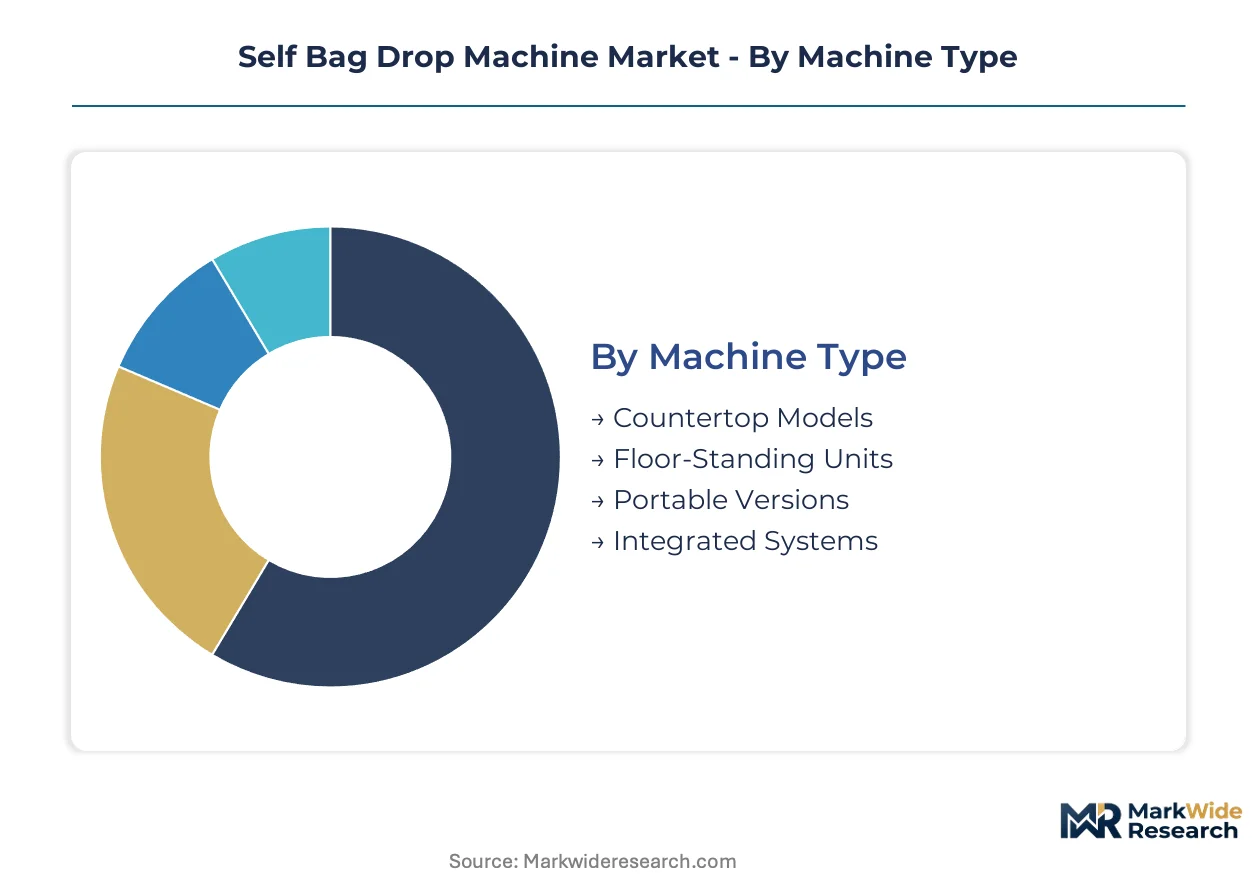
Segmentation in self bag drop equipment reveals how procurement priorities diverge between throughput-maximizing hubs and cost-constrained regional facilities. Equipment specifications, technology integration depth, and ownership models all fragment across airport tiers and regulatory environments.
Machine Type:
The customization-vs-standardization spectrum spans from bespoke integrated systems engineered for specific terminal layouts to mass-produced countertop units deployable across multiple gate configurations.
- Countertop Models:Compact units designed for space-constrained check-in zones and retrofit installations at mid-tier airports. Demand concentrates in European secondary airports where legacy terminal footprints limit floor space availability and IATA compliance deadlines force rapid deployment without structural modifications.
- Floor-Standing Units:Full-height kiosks with integrated conveyor handoff and dimensional scanning capabilities. United States major hubs including Atlanta Hartsfield-Jackson and Dallas-Fort Worth are standardizing on these configurations for their compatibility with existing baggage handling infrastructure and higher passenger throughput per square meter.
- Portable Versions:Mobile units with battery power and wireless connectivity for temporary terminals and seasonal capacity surges. Deployed at Saudi Arabia's seasonal pilgrimage terminals and Australian regional airports during peak tourism windows.
- Integrated Systems:Custom-engineered installations embedding bag drop within complete check-in island architectures. German hub airports commission these from Vanderlande and Daifuku for dedicated airline zones requiring biometric-conveyor fusion.
Leading the category by volume: Floor-Standing Units. Growing fastest: Integrated Systems.
Technology:
Technology selection tracks regulatory mandate timelines and legacy infrastructure replacement cycles across different airport modernization phases.
- RFID Scanning:Radio-frequency identification systems enabling IATA Resolution 753 end-to-end baggage tracking compliance. United States and German airports are mandating this technology in all new procurement specifications ahead of enforcement deadlines.
- Barcode Recognition:Legacy optical scanning dependent on printed tag readability. Retains installed base dominance at Chinese and Indian airports where hardware refresh cycles lag Western compliance schedules.
- Weight Measurement:Precision load cells integrated with airline revenue protection systems. Critical for low-cost carriers at European terminals enforcing strict baggage allowance policies.
- Optical Character Recognition:Document verification systems extracting passenger data from passports and boarding passes. Deployed extensively at Dubai International and Singapore Changi for multi-language document processing.
- Touchscreen Interface:Passenger-facing interaction layers requiring accessibility compliance and multilingual support. French hub specifications now embed EU AI Act conformity requirements for biometric-adjacent touchpoints.
Highest deployment velocity: RFID Scanning. Steepest replacement pressure: Barcode Recognition.
Application:
Application segmentation reflects baggage automation expansion beyond aviation into multimodal passenger terminals.
- Airports:Primary deployment environment encompassing international hubs, domestic terminals, and general aviation facilities. Captures equipment volume concentration and technology specification leadership.
- Rail Stations:Emerging adoption for high-speed rail baggage services in China and European international routes. Shanghai Hongqiao and London St Pancras are piloting integrated check-in for air-rail intermodal journeys.
- Cruise Terminals:Seasonal deployment for embarkation processing at Miami, Barcelona, and Singapore cruise ports. Equipment faces salt corrosion specifications distinct from aviation standards.
- Toll Booths:Niche application for commercial freight identification at automated border crossings. Limited to specific customs integration projects in Switzerland and Norway.
Dominant volume share: Airports. Expanding most quickly: Rail Stations.
End User:
End user segmentation captures the shift from airport authority capital ownership toward airline direct procurement and outsourced terminal operations.
- Airline Operators:Carriers including Lufthansa, Delta, and Emirates contracting directly for dedicated check-in zones. This channel shift concentrates buying power and compresses vendor margins through multi-year fleet commitments.
- Terminal Authorities:Traditional procurement channel encompassing airport-owned common-use systems. Frankfurt Airport and Amsterdam Schiphol maintain this model for shared infrastructure.
- Travel Agencies:Limited deployment for premium passenger services and corporate travel management. Restricted to specific off-airport check-in partnerships in urban centers.
- Logistics Providers:Ground handling companies integrating bag drop into broader passenger service contracts. Swissport and dnata are expanding automated equipment portfolios across their global station networks.
- Security Firms:Specialized procurement for integrated screening and baggage handling at sensitive facilities. Israeli airport security specifications drive this segment's unique certification requirements.
Largest procurement volume: Terminal Authorities. Fastest channel shift: Airline Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atlanta Hartsfield-Jackson anchors the United States market with the world's busiest airport deploying floor-standing units across its domestic terminal modernization. FAA Part 139 certification standards and Bipartisan Infrastructure Law funding are compressing procurement timelines at congested hubs nationwide.
United States
Terminal automation investments at Dallas-Fort Worth and Denver International are standardizing on integrated conveyor-compatible configurations. FAA Part 139 aerodrome certification mandates equipment interoperability specifications that favor established vendor relationships. The Southeast corridor from Atlanta through Florida concentrates deployment velocity as snowbird traffic patterns demand seasonal capacity flexibility.
Germany
Frankfurt Airport and Munich Airport are commissioning custom-engineered systems for dedicated Lufthansa zones requiring biometric-conveyor fusion. EASA aerodrome design regulations embed EU AI Act conformity requirements into procurement specifications. The Rhine-Main industrial cluster hosts Vanderlande and Materna IPS engineering centers that anchor European technology specification leadership.
China
Beijing Daxing and Shanghai Pudong are expanding automated terminals without legacy baggage system constraints. MIIT industrial equipment standards and GB certification protocols govern domestic supplier qualification. The Yangtze River Delta manufacturing corridor supplies conveyor chassis and motion control subsystems to regional airport expansion programs.
United Arab Emirates
Dubai International and Abu Dhabi International are piloting multi-language document processing systems for transit passenger volumes. The country's aviation regulator mandates interoperability with IATA baggage handling guidelines for hub connectivity. Jebel Ali industrial zone fabrication facilities support rapid deployment timelines for seasonal capacity surges.
India
Noida International Airport and Navi Mumbai International Airport are procuring fully automated terminals on greenfield sites without retrofit constraints. BIS equipment certification and DGFT import regulations shape vendor qualification pathways. The Delhi-Mumbai Industrial Corridor logistics infrastructure is aligning with airport automation timelines for multimodal passenger processing.
Self Bag Drop Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integration depth and software-hardware convergence capabilities. The vendor base clusters around three strategic archetypes: baggage handling system integrators with terminal-wide project capabilities, kiosk specialists with passenger experience software stacks, and industrial automation conglomerates with manufacturing scale. Consolidation pressure is accelerating through airline direct procurement channel shifts and multi-year fleet commitment negotiations. Technology licensing partnerships between hardware fabricators and biometric software providers represent the dominant competitive move alongside geographic expansion through airport authority framework agreements.
Within the system integrator tier, Vanderlande Industries and Daifuku Co., Ltd. anchor large-hub deployment capabilities across their respective European and Asian home markets. Materna IPS occupies a position exemplifying software-hardware convergence specialization for biometric-integrated terminals. These three entities represent distinct geographic anchoring strategies—Dutch baggage handling integration expertise, Japanese industrial automation manufacturing scale, and German passenger processing software development—that collectively span the premium procurement channel.
| Leading Market Players |
|---|
| Amadeus IT Group |
| Vanderlande Industries |
| BEUMER Group |
| SITA |
| Materna IPS |
| Collins Aerospace |
| Daifuku Co., Ltd. |
| Embross |
| ICM Airport Technics |
| Others |
Pricing and Supply Chain Analysis
Airline direct procurement contracts are compressing vendor margins while concentrating buying power with carrier procurement teams, forcing equipment suppliers to absorb commodity volatility through captive manufacturing or long-term steel and aluminum offtake agreements.
Pricing Analysis
Throughput-based pricing anchors equipment contracts, with terminal operators paying premium rates for systems guaranteeing sub-sixty-second passenger processing times. Three-tier pricing structure across premium integrated, standard floor-standing, and economy countertop levels reflects certification depth and biometric integration scope. Cost compression in the countertop segment is intensifying because low-cost carriers are unbundling hardware from software maintenance. Regional airports exhibit highest price sensitivity, while major hub authorities prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in the Netherlands, Germany, and Japan coordinate hub-and-spoke delivery patterns for motion control modules and RFID reader assemblies. Manufacturing draws from China's Yangtze River Delta for conveyor chassis, Germany's Rhine-Main cluster for industrial controllers, and Japan's precision component specialists for load cells. Single-source vulnerability in Dutch and German RFID module suppliers creates tariff exposure risk. Distribution runs through airport authority framework agreements and airline direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is executing a technology-transition phase as RFID-enabled systems displace legacy barcode infrastructure ahead of IATA compliance deadlines.
For Market Incumbents: Extend software-hardware convergence capabilities through biometric integration partnerships and edge computing architectures. Counter airline direct procurement concentration by anchoring multi-year service contracts with terminal authorities. Vertical integration into motion control subsystems mitigates European supplier concentration risk. For New Entrants and Emerging Players: Launch via portable and countertop configurations targeting Indian greenfield airports and Australian seasonal terminals where legacy infrastructure constraints are absent. Rail station baggage automation offers the most penetrable adjacent application. Position through modular, API-first platforms enabling rapid airline system integration. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-specialist targets in Germany and biometric verification module developers in the United Arab Emirates during airline procurement pauses. Long-term viability hinges on regulatory compliance technology moats rather than hardware fabrication scale. Monitor IATA messaging protocol adoption rates as inflection indicator for integration service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric-RFID Platform Integration | Fuses facial recognition with baggage tracking for Lufthansa and Delta single-token journey capabilities. |
| Backward Integration into Motion Control | Captive production of industrial controllers reduces German supplier concentration vulnerability. |
| Greenfield Airport Framework Agreements | Noida and Navi Mumbai procurements enable specification influence without retrofit constraints. |
| Edge Computing Architecture Migration | Distributed kiosk intelligence reduces network latency for real-time security screening decisions. |
| Rail Station Pilot Expansion | Shanghai Hongqiao and London St Pancras intermodal check-in opens multimodal revenue streams. |
Research Methodology
Independent corroboration across airport procurement officers, airline technology executives, and baggage handling system integrators underwrites the qualitative findings. Primary fieldwork encompassed terminal operations directors, OEM engineering leads, and ground handling contract managers. Secondary validation drew from FAA Part 139 certification databases, IATA baggage tracking compliance filings, and EASA aerodrome design regulatory updates. Bottom-up equipment deployment tallies and top-down terminal modernization budget aggregates were cross-referenced for triangulation.
Comparable historical deployment cycles anchored the projection horizon against prior automation waves at major hub airports. Segmentation modeling spanned machine type, technology integration depth, application environment, and end-user procurement channel. CAGRs were derived from equipment unit forecasts weighted by average selling price trajectories. Industry-specific inputs included IATA Resolution 753 compliance deadline proximity and Bipartisan Infrastructure Law funding allocation patterns.
Regulatory enforcement delays, commodity price volatility in steel and aluminum, and biometric certification timeline extensions are the dominant revision risks. Forecasts reflect assumptions regarding airline capital commitment continuity and terminal authority technology refresh prioritization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Intelligent Remote Terminal Unit Market
Automation
Modular Laboratory Automation Market
Automation
Asia-Pacific Data Center Automation Market
Automation
Global Direct Mail Automation Software Market
Automation
Europe Laboratory Automation Market
Automation
Home Automation Market
Automation
Global Sales Force Automation (SFA) Market
Automation
CNC Controller Market
Automation
Global Smart Vending Machines Market
Automation
Middle East and Africa Workforce Management Market
Automation
Global Zig-Bee Automation Market
Automation
Service Delivery Automation (SDA) Market
Automation
Data Center Automation Market
Automation
Terminal Automation Systems Market
Automation
Global Database Automation Systems Market
Automation
Workload Automation Software Market