
 North America Home Automation Systems Market | 2026-2036
North America Home Automation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Home Automation Systems Market Intelligence
Whole-home integration standards are reorganizing competitive dynamics in North America. Honeywell International Inc. leverages its building-controls heritage to anchor commercial-to-residential crossover sales. ADT competes through monitored security bundles that extend into climate and lighting orchestration. Vivint controls its channel through direct-to-consumer installation fleets, sustaining recurring revenue density in the Sun Belt.
North America home automation systems encompass networked sensors, controllers, and actuators that manage lighting, security, climate, and energy loads through protocols such as Zigbee mesh networking and Z-Wave sub-GHz radio. These installations reduce operational expenditure for property owners while enabling utility demand-response participation. Security Systems currently dominates product-type revenue due to insurance-premium incentives and professional monitoring contracts. DIY Installation is the fastest-expanding channel, though Professional Installation still captures the margin pool in luxury residential and hospitality verticals where Crestron Electronics and Savant Systems specialize.
FCC Part 15 governs unlicensed radio emissions for Wi-Fi, Zigbee, and Z-Wave devices, while the U.S. Department of Energy and Natural Resources Canada set minimum efficiency thresholds that shape thermostat and load-controller specifications. CSA Group standards and UL certification requirements create compliance cost barriers that favor scaled manufacturers over import-only entrants. Stakeholders must monitor evolving state-level data-privacy statutes and utility interconnection rules that could fragment product certification requirements across provincial and state jurisdictions.
Market Dynamics
Net-zero building codes across U.S. states and Canadian provinces are forcing deep integration of climate, security, and energy management stacks into single orchestration layers, compressing vendor margins while elevating specification power for electrical contractors and systems integrators.
Growth Catalysts
- Utility demand-response programs:FERC Order 2222 aggregation rules enable residential battery and HVAC load participation in wholesale markets, creating recurring revenue pools for automation platforms in Texas and California.
- Z-Wave Long Range protocol:Sub-GHz mesh extension reaches detached garages and outdoor lighting without repeaters, unlocking whole-property coverage for suburban single-family developments in Arizona and Florida.
- Canada Greener Homes Grant:Federal rebates for smart thermostats and energy monitoring hardware accelerate retrofit adoption in Ontario and British Columbia beyond new-construction penetration rates.
Market Restraints
- Silicon supply concentration:Zigbee and Thread radio SoC fabrication depends on TSMC and Samsung foundry capacity in Taiwan and South Korea, exposing lead-time volatility for North American hardware vendors.
- Copper and lithium price swings:Battery-backed smart panels and load controllers face input cost pressure from commodity markets, compressing gross margins on energy storage-integrated SKUs.
- FCC Part 15 certification timelines:Unlicensed device approval queues at the FCC's Office of Engineering and Technology extend product launch windows by four to eight months for sub-GHz automation hardware.
Strategic Opportunities
- Midwest retrofit underpenetration:Aging housing stock in Illinois, Ohio, and Michigan lacks pre-wiring for smart systems, creating whitespace for wireless retrofit kits with battery-powered sensors.
- Matter protocol convergence:Thread and Wi-Fi unification under the Connectivity Standards Alliance specification collapses compatibility fragmentation, enabling single-app control across previously siloed device ecosystems.
- California Title 24 compliance mandates:2025 building efficiency standards require automated daylight harvesting and plug-load control in commercial and high-rise residential, opening specification channels for integrated lighting-HVAC platforms.
Industry Challenges
- Low-voltage electrician scarcity:Installation of PoE lighting and structured wiring panels requires certified technicians, and trade school pipeline gaps in Texas and Arizona constrain professional channel expansion.
- CSA Group and UL certification stacking:Dual safety and interoperability testing for Canadian and U.S. markets adds six-figure fixed costs per product line, disadvantaging mid-tier hardware entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Home Automation Systems Market |
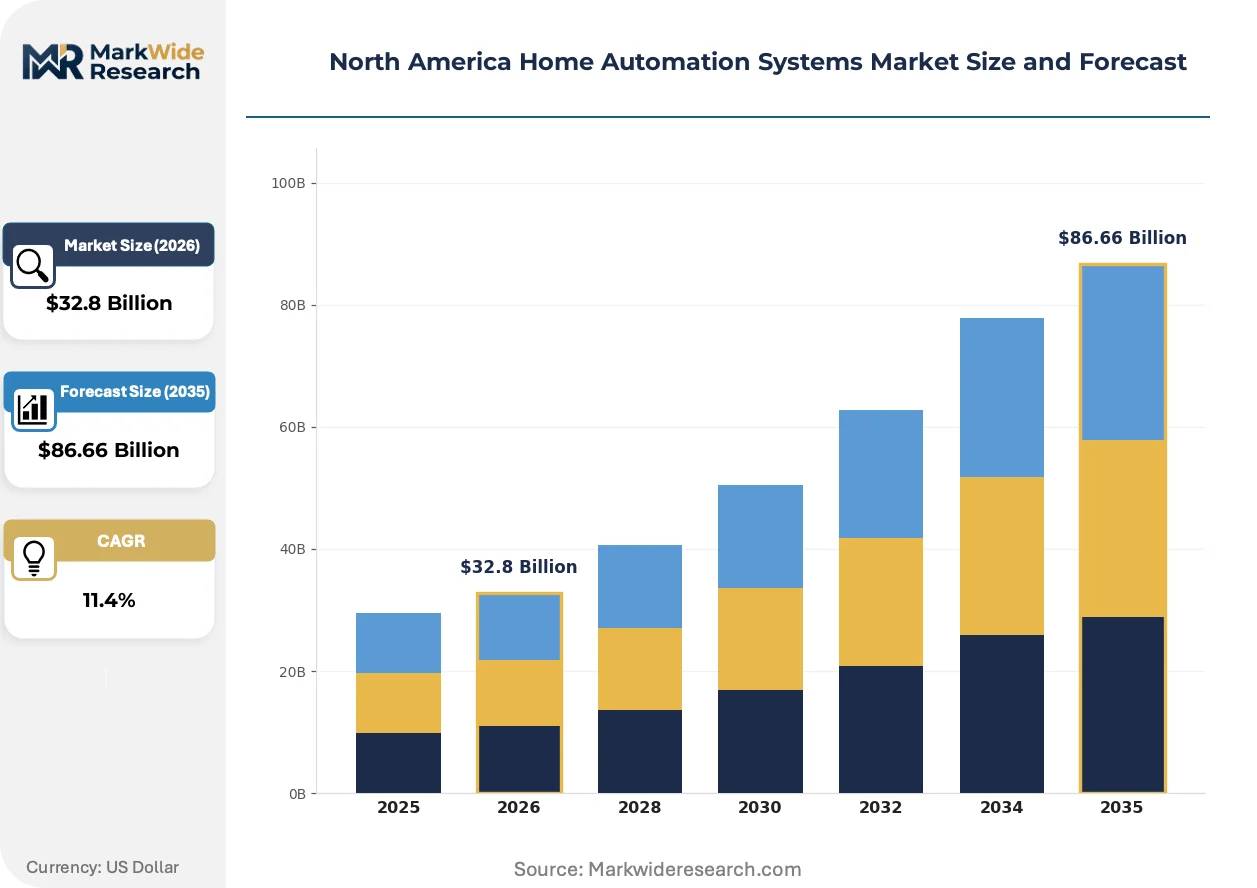
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $86.66 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Security Systems, Climate Control, Energy Management End User: Residential, Commercial, Industrial, Hospitality Technology: Wi-Fi, Bluetooth, Zigbee, Z-Wave Installation Type: Retrofit, New Construction, DIY, Professional |
| Companies Covered | Honeywell International Inc., ADT, Vivint, Control4 Corporation, Crestron Electronics, Lutron Electronics, Savant Systems, Johnson Controls International PLC, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Home Automation Systems Market Strategic Shifts & Innovations
Protocol unification and edge AI processing are collapsing the traditional hub-and-spoke architecture of residential automation, redistributing compute load toward endpoint devices and flattening vendor hierarchies.
Matter-over-Thread connectivity is fragmenting the smart home stack by enabling direct smartphone-to-device commissioning without proprietary bridges. Homebuilders in the Sun Belt are specifying Matter-certified hardware to reduce callback rates from interoperability failures. This fragmentation compresses margin for legacy hub manufacturers while elevating semiconductor vendors with certified radio stacks.
IRA residential clean energy credits are accelerating heat pump and battery storage adoption, forcing automation platforms to integrate with inverter APIs and utility time-of-use signals. The U.S. Department of Energy efficiency standards now require smart thermostat pre-installation in new federal housing. Equipment manufacturers are responding by certifying hardware to ENERGY STAR Most Efficient criteria to maintain specification status.
Subscription fatigue among millennial and Gen Z homebuyers is compressing the attach rate for monitored security bundles. DIY installation of unmonitored camera and sensor systems is displacing professional monitoring contracts in starter-home segments across Colorado and North Carolina. Channel preference divergence is most visible in new-construction versus resale housing verticals.
North America Home Automation Systems Market Segmentation
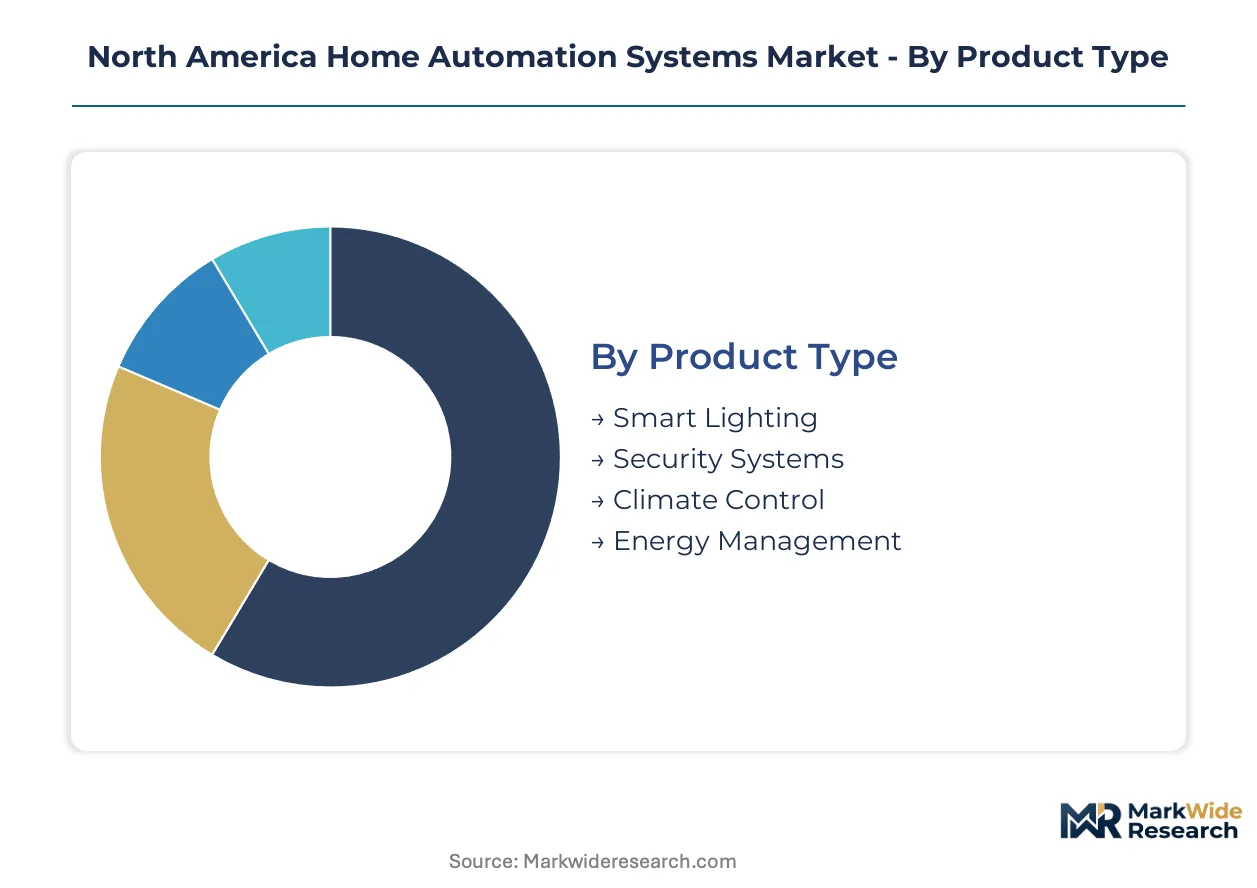
Segmentation in North American home automation reveals how protocol standards, installation labor availability, and building code variations create divergent growth corridors across product categories. Understanding these divisions exposes where utility incentives and builder specifications concentrate demand versus where wireless retrofit kits unlock aging housing stock.
Product Type:
Domestic demand concentrates in climate and security hardware tied to U.S. state energy codes and Canadian federal rebate programs, while export-oriented manufacturing of lighting controllers ships to Latin American and Caribbean markets from assembly facilities in Mexico.
- Smart Lighting:LED fixture controllers with daylight harvesting sensors and circadian dimming algorithms. Demand clusters in California and Ontario where Title 24 and provincial building codes mandate automated daylight response in new commercial and high-rise residential construction.
- Security Systems:Integrated camera, sensor, and monitoring platforms with cellular backup and professional dispatch. Revenue concentrates in Texas, Florida, and Arizona Sun Belt metros where insurance premium discounts for monitored systems drive builder specifications and retrofit attach rates.
- Climate Control:Smart thermostats and HVAC zone controllers with utility API integration.
- Energy Management:Whole-home load monitoring and battery inverter orchestration platforms.
Security Systems commands the established base. The steepest expansion runs through Energy Management.
End User:
Cost-tier stratification separates premium integrated stacks in luxury hospitality from mass-market DIY kits in starter residential, with commercial mid-market facing the sharpest budget pressure from net-zero compliance mandates.
- Residential:Single-family and multifamily installations spanning new construction pre-wiring and wireless retrofit deployments. Volume concentrates in U.S. Sun Belt states and Canadian provinces with active new housing starts and Greener Homes Grant eligibility.
- Commercial:Office, retail, and institutional buildings requiring centralized building management system integration. Demand is accelerating in California and British Columbia where automated plug-load control and daylight harvesting are code-mandated for energy compliance.
- Industrial:Warehouse and manufacturing facility automation for security perimeter and climate control.
- Hospitality:Hotel and resort guest room management systems with centralized energy and lighting orchestration.
Residential captures volume leadership. Commercial is climbing the fastest as code mandates harden.
Technology:
Protocol maturity curves separate legacy Wi-Fi and Bluetooth dominance in retrofit consumer devices from emerging Thread and Z-Wave Long Range adoption in new construction where mesh reliability and sub-GHz range justify specification.
- Wi-Fi:High-bandwidth IP-native connectivity for cameras, streaming devices, and cloud-dependent controllers. Ubiquitous in existing North American homes where router infrastructure eliminates gateway costs, though congestion and power consumption limit battery sensor applications.
- Zigbee:Mesh networking protocol operating in 2.4 GHz spectrum with self-healing topology. Established installed base in utility-deployed smart meters and thermostat programs across Ontario, Texas, and California creates specification inertia for compatible home devices.
- Bluetooth:Low-energy beacon and direct phone-to-device commissioning for setup and proximity automation.
- Z-Wave:Sub-GHz mesh protocol with Long Range extension for whole-property coverage without repeaters.
Wi-Fi holds the installed base. Z-Wave is gaining share fastest through new construction specification.
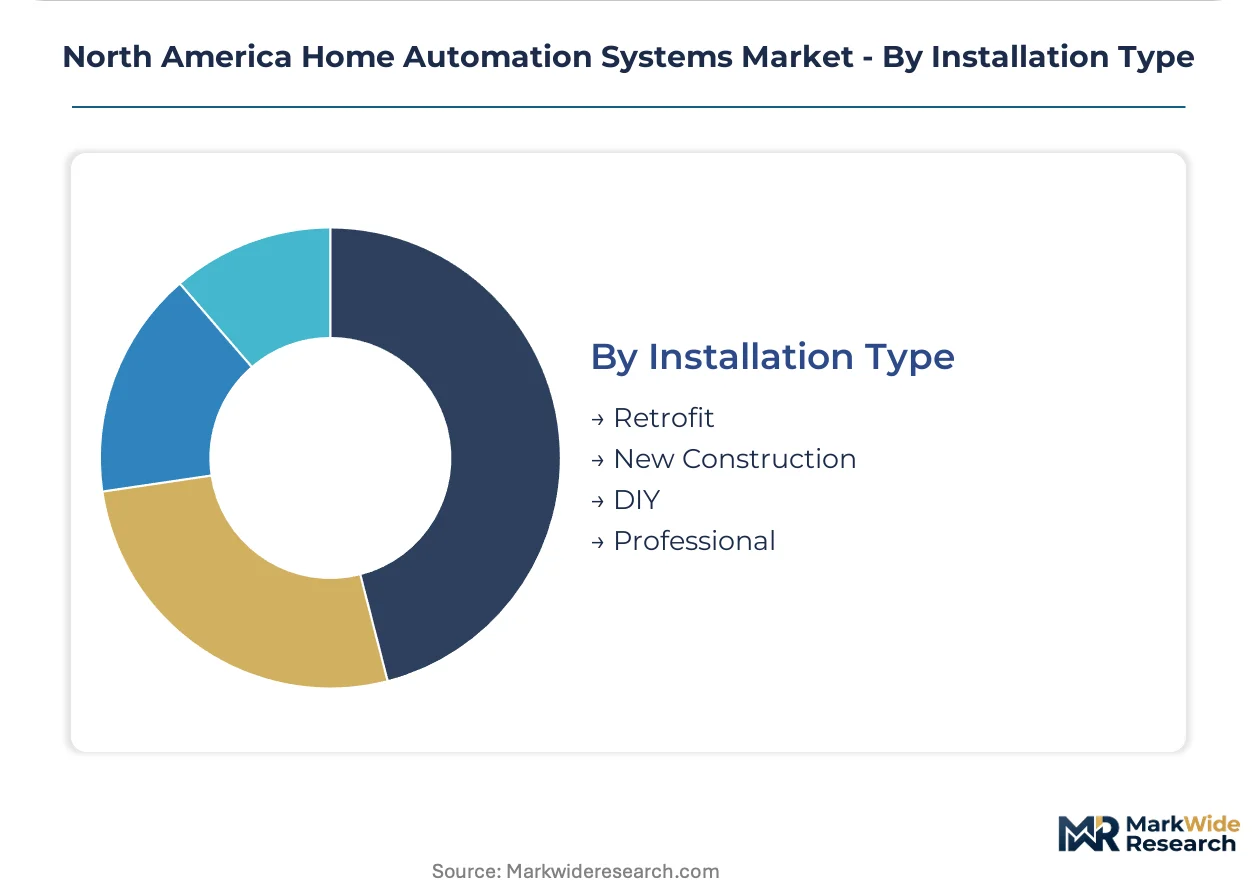
Installation Type:
Channel preference splits sharply by housing vintage: new construction favors professional structured wiring and PoE lighting, while resale and aging Midwest stock drive wireless DIY retrofit adoption.
- DIY:Consumer-purchased wireless sensors, cameras, and hubs with smartphone-guided commissioning. Expanding most quickly in Colorado, North Carolina, and Michigan where millennial and Gen Z buyers reject monitored security subscriptions and favor unmonitored camera systems.
- Professional:Certified low-voltage electrician and systems integrator deployment of structured wiring, PoE lighting panels, and centralized control racks. Margin concentrates in luxury residential and hospitality verticals across Arizona, Florida, and Texas where callback liability drives builder preference for certified installation.
- Retrofit:Wireless and battery-powered hardware upgrades to existing housing stock without structural modification.
- New Construction:Pre-wired infrastructure and integrated platform specification during building phase.
Professional installation captures margin density. DIY is expanding most quickly through wireless kit adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly of automation hardware concentrates in Mexican border states serving U.S. distribution channels, while specification power and software development cluster in American Sun Belt metros and Canadian technology corridors.
United States
New housing starts in Arizona, Florida, and Texas drive builder-grade automation specifications for climate and security stacks. FERC Order 2222 enables residential battery aggregation in Texas and California wholesale markets. Dallas-Fort Worth and Phoenix anchor installer network expansion for professional deployment channels.
Canada
Federal Greener Homes Grant rebates accelerate smart thermostat retrofits beyond new-construction penetration in Ontario and British Columbia. Natural Resources Canada efficiency standards shape hardware specifications for cross-border product lines. Toronto and Vancouver concentrate systems integrator capacity for high-rise residential and commercial verticals.
Mexico
Maquiladora facilities in Baja California and Chihuahua assemble lighting controllers and sensor hardware for export to U.S. and Latin American markets. Proximity to California and Texas distribution hubs reduces logistics lead times for Sun Belt builder supply chains. Tijuana and Ciudad Juárez host contract manufacturing for mid-tier automation OEMs.
North America Home Automation Systems Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Premium integration specialists command specification power in luxury residential and hospitality verticals through certified installation networks. Mass-market security and climate providers compete on recurring revenue density and utility partnership scale. Strategic moves concentrate on protocol certification stacking and direct-to-consumer channel expansion.
Among building-controls heritage conglomerates, Honeywell International Inc. and Johnson Controls International PLC occupy positions spanning commercial-to-residential crossover sales. Within the monitored security bundle tier, ADT exemplifies recurring revenue models extending into climate and lighting orchestration. Vivint sits within the direct-to-consumer installation archetype, controlling channel density through owned technician fleets in Sun Belt markets.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| ADT |
| Vivint |
| Control4 Corporation |
| Crestron Electronics |
| Lutron Electronics |
| Savant Systems |
| Johnson Controls International PLC |
| Schneider Electric SE |
| Others |
Cost & Logistics Intelligence
Sixteen-week lead times for Zigbee and Thread radio SoCs from TSMC and Samsung foundries compress margin buffers for North American hardware vendors while elevating pricing power for semiconductor suppliers with certified Matter stacks. Inventory cycles in this market tether pricing flexibility to foundry allocation windows and copper-lithium commodity curves.
Pricing Analysis
FCC Part 15 certification requirements dictate the pricing tier structure across professional installation, DIY retrofit, and builder-grade hardware segments. Three-tier pricing structure across premium, standard, and economy levels separates Crestron-certified integration racks from Vivint-monitored bundles and Amazon-basics sensor kits. Price differentiation hinges on UL certification grade and after-sales service bundling. Cost compression in the DIY tier is intensifying because millennial buyers reject monitored security subscriptions. Starter-home segments in Colorado and North Carolina exhibit the highest price sensitivity, while luxury residential in Arizona and Florida tolerates premium positioning.
Supply Chain Analysis
Port congestion on the Los Angeles-Long Beach corridor and container availability swings on the Trans-Pacific lane elevate inbound logistics costs for Mexican maquiladora assembly operations. Hardware fabrication concentrates in Taiwan, South Korea, and China for radio SoCs, with Mexico and Vietnam hosting final assembly of lighting controllers and sensor housings. Raw material dependencies span lithium carbonate for battery-backed panels, copper for PoE infrastructure, and rare earth elements for actuator motors. Single-source vulnerability in TSMC's advanced node capacity threatens production continuity. Distribution runs through Sun Belt builder supply chains and big-box retail channels for DIY kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Voice-activated ambient computing and generative AI assistants threaten to displace dedicated home automation hubs, forcing incumbents to defend installed-base stickiness through deeper energy-utility integration.
For Market Incumbents: Compound specification power in California Title 24 compliance channels by certifying integrated lighting-HVAC platforms to ENERGY STAR Most Efficient criteria. Deepen backward integration into battery inverter API development to capture IRA-driven residential storage adoption. Defend against DIY displacement by embedding utility demand-response revenue sharing into monitored security bundles.
For New Entrants and Emerging Players: Post-installation commissioning and Matter-certified troubleshooting services represent the service-layer gap where incumbents under-serve Midwest retrofit markets. Wireless retrofit kits for aging housing stock in Illinois, Ohio, and Michigan offer the most penetrable white space. Partner with electrical contractor associations in Texas and Arizona to bypass Vivint's owned-fleet channel control.
For Investors and Strategic Acquirers: Carve-out targets emerge from building-controls conglomerates seeking to divest residential automation divisions amid commercial-to-residential margin compression. Five-to-ten-year viability hinges on protocol certification stacking economies and utility partnership density. Watch FERC Order 2222 implementation velocity in Texas and California as the inflection signal for residential battery aggregation revenue pools.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | CSA Group certification collapses compatibility fragmentation for cross-platform device control. |
| Utility API Integration | FERC Order 2222 participation unlocks recurring revenue from Texas and California wholesale markets. |
| Direct-to-Consumer Channel Expansion | Owned installation fleets in Sun Belt metros bypass big-box retail margin dilution. |
| Backward Integration into Radio Stacks | In-house Thread and Z-Wave semiconductor development reduces TSMC allocation dependency. |
| Retrofit Wireless Kit Development | Battery-powered sensor platforms unlock aging Midwest housing stock without structural modification. |
Research Approach
Initial hypotheses were tested against primary input from low-voltage electrical contractors, systems integrators, utility demand-response program managers, and homebuilder purchasing directors, and refined through secondary validation against FCC equipment authorization databases, U.S. Department of Energy appliance efficiency filings, CSA Group certification registries, and utility interconnection rulemakings. Bottom-up channel volume estimates triangulated with top-down construction spending allocations across the analysis window.
Variance decomposition across product type, installation channel, protocol technology, and end-user vertical shaped the analytical framework. CAGRs derived from housing start projections, utility incentive program budgets, and equipment replacement cycles. Forecast inputs incorporated Z-Wave Long Range adoption curves, Matter protocol penetration assumptions, and state-level net-zero code implementation schedules.
Underlying assumptions cover stable copper-lithium commodity bands and continued TSMC foundry allocation to industrial IoT radio SoCs, with deviation risk concentrated in FCC certification queue extensions and state-level data-privacy statute fragmentation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Asia-Pacific Automated Liquid Handling Market
Automation
North America Data Center Automation Market
Automation
Digital Process Automation Market
Automation
Elevator Control Market
Automation
Hyperautomation Market
Automation
Indonesia Automation and Control System Market
Automation
Global Warehouse Barcode System Market
Automation
Workflow Automation Market
Automation
Laboratory Benchtop Automation Market
Automation
Industrial Vending Machines Market
Automation
Window Automation Market
Automation
Global Process Automation and Instrumentation Market
Automation
AR Automation Market
Automation
Distribution Automation Solutions Market
Automation
Automation Testing Market
Automation
Automatic Message Handling System Market