
 Chocolate Malt Drink Market | 2026-2036
Chocolate Malt Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Malt Drink Market Analysis
Barley malt extract is repositioning cost structures as manufacturers substitute partially processed cocoa solids with malt-forward formulations to offset raw material volatility. Nestle leverages its dairy sourcing networks to secure consistent milk powder supply chains across tropical markets. Ovaltine (Associated British Foods) anchors its competitive stance through heritage brand equity in European and Asian retail channels. Mars competes aggressively in the ready-to-drink segment via convenience-store placement and single-serve packaging formats.
A chocolate malt drink is a beverage formulation combining roasted malted barley or wheat powder with cocoa solids, milk derivatives, and sweeteners, typically reconstituted with water or milk to deliver a caloric energy source with distinctive roasted-caramel flavor notes. Industrial production employs spray-drying or roller-drying of malt slurries to achieve shelf-stable powder with controlled moisture content below five percent. The powdered mix segment dominates volume due to lower logistics costs and extended ambient shelf life in emerging markets. Ready-to-drink formats command premium positioning in supermarket and convenience store channels where chilled distribution infrastructure supports higher margin capture.
The US FDA governs nutritional labeling and health claim substantiation for malt beverages positioned with functional benefits, while India's FSSAI mandates explicit malt content disclosure and prohibits misleading growth claims in children's products. EFSA in Europe evaluates novel ingredient approvals for fortified variants seeking CE marking equivalence across member states. Stakeholders must monitor evolving sugar taxation regimes and clean-label certification requirements that will determine which formulations maintain retail access and price positioning.
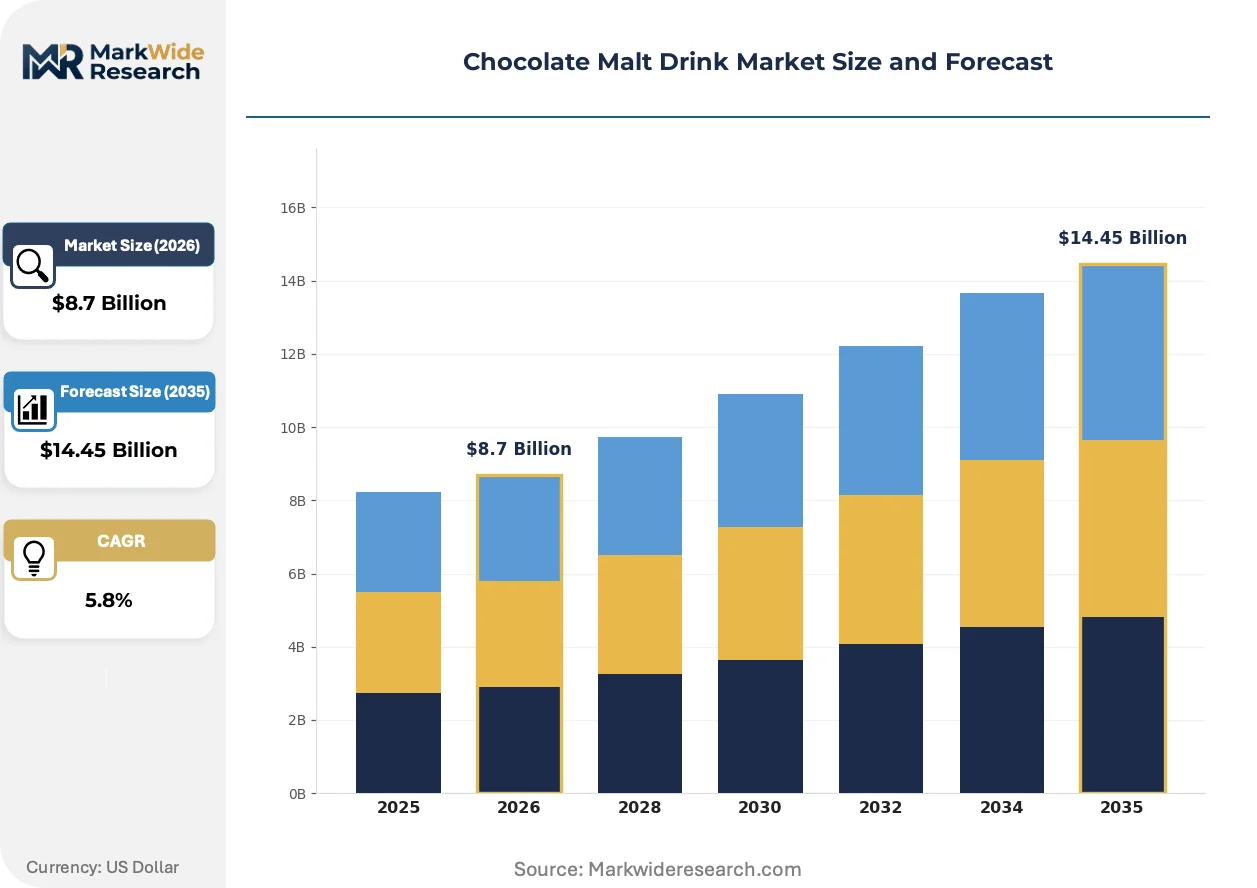
Market Dynamics
India's FSSAI labeling mandates are forcing rapid reformulation across malt-based health drinks, compressing product development cycles while manufacturers scramble to maintain shelf positioning in one of the category's highest-volume markets.
Growth Catalysts
- Sports Nutrition Pivot:Protein-fortified formulations are capturing gym-goers and amateur athletes as dedicated recovery beverages, expanding the consumer base beyond traditional breakfast occasions.
- FSSAI Compliance Window:India's tightened disclosure requirements for malt content are accelerating clean-label innovation, rewarding early reformulators with retail preferential placement.
- Spray-Drying Advancement:Controlled moisture extraction below five percent is extending ambient shelf life, enabling deeper penetration into Southeast Asian convenience channels with limited cold-chain infrastructure.
Market Restraints
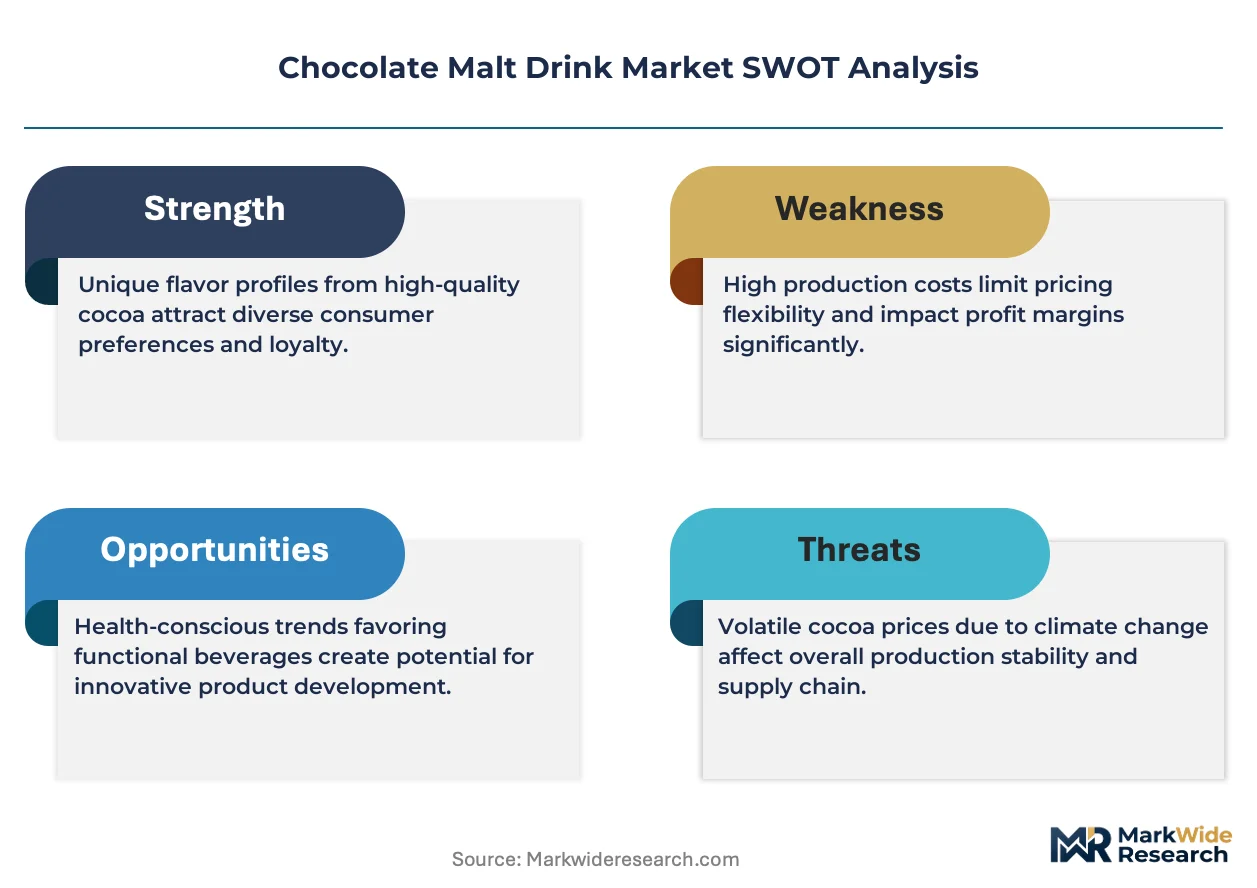
- Cocoa Solid Volatility:Raw cocoa price swings are compressing margins for manufacturers locked into long-term retail price agreements with supermarket chains.
- Milk Powder Concentration:Tropical market supply chains depend heavily on New Zealand and Australian dairy cooperatives, creating vulnerability to El Niño-driven production shortfalls.
- Sugar Taxation Escalation:Thailand, Philippines, and Indonesia have implemented tiered sweetener levies that directly erode the value proposition of traditional high-malt formulations.
Strategic Opportunities
- Vietnam Rural Distribution:Powdered mix penetration remains below thirty percent in Mekong Delta provinces, offering first-mover advantage through sachet-format entry pricing.
- Clean-Label Certification:EU Organic and Rainforest Alliance credentials are unlocking premium shelf space in German and Dutch supermarket chains that actively delist conventional alternatives.
- E-Commerce Subscription Models:Direct-to-consumer replenishment platforms are bypassing traditional wholesale markups in South Korean urban markets, capturing lifetime value through auto-ship malt deliveries.
Industry Challenges
- Reformulation Talent Scarcity:Food technologists with dual expertise in malt biochemistry and sugar-reduction chemistry command premium compensation, constraining mid-tier manufacturer R&D bandwidth.
- Chilled Distribution Capex:Ready-to-drink margin capture requires refrigerated last-mile investment that exceeds the balance sheet capacity of regional Southeast Asian bottlers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Malt Drink Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Mix, Ready-to-Drink, Liquid Concentrate, Carbonated Beverage Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores End User: Children, Adults, Sports Enthusiasts, Fitness Fans Packaging Type: Box, Bottle, Tetra Pak, Sachet |
| Companies Covered | Mars, Ferrero, Nestle, Monarch Beverages, Ovaltine (Associated British Foods), Mondelez International, Hershey, United Brands, Coca-Cola, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Malt Drink Market Emerging Trajectories
Automation of production lines and algorithmic quality control are compressing batch-to-batch variation while regulatory disclosure requirements and shifting procurement preferences reshape competitive positioning.
Near-infrared spectroscopy is automating real-time moisture and protein content verification during spray-drying operations. Contract manufacturers in Malaysia and Thailand are adopting these systems to meet Nestle and Ovaltine audit standards. This technology is automating quality assurance labor, reducing headcount-dependent bottlenecks that previously constrained output scaling during seasonal demand spikes.
REACH registration requirements for novel emulsifiers and stabilizers are extending ingredient approval timelines for European fortification projects. EFSA novel food assessments now average fourteen months for probiotic-enhanced malt variants. Ready-to-drink functional lines targeting German pharmacy channels face the steepest compliance burden, with several brands withdrawing reformulation plans rather than absorbing regulatory delay costs.
Buyer concentration among Southeast Asian e-commerce platforms is consolidating procurement leverage. Shopee and Lazada now mandate exclusive flavor variants and promotional bundling terms that erode manufacturer margin. Indonesian and Vietnamese household purchasers have shifted toward bulk powder purchases during platform mega-sale events, compressing traditional grocery channel volume and forcing distributors to absorb return-logistics costs for expired promotional stock.
Chocolate Malt Drink Market Segmentation
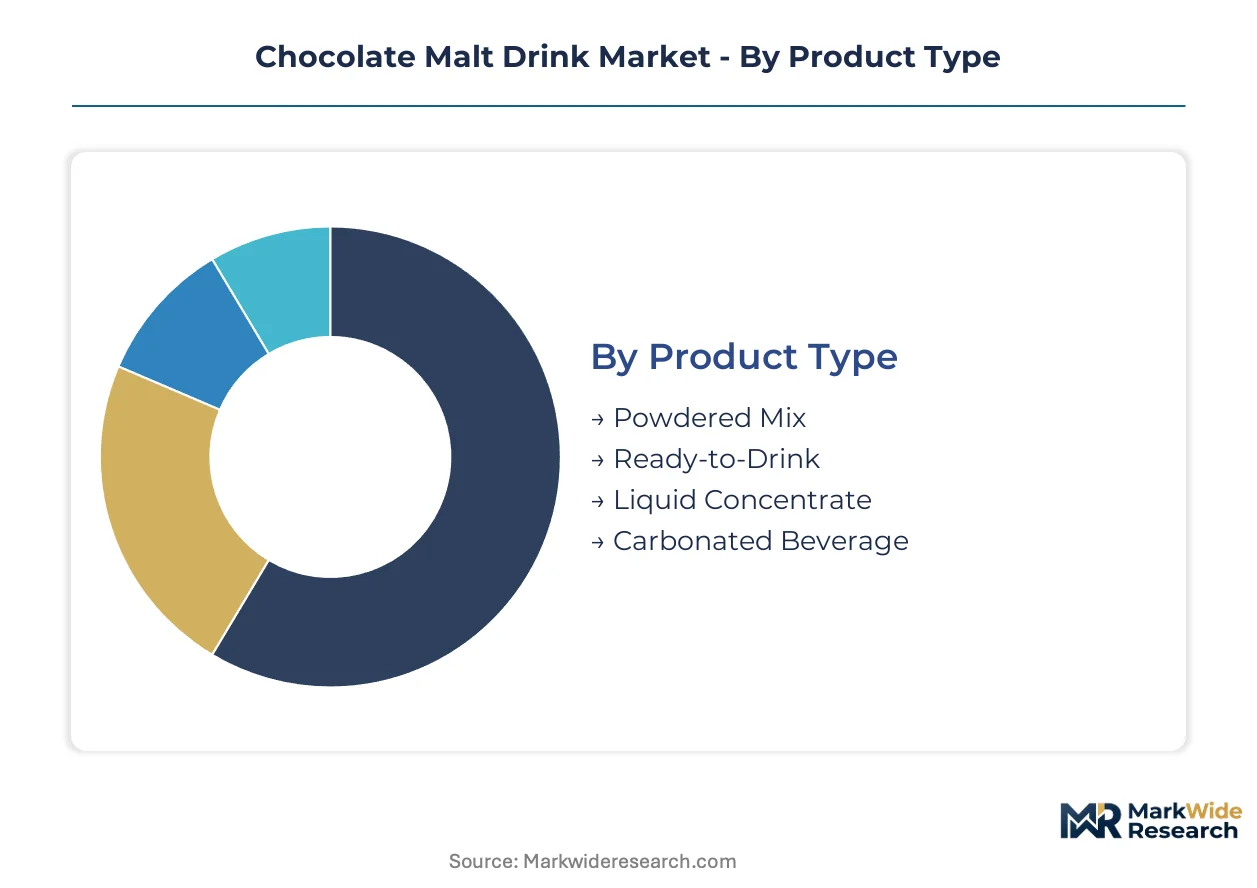
Segmentation in chocolate malt drinks reveals how formulation choices, packaging economics, and channel infrastructure determine which consumer occasions manufacturers can profitably serve. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning across tropical and temperate markets.
Product Type:
Standalone powdered formulations dominate household pantry penetration, while embedded ready-to-drink systems require chilled infrastructure but capture impulse purchase occasions.
- Powdered Mix:Spray-dried malt slurries with moisture content below five percent deliver extended ambient shelf life. Demand concentrates in Southeast Asian markets where cold-chain gaps persist and household bulk purchasing reduces per-serving cost.
- Ready-to-Drink:UHT-processed liquid formulations in aseptic packaging command premium positioning through convenience-store placement. Single-serve formats in South Korean and Japanese urban markets capture commuter breakfast occasions where preparation time constraints override price sensitivity.
- Liquid Concentrate:Reduced-water formulations requiring dilution prior to consumption occupy niche foodservice applications in institutional catering and quick-service restaurant fountain systems.
- Carbonated Beverage:Malt-flavored effervescent variants target youthful demographics in Latin American markets where carbonation signals refreshment and differentiates from traditional chocolate milk positioning.
Powdered Mix leads volumes today; Ready-to-Drink is gaining share fastest.
Distribution Channel:
Channel selection determines margin capture through markup structures and promotional control, with cost tiers separating high-service specialty formats from high-volume supermarket negotiations.
- Supermarkets:Multi-brand shelf facings in hypermarket chains drive household stock-up purchases. Slotting fee burdens in Thai and Indonesian retail conglomerates compress net margins for secondary brands lacking scale leverage.
- Convenience Stores:Ready-to-drink placement in 7-Eleven and FamilyMart networks across Taiwan and Japan captures immediate consumption demand. Chilled cabinet access fees and strict rotation requirements favor suppliers with dedicated route-to-market infrastructure.
- Online Retail:Shopee and Lazada consolidation in Indonesia and Vietnam shifts volume toward bulk powder purchases during promotional mega-events. Subscription auto-ship models in South Korea bypass traditional wholesale markups.
- Specialty Stores:Pharmacy channel positioning in Germany and Netherlands requires EFSA-compliant health claims and organic certification credentials that exclude conventional formulations.
Supermarkets retain volume leadership; Online Retail is expanding most quickly.
End User:
Customer type segmentation separates occasional breakfast consumers from high-frequency sports nutrition users with distinct formulation requirements and price elasticity profiles.
- Children:Fortified variants with vitamin and mineral additions target parental purchase decisions. India's FSSAI prohibition on misleading growth claims has forced reformulation away from explicit height-promotion positioning.
- Adults:Traditional breakfast occasion consumption persists in European heritage markets where Ovaltine and similar brands retain generational loyalty through nostalgic brand equity.
- Sports Enthusiasts:Protein-fortified formulations with 15-20g protein per serving capture gym-goer recovery demand. Amateur athlete segments in Australia and South Korea accept price premiums for functional positioning.
- Fitness Fans:Sugar-reduced and clean-label variants target calorie-conscious consumers in German and Dutch markets where sugar taxation and organic certification requirements filter conventional formulations from premium shelf space.
Adults maintain the largest installed base; Sports Enthusiasts show the steepest expansion trajectory.
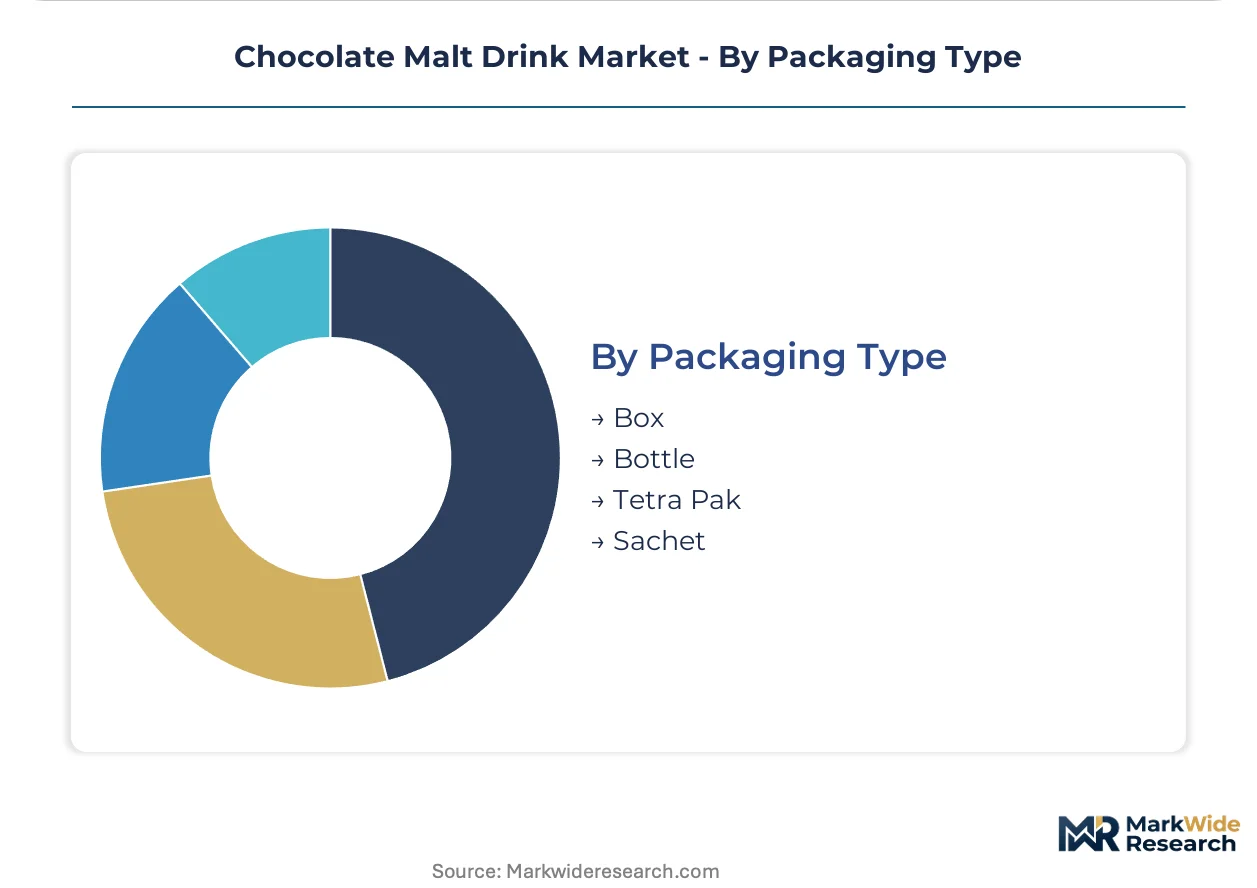
Packaging Type:
Packaging economics align with volume scale and distribution reach, with material choices determining shelf-life extension and logistics cost structures across ambient and chilled supply chains.
- Box:Paperboard cartons for powdered mix formats optimize pallet density in warehouse distribution. Retail-ready case packaging reduces in-store labor for supermarket replenishment.
- Bottle:PET and glass formats for ready-to-drink lines support resealability and brand differentiation through shape design. Deposit-return schemes in German retail add reverse logistics complexity.
- Tetra Pak:Aseptic carton systems enable ambient distribution for liquid concentrates and ready-to-drink variants in Southeast Asian markets with limited refrigeration penetration.
- Sachet:Single-serve foil pouches at entry price points target rural Vietnamese and Indonesian households with irregular purchasing power and trial-size preferences.
Box and Tetra Pak dominate current shipment volumes; Sachet formats are climbing fastest in emerging market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asian manufacturing clusters dominate chocolate malt drink production, with spray-drying facilities concentrated in Malaysia and Thailand serving export demand across tropical markets. India's regulatory tightening and Vietnam's rural penetration gaps are reshaping competitive entry strategies.
India
FSSAI labeling mandates are accelerating clean-label reformulation among domestic manufacturers. The regulator now prohibits misleading growth claims in children's products, forcing portfolio repositioning. Maharashtra's Mumbai-Pune industrial corridor hosts the largest concentration of malt processing plants, where contract manufacturers are investing in near-infrared spectroscopy systems to meet audit standards.
Vietnam
Powdered mix penetration remains below thirty percent in Mekong Delta provinces, creating first-mover opportunities through sachet-format entry pricing. The country's Ministry of Health has implemented tiered sugar taxation that erodes margins on traditional high-malt formulations. Ho Chi Minh City anchors national distribution networks, with regional bottlers struggling to fund refrigerated last-mile infrastructure for ready-to-drink variants.
Thailand
Sugar taxation escalation has compressed value propositions for conventional formulations, pushing manufacturers toward reduced-sugar recipes. The Thai Food and Drug Administration enforces strict nutritional labeling for malt-based health drinks positioned with functional benefits. Bangkok's surrounding provinces concentrate spray-drying capacity serving ASEAN export markets, with Shopee and Lazada consolidation shifting volume toward promotional mega-events.
Germany
EFSA novel food assessments averaging fourteen months are delaying probiotic-enhanced malt variant launches. REACH registration requirements for emulsifiers extend ingredient approval timelines for fortification projects. The North Rhine-Westphalia region hosts pharmacy-channel distributors demanding EU Organic and Rainforest Alliance credentials that exclude conventional formulations from premium shelf space.
United States
FDA nutritional labeling governs health claim substantiation for protein-fortified sports nutrition positioning. Sports enthusiasts represent the fastest-expanding end-user segment as gym-goer recovery demand shifts consumption beyond breakfast occasions. California's Los Angeles-Long Beach logistics cluster handles bulk milk powder imports from New Zealand and Australian dairy cooperatives, creating vulnerability to El Niño-driven production shortfalls.
Chocolate Malt Drink Market Vendor Landscape
Global majors compete with regional champions across formulation expertise and channel infrastructure, creating a tiered structure where heritage brand equity and dairy sourcing networks determine shelf access. Three archetypes dominate: multinational CPG conglomerates with integrated dairy supply chains, regional beverage specialists with convenience-store route density, and private-label contract manufacturers serving platform-dependent e-commerce channels. Competitive moves concentrate on clean-label reformulation racing and chilled distribution partnerships.
Among heritage-positioned specialists, Ovaltine (Associated British Foods) and Nestle occupy positions where generational brand loyalty and tropical market dairy sourcing networks create defensive moats. Mars exemplifies the convenience-store aggressive placement archetype through single-serve packaging formats. These three companies represent distinct strategic vectors—heritage equity, supply chain control, and impulse-channel dominance—that other competitors must match or circumvent.
| Leading Market Players |
|---|
| Mars |
| Ferrero |
| Nestle |
| Monarch Beverages |
| Ovaltine (Associated British Foods) |
| Mondelez International |
| Hershey |
| United Brands |
| Coca-Cola |
| Others |
Supply Flow & Price Mechanics
ICCO cocoa futures volatility cascades through chocolate malt drink manufacturing into three distinct pricing strata: premium ready-to-drink lines absorbing margin compression, standard powdered mixes locked into supermarket promotional cycles, and economy sachets vulnerable to El Niño-driven milk powder spikes.
Pricing Analysis
Input-cost pass-through operates asymmetrically across the category. Powdered mix manufacturers face compressed margins when locked into annual retail price agreements while cocoa solid and milk powder costs fluctuate. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-compliant organic formulations from conventional breakfast-positioned brands and rural-market sachet entries. Pricing pressure stems from Thailand's tiered sugar taxation eroding value propositions on traditional high-malt recipes. Economy sachet buyers in Vietnamese Mekong Delta provinces exhibit highest price sensitivity; sports nutrition consumers in South Korean urban markets accept functional premiums.
Supply Chain Analysis
India's FSSAI local-content disclosure mandates are accelerating domestic malt processing investment, reshaping sourcing patterns away from import-dependent formulations. Spray-drying capacity concentrates in Malaysia, Thailand, and Maharashtra's Mumbai-Pune corridor serving ASEAN and Indian demand. Raw material dependencies center on New Zealand and Australian milk powder cooperatives, Ghana and Ivory Coast cocoa solids, and Australian barley malt. Supply chain risk manifests as El Niño-driven dairy production shortfalls creating single-source vulnerability for tropical market formulations. Distribution runs through Shopee and Lazada consolidation in Indonesia and Vietnam alongside traditional supermarket and convenience store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chocolate malt drinks function as a stable compounder anchored by generational breakfast rituals in Asian and European markets, with protein-fortification expansion into sports nutrition providing incremental growth vectors.
For Market Incumbents: Anticipate regulatory tightening by accelerating clean-label certification investments ahead of FSSAI and EFSA disclosure mandates. Secure captive dairy supply through backward integration into New Zealand or Australian milk powder sourcing networks. Defensive positioning requires near-infrared spectroscopy deployment across spray-drying lines to meet Nestle and Ovaltine audit standards and maintain contract manufacturing relationships. For New Entrants and Emerging Players: Algorithmic quality control systems offer technology-first wedge into mid-tier contract manufacturing serving e-commerce platform private labels. Vietnam's Mekong Delta provinces present the most penetrable geography with powdered mix penetration below thirty percent. Sachet-format entry pricing combined with Shopee-exclusive flavor variants captures rural household trial behavior. For Investors and Strategic Acquirers: Asymmetric upside sits with regional spray-drying specialists possessing FSSAI-compliant facilities and existing Nestle or Ovaltine audit certifications. Long-term viability rests on reformulation capability spanning malt biochemistry and sugar-reduction chemistry. Watch for FSSAI enforcement actions against growth-claim violations as inflection indicator for portfolio repositioning urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FSSAI and EFSA disclosure mandates reward early compliance with retail preferential placement. |
| Spray-Drying Automation | Near-infrared spectroscopy adoption meets Nestle audit standards and compresses batch variation. |
| Rural Sachet Distribution | Mekong Delta entry pricing captures Vietnamese households below thirty percent powdered mix penetration. |
| Sports Nutrition Positioning | Protein-fortified variants capture South Korean gym-goer recovery demand beyond breakfast occasions. |
| E-Commerce Subscription Models | Auto-ship platforms bypass wholesale markups and capture lifetime value in South Korean urban markets. |
Methodological Framework
Multiple input streams — regulatory filing analysis, trade customs databases, and executive interview panels — were reconciled to construct demand and supply estimates. Primary engagement spanned brand managers at multinational CPG conglomerates, category buyers at Thai and Indonesian retail conglomerates, spray-drying plant managers in Malaysia and Thailand, and FSSAI regulatory affairs specialists. Secondary validation drew from FSSAI notification gazettes, EFSA novel food assessment registers, ICCO cocoa market reports, and Nielsen retail audit data across Southeast Asian markets. Bottom-up volume modeling and top-down expenditure reconciliation were cross-checked for consistency.
Historical shipment trajectories were cross-referenced against executive panel input to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end-user occasion, and packaging format alongside regional regulatory cluster differentiation. CAGRs were derived from curve-fitting approaches applied to normalized volume and value series. Industry-specific forecast inputs incorporated El Niño cycle projections affecting New Zealand dairy output and FSSAI enforcement intensity timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sugar taxation escalation trajectories in Southeast Asia and chilled infrastructure investment rates for ready-to-drink expansion. Forecasts reflect documented assumptions regarding regulatory enforcement pacing and commodity price cycle phases. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Juice Concentrates Market
Beverages
Asia-Pacific Probiotic Drinks Market
Beverages
North America Juices Market
Beverages
GCC Coconut Water Market
Beverages
Blenders Market
Beverages
Botanical Infused Beverages Market
Beverages
Europe Ready-To-Drink Beverages Market
Beverages
Ready to Drink Margarita Market
Beverages
Germany Probiotic Drinks Market
Beverages
Sparkling Water Machine Market
Beverages
Hydrogen Water Bottle Market
Beverages
Plant-Based Energy Drink Market
Beverages
Global Bottled Water Market
Beverages
Fruit Vinegar Market
Beverages
Enzyme-Enabled Cold-Brew Concentrates Market
Beverages
Commercial Drink Mixers Market