
 Recovery Drinks Market | 2026-2036
Recovery Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Recovery Drinks Market Analytics
Subscription-based replenishment programs is recalibrating how recovery drinks reach repeat buyers. Abbott Nutrition leverages its clinical nutrition heritage to anchor hospital and rehabilitation channel access. PepsiCo Inc. competes through mass retail distribution scale and sports sponsorship integration. Glanbia PLC specializes in whey protein sourcing and sports nutrition ingredient supply, sustaining premium positioning in the athlete segment.
Recovery drinks are formulated beverages delivering macronutrients, electrolytes, or bioactive compounds to accelerate physiological restoration after exertion, with typical formulations specifying protein loads between 15-30 grams per serving or electrolyte concentrations matching sweat sodium losses. Protein shakes occupy the largest revenue pool due to established gym culture penetration, while electrolyte drinks represent the fastest-expanding category as endurance sports participation broadens beyond competitive athletes to casual fitness participants.
The FDA governs health claim substantiation and nutrient content declarations for functional beverages sold in the United States, while the EFSA enforces similar evidentiary standards across European markets, and both frameworks directly determine which performance claims brands can deploy in consumer messaging. The USDA's organic certification program and the Non-GMO Project verification standard create parallel compliance pathways that premium brands increasingly pursue for shelf differentiation. Stakeholders must monitor how evolving clean-label requirements and sugar taxation proposals reshape acceptable ingredient palettes and pricing architecture.
Market Dynamics
Subscription-based replenishment programs are recalibrating how recovery drinks reach repeat buyers, compressing traditional retail cycles while demanding precision in amino acid profile certification from contract manufacturers.
Growth Catalysts
- Certified amino acid specifications:Professional sports teams and collegiate athletic programs now mandate post-workout beverages with verified amino acid profiles, creating procurement standards that filter down to consumer tiers.
- FDA nutrition labeling updates:The FDA's revised disclosure requirements for functional beverages are forcing formulation transparency that premium brands leverage for shelf differentiation against mass-market alternatives.
- Gym culture density:United States gym penetration rates sustain the highest sports nutrition retail density globally, anchoring protein shake consumption in established fitness routines.
Market Restraints
- Whey protein input volatility:Dairy commodity price swings directly compress margin structures for protein-dominant formulations, particularly affecting mid-tier brands without backward integration into ingredient supply.
- Supply concentration in specialized isolates:Premium whey protein isolate production concentrates among a limited set of European and North American processing facilities, creating geographic vulnerability in ingredient sourcing.
- Sugar taxation proposals:Pending state-level sugar taxation legislation in multiple US jurisdictions threatens acceptable ingredient palettes for flavored recovery formulations.
Strategic Opportunities
- Electrolyte category expansion:Endurance sports participation broadening beyond competitive athletes to casual fitness participants in Germany and Australia creates whitespace for sodium-matched sweat-replacement formulations.
- Clean-label certification stacking:The USDA organic program combined with Non-GMO Project verification enables dual-pathway compliance that commands pricing premiums in natural retail channels.
- Hospital and rehabilitation channels:Clinical nutrition heritage credentials unlock institutional procurement contracts for medical-grade recovery formulations in post-surgical and physical therapy settings.
Industry Challenges
- Formulation scientist scarcity:The intersection of sports nutrition science and beverage engineering requires specialized talent pools that remain thin across contract manufacturing networks.
- Clean-label compliance timelines:EFSA evidentiary standards for health claim substantiation demand extended documentation periods that delay European market entry for novel bioactive ingredients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recovery Drinks Market |
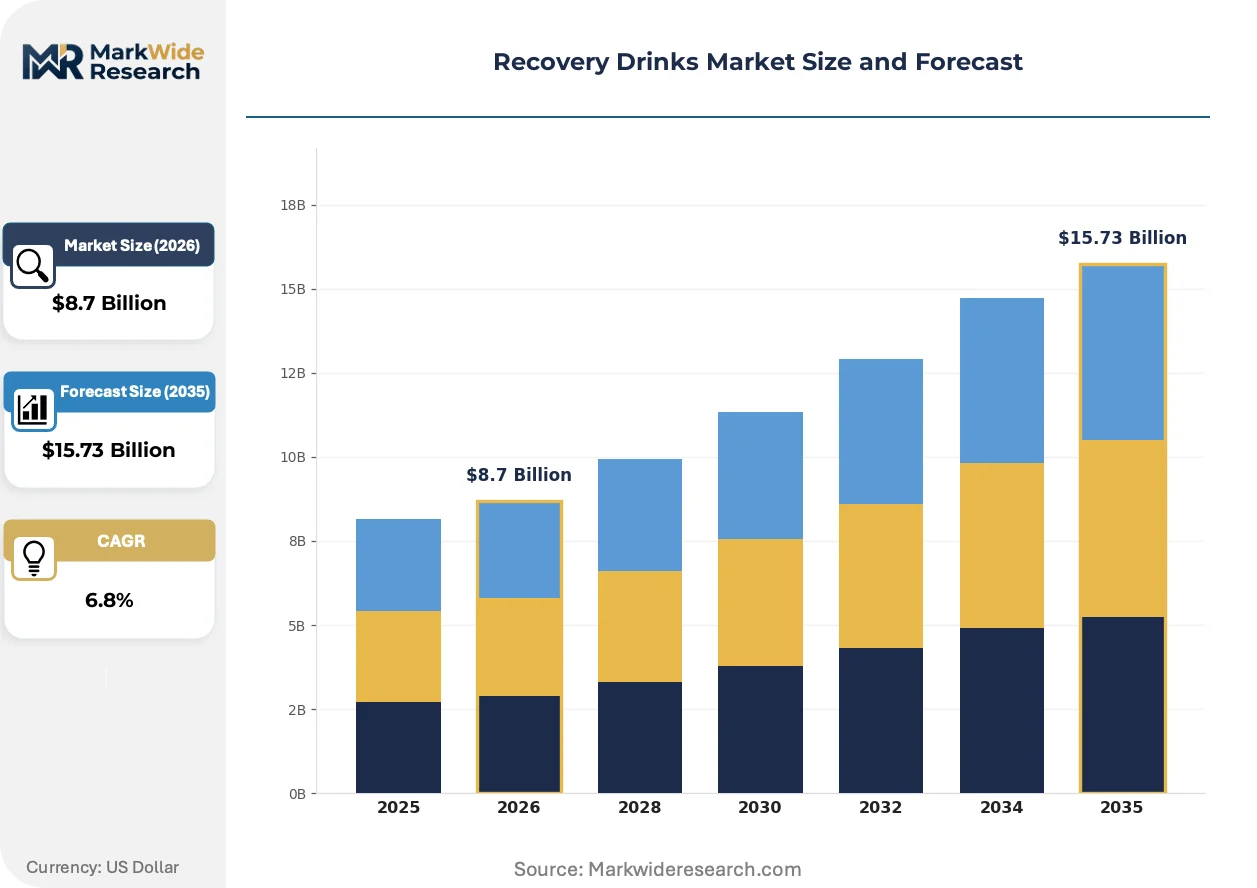
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Shakes, Electrolyte Drinks, Meal Replacement Beverages, Herbal Infusions End User: Athletes, Fitness Enthusiasts, Casual Users, Medical Patients Distribution Channel: Online Retail, Supermarkets, Health Stores, Gyms Ingredients: Vitamins, Amino Acids, Natural Sweeteners, Probiotics |
| Companies Covered | Abbott Nutrition, SiS (Science in Sport), PepsiCo Inc., Celsius Holdings Inc., Oatly Group AB, The Coca-Cola Company, Otsuka Pharmaceuticals, Nestle S.A., Glanbia PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recovery Drinks Market Evolving Landscape
Reformulation priorities are pivoting toward ingredient transparency and physiological specificity, with brands racing to match certified nutrient declarations against shifting regulatory baselines and athlete procurement standards.
Precision fermentation-derived proteins are absorbing capital allocation from traditional dairy extraction methods. Specialty ingredient suppliers in the Netherlands and California are scaling microbial whey production to serve brands seeking supply chain decoupling from commodity dairy markets. This technology is absorbing volume share in premium tier formulations where provenance claims command measurable price premiums.
EFSA health claim substantiation protocols are tightening evidentiary requirements for performance messaging across European markets. Brands must now maintain clinical trial documentation for any recovery-related physiological claims, compressing marketing vocabulary to strictly compliant phrasing. Protein shake segments targeting competitive athletes face the steepest compliance burdens, with several UK and French manufacturers reformulating to remove borderline functional descriptors.
Direct-to-consumer replenishment cycles are displacing gym-based impulse purchases as the dominant acquisition mode. Subscription platforms with personalized amino acid profiling are capturing endurance sport enthusiasts in Colorado and Queensland who previously bought retail. This channel rotation concentrates customer data ownership with brands while reducing slotting fee exposure in sports nutrition retail.
Recovery Drinks Market Segmentation
Segmentation in recovery drinks reveals how formulation specificity and channel access determine margin capture. Each dimension exposes different competitive barriers, from amino acid certification standards to institutional procurement pathways.
Product Type:
Standalone consumption dominates protein and electrolyte formulations, while meal replacement and herbal variants embed within broader dietary protocols.
- Protein Shakes:Formulations specify 15-30 grams of whey or plant-derived protein per serving, with amino acid profiles now certified for collegiate athletic procurement. Demand concentrates in United States gym retail where established fitness culture sustains repeat purchase frequency against commodity dairy price volatility.
- Electrolyte Drinks:Sodium-matched formulations replicate sweat mineral losses for endurance participants. Casual fitness expansion in Germany and Australia drives volume beyond competitive athlete bases, with subscription platforms capturing endurance enthusiasts in Colorado and Queensland.
- Meal Replacement Beverages:Macronutrient-complete formulations serve time-constrained professionals seeking post-workout caloric recovery.
- Herbal Infusions:Adaptogen and botanical blends target wellness-oriented consumers prioritizing clean-label certification stacking.
Volume placements concentrate in Protein Shakes; the faster expansion belongs to Electrolyte Drinks.
End User:
Cost tiers separate institutional procurement from discretionary retail, with medical and athletic segments commanding premium pricing against casual mass-market consumption.
- Athletes:Competitive and collegiate programs mandate certified amino acid documentation and batch-tested formulations. Procurement standards from professional sports teams filter down to consumer tiers, creating compliance moats for certified suppliers.
- Fitness Enthusiasts:Regular gym attendees sustain protein shake consumption through subscription replenishment cycles displacing retail impulse purchases.
- Casual Users:Occasional participants in recreational sports drive electrolyte category growth with lower formulation specificity requirements.
- Medical Patients:Post-surgical and physical therapy settings demand clinical nutrition credentials unlocking hospital and rehabilitation channel access.
Pricing power concentrates with Athletes; Medical Patients represent the steepest margin expansion opportunity.
Distribution Channel:
Channel maturity separates established physical retail from emerging direct-to-consumer platforms reshaping replenishment economics.
- Online Retail:Subscription platforms with personalized amino acid profiling capture customer data ownership while reducing slotting fee exposure. Direct-to-consumer cycles now dominate acquisition for endurance sport enthusiasts.
- Supermarkets:Mass retail scale enables sports sponsorship integration and broad demographic reach for mainstream formulations.
- Health Stores:Natural retail channels command premiums for USDA organic and Non-GMO Project dual-certification stacking.
- Gyms:Impulse purchase locations face displacement as replenishment programs compress traditional retail cycles.
Customer data ownership concentrates in Online Retail; Gyms face the steepest volume erosion.
Ingredients:
Supply concentration in specialized isolates creates sourcing vulnerability for premium tiers against commodity vitamin and sweetener inputs.
- Vitamins:Standard micronutrient fortification serves baseline nutritional claims with established supply chains.
- Amino Acids:Branched-chain and essential amino acid specifications now require verified profiles for athletic procurement compliance. European and North American processing facility concentration creates geographic sourcing risk.
- Natural Sweeteners:Clean-label alternatives face pending sugar taxation legislation in multiple US jurisdictions threatening acceptable formulation palettes.
- Probiotics:Digestive health positioning targets wellness segments with EFSA evidentiary standards demanding extended documentation periods for European market entry.
Procurement scrutiny concentrates on Amino Acids; Natural Sweeteners face the most acute regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denver anchors the highest density of endurance sport subscription platforms in North America, with personalized amino acid profiling services capturing fitness enthusiasts who previously bought retail. This metropolitan cluster exemplifies how direct-to-consumer replenishment cycles now dominate acquisition modes across major markets.
United States
Gym penetration rates sustain the highest sports nutrition retail density globally, anchoring protein shake consumption in established fitness routines. The FDA's updated nutrition labeling requirements for functional beverages reshape formulation disclosure standards nationwide. Colorado and California host the densest concentrations of endurance sport subscription platforms.
Germany
Casual fitness expansion drives electrolyte category volume beyond competitive athlete bases. EFSA health claim substantiation protocols tighten evidentiary requirements for performance messaging across European markets. Bavaria and North Rhine-Westphalia concentrate specialized whey protein isolate processing facilities.
Australia
Endurance sport enthusiasts in Queensland shift toward subscription platforms with personalized amino acid profiling. The country's national food standards regulator enforces strict nutrient content declarations for functional beverages. Sydney and Melbourne anchor natural retail channels commanding premiums for clean-label certification stacking.
United Kingdom
Collegiate athletic programs mandate certified amino acid documentation filtering procurement standards to consumer tiers. EFSA evidentiary standards demand extended documentation periods delaying European market entry for novel bioactive ingredients. London and the Southeast concentrate reformulation activity removing borderline functional descriptors.
Japan
Medical-grade recovery formulations unlock institutional procurement contracts in post-surgical and physical therapy settings. The Pharmaceuticals and Medical Devices Agency governs health claim substantiation for functional beverages with clinical positioning. Tokyo and Osaka anchor hospital and rehabilitation channel access for clinical nutrition heritage brands.
Recovery Drinks Market Competitive Landscape
Capital-heavy producers with backward integration into ingredient supply compete with asset-light brands relying on contract manufacturing networks. The vendor base stratifies across three tiers: multinational beverage conglomerates with mass retail scale, specialized sports nutrition houses with certified amino acid capabilities, and clinical nutrition heritage players with institutional channel access. Dominant competitive moves include sports sponsorship integration for brand awareness and precision fermentation technology licensing for supply chain decoupling from commodity dairy markets.
Within the clinical nutrition tier, Abbott Nutrition exemplifies hospital and rehabilitation channel anchoring. Among diversified beverage conglomerates, PepsiCo Inc. and The Coca-Cola Company occupy positions defined by mass retail distribution scale. On the specialized sports nutrition vector, Glanbia PLC represents premium whey protein sourcing and sports nutrition ingredient supply archetypes.
| Leading Market Players |
|---|
| Abbott Nutrition |
| SiS (Science in Sport) |
| PepsiCo Inc. |
| Celsius Holdings Inc. |
| Oatly Group AB |
| The Coca-Cola Company |
| Otsuka Pharmaceuticals |
| Nestle S.A. |
| Glanbia PLC |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Bavaria and Wisconsin anchor premium whey protein isolate production, their concentrated ownership structures enabling patient capital allocation toward certified amino acid capacity while sustaining pricing discipline against commodity dairy volatility. This ownership pattern reinforces supply-side discipline that filters through to downstream formulation tiers.
Pricing Analysis
Outcome-based pricing anchors premium recovery drink tiers, with certified amino acid profiles commanding measurable premiums over commodity protein formulations. Three-tier pricing structure across premium, standard, and economy levels separates batch-tested athletic procurement grades from mass-market retail variants. Cost compression in mid-tier protein shakes is intensifying because dairy commodity swings transmit directly to margin structures without backward integration buffers. Casual fitness participants in electrolyte categories exhibit highest price sensitivity, while collegiate athletic programs demonstrate lowest sensitivity due to mandated compliance standards.
Supply Chain Analysis
Freight cost escalation from European and North American processing hubs to Asia-Pacific markets is reshaping regional sourcing strategies for premium isolates. Supply concentrates in Germany, Ireland, and Wisconsin for specialized whey protein isolate production, with precision fermentation pilots in California and the Netherlands emerging as alternative pathways. Raw material dependencies center on dairy milk solids, microbial feedstocks for fermentation, and natural sweetener alternatives facing regulatory pressure. Single-source vulnerability concentrates in European processing facilities certified for athletic procurement standards. Distribution runs through subscription platforms consolidating customer data ownership alongside traditional sports nutrition retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized isolate production capacity constraints in certified European facilities prop pricing premiums across premium tiers, constraining volume expansion for uncertified competitors.
For Market Incumbents: Deploy precision fermentation licensing to decouple from commodity dairy volatility while securing alternative protein supply pathways. Anchor hospital and rehabilitation channel access through clinical nutrition heritage credentials against emerging sports nutrition entrants. Pursue backward integration into amino acid testing and certification infrastructure to defend procurement standards moats. For New Entrants and Emerging Players: Precision fermentation-derived proteins offer technology-first entry into premium tiers where provenance claims command price premiums. White-space concentrates in sodium-matched electrolyte formulations for casual fitness expansion in Germany and Australia, with personalized amino acid profiling subscription platforms capturing endurance enthusiasts. Direct-to-consumer replenishment cycles with data-driven personalization represent the most penetrable go-to-market angle against established retail slotting fee structures. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract manufacturers with certified amino acid capabilities in North America and Europe facing temporary dairy commodity margin compression. Long-term viability hinges on regulatory compliance infrastructure and channel diversification beyond gym retail concentration. Watch EFSA health claim substantiation protocol tightening as inflection indicator for European market entry barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial whey production in California and the Netherlands decouples supply from commodity dairy price cycles. |
| Dual Certification Stacking | USDA organic combined with Non-GMO Project verification commands shelf premiums in natural retail channels. |
| Subscription Platform Launch | Personalized amino acid profiling captures customer data ownership while reducing slotting fee exposure. |
| Hospital Channel Partnership | Clinical nutrition heritage credentials unlock institutional procurement contracts in post-surgical settings. |
| Electrolyte Formulation Expansion | Sodium-matched sweat replacement targets casual fitness growth in Germany and Australia beyond competitive athletes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted across sports nutrition formulators, contract manufacturing procurement leads, collegiate athletic program nutrition directors, and natural retail category buyers. FDA nutrition labeling guidance documents, EFSA health claim substantiation protocols, and USDA organic certification databases provided regulatory baselines. Bottom-up volume builds triangulated against top-down market sizing from gym penetration rates and subscription platform disclosed metrics.
Granularity-level modeling specified protein load tiers, electrolyte concentration bands, and certification status across product types, with channel economics differentiated by slotting fee structures versus direct-to-consumer customer acquisition costs. CAGRs derived from segment-level volume trajectories weighted by pricing tier mix. Forecast inputs incorporated endurance sport participation trends, precision fermentation capacity buildout timelines, and state-level sugar taxation legislative tracking.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EFSA evidentiary standard tightening or dairy commodity price spike scenarios. Forecasts reflect documented assumptions on gym culture retention rates and subscription platform churn benchmarks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Fruit Beverages Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Gluten Free Beverages Market
Beverages
Europe Bottled Water Processing Market
Beverages
Beverage Dispenser Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
India Soy Beverages Market
Beverages
Pineapple Juice Market
Beverages
Plant-Based Energy Drink Market
Beverages
Fruit Water Market
Beverages
Nitro-Infused Cola Market
Beverages
Nitro-Infused Beverages Market
Beverages
Asia-Pacific Spring Water Market
Beverages
Dairy Based Beverages Market
Beverages
Orange Juice Market
Beverages
Beverage Cooler Market