
 Reconstituted Juice Market | 2026-2036
Reconstituted Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Reconstituted Juice Market Analytics
Aseptic cold filling technology is reconfiguring how reconstituted juice moves from concentrate to shelf-stable finished goods without thermal degradation. PepsiCo leverages its global bottling network to sustain cost advantages in high-volume orange and apple juice lines. Citrosuco S.A. anchors Brazilian orange concentrate supply through integrated groves-to-port operations. The Coca-Cola Company differentiates via controlled-atmosphere packaging partnerships that extend juice freshness in emerging markets.
Reconstituted juice refers to beverage products manufactured by restoring water to concentrated fruit juice, typically achieving Brix levels between 11.3 and 11.8 degrees for orange juice to match single-strength equivalents. This process enables efficient bulk transport of reduced-volume concentrate followed by local reconstitution and packaging to serve retail and food service channels cost-effectively. Concentrated juice remains the dominant product form due to established logistics infrastructure and multi-year supply contracts with institutional buyers. Tetra Packs capture expanding share in retail distribution channels where ambient storage and extended shelf life reduce cold-chain dependency and inventory spoilage.
FDA enforces juice HACCP regulations mandating pathogen reduction treatments, while USDA grades concentrate quality through standardized Brix-acid ratio classifications that shape procurement premiums. ISO 22000 certification requirements from major European retailers are forcing export-oriented processors to upgrade traceability systems across concentrate blending and reconstitution lines. Stakeholders must monitor how evolving EU Green Deal packaging mandates and emerging state-level extended producer responsibility laws in California and New York reshape material choices and cost structures across the value chain.
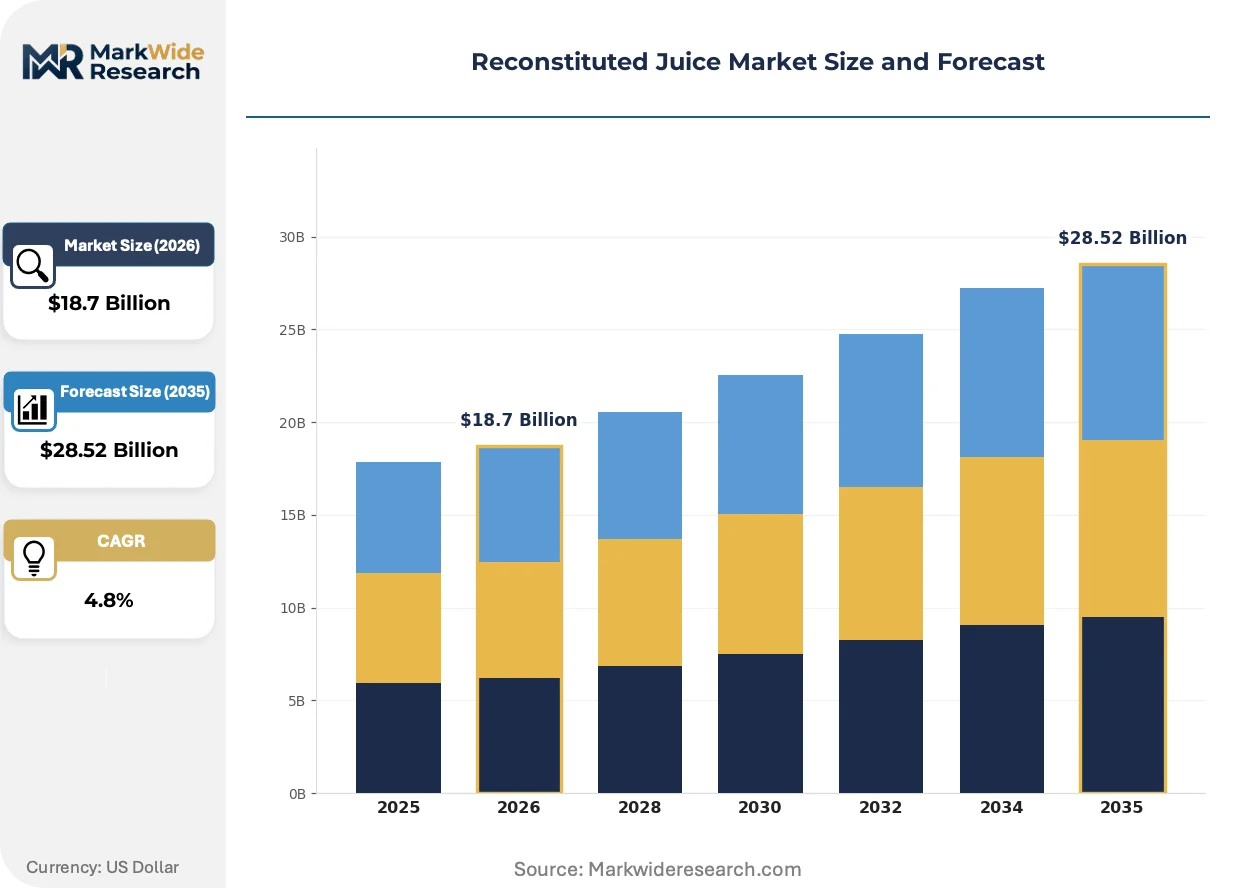
Market Dynamics
Aseptic cold filling technology is compressing thermal processing requirements while FDA juice HACCP mandates tighten pathogen control protocols. This dual pressure is forcing capital reallocation toward equipment upgrades and compliance infrastructure across concentrate-to-beverage operations.
Growth Catalysts
- EU Green Deal packaging mandates:Ambient-stable Tetra Pack formats gain procurement preference as retailers eliminate refrigerated SKUs to meet circular economy targets.
- Food service breakfast menu expansion:Institutional operators are adding reconstituted juice dispensers to reduce per-serve labor and waste versus fresh-squeezed alternatives.
- Brazilian orange concentrate cluster:Integrated groves-to-port infrastructure at Santos port enables year-round supply security for North American and European buyers.
Market Restraints
- Concentrate supply geographic concentration:Overreliance on São Paulo state citrus belt exposes buyers to frost risk and currency volatility.
- Single-strength not-from-concentrate substitution:Premium retail segments are migrating to NFC orange juice despite higher logistics costs.
- Extended producer responsibility laws:California and New York state packaging fee structures are elevating per-unit container economics.
Strategic Opportunities
- Clean-label enzyme clarification:Pectinase and amylase treatments enable reduced thermal processing while maintaining visual clarity standards.
- India urban retail cold-chain buildout:Modern trade expansion in Mumbai and Delhi creates ambient-stable juice penetration potential.
- Controlled-atmosphere packaging partnerships:Modified atmosphere formats extend shelf life in Southeast Asian humidity conditions.
Industry Challenges
- ISO 22000 traceability system integration:European retailer certification demands require lot-level tracking across blending and reconstitution lines.
- Multi-year institutional contract renegotiation:Brix-acid ratio specifications and volume commitments complicate margin defense amid input volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reconstituted Juice Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Juice, Puree, Extract, Powdered Juice Packaging Type: Bottles, Cartons, Pouches, Tetra Packs End User: Food Service, Retail, Canteens, Hotels Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Citrus World Inc., Ocean Spray Cranberries Inc., PepsiCo Inc., Citrosuco S.A., Dole Food Company Inc., The Coca-Cola Company, Del Monte Foods Inc., Louis Dreyfus Company B.V., Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reconstituted Juice Market Evolving Landscape
Processing technology and regulatory frameworks are converging to redefine shelf-stable juice economics. Equipment manufacturers and concentrate processors are racing to deploy systems that reduce thermal exposure while satisfying evolving safety mandates.
High-pressure processing (HPP) systems are penetrating mid-volume reconstitution facilities seeking to bypass traditional pasteurization tunnels. Beverage co-packers in California and Texas are retrofitting lines to handle HPP-compatible bottle formats. This shift is rendering obsolete conventional hot-fill operations for premium private-label juice programs.
EU Green Deal packaging mandates are accelerating fiber-based barrier material trials across European retail supply chains. Concentrate importers must now validate compostability certifications for secondary packaging to maintain supermarket listings. German and Dutch retailers are imposing the strictest compliance timelines, forcing Q3 2025 format transitions.
Direct-store-delivery consolidation is compressing traditional wholesale juice distribution in urban North American markets. Large-format retailers are consolidating beverage procurement through centralized distribution centers, bypassing regional distributors. This pattern is most visible in Texas and Florida metro corridors where convenience store chains dominate volume.
Reconstituted Juice Market Segmentation
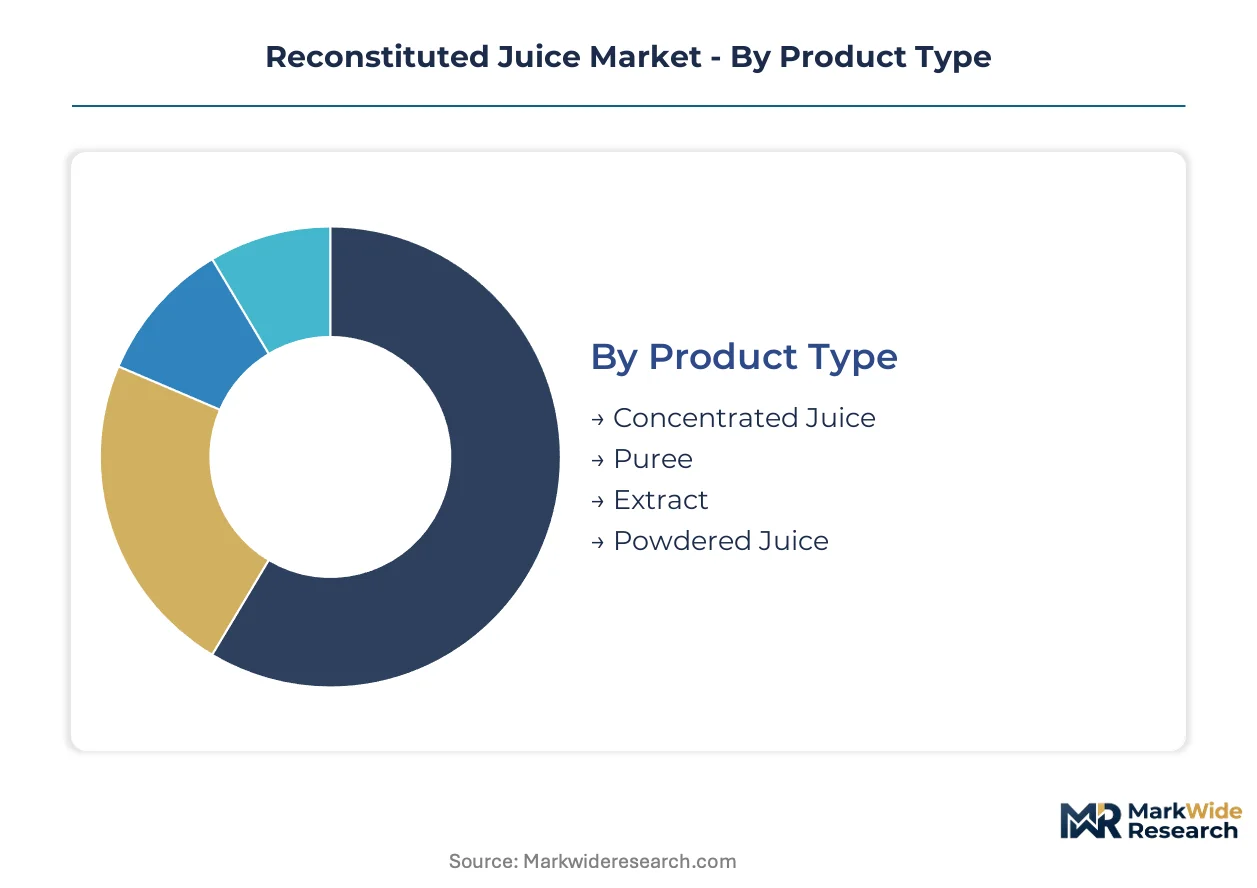
Reconstituted juice supply chains fragment across concentrate forms, packaging technologies, and channel economics. Each dimension shapes capital allocation, margin structure, and regulatory exposure differently across the value chain.
Product Type:
Cost tier determines logistics efficiency and processing intensity across concentrate formats.
- Concentrated Juice:Reduced-volume liquid concentrate achieves 65-70°Brix for bulk ocean freight efficiency. Food service operators in Brazil and Florida rely on this format for high-throughput breakfast programs where per-serve cost minimization dominates procurement criteria.
- Puree:Thick fruit pulp retains fiber and cloud stability for premium beverage applications. European smoothie chains and German retail private labels are expanding puree-based SKUs to satisfy clean-label positioning without NFC price premiums.
- Extract:Clarified juice concentrates deliver standardized color and flavor for industrial ingredient use. Brazilian processors supply extract to North American carbonated soft drink bottlers seeking consistent year-round inputs.
- Powdered Juice:Spray-dried or freeze-dried concentrates enable ambient distribution in cold-chain-deficient markets. Indian urban retail and Nigerian distributors are adopting powdered formats for extended shelf stability in tropical storage conditions.
Concentrated juice commands the established base. The steepest expansion runs through puree as premium positioning migrates downstream.
Packaging Type:
Application context shapes material selection between ambient shelf stability and refrigerated freshness signaling.
- Tetra Packs:Aseptic carton systems combine aluminum barrier layers with fiber-based exteriors for 12-month ambient shelf life. EU Green Deal mandates are accelerating format adoption as German and French retailers eliminate refrigerated juice SKUs from circular economy compliance roadmaps.
- Bottles:PET and HDPE containers dominate food service dispenser refills and family-size retail formats. California extended producer responsibility fees are elevating per-unit economics and pushing converters toward rPET content thresholds.
- Cartons:Gable-top refrigerated cartons signal freshness in premium retail segments. Northeast US supermarket chains maintain carton listings for private-label orange juice despite higher cold-chain costs versus aseptic alternatives.
- Pouches:Flexible stand-up formats reduce material weight for single-serve and children's juice segments. Southeast Asian convenience store chains are expanding pouch distribution to match on-the-go consumption patterns in humid climates.
Tetra Packs are gaining share fastest in retail channels where ambient distribution collapses logistics complexity. Bottles retain food service dominance.
End User:
Customer type dictates volume predictability, specification stringency, and contract structure across demand pools.
- Food Service:Institutional operators including hotel breakfast programs and QSR chains prioritize concentrate-to-beverage systems that minimize labor and waste. Brazilian orange concentrate flows to North American food service distributors under multi-year Brix-acid ratio contracts.
- Retail:Supermarket and hypermarket channels balance private-label margin optimization with branded traffic generation. ISO 22000 certification requirements from European retailers are forcing concentrate suppliers to upgrade traceability systems for retail qualification.
- Hotels:Full-service properties maintain fresh-squeezed theater while back-of-house operations rely on reconstituted formats for cost control. Dubai and Singapore hotel clusters source ambient-stable concentrates to reduce refrigeration footprint in premium properties.
- Canteens:Corporate and institutional feeding operations prioritize lowest-unit-cost procurement with minimal quality variance. Indian IT campus canteens and Brazilian factory feeding programs represent volume concentration in emerging market industrial zones.
Food service commands the established base. The steepest expansion runs through retail as modern trade penetration deepens in India and Southeast Asia.
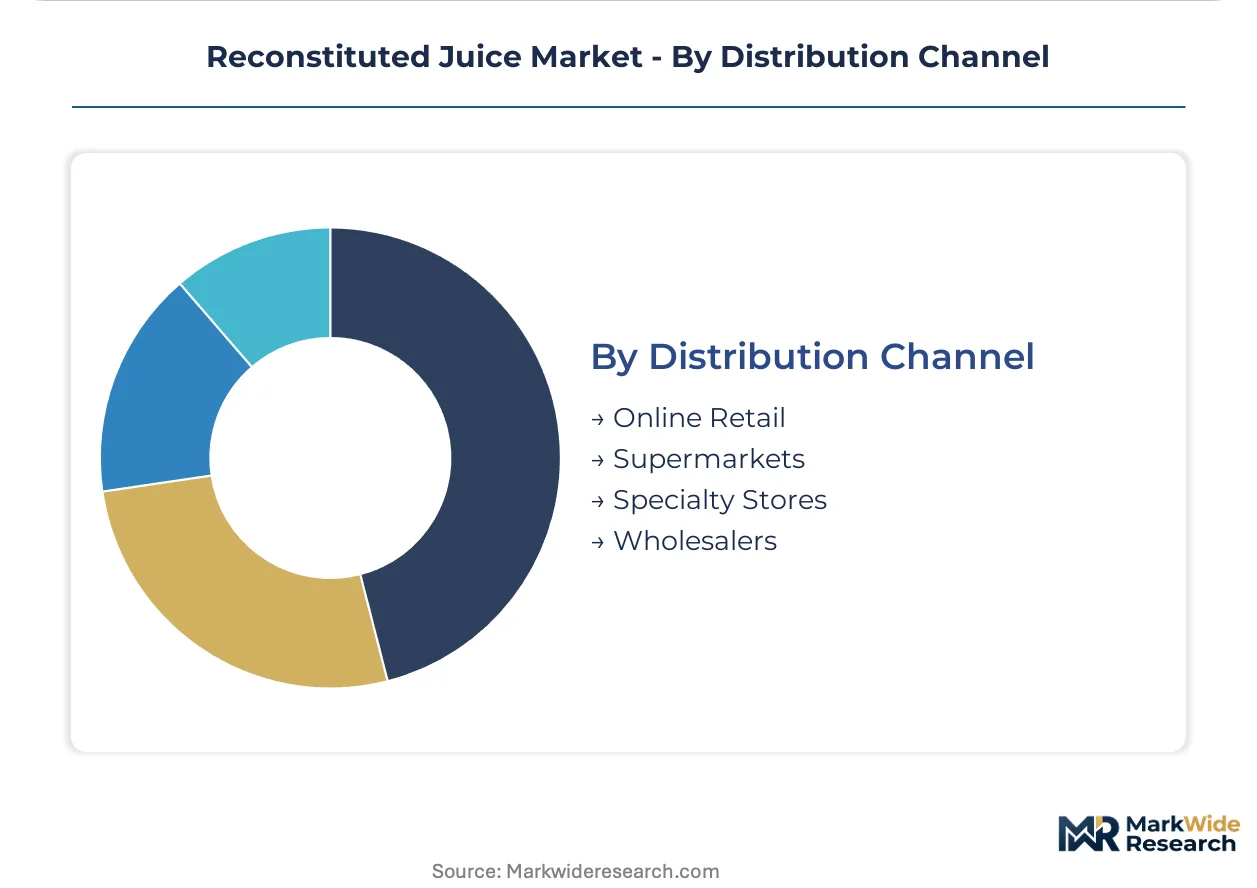
Distribution Channel:
Volume concentration and margin capture diverge sharply between centralized procurement and fragmented wholesale networks.
- Supermarkets:Large-format retailers consolidate beverage procurement through centralized distribution centers, bypassing regional distributors in Texas and Florida metro corridors. Direct-store-delivery compression is most visible in these channels.
- Online Retail:E-commerce platforms enable subscription-based concentrate replenishment and bulk pack economics for household stockpiling. Indian quick-commerce operators are building ambient juice categories for 10-minute delivery promises in Mumbai and Delhi.
- Wholesalers:Traditional cash-and-carry networks serve independent retailers and small food service accounts in cold-chain-deficient regions. Nigerian and Kenyan distributors rely on wholesale concentrate importation for local reconstitution and repackaging.
- Specialty Stores:Organic and natural product retailers command premium positioning for enzyme-clarified and reduced-thermal-processing concentrates. German Bio-Siegel certification requirements shape supplier qualification for this channel.
Supermarkets command the established base. The steepest expansion runs through online retail as quick-commerce infrastructure scales in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for orange concentrate defines regional procurement strategies. Brazil dominates export supply while North American and European buyers balance cost efficiency against frost risk exposure. Asian markets are building cold-chain infrastructure to absorb rising reconstituted juice volumes.
United States
Florida food service operators and Texas retail chains drive concentrate demand for breakfast programs and family-size formats. FDA juice HACCP regulations mandate pathogen reduction treatments that elevate processing costs at domestic reconstitution facilities. The Dallas-Fort Worth metro corridor hosts expanding beverage co-packing capacity to serve quick-service restaurant chains.
Brazil
São Paulo state citrus belt supplies the dominant share of global orange concentrate through integrated groves-to-port operations. ANVISA enforces sanitary standards that align with FDA and EFSA requirements for export qualification. Santos port infrastructure enables year-round loading for North American and European buyers seeking supply security.
Germany
Retail chains in Berlin and Hamburg are eliminating refrigerated juice SKUs to satisfy EU Green Deal circular economy compliance timelines. EFSA standards shape Brix-acid ratio specifications for concentrate imports from Brazilian suppliers. The Rhine-Ruhr industrial zone hosts aseptic packaging equipment manufacturers serving ambient-stable format transitions.
India
Mumbai and Delhi modern trade expansion creates penetration potential for ambient-stable powdered and Tetra Pack formats. FSSAI labeling requirements are tightening for imported concentrate reconstitution and local packaging operations. Maharashtra state distributors are building wholesale networks for quick-commerce 10-minute delivery promises in dense urban corridors.
China
Yangtze River Delta retail consolidation is compressing traditional wholesale juice distribution through centralized procurement at Shanghai distribution centers. SAMR food safety standards enforce traceability across concentrate blending and reconstitution lines. Pearl River Delta beverage manufacturers are retrofitting lines for aseptic cold filling technology to reduce thermal degradation.
Reconstituted Juice Market Competitive Landscape
On the supply side, the industry is consolidating around integrated processors with captive concentrate supply and global bottling networks. Tiered competitive positioning separates scale-driven multinational beverage conglomerates from regional concentrate specialists and private-label co-packers. Dominant competitive moves include backward integration into citrus groves and strategic partnerships for controlled-atmosphere packaging technology.
Within the integrated processor tier, Citrosuco S.A. exemplifies groves-to-port vertical control, while Louis Dreyfus Company B.V. occupies a position as a commodity trading house with concentrate processing exposure. Among multinational beverage conglomerates, PepsiCo Inc. and The Coca-Cola Company anchor scale advantages through global bottling infrastructure and retail channel access.
| Leading Market Players |
|---|
| Citrus World Inc. |
| Ocean Spray Cranberries Inc. |
| PepsiCo Inc. |
| Citrosuco S.A. |
| Dole Food Company Inc. |
| The Coca-Cola Company |
| Del Monte Foods Inc. |
| Louis Dreyfus Company B.V. |
| Nestlé S.A. |
| Others |
Value Network & Pricing Analysis
Undercapacity in Brazilian orange concentrate processing during the Southern Hemisphere frost season tightens spot pricing and accelerates long-term offtake contracting among North American food service buyers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across reconstituted juice procurement. Three-tier pricing structure across premium enzyme-clarified, standard heat-pasteurized, and economy bulk-concentrate levels separates Citrosuco-certified supply from private-label alternatives. Cost compression in economy tiers intensifies because Brazilian currency volatility elevates import basis risk for US distributors. Quick-service restaurant chains exhibit highest price sensitivity due to per-serve margin targets, while premium hotel operators absorb certification premiums for traceability assurance.
Supply Chain Analysis
Extended payment terms from European retailers now stretch to 90-120 days, forcing Brazilian processors to access supply-chain finance facilities through Santos port trade houses. Raw material flows concentrate in Brazil, Mexico, and Florida, with frozen concentrate orange juice futures hedging currency exposure. Pectinase enzymes, aseptic carton barriers, and cold-chain equipment constitute critical input dependencies. Single-source vulnerability runs through São Paulo state frost corridors. Distribution runs through centralized retail procurement at Texas and Florida distribution centers, bypassing regional wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment leasing and technical service contracts for aseptic filling lines expand faster than concentrate commodity sales, creating recurring-revenue attachment opportunities for processors with installed base control.
For Market Incumbents: Pre-empt NFC substitution threat by locking multi-year Brix-acid ratio contracts with institutional food service operators before premium retail migration accelerates. Backward integration into enzyme clarification technology preserves margin defense against clean-label competitors. Channel control through direct-store-delivery consolidation in Texas metro corridors blocks private-label encroachment. For New Entrants and Emerging Players: Mid-tier Indian urban retail in Mumbai and Delhi represents the most penetrable entry point, where ambient-stable powdered formats bypass cold-chain infrastructure gaps. Nigerian wholesale concentrate importation for local repackaging offers second white-space anchor. Partner with quick-commerce operators for 10-minute delivery slot penetration rather than building proprietary distribution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aseptic cold filling retrofit programs, favoring asset-light co-packing models over integrated processing. Five-to-ten-year viability hinges on controlled-atmosphere packaging technology access. Target regional concentrate specialists with captive Brazilian supply relationships. Watch EU Green Deal packaging mandate compliance timelines as inflection signal for format transition winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Groves | Citrosuco's groves-to-port model secures year-round supply security against frost volatility. |
| Aseptic Cold Filling Retrofit | PepsiCo bottling network upgrades reduce thermal degradation while meeting FDA juice HACCP mandates. |
| Controlled-Atmosphere Packaging Partnership | Coca-Cola alliances extend shelf life in Southeast Asian humidity conditions beyond conventional barriers. |
| Clean-Label Enzyme Clarification Investment | Pectinase and amylase treatments enable reduced thermal processing for premium positioning. |
| Quick-Commerce Channel Expansion | Indian operators build ambient juice categories for 10-minute delivery promises in dense urban corridors. |
Research Methodology
Cross-validation between concentrate processor procurement directors and food service distributor category managers anchors the qualitative findings. Primary interviews with Brazilian citrus operations executives, European retail buyer committees, FDA regulatory affairs consultants, and aseptic packaging equipment engineers combined with secondary validation from ANVISA export filings, EU Green Deal compliance databases, and FSSAI labeling directives. Bottom-up volume modeling and top-down trade flow analysis triangulate market sizing.
Calibration against historical Brix-acid ratio contract structures and freight rate volatility patterns shapes the analytical framework across the projection horizon. Segmentation dimensions include concentrate form, packaging technology, end-user channel, and regional regulatory cluster. CAGRs derive from weighted average growth across modeled scenarios. Forecast inputs incorporate Brazilian frost frequency distributions and EU packaging mandate compliance timelines.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real volatility, ocean freight rates, or European energy costs would shift the trajectory. Forecasts reflect documented assumptions regarding pasteurization technology adoption curves and cold-chain infrastructure buildout rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Hydration Infusers Market
Beverages
South America Dairy Based Beverages Market
Beverages
Probiotic Beverage Market
Beverages
Bubble Food and Beverages Market
Beverages
United States Beverage Contract Bottling and Filling Market
Beverages
Peanut Oil Market
Beverages
United States Recovery Drinks Market
Beverages
Sports and Energy Drinks Market
Beverages
Fermented Foods and Beverages Market
Beverages
Chocolate Powdered Drinks Market
Beverages
Low Calorie RTD Beverages Market
Beverages
Premium Water Market
Beverages
Asia-Pacific Spring Water Market
Beverages
Nitro-Infused Cola Market
Beverages
Europe Probiotic Drinks Market
Beverages
North America Sugar Free Energy Drinks Market