
 Europe Juices Market | 2026-2036
Europe Juices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Juices Market Insights
Aseptic cold processing and high-pressure pascalization is reconfiguring how European juice manufacturers preserve flavor without thermal degradation. Eckes-Granini Group GmbH leverages its German production footprint to dominate the not-from-concentrate segment across Central Europe. Refresco Group N.V. anchors private-label supply for major retailers, competing on scale and formulation flexibility. PepsiCo Inc. extends its Tropicana heritage through reformulated lower-sugar lines that navigate evolving nutritional guidelines.
Europe juices comprise unfermented liquid extracts from fruits or vegetables, typically standardized to brix levels between 11.2 and 12.3 degrees for orange juice and pasteurized or cold-treated to achieve shelf stability from days to months. These products serve commercial refreshment, at-home consumption, and ingredient applications across foodservice and manufacturing. Citrus juices occupy the largest volume share given Mediterranean sourcing proximity and year-round availability, while mixed juices capture faster value growth as blend innovation targets functional positioning with added botanicals or vitamins. Carton packaging leads ambient distribution through supermarkets, though pouches and smaller-format bottles gain traction in convenience channels and on-the-go consumption.
EFSA nutrition claims regulation and EU Sugar Reduction Framework shape permissible health messaging and formulation thresholds, compelling manufacturers to reformulate or risk delisting. ECHA oversight of food contact materials for packaging migration limits influences material selection across carton, bottle, and pouch formats. REACH compliance for processing additives and cleaning chemicals adds operational complexity for producers operating multi-country supply chains. Stakeholders must monitor evolving EU-wide front-of-pack labeling schemes and national sugar tax implementations to anticipate margin compression and portfolio restructuring requirements.
Market Dynamics
The EU's Farm to Fork Strategy is compressing formulation timelines across European juice manufacturing, forcing rapid sugar reduction and clean-label transitions before 2030 enforcement milestones.
Growth Catalysts
- EFSA Nutrition Claims Regulation:Standardized health messaging rules enable cross-border marketing consistency, reducing compliance fragmentation for reformulated low-sugar lines.
- Aseptic Cold Processing:High-pressure pascalization preserves volatile flavor compounds without thermal degradation, unlocking premium positioning for not-from-concentrate segments.
- German Retail Infrastructure:Dense supermarket and convenience networks accelerate SKU velocity for functional juice blends targeting health-conscious urban households.
Market Restraints
- Citrus Concentrate Price Volatility:Mediterranean climate variability and irrigation constraints create input cost instability for orange juice base stocks.
- Single-Origin Supply Concentration:Spanish and Italian citrus groves dominate raw material sourcing, exposing processors to regional harvest disruptions.
- REACH Compliance Burden:Multi-country supply chains face escalating documentation requirements for processing additives and food-contact cleaning chemicals.
Strategic Opportunities
- Poland and Romania:Underdeveloped premium juice penetration offers first-mover positioning as disposable incomes rise and modern retail expands.
- Botanical-Infused Functional Blends:Adaptogenic and vitamin-fortified formulations command price premiums in pharmacy and wellness channels.
- EU Green Deal Packaging Mandates:Biodegradable carton and recyclable pouch requirements favor early movers in sustainable material sourcing.
Industry Challenges
- Reformulation Expertise Scarcity:Food technologists capable of maintaining taste profiles while cutting sugar content command premium salaries and extended recruitment cycles.
- Front-of-Pack Labeling Integration:National color-coded schemes in France, Germany, and the UK require parallel packaging runs, complicating inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Juices Market |
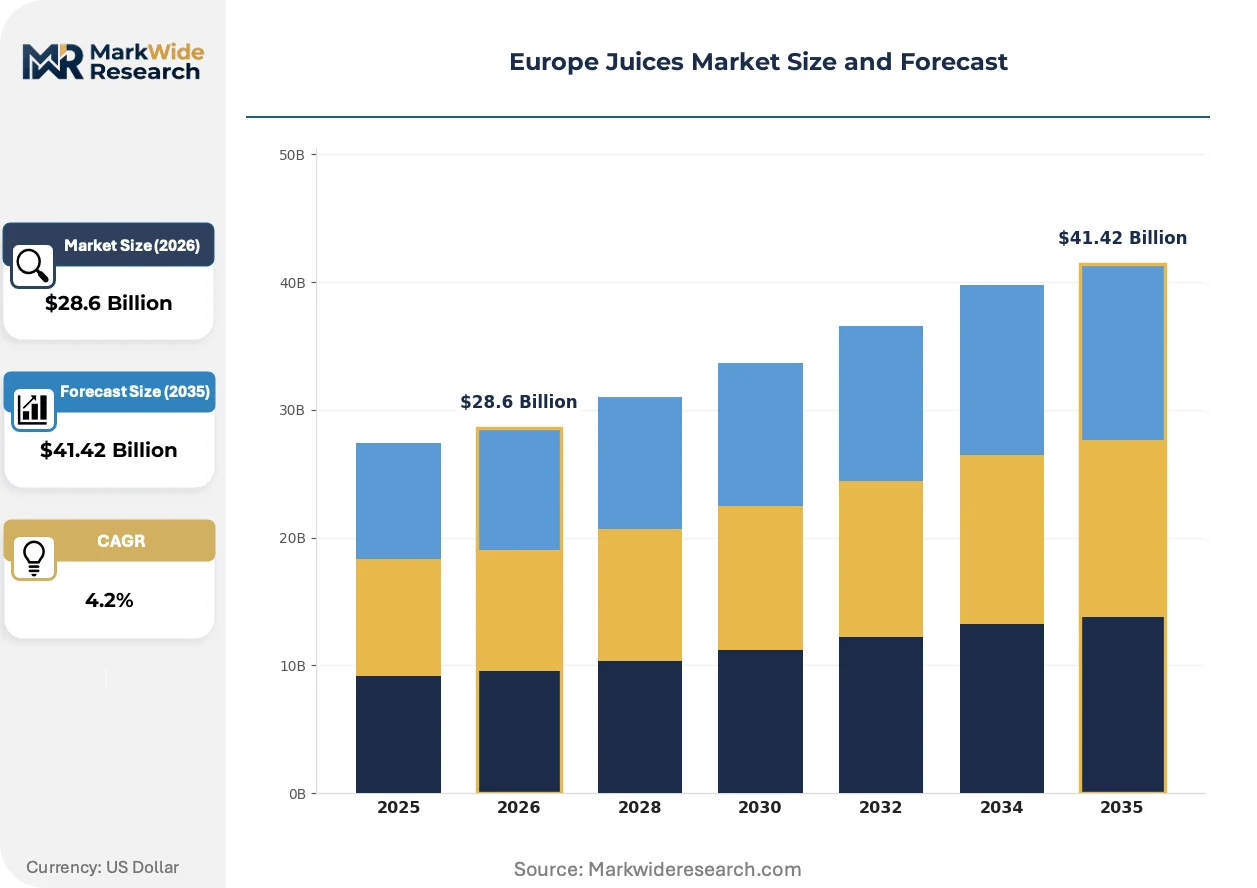
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $41.42 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus Juices, Apple Juices, Grape Juices, Mixed Juices Packaging Type: Bottles, Cartons, Cans, Pouches Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Convenience Stores End User: Households, Restaurants, Cafes, Juice Bars |
| Companies Covered | Refresco Group N.V., Riha WeserGold Getränke GmbH & Co. KG, Eckes-Granini Group GmbH, Conserve Italia, Refresco Deutschland GmbH, The Coca-Cola Co., J. García Carrión S.A., Parmalat, PepsiCo Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Juices Market Trends and Innovations
Digital traceability platforms and non-thermal preservation methods are reconfiguring how European juice producers demonstrate provenance while extending shelf life without chemical additives.
High-pressure pascalization equipment is virtualizing traditional thermal pasteurization workflows. German and Dutch mid-cap processors are retrofitting production lines at accelerating rates. This virtualization collapses the capital barrier between ambient-stable and chilled-fresh supply chains, enabling regional brands to contest national shelf space.
EU Sugar Reduction Framework thresholds are tightening permissible added-sugar content for products bearing health claims. Manufacturers face reformulation or delisting decisions across core orange and mixed-fruit portfolios. German and French retail buyers are already enforcing these standards through procurement specifications ahead of statutory deadlines.
Health-conscious households are consolidating purchases around transparent ingredient lists and single-origin sourcing disclosures. Discounters and hard discounters are responding with dedicated clean-label tiers, compressing margins for legacy brands dependent on ambiguous "natural flavor" positioning. This behavioral pivot concentrates in German-speaking markets and Nordic urban centers where nutritional literacy rates run highest.
Europe Juices Market Segmentation
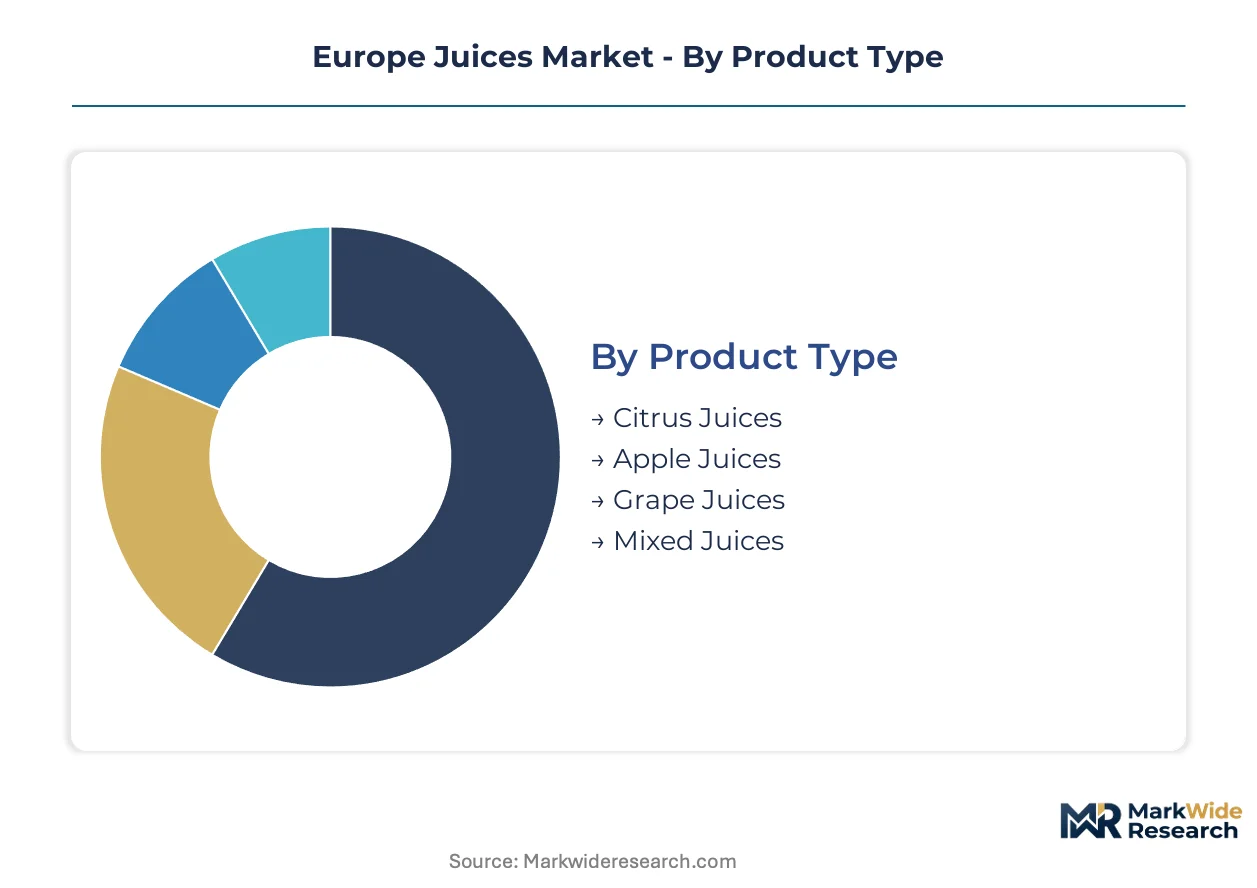
European juice manufacturers configure production assets around four intersecting dimensions that determine margin capture and shelf placement. Product formulation, packaging format, route-to-market, and end-use application each impose distinct technical specifications and regulatory compliance burdens that shape competitive positioning.
Product Type:
Mature categories dominate volume flows while emerging blends command innovation investment and price premiums.
- Citrus Juices:Orange and grapefruit extracts standardized to brix levels between 11.2 and 12.3 degrees constitute the foundational raw material for European blending operations. Spanish and Italian Mediterranean groves supply the majority of base stocks, though climate variability and irrigation constraints create input cost instability for processors.
- Mixed Juices:Multi-fruit formulations incorporating adaptogenic botanicals or vitamin fortification target pharmacy and wellness channels with functional positioning. German health-conscious households and Nordic urban centers drive adoption where nutritional literacy rates run highest and clean-label expectations are most stringent.
- Apple Juices:Central European orchard networks in Poland and Germany provide regional sourcing proximity for this mature category.
- Grape Juices:Concentrated and single-strength variants serve both direct consumption and ingredient applications across foodservice manufacturing.
Citrus Juices retains volume leadership; Mixed Juices holds the steepest expansion curve.
Packaging Type:
Cost tier stratification separates premium preservation technologies from commodity formats in ambient and chilled distribution.
- Cartons:Aseptic carton systems enable ambient shelf stability for extended distribution reach without refrigeration infrastructure. EU Green Deal packaging mandates for biodegradable materials favor early movers in sustainable material sourcing, though ECHA oversight of food contact migration limits complicates substrate selection.
- Bottles:PET and glass formats dominate chilled fresh segments where high-pressure pascalization replaces thermal pasteurization. German and Dutch mid-cap processors retrofit production lines at accelerating rates to contest national shelf space with regional brands.
- Pouches:Flexible formats gain traction in convenience channels and on-the-go consumption with smaller portion sizing.
- Cans:Aluminum formats serve specific foodservice and vending applications with durability advantages.
Cartons dominate ambient volume; pouches are climbing the fastest in convenience channel penetration.
Distribution Channel:
Customer type concentration varies sharply between mass retail consolidation and fragmented specialty access points.
- Supermarkets:Dense German and French retail networks enforce procurement specifications ahead of statutory EU Sugar Reduction Framework deadlines, compelling manufacturers to reformulate or risk delisting. Discounters and hard discounters respond with dedicated clean-label tiers that compress margins for legacy brands.
- Online Retailers:Digital platforms enable direct-to-household subscription models for premium functional blends with transparent ingredient disclosures. Poland and Romania present underdeveloped penetration where modern retail expansion and rising disposable incomes create first-mover positioning opportunities.
- Health Food Stores:Pharmacy and wellness channels command price premiums for botanical-infused formulations with EFSA-permitted nutrition claims.
- Convenience Stores:Smaller-format bottles and single-serve pouches address immediate consumption occasions in urban transit corridors.
Supermarkets retain volume leadership; online retailers hold the steepest expansion curve.
End User:
Application context determines formulation specifications from standardized foodservice brix levels to customizable juice bar preparations.
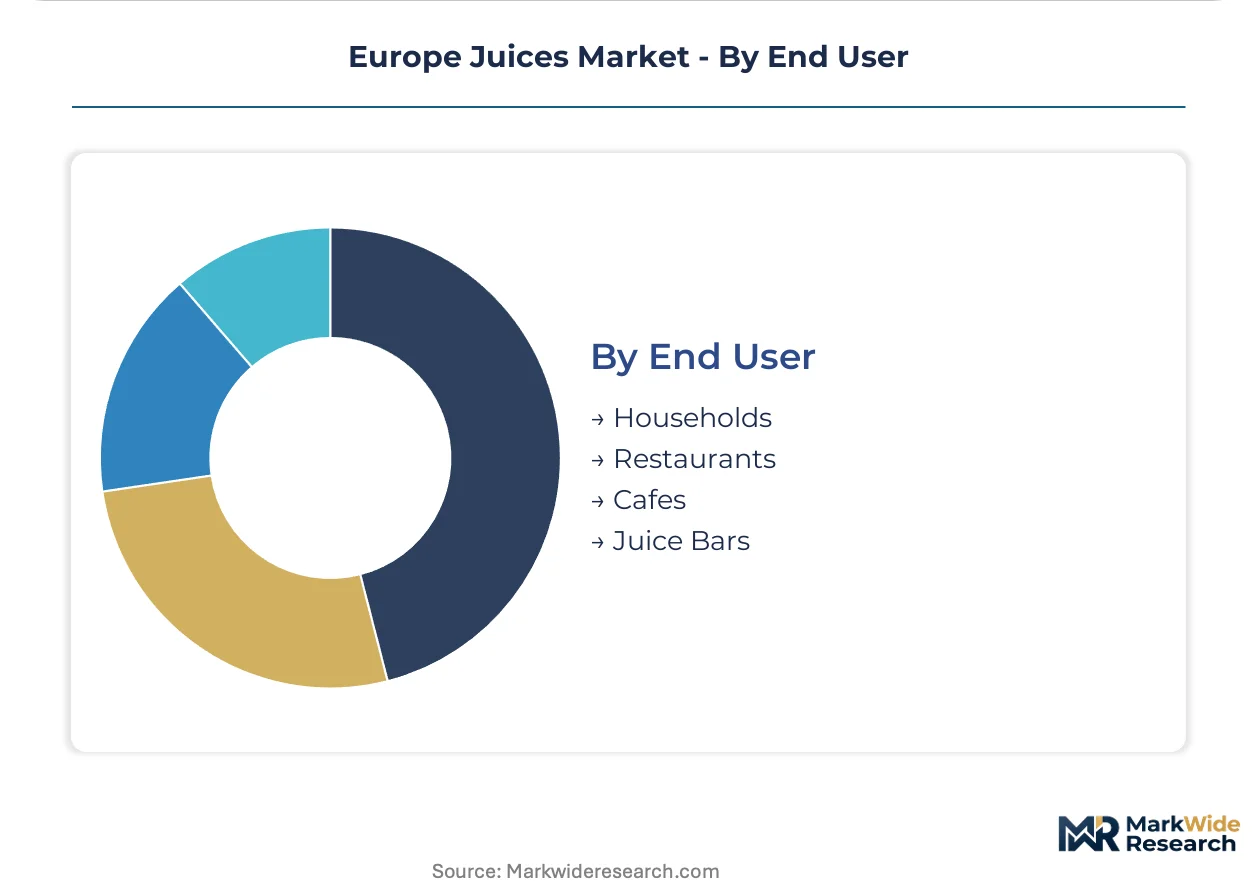
- Households:European households represent the primary consumption segment where adoption concentrates around health-conscious urban demographics. EFSA nutrition claims regulation and front-of-pack labeling schemes in France, Germany, and the UK require parallel packaging runs that complicate inventory management for multi-country suppliers.
- Restaurants:Foodservice operations demand consistent brix standardization for menu cost control and batch reproducibility.
- Cafes:Beverage-forward hospitality venues source both ready-to-serve and concentrate formats for operational flexibility.
- Juice Bars:Custom preparation sites emphasize fresh-pressed positioning with single-origin sourcing disclosures that satisfy transparency expectations in German-speaking markets.
Households retain volume leadership; juice bars hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish citrus processors ship concentrated orange base stocks to German bottlers who reformulate for EFSA-compliant health claims. Mediterranean sourcing corridors feed Central European manufacturing clusters where sugar reduction mandates are tightening fastest.
Germany
Health-conscious urban households in Berlin and Hamburg drive demand for functional blends with transparent ingredient disclosures. EFSA nutrition claims regulation enables cross-border marketing consistency for reformulated low-sugar lines. The Rhine-Main manufacturing corridor hosts Eckes-Granini production assets serving Central European distribution networks.
France
Nutri-Score front-of-pack labeling shapes procurement decisions by Paris-based retail buyers enforcing standards ahead of EU deadlines. ANSM oversight of food contact materials influences carton substrate selection for ambient distribution. The Pays de la Loire orchard belt supplies regional apple juice raw materials to domestic processors.
Italy
Mediterranean citrus groves in Sicily and Calabria anchor orange juice concentrate supply for European blending operations. EU Farm to Fork Strategy sugar reduction timelines compress formulation schedules for Emilia-Romagna-based processors. Conserve Italia exemplifies national-scale integration from southern sourcing to northern packaging.
Spain
Valencian and Murcian citrus belts dominate raw material exports to German and French bottlers. Climate variability and irrigation constraints create input cost instability for processors dependent on single-origin sourcing. The Mediterranean port infrastructure accelerates concentrate shipment velocity to northern European manufacturing hubs.
Poland
Rising disposable incomes in Warsaw and Kraków create first-mover positioning for premium juice penetration. Underdeveloped modern retail infrastructure relative to Western Europe leaves whitespace for functional blend expansion. Central European orchard networks provide regional apple sourcing proximity for domestic bottling operations.
Europe Juices Market Competitive Landscape
On the supply side, the industry is consolidating around three structural tiers: multinational beverage conglomerates with reformulated legacy portfolios, mid-cap private-label specialists competing on scale flexibility, and regional not-from-concentrate purveyors commanding premium positioning. Strategic archetypes include scale-driven co-manufacturers, brand-heritage bottlers, and cold-processing technology adopters. Dominant competitive moves encompass portfolio diversification into functional botanical blends and backward integration into Mediterranean citrus sourcing.
Within the private-label manufacturing tier, Refresco Group N.V. and Refresco Deutschland GmbH exemplify scale-driven co-manufacturing archetypes serving major retail procurement specifications. Eckes-Granini Group GmbH anchors the not-from-concentrate premium segment from its German production footprint. PepsiCo Inc. occupies a reformulation-focused position leveraging Tropicana heritage through lower-sugar line adaptations.
| Leading Market Players |
|---|
| Refresco Group N.V. |
| Riha WeserGold Getränke GmbH & Co. KG |
| Eckes-Granini Group GmbH |
| Conserve Italia |
| Refresco Deutschland GmbH |
| The Coca-Cola Co. |
| J. García Carrión S.A. |
| Parmalat |
| PepsiCo Inc. |
| Others |
Pricing and Supply Chain Analysis
Spanish and Italian citrus concentrate supply anchors margin capture for northern European bottlers, with Mediterranean sourcing proximity creating tiered pricing power that concentrates value downstream with reformulation-capable processors. German and French retail procurement specifications for EFSA-compliant health claims compress margins for undifferentiated concentrate traders while rewarding cold-processing technology adopters.
Pricing Analysis
Thermal pasteurization equipment carries legacy pricing discounts against high-pressure pascalization lines, with not-from-concentrate premiums widening as German health-conscious households demand cleaner labels. Three-tier pricing structure across premium cold-pressed, standard NFC, and economy reconstituted segments separates buyers by nutritional literacy and channel access. Pricing pressure stems from EU Sugar Reduction Framework compliance costs and front-of-pack labeling adaptation. Discounters and hard discounters exhibit highest price sensitivity; pharmacy and wellness channels show lowest.
Supply Chain Analysis
Refresco Group and Eckes-Granini production assets concentrate contract-manufacturing capacity across Germany, Netherlands, and Spain, with co-manufacturing scale determining shelf access for private-label and branded portfolios. Raw material flows draw from Sicilian and Valencian citrus belts, Polish apple orchards, and Central European botanical suppliers. Single-origin sourcing from Mediterranean groves creates climate-driven commodity volatility. Distribution runs through German and French supermarket networks with expanding online retail direct-to-household subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's juice sector faces high-growth disruption from EU Farm to Fork Strategy sugar reduction mandates and cold-processing technology virtualization that collapses barriers between ambient and chilled supply chains.
For Market Incumbents: Harden formulation expertise retention through competitive compensation for food technologists capable of maintaining taste profiles under reduced-sugar thresholds. Deepen backward integration into Spanish citrus sourcing to secure concentrate supply against climate volatility. EFSA nutrition claims compliance and clean-label procurement specifications from German retail buyers constitute the primary threat vectors requiring defensive investment. For New Entrants and Emerging Players: Poland and Romania present geographic underpenetration where rising disposable incomes and underdeveloped modern retail infrastructure create whitespace for premium functional blend introduction. Botanical-infused adaptogenic formulations targeting pharmacy channels offer the most penetrable segment given price tolerance and regulatory clarity. Direct-to-household digital subscription models bypass incumbent shelf dominance. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap cold-processing technology adopters with regional brand equity and reformulation capabilities aligned to EU Sugar Reduction Framework timelines. Long-term viability centers on sustainable material sourcing positions ahead of EU Green Deal packaging mandates. Cold-processing equipment retrofit rates and EFSA health claim application approvals signal inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Investment | EFSA-compliant low-sugar lines secure shelf placement ahead of statutory deadlines. |
| Cold-Processing Retrofit | High-pressure pascalization equipment unlocks premium positioning against thermal pasteurization. |
| Backward Integration | Mediterranean citrus grove control reduces concentrate price volatility exposure. |
| Sustainable Packaging Transition | Biodegradable carton sourcing aligns with EU Green Deal procurement specifications. |
| Digital Subscription Launch | Direct-to-household models bypass German supermarket network consolidation. |
Research Methodology
The analysis maps citrus, mixed fruit, apple, and grape juice sub-sectors, each validated through production directors at bottling facilities, category buyers at German and French retailers, and regulatory affairs specialists navigating EFSA nutrition claims. Primary interviews with supply chain planners and cold-processing equipment vendors combined with secondary validation from EFSA guidance documents, EU Farm to Fork Strategy publications, and national sugar tax implementation records. Bottom-up volume triangulation against top-down category value estimates anchored projection reliability.
Fixed assumptions held EU Sugar Reduction Framework enforcement timelines and EFSA health claim approval standards constant while varying cold-processing adoption rates and Polish retail modernization trajectories. Segmentation modeling spanned product formulation, packaging preservation technology, distribution channel concentration, and end-use application context. CAGRs derived from historical volume elasticities applied to projected household penetration curves and foodservice recovery patterns. Mediterranean climate variability indices and German retail procurement specification timelines served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by private-label specialists or accelerated EFSA claim approvals for botanical additives would shift outcomes. Regulatory timeline delays, REACH compliance cost escalation, or sustained citrus belt drought conditions present specific revision risks. Quarterly review of EFSA guidance updates, German retail buyer procurement circulars, and Valencian harvest yield reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Craft Soda Market
Beverages
Packaged Milkshake Market
Beverages
US and Canada Tonic Water Market
Beverages
Pineapple Juice Market
Beverages
BBQ Charcoal Market
Beverages
Electrolyte Mixes Market
Beverages
Rose Floral Water Market
Beverages
Sparkling Water Market
Beverages
United States Sports and Energy Drinks Market
Beverages
Fruit Water Market
Beverages
Italy Probiotic Drinks Market
Beverages
India Sports Drinks Market
Beverages
Beverage Cooler Market
Beverages
Vegetable Juice Market
Beverages
Ready to Drink Margarita Market
Beverages
Global Soda Maker Market