
 Commercial Sparkling Water Dispenser Market | 2026-2036
Commercial Sparkling Water Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Sparkling Water Dispenser Market Analysis
Asset-light leasing and subscription-based financing is tilting competitive dynamics toward providers who can bundle hardware, CO2 replenishment, and maintenance into predictable monthly fees. SodaStream International Ltd. leverages its direct-to-consumer heritage to build commercial channel partnerships. PepsiCo, Inc. anchors its position through foodservice distribution networks that place dispensers in captive traffic environments. Waterlogic Holdings Limited specializes in plumbed-in hydration systems, extending its technical competence from still to carbonated delivery.
A commercial sparkling water dispenser is a plumbed or reservoir-fed appliance that injects food-grade CO2 into chilled potable water to produce on-demand carbonated water, typically operating at 3-5 bar pressure with integrated filtration and temperature control. The primary commercial purpose is to eliminate bottled water logistics while providing customizable carbonation levels in high-traffic settings. Countertop units dominate current installation volumes in offices and restaurants where floor space commands premium allocation. Freestanding models capture expanding hotel and gym deployments where lobby visibility and self-service convenience drive placement decisions. Smart dispensing technology with IoT-enabled consumption tracking and predictive maintenance represents the fastest-growing segment as facility managers prioritize operational transparency.
The US FDA governs food-contact materials and CO2 purity standards for commercial beverage equipment, while the EPA Safe Drinking Water Act provisions shape municipal water quality assumptions that underpin filtration system design. The EU F-Gas Regulation constrains refrigerant choices in cooling systems, indirectly affecting manufacturer R&D allocation and product certification pathways. Stakeholders must monitor how evolving extended producer responsibility frameworks in multiple jurisdictions redefine ownership obligations for end-of-life equipment and CO2 cylinder recovery.
Market Dynamics
Plumbed-in carbonation systems are displacing bottled water logistics as corporate sustainability mandates and municipal procurement rules converge. The shift compresses replacement cycles and redirects facility budgets toward service-integrated hardware.
Growth Catalysts
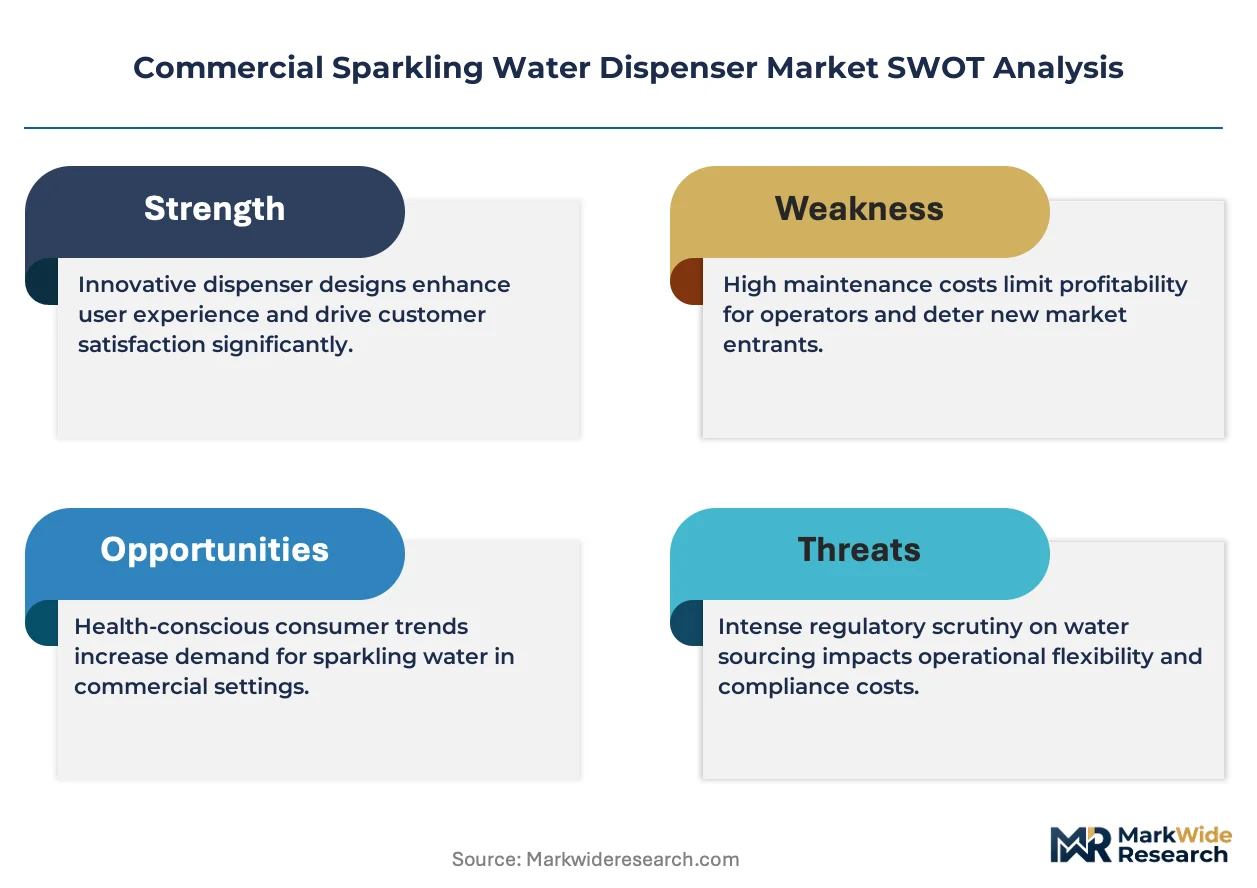
- EU Single-Use Plastics Directive:National bans on bottled water in public facilities redirect procurement budgets toward plumbed-in systems. Municipalities accelerate tender processes to meet compliance deadlines.
- Workplace hydration standards:German facility managers upgrade breakroom infrastructure to meet employee wellness certifications. Carbonation customization becomes a retention tool in tight labor markets.
- IoT-enabled predictive maintenance:Sensor networks reduce downtime and service costs. Facility operators prioritize transparent consumption tracking for ESG reporting.
Market Restraints
- Food-grade CO2 supply concentration:Industrial gas distributors control cylinder replenishment networks. Regional shortages disrupt service continuity for leased units.
- Refrigerant constraints under EU F-Gas Regulation:Cooling system redesigns extend product certification timelines. Manufacturers allocate R&D budgets to alternative refrigerant pathways.
- Tap water quality variance:Municipal infrastructure gaps in secondary cities necessitate upgraded filtration. Installation costs rise where pre-treatment is required.
Strategic Opportunities
- Hotel lobby deployments:Freestanding units capture guest-facing visibility. Self-service convenience differentiates mid-tier properties from competitors.
- Outcome-based leasing models:Subscription pricing bundles hardware, CO2, and maintenance into predictable fees. CFOs favor opex treatment over capital allocation.
- Smart building integration:API connectivity with facility management platforms enables automated reordering. Real estate investment trusts pilot centralized monitoring across portfolios.
Industry Challenges
- Certification timeline compression:NSF/ANSI 42 and 53 testing for filtration components delays product launches. Labs face backlog from concurrent appliance categories.
- Legacy plumbing compatibility:Older commercial buildings require pressure booster installation. Project margins erode where infrastructure surveys underestimate retrofit complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Sparkling Water Dispenser Market |
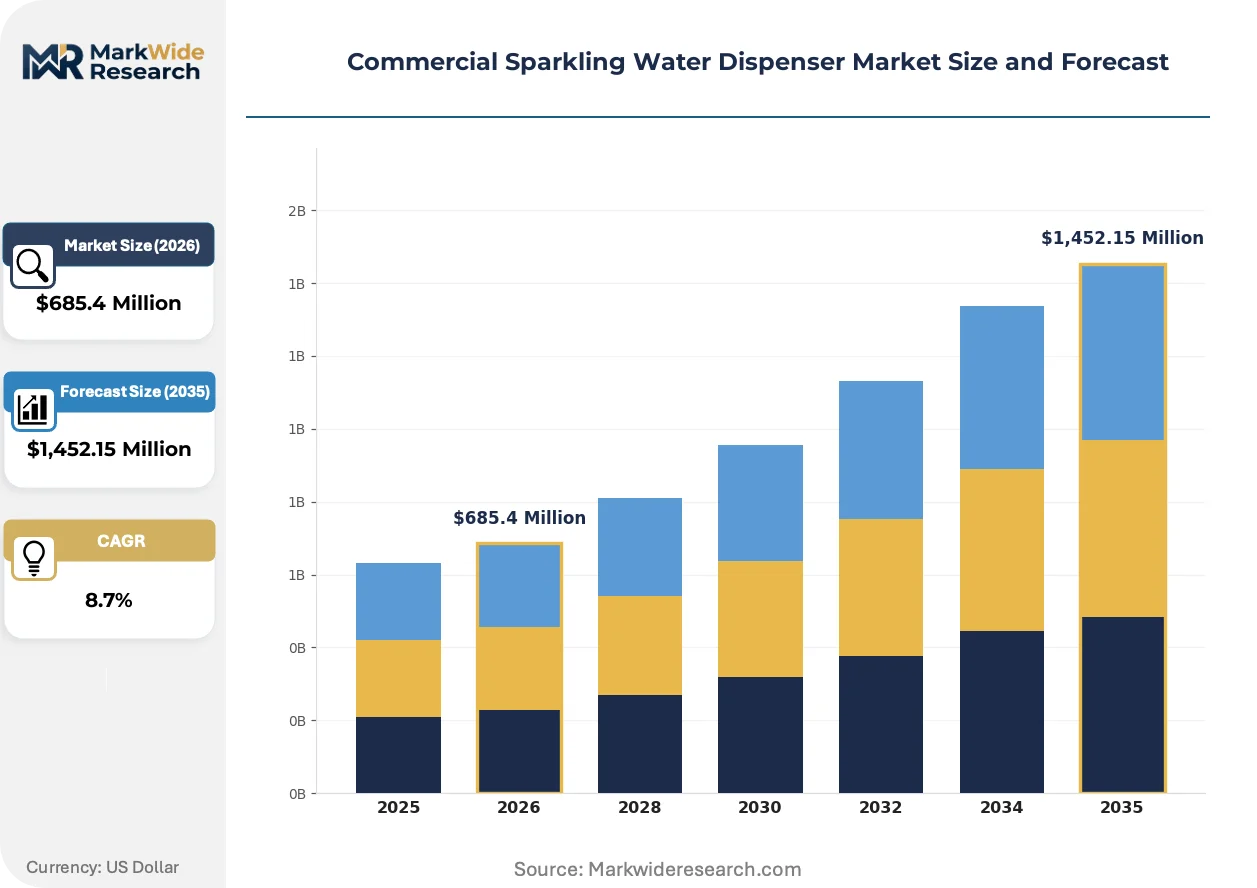
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Freestanding, Built-in, Wall-mounted End User: Restaurants, Offices, Hotels, Gyms Distribution Channel: Direct Sales, Online Retail, Specialty Stores, Wholesalers Technology: CO2 Injection, Carbonation Control, Multi-functional, Smart Dispensing |
| Companies Covered | SodaStream International Ltd., PepsiCo, Inc., Nestlé Waters, Waterlogic Holdings Limited, Elkay Manufacturing Company, BRITA GmbH, Coca-Cola Company, Primo Water Corporation, Culligan International Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Sparkling Water Dispenser Market Emerging Trajectories
Connected dispensing infrastructure is digitizing operational workflows across facility management. Three convergent developments reshape how carbonation systems are specified, monitored, and monetized.
Sensor-embedded dispensers is digitizing consumption patterns and maintenance scheduling. Corporate real estate teams in Germany and the Netherlands deploy fleet-wide dashboards to track per-location usage. The data stream enables dynamic CO2 replenishment routing and compresses service response times from days to hours.
The EU F-Gas Regulation constrains hydrofluorocarbon refrigerants in cooling systems. Manufacturers pivot to hydrocarbon or CO2-based alternatives, extending engineering cycles by 8-14 months. Countertop units with smaller thermal loads reach certification first, creating a temporary product mix skew toward compact form factors.
Facility managers now specify dispensers through managed service contracts rather than capital purchase. Foodservice distributors capture this shift by bundling hardware with preventive maintenance and consumable replenishment. The model concentrates most visibly in North American corporate headquarters, where sustainability officers negotiate enterprise-wide installations.
Commercial Sparkling Water Dispenser Market Segmentation
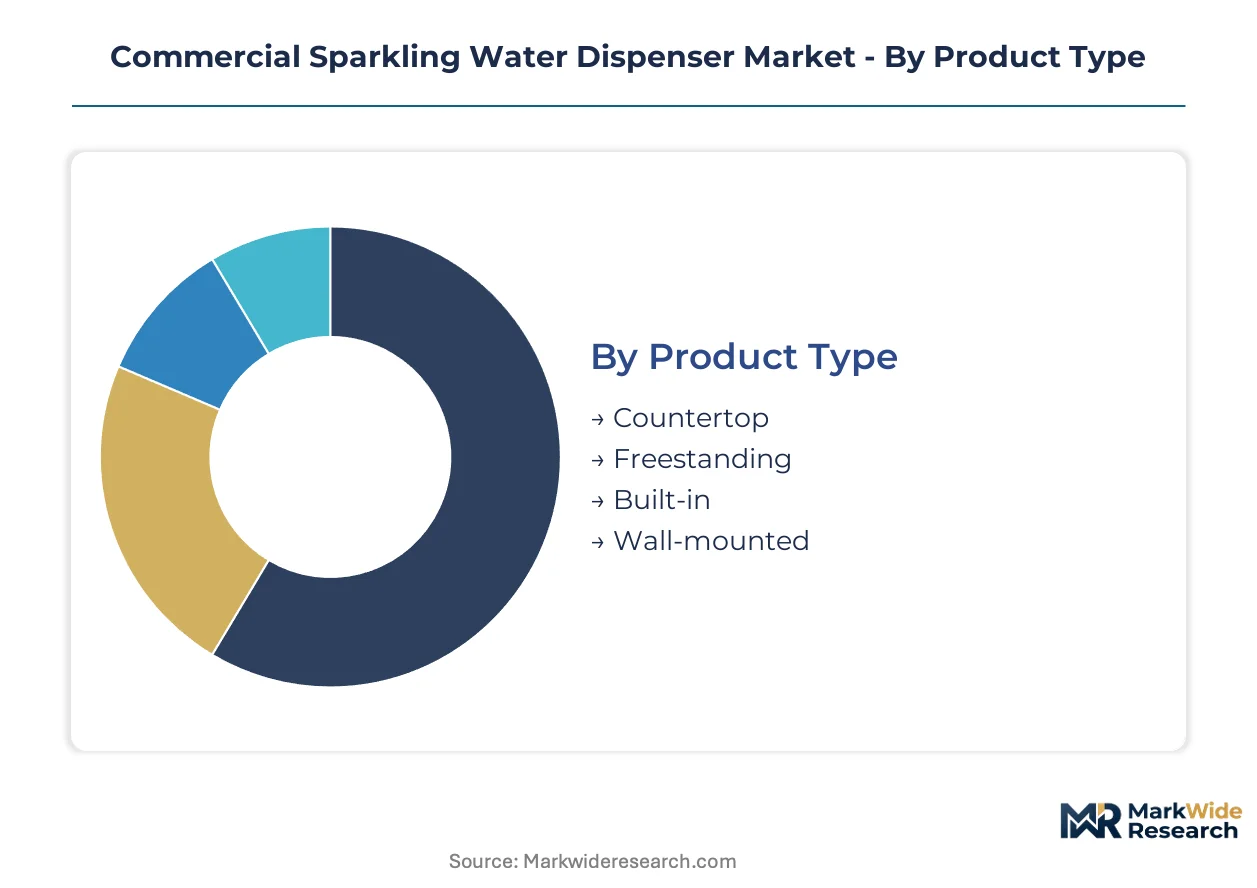
Dispenser procurement varies sharply across deployment contexts. Facility managers match form factor to traffic density, while technology choices reflect operational sophistication and ESG reporting requirements.
Product Type:
Countertop and freestanding units anchor the use-case spectrum from space-constrained breakrooms to high-visibility lobbies.
- Countertop:Compact units operating at 3-5 bar pressure integrate filtration and chilling in under-counter footprints. Corporate offices in Germany specify these for workstation-adjacent hydration points where floor space commands premium allocation and lease agreements prohibit structural modifications.
- Freestanding:Self-contained systems with elevated dispensing height and branded cladding serve guest-facing applications. Hotel lobbies in France deploy these for self-service convenience that differentiates mid-tier properties, though EU F-Gas Regulation refrigerant constraints extend certification timelines for cooling system redesigns.
- Built-in:Under-counter carbonation modules with remote dispensing taps suit premium kitchen installations where aesthetic integration outweighs mobility.
- Wall-mounted:Space-saving configurations for narrow corridors and retrofit environments where floor placement is impractical.
Established volume favors countertop; emerging adoption favors freestanding.
End User:
Customer type determines service integration depth and contract structure preferences.
- Offices:Enterprise accounts drive subscription-based leasing with bundled CO2 replenishment and predictive maintenance. German workplace hydration standards accelerate replacement cycles as facility managers pursue employee wellness certifications.
- Restaurants:Foodservice operators prioritize throughput and flavor customization for menu integration. Front-of-house placement in bistros and cafés demands quiet operation and rapid carbonation cycles.
- Hotels:Mid-tier properties capture guest loyalty through lobby visibility. Self-service models reduce labor costs while supporting sustainability narratives in corporate travel segments.
- Gyms:High-traffic fitness centers specify durable touchless dispensing for hygiene compliance. Post-workout hydration stations command premium placement in wellness-focused chains.
Contract sophistication concentrates in offices; volume growth climbs fastest in hotels.
Distribution Channel:
Channel selection reflects buyer scale and technical support requirements.
- Direct Sales:Enterprise accounts negotiate fleet-wide installations with dedicated account management. Real estate investment trusts pilot centralized monitoring across portfolios through manufacturer-direct API integration.
- Specialty Stores:Regional distributors serve independent restaurants with localized service networks and rapid parts availability.
- Wholesalers:Foodservice distribution networks place dispensers in captive traffic environments through existing beverage equipment relationships.
- Online Retail:Smaller offices and gyms procure standardized units through e-commerce platforms with self-installation support.
Service depth favors direct sales; transaction velocity favors online retail.
Technology:
Capability tier separates operational transparency from basic functionality.
- Smart Dispensing:IoT-enabled sensor networks transmit consumption data and predictive maintenance alerts to facility management platforms. Corporate real estate teams in the Netherlands deploy fleet-wide dashboards that compress service response times from days to hours.
- Carbonation Control:Variable pressure systems allow end-user customization of bubble intensity. Restaurants leverage this for menu differentiation and customer retention.
- CO2 Injection:Standard fixed-pressure carbonation meets baseline requirements for cost-sensitive installations with predictable usage patterns.
- Multi-functional:Integrated still and sparkling delivery with temperature variants reduces equipment footprint in space-constrained environments.
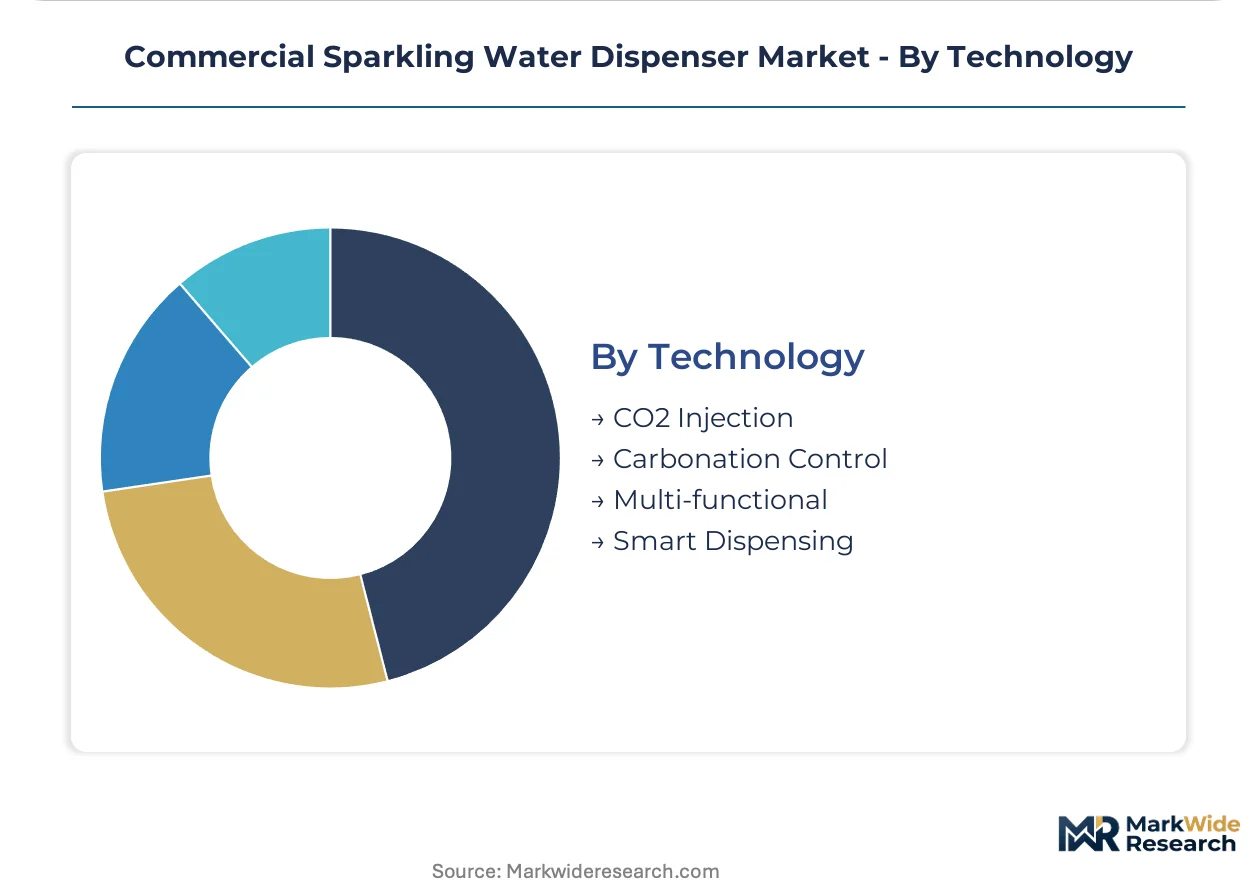
Deployment scale favors CO2 injection; margin expansion favors smart dispensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Single-Use Plastics Directive and parallel national bans on bottled water procurement are redirecting facility budgets toward plumbed-in carbonation systems across multiple jurisdictions. Corporate sustainability mandates and municipal procurement rules now converge to accelerate replacement cycles in high-income markets.
Germany
Workplace hydration standards and employee wellness certifications drive enterprise adoption of countertop units in Frankfurt and Munich corporate campuses. The EU F-Gas Regulation constrains refrigerant choices, extending certification timelines for cooling system redesigns. Bavarian facility managers bundle carbonation customization into retention strategies amid tight labor markets.
United States
Corporate headquarters in Chicago and Manhattan specify subscription-based leasing with predictive maintenance and consumption tracking. The FDA governs food-contact materials and CO2 purity standards for commercial beverage equipment. Foodservice distributors in Texas and California capture channel share by placing dispensers in captive traffic environments.
France
Mid-tier hotel properties in Paris and Lyon deploy freestanding units for lobby visibility and guest-facing sustainability narratives. National procurement rules for public facilities accelerate tender processes to meet EU directive compliance deadlines. The Occitanie region sees concentrated retrofit activity in older commercial buildings requiring pressure booster installation.
Netherlands
Corporate real estate teams in Amsterdam and Rotterdam deploy fleet-wide IoT dashboards that compress service response times from days to hours. The EU Green Deal implementation shapes municipal water quality assumptions for filtration system design. Smart building integration pilots emerge across Randstad commercial portfolios.
United Kingdom
London financial services firms specify plumbed-in systems to eliminate bottled water logistics from ESG reporting scopes. Extended producer responsibility frameworks under consultation redefine ownership obligations for end-of-life equipment recovery. Birmingham and Manchester facility managers prioritize operational transparency through connected dispensing infrastructure.
Commercial Sparkling Water Dispenser Market Vendor Landscape
On the supply side, the industry is consolidating around providers who can bundle hardware, CO2 replenishment, and maintenance into predictable monthly fees. The competitive terrain separates legacy beverage conglomerates with foodservice distribution networks from specialized hydration system manufacturers with technical competence in plumbed-in delivery. Three archetypes dominate: diversified beverage multinationals leveraging existing channel relationships, pure-play hydration specialists extending from still to carbonated systems, and direct-to-consumer heritage brands building commercial channel partnerships. Dominant competitive moves include strategic partnerships with facility management platforms and geographic expansion through asset-light leasing models.
Within the diversified beverage tier, PepsiCo, Inc. and Coca-Cola Company occupy positions anchored by foodservice distribution networks that place dispensers in captive traffic environments. SodaStream International Ltd. exemplifies the direct-to-consumer heritage archetype now building commercial channel partnerships. Waterlogic Holdings Limited represents the specialized hydration system fabricator extending technical competence from still to carbonated delivery.
| Leading Market Players |
|---|
| SodaStream International Ltd. |
| PepsiCo, Inc. |
| Nestlé Waters |
| Waterlogic Holdings Limited |
| Elkay Manufacturing Company |
| BRITA GmbH |
| Coca-Cola Company |
| Primo Water Corporation |
| Culligan International Company |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese compressor manufacturing is compressing margins for cooling system integrators while simultaneously enabling aggressive pricing postures among European and North American dispenser assemblers who source these components. This utilization dynamic rewards buyers with volume scale while squeezing smaller regional fabricators who lack procurement leverage against tier-one suppliers.
Pricing Analysis
Certification level creates the primary spread across the product spectrum, with NSF/ANSI 42 and 53 filtration tiers commanding substantial premiums over basic carbonation units. Three-tier pricing structure separates enterprise-grade smart dispensing with IoT integration from standard plumbed-in units and economy reservoir-fed models. Pricing pressure stems from foodservice distributor consolidation, which extracts volume rebates and compresses project margins for equipment-only vendors. Small independent restaurants exhibit acute price sensitivity, whereas German corporate headquarters prioritize total cost of ownership and service bundling over unit economics.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates risk planning for electronic control module sourcing. Component manufacturing concentrates in China for compressors and sensors, Germany for precision carbonation valves, and Italy for aesthetic cladding and housing materials. The supply chain draws from food-grade CO2 industrial gas networks, stainless steel food-contact tubing, and refrigerant gases constrained by EU F-Gas Regulation quotas. Single-source vulnerability persists in IoT connectivity chipsets where semiconductor allocation prioritizes automotive and consumer electronics. Distribution runs through foodservice equipment wholesalers and direct manufacturer fleets for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial sparkling water dispenser market sits in early-cycle expansion as municipal single-use plastic bans in Germany, France, and the Netherlands redirect public procurement budgets toward plumbed-in infrastructure at accelerating velocity.
For Market Incumbents: Build switching-cost moats through API-integrated fleet management platforms that embed dispensers into smart building ecosystems. Incumbents should consolidate regional service networks to capture CO2 replenishment economics and preempt emerging entrants from achieving route density. The threat of direct-to-consumer heritage brands building commercial channel partnerships demands defensive certification investment in EU F-Gas Regulation-compliant cooling systems.
For New Entrants and Emerging Players: Establish a beachhead in mid-tier French hotel properties where lobby visibility requirements favor freestanding form factors and incumbent penetration remains shallow. White-space targets include UK financial services breakrooms pursuing ESG reporting transparency and Dutch corporate real estate portfolios piloting centralized monitoring. A subscription-first go-to-market angle with bundled maintenance and predictive analytics bypasses capital budget friction.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light leasing models as hardware-as-a-service structures displace capital purchase. Long-term viability favors providers who control CO2 replenishment logistics and capture recurring revenue streams. Acquisition targets should display technical competence in plumbed-in hydration systems with established municipal tender relationships. The signal to watch is smart building integration adoption rates in Randstad and London commercial portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Building API Integration | Enables automated CO2 reordering and fleet-wide consumption dashboards for corporate real estate teams. |
| EU F-Gas Regulation Compliance Pathway | Accelerates certification timelines for hydrocarbon refrigerant cooling systems ahead of competitor redesigns. |
| Outcome-Based Leasing Model | Converts capital expenditure to operational expenditure, matching CFO preference in North American headquarters. |
| Foodservice Distribution Partnership | Places dispensers in captive traffic environments through existing beverage equipment relationships. |
| CO2 Cylinder Recovery Program | Anticipates extended producer responsibility frameworks redefining end-of-life equipment ownership obligations. |
Methodological Framework
The analysis maps countertop, freestanding, built-in, and wall-mounted dispenser sub-sectors, each validated through facility managers, foodservice procurement leads, hotel operations directors, and industrial gas distributors. Primary interviews with German workplace wellness certification auditors and French municipal tender officers combined with secondary validation from EU Single-Use Plastics Directive implementation reports, EPA Safe Drinking Water Act provisions, and FDA food-contact material standards. Bottom-up unit deployment tracking and top-down facility budget allocation analysis provided triangulation across data sources.
Assumptions held fixed include regulatory compliance deadlines for EU member states and prevailing municipal water quality standards; varied conditions included corporate sustainability mandate adoption rates and smart building integration velocity. The projection horizon spans product type, end-user segment, distribution channel, and technology capability tiers. CAGRs were derived from replacement cycle compression analysis and penetration modeling across office, hotel, and gym deployment contexts. Forecast inputs incorporated food-grade CO2 supply network capacity and refrigerant transition timelines under EU F-Gas Regulation constraints.
Stress conditions across tap water quality variance, CO2 supply disruption scenarios, and certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory enforcement consistency and enterprise leasing preference durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Spring Water Market
Beverages
US and Canada Tonic Water Market
Beverages
Root Beer Market
Beverages
Water Bottle Market
Beverages
North America Juices Market
Beverages
Nitro-Infused Cola Market
Beverages
Beverage Dispenser Market
Beverages
North America Yerba Mate Market
Beverages
Bottled Deep Ocean Water Market
Beverages
Europe Ready-To-Drink Beverages Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
Beverage Cooler Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Packaged Coconut Water Market
Beverages
Europe Fruits and Vegetables Juice Market
Beverages
China Orange Juice Market