
 Global Electrolyte Drinks Market | 2026-2036
Global Electrolyte Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrolyte Drinks Market Analysis
Coconut water is expanding its share in electrolyte drink formulations as brands reduce reliance on synthetic mineral blends. PepsiCo Inc. leverages its Gatorade manufacturing infrastructure to sustain volume leadership in North American sports channels. The Coca-Cola Company anchors its position through Powerade's institutional contracts with collegiate athletic programs. Nestlé S.A. differentiates via specialized pediatric and medical hydration lines under its healthcare nutrition division.
Electrolyte drinks are aqueous beverages formulated with dissolved mineral salts—primarily sodium, potassium, magnesium, and calcium—engineered to restore ionic balance during fluid loss from exertion, heat exposure, or illness. Manufacturing involves precision osmolality calibration to optimize gastric emptying rates and intestinal absorption efficiency. Sports drinks occupy the dominant revenue position due to entrenched athletic sponsorships and locker room distribution networks. Functional beverages represent the fastest-expanding category as adaptogenic and nootropic ingredient integration attracts wellness-oriented consumers beyond traditional exercise contexts. Powders and tablets capture accelerating shelf space as portable formats reduce shipping weights and enable consumer-controlled dilution.
The FDA governs electrolyte drink labeling under beverage versus supplement distinctions, while EFSA establishes permitted health claims for mineral content across European markets. Both frameworks are tightening scrutiny on added sugar thresholds and natural-origin certification requirements. Stakeholders must monitor evolving front-of-pack labeling mandates and sugar taxation schemes that threaten conventional sports drink profitability while rewarding reformulated low-calorie alternatives.
Market Dynamics
Clean-label formulation mandates under EU and US food safety frameworks are forcing electrolyte drink manufacturers to replace synthetic mineral salts with plant-derived alternatives, compressing legacy supply chains built on petrochemical inputs.
Growth Catalysts
- EU Front-of-Pack Labeling Mandates:Nutri-Score and traffic-light systems in France and Germany are penalizing high-sugar formulations, accelerating reformulation investments toward low-calorie electrolyte portfolios.
- Medical Hydration Protocols:Hospital systems in the United States and Japan are integrating oral rehydration solutions into post-surgical recovery pathways, expanding institutional procurement volumes beyond athletic use cases.
- Precision Fermentation:Biotechnology platforms for bio-identical mineral production are reducing dependency on mined salt suppliers while enabling custom osmolality profiles for specialized hydration needs.
Market Restraints
- Potassium Chloride Supply Concentration:Canadian and Chilean potash mining consortiums control 70% of global potassium inputs, exposing electrolyte manufacturers to fertilizer-market volatility and export quota disruptions.
- Technical Limitation of Natural Preservatives:Clean-label alternatives to sodium benzoate deliver shorter shelf stability, constraining distribution radius for refrigerated coconut-water-based formulations.
- Substitution Threat from Functional Waters:Hydrogen-infused and oxygenated water brands are capturing wellness-oriented consumers seeking hydration without caloric or mineral load.
Strategic Opportunities
- Pediatric Dehydration Management:India's rural primary health centers present underpenetrated demand for low-osmolality oral rehydration salts compliant with WHO guidelines.
- Regulatory Tailwind from Sugar Taxation:Mexico's IEPS levy and South Africa's Health Promotion Levy are structurally advantaging zero-sugar electrolyte formats against conventional sports drinks.
- Direct-to-Consumer Subscription Models:Personalized hydration testing kits paired with algorithmic powder formulations are bypassing retail slotting fees and capturing lifetime value data.
Industry Challenges
- Flavor Chemist Talent Scarcity:Natural masking technologies for stevia and monk fruit off-notes require specialized formulation expertise concentrated in Swiss and Dutch flavor houses.
- ISO 22000 Certification Timelines:New manufacturing facilities face 14-18 month approval cycles for food safety management systems, delaying market entry for regional challengers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrolyte Drinks Market |
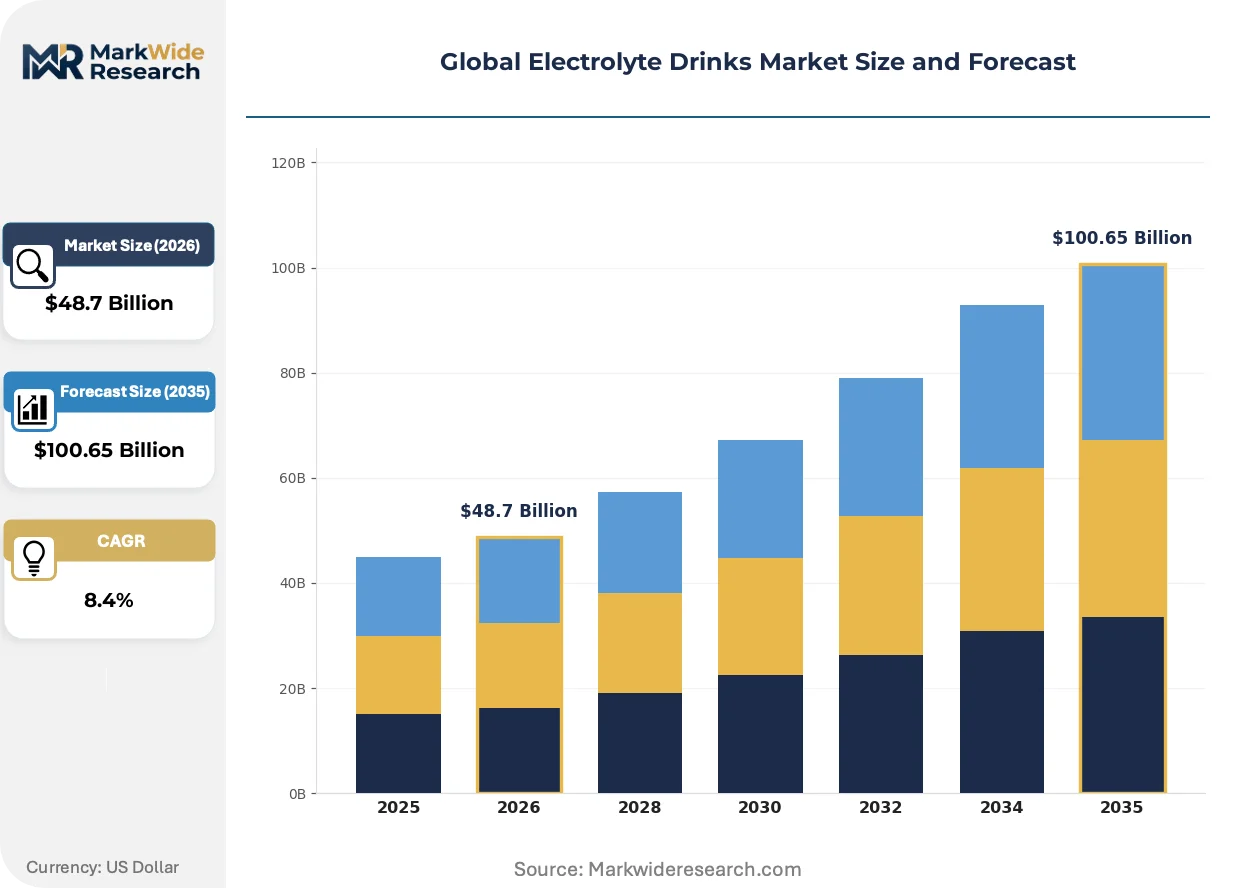
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Sports Drinks, Functional Beverages, Enhanced Waters, Coconut Water Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Shops Form: Liquid, Powders, Tablets, Gummies Packaging Type: Bottles, Cans, Pouches, Tetra Packs |
| Companies Covered | The Coca-Cola Company, PepsiCo Inc., Abbott Laboratories, Nestlé S.A., The Kraft Heinz Company, Unilever PLC, The Vita Coco Company, Nuun Hydration, liquid I.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrolyte Drinks Market Emerging Trajectories
Biotechnology-enabled ingredient sourcing and algorithmic personalization are compressing traditional R&D cycles while fragmenting mass-market positioning into micro-segmented hydration protocols.
Precision fermentation for bio-identical electrolyte minerals is electrifying supply chain economics. Startups in California and the Netherlands are scaling cellular agriculture platforms to produce sodium, potassium, and magnesium compounds without mining extraction. Functional beverage brands in Germany and Australia are adopting these inputs to secure EU organic certification and Australian Certified Organic status. The technology is electrifying competitive dynamics by collapsing the cost premium between synthetic and natural mineral sources.
EFSA's 2023 tightened health claims guidance for sodium reduction is forcing reformulation across European portfolios. The regulation now requires clinical trial evidence for electrolyte absorption rate claims, disqualifying generic sports drink marketing. Manufacturers in Italy and Spain are responding by funding university hydration physiology research to substantiate product-specific efficacy data. The policy shift is compressing marketing budgets toward scientific affairs functions.
Wellness consumers are unbundling hydration from exercise contexts, creating demand for adaptogen-infused electrolyte powders consumed during work-from-home routines. E-commerce subscriptions in the United Kingdom and Canada are displacing convenience store impulse purchases as the primary acquisition channel. This behavioral pivot is visible most acutely among knowledge workers aged 25-40 who integrate hydration protocols into productivity optimization regimens.
Global Electrolyte Drinks Market Segmentation
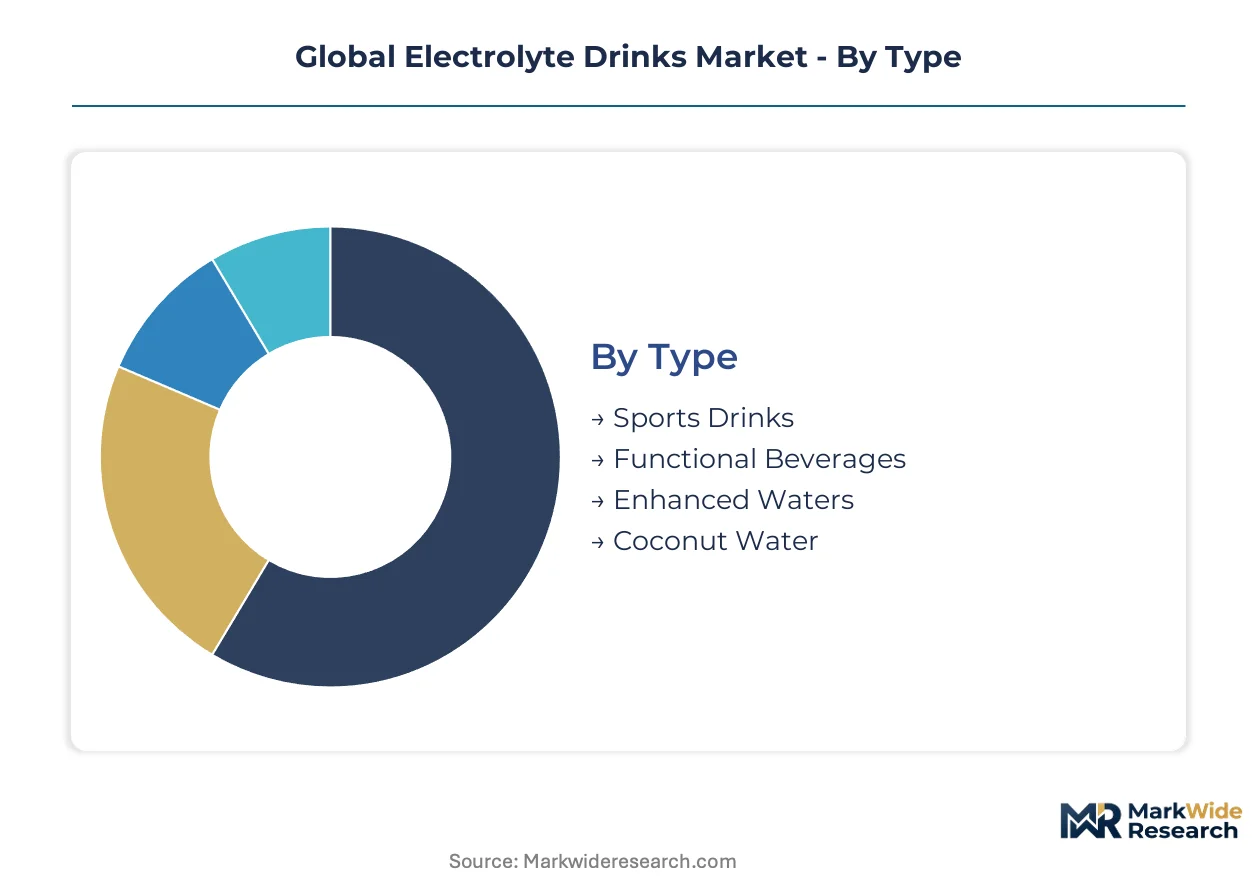
Electrolyte drink manufacturers engineer product portfolios around distinct consumption moments, channel economics, and formulation preferences. Segmentation reveals how athletic sponsorships, wellness trends, and supply chain constraints partition revenue across format and access dimensions.
Type:
Athletic intensity and ingredient transparency requirements drive format selection among institutional buyers and wellness consumers.
- Sports Drinks:Isotonic formulations calibrated to sodium concentration profiles matching sweat loss rates dominate collegiate and professional locker room procurement. PepsiCo's Gatorade and Coca-Cola's Powerade anchor institutional contracts across United States high school and university athletic programs, with sodium content between 200-700 mg per liter optimized for rapid gastric emptying.
- Functional Beverages:Adaptogen and nootropic integration attracts knowledge workers seeking hydration protocols beyond exercise contexts. Demand concentrates in Germany and the United Kingdom where EFSA health claims scrutiny rewards clinically substantiated absorption rate marketing, with magnesium and L-theanine combinations gaining fastest share among 25-40 age demographics.
- Enhanced Waters:Electrolyte-fortified still and sparkling variants target sugar-avoidant consumers in California and New York metropolitan markets.
- Coconut Water:Naturally occurring potassium and magnesium appeals to clean-label adherents, though shorter shelf stability constrains distribution radius.
Volume sits with Sports Drinks; growth tilts toward Functional Beverages.
Distribution Channel:
Channel selection reflects impulse velocity versus subscription economics and the trade-off between slotting fee exposure and customer lifetime value capture.
- Supermarkets:Grocery retail commands the largest absolute transaction volume through end-cap placements and seasonal sports calendar promotions. Walmart and Kroger in the United States, plus Carrefour in France, negotiate annual volume commitments that lock in manufacturing capacity for legacy sports drink brands.
- Online Retail:Direct-to-consumer platforms enable algorithmic personalization and bypass retail margin stacking. Amazon and specialized wellness portals in Canada and Australia capture recurring subscription revenue for powder formats, with customer data feeding R&D pipelines for flavor and mineral customization.
- Convenience Stores:Immediate consumption occasions drive refrigerated single-serve purchases at petroleum retail locations.
- Health Shops:Pharmacist and nutritionist recommendations steer medical hydration and pediatric oral rehydration salt sales.
Supermarkets retain the highest transaction frequency; Online Retail delivers the steepest expansion trajectory.
Form:
Portability requirements and osmolality control preferences segment buyers between ready-to-drink convenience and consumer-calibrated preparation.
- Liquid:Pre-mixed formulations dominate immediate consumption with established supply chains for PET and aluminum packaging. Coca-Cola and PepsiCo manufacturing infrastructure in Georgia and Florida sustains cost advantages through scale economies in aseptic filling lines.
- Powders:Lightweight shipping economics and dilution control attract fitness enthusiasts and international travelers. Brands in the Netherlands and Switzerland leverage precision fermentation mineral inputs to differentiate powder portfolios for EU organic certification compliance.
- Tablets:Effervescent formats suit gym bag and luggage portability with extended shelf stability.
- Gummies:Chewable delivery appeals to pediatric dehydration management and supplement-adjacent positioning.
Liquid commands current volume share; Powders are expanding most quickly through e-commerce subscription models.
Packaging Type:
Sustainability mandates and cold chain requirements determine material selection across ambient and refrigerated distribution networks.
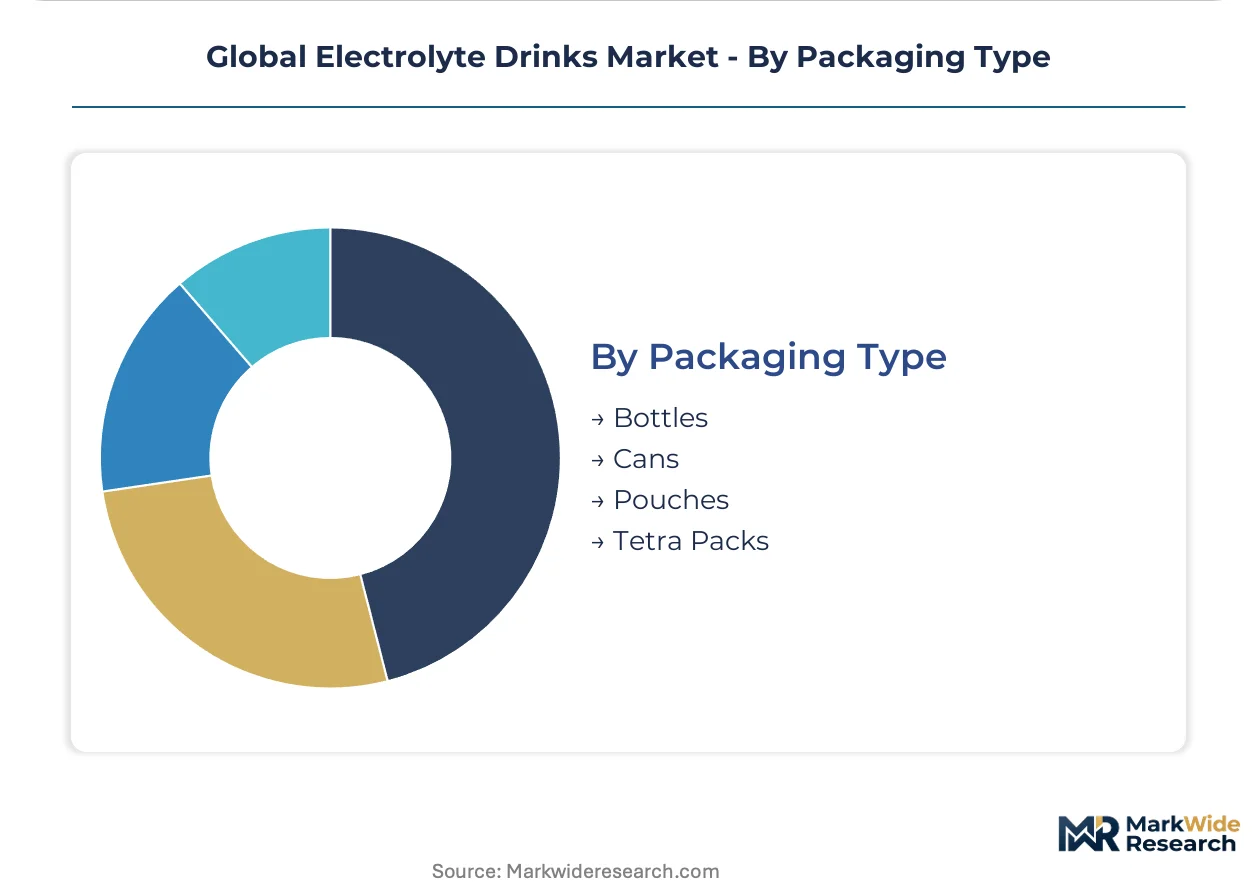
- Bottles:PET and rPET containers dominate mass-market sports drink distribution with established recycling infrastructure. California's SB 54 extended producer responsibility legislation is accelerating rPET content requirements, forcing reformulation of bottle weight specifications to maintain cost parity.
- Cans:Aluminum delivers superior chill speed and infinite recyclability for convenience store and stadium channels. Ball Corporation and Crown Holdings supply agreements with major beverage brands in Texas and Ohio lock in aluminum sheet capacity through multi-year contracts.
- Pouches:Flexible packaging reduces shipping cube for powder and liquid concentrate formats.
- Tetra Packs:Aseptic carton technology extends ambient shelf life for coconut water and medical hydration products.
Bottles retain manufacturing scale advantages; Cans gain share fastest through sustainability positioning and stadium venue contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's biomedical manufacturing tax incentive zones and free trade agreements with ASEAN neighbors are drawing electrolyte drink production capacity from European and North American multinationals seeking Asia-Pacific distribution hubs.
United States
Collegiate athletic procurement contracts and military hydration standardization drive institutional demand. FDA beverage labeling distinctions under 21 CFR 101 create compliance thresholds that favor established manufacturers with in-house regulatory affairs teams. Atlanta and Chicago anchor manufacturing clusters where aseptic filling infrastructure serves both sports drink and medical hydration lines.
Germany
EFSA health claims scrutiny and Nutri-Score front-of-pack mandates are accelerating reformulation toward low-sugar functional beverages. Federal Ministry of Food and Agriculture funding for precision fermentation research supports domestic biotechnology startups. Bavaria's Ingolstadt corridor hosts contract manufacturing facilities supplying EU organic-certified electrolyte powders to Scandinavian markets.
China
SAMR's tightened beverage labeling standards and dual carbon goals are pressuring PET packaging reduction across domestic brands. Yangtze River Delta manufacturing zones concentrate precision fermentation capacity for bio-identical mineral production. Shanghai-based e-commerce platforms are displacing traditional retail for powder format subscriptions among urban knowledge workers.
India
FSSAI fortification guidelines and Ayush Ministry integration of oral rehydration into primary health protocols expand institutional procurement. Maharashtra's Pune-Ahmednagar corridor hosts WHO-compliant pediatric dehydration manufacturing for rural health center distribution. Gujarat's Mundra port zone enables coconut water concentrate imports from Southeast Asian suppliers.
Australia
TGA therapeutic goods distinctions for medical hydration products create certification premiums for hospital system suppliers. Australian Certified Organic standards drive demand for plant-derived mineral inputs from precision fermentation platforms. Melbourne and Sydney anchor direct-to-consumer subscription fulfillment networks targeting fitness enthusiasts across Oceania.
Global Electrolyte Drinks Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with beverage conglomerates commanding institutional sports channels while biotechnology-enabled startups capture wellness-oriented direct-to-consumer growth. Market structure tilts toward consolidated leadership in ready-to-drink formats alongside fragmented competition in powders and functional additives. Three archetypes dominate: multinational beverage conglomerates with captive distribution infrastructure, healthcare nutrition specialists with clinical validation capabilities, and precision fermentation startups with bio-identical mineral platforms. Competitive dynamics center on M&A activity targeting clean-label formulation expertise and strategic partnerships between flavor houses and mineral technology providers.
Within the multinational beverage tier, PepsiCo Inc. and The Coca-Cola Company exemplify scale-driven manufacturing and sponsorship-based distribution lock-in. Nestlé S.A. occupies a position bridging consumer packaged goods and medical nutrition, with its healthcare division anchoring clinical hydration protocols. Abbott Laboratories represents the healthcare-specialist archetype, leveraging hospital system relationships and therapeutic goods regulatory pathways to differentiate from commodity sports drinks.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo Inc. |
| Abbott Laboratories |
| Nestlé S.A. |
| The Kraft Heinz Company |
| Unilever PLC |
| The Vita Coco Company |
| Nuun Hydration |
| liquid I.V. |
| Others |
Supply Flow & Price Mechanics
Premium-mid-economy pricing differentiation in electrolyte drinks manifests through formulation transparency tiers and mineral sourcing provenance, with precision fermentation inputs commanding supply chain premiums while commodity sports drinks compete on volume scale and slotting fee absorption.
Pricing Analysis
Volume-driven mass-market sports drinks trade margin for manufacturing scale, while functional beverage tiers capture premium through EFSA-substantiated absorption claims and bio-identical mineral certification. Price differentiation drivers center on clean-label certification grade and brand-sponsored clinical validation. Pricing pressure stems from EU sugar taxation schemes compressing conventional formulation profitability. Institutional buyers in collegiate athletic programs exhibit lowest price sensitivity; private-label entrants in convenience channels face highest.
Supply Chain Analysis
Direct-to-consumer subscription channels handle algorithmic personalization demand, while mass retail distribution runs through captive bottling infrastructure in Georgia and Florida. Raw material dependencies include Canadian and Chilean potash for potassium chloride, Southeast Asian coconut water concentrate, and precision fermentation outputs from California and the Netherlands. Supply chain risk concentrates in fertilizer-market volatility affecting mineral salt pricing. Geographic supply concentration in North American bottling clusters and Asian-Pacific flavor extraction facilities shapes downstream logistics configuration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolyte drink manufacturing is transitioning from petrochemical-derived mineral sourcing to biotechnology-enabled production, with precision fermentation platforms displacing legacy mined salt supply chains.
For Market Incumbents: To counter precision fermentation startups capturing EU organic certification premiums, PepsiCo and Coca-Cola should secure exclusive supply agreements with cellular agriculture platforms in California and the Netherlands. Backward integration into captive mineral production capacity insulates against potash consortium pricing volatility. For New Entrants and Emerging Players: Capture underpenetrated pediatric dehydration management in India's rural primary health centers through WHO-compliant oral rehydration salt formulations. Direct-to-consumer algorithmic personalization in Canadian and Australian subscription channels offers lowest customer acquisition cost relative to retail slotting fee exposure. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation mineral platforms given EFSA tightened health claims guidance forcing clinical substantiation investment. Long-term viability favors biotechnology-enabled ingredient suppliers with EU organic and Australian Certified Organic accreditation. Watch for FDA beverage-supplement labeling rulemaking as inflection signal for reformulation cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | California and Netherlands cellular agriculture platforms collapse synthetic-natural mineral cost premiums for EU organic compliance. |
| Direct-to-Consumer Subscription Launch | Algorithmic powder formulations bypass Walmart and Kroger slotting fees while capturing lifetime hydration data. |
| Clinical Validation Investment | University hydration physiology research substantiates EFSA-compliant absorption rate claims for functional beverage tiers. |
| Pediatric Line Extension | WHO-compliant oral rehydration salts address institutional procurement expansion in India and Japan hospital systems. |
| Sustainability Repositioning | rPET and aluminum packaging transitions respond to California SB 54 and EU extended producer responsibility mandates. |
Methodological Framework
Multi-period observation of formulation patent filings, regulatory submission timelines, and mineral sourcing contracts anchored the trend analysis, supplemented by interviews with beverage brand managers, precision fermentation R&D directors, retail category buyers, and hospital procurement officers. Secondary validation drew from FDA 21 CFR 101 guidance documents, EFSA health claims registers, SAMR beverage labeling standards, FSSAI fortification notifications, and customs trade data for potassium chloride and coconut water concentrate imports. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Segment-weighting across the analysis window applied distinct growth coefficients to sports drinks, functional beverages, enhanced waters, and coconut water categories, with further disaggregation by liquid, powder, tablet, and gummy form factors. CAGRs were derived from trend extrapolation of historical consumption patterns adjusted for regulatory inflection points. Forecast inputs included precision fermentation capacity build-out timelines and EU front-of-pack labeling mandate compliance costs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to potash mining consortium export quotas, FDA beverage-supplement reclassification, and biotechnology platform scale-up execution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Maple Water Market
Beverages
North America Fruits and Vegetables Juice Market
Beverages
Blenders Market
Beverages
US Bubble Tea Market
Beverages
Hot Cocoa Mix Market
Beverages
Fruit Water Market
Beverages
United States and Australia Coconut Water Market
Beverages
North America Cold Pressed Juices Market
Beverages
United States Soy Beverages Market
Beverages
Europe Coconut Water Market
Beverages
United States Beverage Contract Bottling and Filling Market
Beverages
Spring Water Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Asia Pacific Soy Beverages Market
Beverages
Growlers Market
Beverages
Smart Home-Based Beverage Machine Market