
 PERC Solar Cell Market | 2026-2036
PERC Solar Cell Market Size, Share, and Industry Trends Forecast 2026-2036
PERC Solar Cell Market Insights
CE marking under the EU's Construction Products Regulation is collapsing the supplier base for European project developers. LONGi Green Energy Technology leverages backward integration into polysilicon to sustain cost leadership across monocrystalline lines. JinkoSolar anchors its position through vertically integrated cell-to-module capacity in Southeast Asian hubs. Hanwha Q Cells differentiates via German-engineered quality protocols that dominate premium residential segments.
Passivated Emitter and Rear Contact (PERC) solar cells add a dielectric passivation layer and localized rear contact structure to conventional silicon architecture, boosting conversion efficiency above 23% in mass production while using standard p-type silicon wafers. The technology's primary purpose is to extract more energy per panel area in space-constrained or cost-sensitive installations. Monocrystalline PERC leads value capture due to superior efficiency premiums in utility-scale tenders, while bifacial variants are expanding fastest as trackers and albedo-optimized sites multiply returns. Ground-mounted installation types concentrate margin pools where single-axis tracking pairs with bifacial PERC to maximize yield per hectare.
FERC Order 2023 in the United States accelerates interconnection queue reforms that shape utility-scale solar deployment timelines, while China's MIIT enforces minimum efficiency thresholds that filter subscale cell producers from state-backed project pipelines. India's BIS certification mandates and the EU's CSRD disclosure rules are tightening documentation burdens for module imports. Stakeholders must monitor how carbon-border adjustment mechanisms and domestic content incentives redistribute manufacturing geography before committing to long-term supply agreements.
Market Dynamics
China's MIIT efficiency mandates are compressing the supplier base for p-type PERC cells while bifacial variants capture desert utility installations across Saudi Arabia, Australia, and Chile. This regulatory tightening intersects with raw material pass-through volatility in polysilicon to reshape competitive positioning.
Growth Catalysts
- MIIT minimum efficiency thresholds:China's GB standards filter subscale producers from state-backed pipelines, consolidating procurement around certified tier-one cell manufacturers.
- Albedo-optimized desert sites:Saudi Arabia's Red Sea Project and Chilean Atacama installations deploy bifacial PERC with single-axis tracking to multiply energy yield per hectare.
- Interconnection queue reform:FERC Order 2023 accelerates US utility-scale solar deployment timelines, pulling forward module demand from independent power producers.
Market Restraints
- Polysilicon price volatility:Metallurgical-grade silicon feedstock swings compress cell margins when long-term module contracts lock in fixed pricing.
- TOPCon substitution threat:Tunnel oxide passivated contact cells achieve higher efficiency on n-type wafers, diverting R&D capital from PERC line expansion.
- CE marking documentation burden:EU Construction Products Regulation compliance collapses the supplier base accessible to European project developers.
Strategic Opportunities
- Agrivoltaic dual-use installations:PERC modules mounted above crops in India and Southeast Asia unlock land-constrained deployment without agricultural displacement.
- Carbon-border adjustment readiness:EU CBAM implementation rewards low-carbon polysilicon sourcing, creating first-mover advantage for integrated manufacturers with renewable-powered smelters.
- Building-integrated photovoltaics:Lightweight PERC glass-glass modules penetrate commercial rooftop segments previously served by thin-film alternatives.
Industry Challenges
- Cell metallization skill scarcity:Screen printing and laser contact opening expertise concentrates in legacy manufacturing hubs, constraining greenfield line commissioning.
- BIS certification timeline compression:India's mandatory testing protocols for module imports create inventory bottlenecks during tender award windows.
- Legacy p-type wafer equipment stranding:Existing pullers and wire saws face accelerated obsolescence as n-type mono-casting displaces conventional Czochralski capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PERC Solar Cell Market |
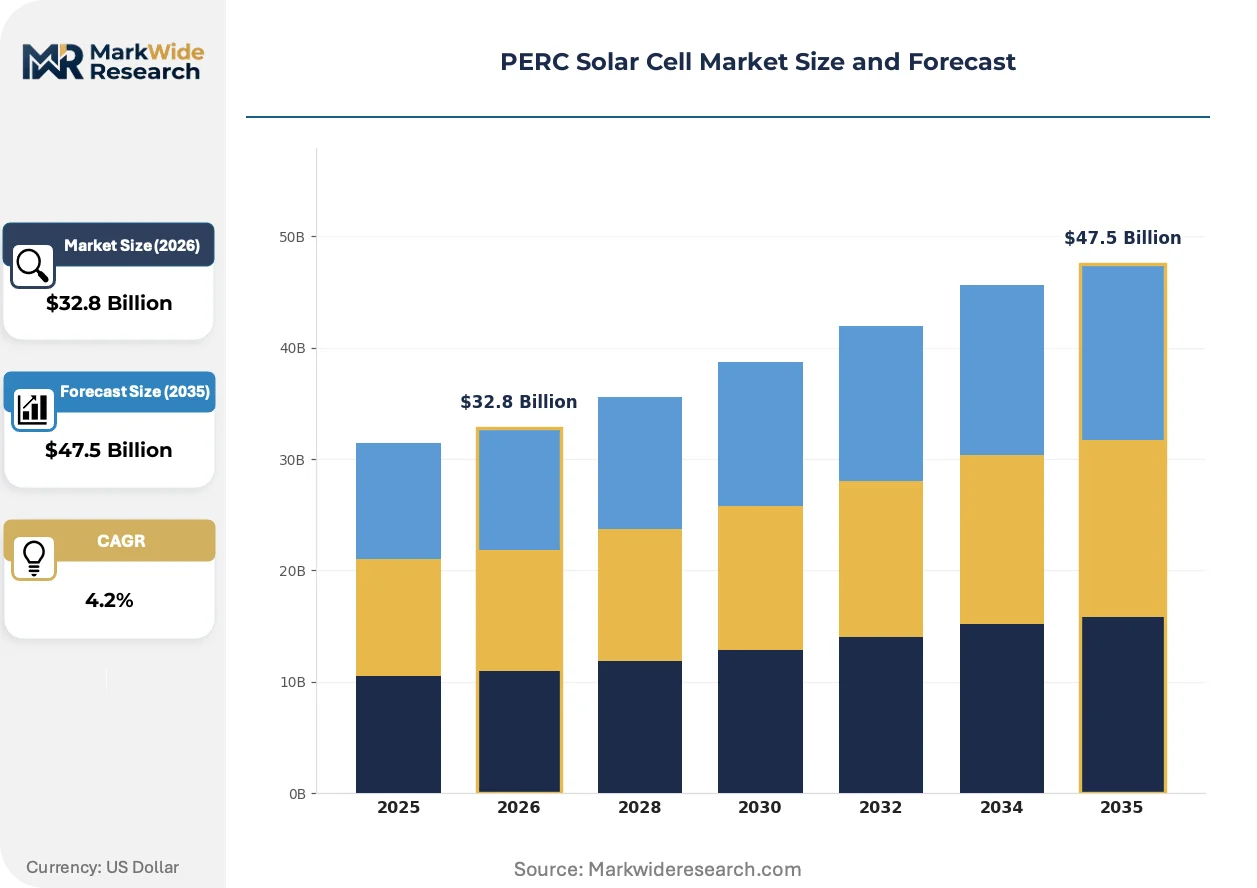
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Thin-Film Application: Residential, Commercial, Utility-Scale, Off-Grid Installation Type: Roof-Top, Ground-Mounted, Floating, Building-Integrated End User: Households, Businesses, Utilities, Government |
| Companies Covered | JinkoSolar, Risen Energy, LONGi Green Energy Technology, Hanwha Q Cells, Tongwei Co. Ltd, JA Solar, Canadian Solar, REC Solar, Trina Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PERC Solar Cell Market Trends and Innovations
Passivated emitter and rear contact architecture is decomposing into component innovations that recombine with heterojunction and TOPCon processes. This technological fragmentation is redrawing equipment vendor relationships and module warranty structures.
SE+ (selective emitter plus) laser doping is decomposing the traditional diffusion furnace bottleneck in PERC lines. Tier-one Chinese manufacturers deploy picosecond lasers to create heavily doped regions beneath front contacts without masking steps. This process simplification is compressing capex per gigawatt and enabling retrofits of legacy Al-BSF lines.
EU CSRD disclosure rules are mandating supply-chain carbon intensity reporting for photovoltaic imports. Module buyers must document embodied emissions from polysilicon through cell fabrication to qualify for green taxonomy alignment. European project developers are responding by qualifying suppliers with renewable-powered ingot production and granular traceability systems.
Aggregator-led procurement consortia are consolidating demand from distributed commercial and industrial buyers. These pooled purchasing vehicles bypass traditional distributor markups by contracting directly with cell-to-module manufacturers. The model is most visible in India's MSME rooftop segment and Germany's Mittelstand commercial installations.
PERC Solar Cell Market Segmentation
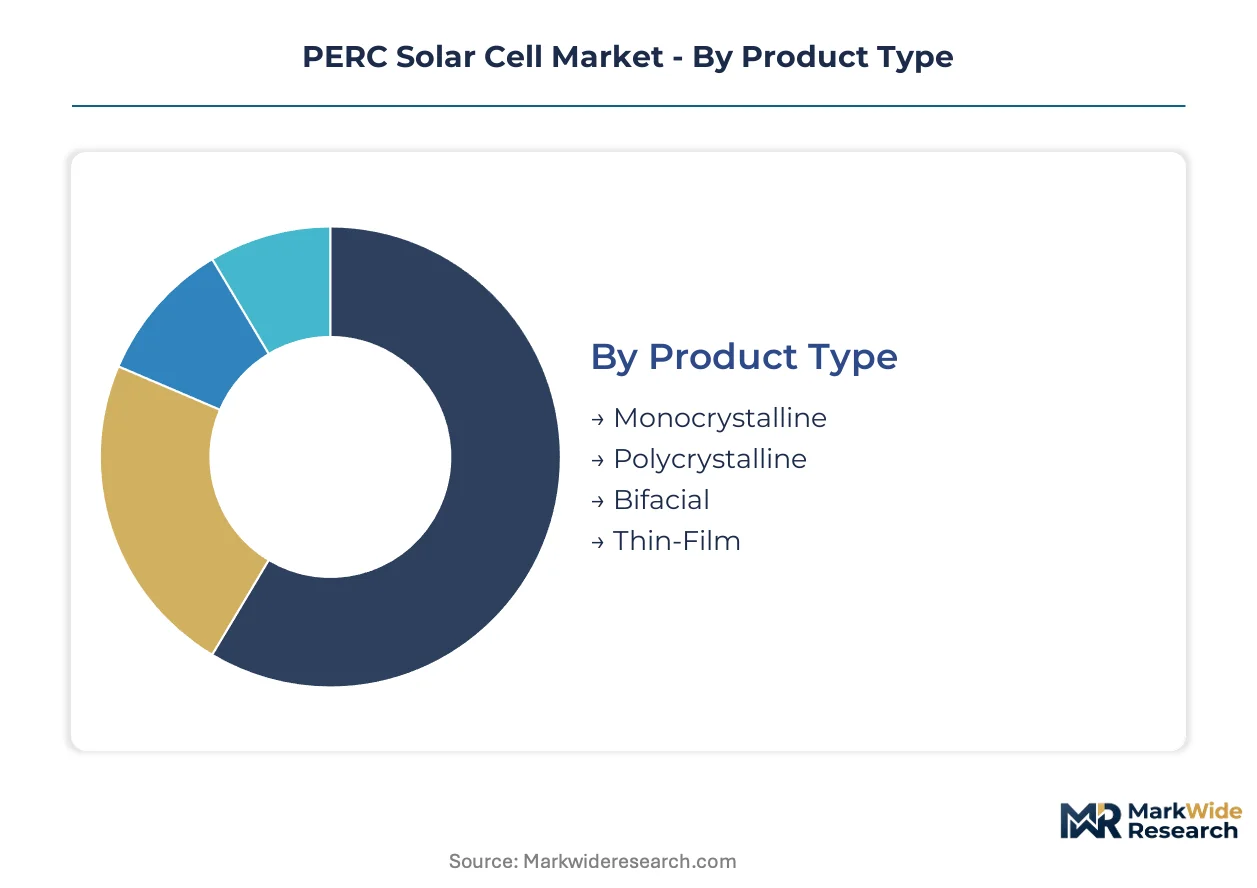
PERC solar cell procurement splits along efficiency certification tiers and installation physics, with regulatory thresholds in China, India, and the EU filtering which product architectures qualify for subsidized pipelines. Understanding these segment boundaries clarifies where margin pools concentrate versus where commoditization pressures dominate.
Product Type:
MIIT efficiency mandates and EU CE marking protocols bifurcate procurement between certified monocrystalline lines and legacy polycrystalline capacity.
- Monocrystalline:p-type Czochralski wafers with dielectric rear passivation achieve conversion efficiencies above 23% in mass production. Procurement concentrates in Chinese state-backed tenders where GB standards filter subscale producers, compressing supply around tier-one cell manufacturers with backward-integrated polysilicon.
- Bifacial:Dual-glass encapsulation captures rear-side irradiance, multiplying yields on albedo-optimized desert sites. Saudi Arabia's Red Sea Project and Chilean Atacama installations deploy these modules with single-axis tracking to maximize energy per hectare.
- Polycrystalline:Cast multicrystalline wafers with lower efficiency premiums serve cost-sensitive distributed markets in Southeast Asia and Africa where certification burdens remain lighter.
- Thin-Film:Cadmium telluride and CIGS alternatives occupy niche building-integrated segments where weight constraints outweigh efficiency priorities.
Established volume favors monocrystalline; emerging adoption favors bifacial.
Application:
Interconnection queue reforms and carbon-border mechanisms reshape demand concentration across deployment scales.
- Utility-Scale:FERC Order 2023 accelerates US grid connection timelines, pulling forward module demand from independent power producers. Single-axis tracking pairs with bifacial PERC to maximize yield per hectare on desert installations.
- Residential:German-engineered quality protocols dominate premium rooftop segments where warranty terms and aesthetic integration command price premiums. Hanwha Q Cells anchors this channel through vertically distributed installer networks.
- Commercial:Aggregator-led procurement consortia in India's MSME segment and Germany's Mittelstand bypass distributor markups through direct manufacturer contracting.
- Off-Grid:Remote mining and telecom loads in Australia and Chile drive demand for modular containerized systems with minimal grid dependency.
Margin concentration sits with utility-scale volume; policy tailwinds accelerate residential premium capture.
Installation Type:
Land-use constraints and albedo optimization determine mounting architecture selection.
- Ground-Mounted:Single-axis tracking systems dominate utility procurement in Saudi Arabia, Australia, and Chile where flat terrain and high irradiance multiply bifacial returns. This architecture captures the steepest expansion trajectory as desert utility installations multiply.
- Roof-Top:Distributed commercial and industrial deployment in India and Germany faces BIS certification bottlenecks and CSRD disclosure burdens that filter supplier bases.
- Floating:Reservoir and coastal installations in Southeast Asia unlock land-constrained markets without agricultural displacement.
- Building-Integrated:Lightweight glass-glass modules penetrate commercial rooftop segments previously served by thin-film alternatives, particularly in EU markets with strict facade aesthetic codes.
Yield optimization favors ground-mounted; regulatory compliance complexity favors building-integrated.
End User:
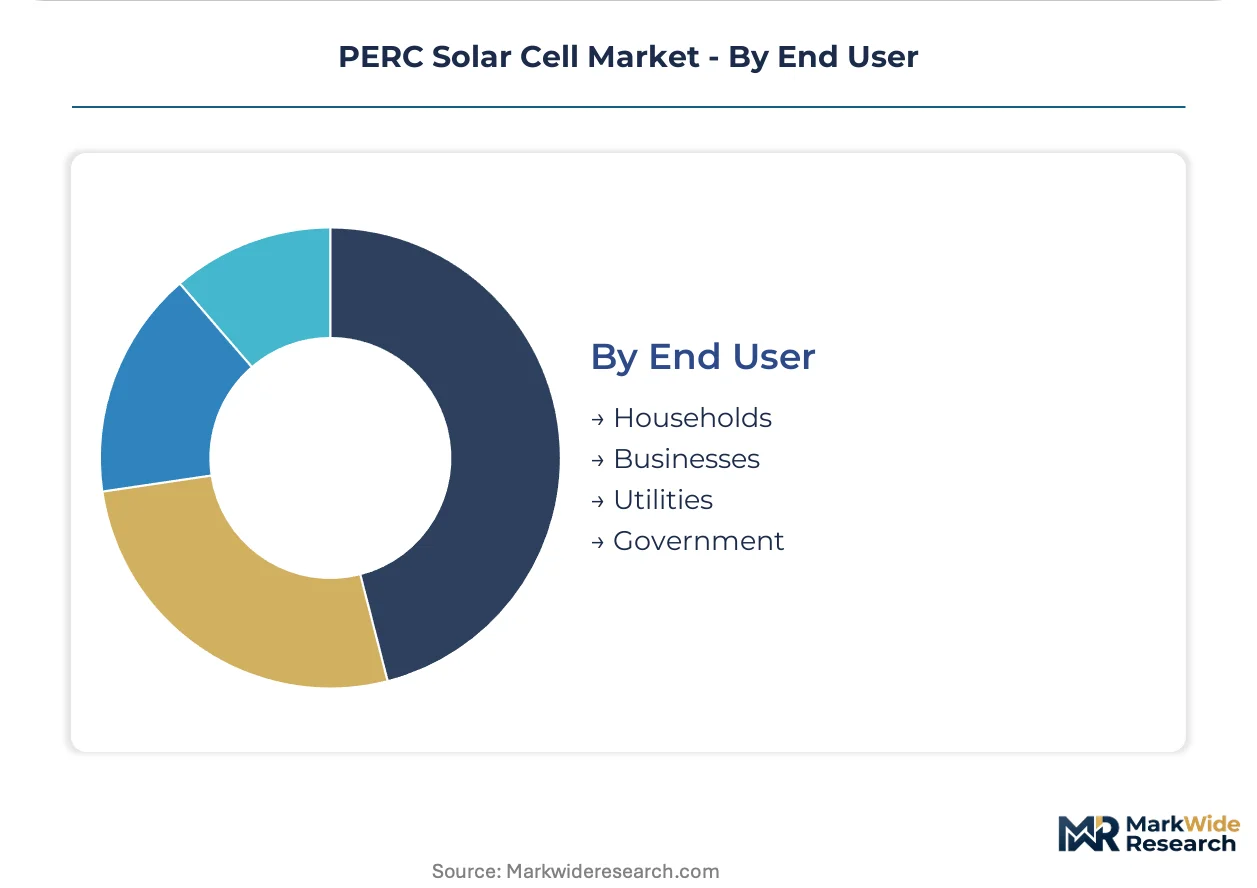
Procurement scale and risk tolerance segment buyer behavior.
- Utilities:State-backed pipelines in China filter procurement around MIIT-certified tier-one manufacturers with proven bankability. LONGi and JinkoSolar anchor this channel through captive polysilicon and Southeast Asian cell-to-module capacity.
- Businesses:Corporate power purchase agreements in Germany and India drive demand for documented supply-chain carbon intensity under EU CSRD and emerging carbon-border adjustment mechanisms.
- Households:Premium residential segments in Germany prioritize German-engineered quality protocols over pure cost minimization.
- Government:Public procurement mandates in Saudi Arabia and India specify domestic content requirements and BIS certification that reshape supplier geography.
Contract scale favors utilities; margin sustainability favors businesses with carbon-border readiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale developers concentrate procurement in jurisdictions with bankable interconnection frameworks and domestic content incentives. State-backed pipelines in China, FERC-governed queues in the United States, and albedo-optimized desert installations across Saudi Arabia and Chile drive divergent regional demand patterns.
China
MIIT efficiency mandates under GB standards filter subscale cell producers from state-backed tenders, consolidating procurement around certified manufacturers. The dual carbon goals accelerate n-type transition timelines that compress legacy p-type PERC equipment utilization. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces concentrate dielectric passivation and laser contact opening capacity for export markets.
United States
FERC Order 2023 accelerates interconnection queue reforms that pull forward module demand from independent power producers. The Inflation Reduction Act domestic content bonuses reshape supplier geography toward Southeast Asian cell-to-module capacity qualifying for tax credits. Texas and California utility-scale installations dominate bifacial PERC deployment with single-axis tracking systems.
Saudi Arabia
The Red Sea Project and NEOM Northwest developments deploy bifacial PERC with albedo-optimized desert surfaces to maximize energy yield per hectare. SFDA-equivalent quality protocols and domestic content requirements filter supplier bases for gigawatt-scale tenders. Eastern Province industrial zones concentrate module assembly capacity serving Middle East and North Africa export markets.
Germany
EU CSRD disclosure rules and CE marking under the Construction Products Regulation collapse accessible supplier bases for European project developers. German-engineered quality protocols dominate premium residential segments where warranty terms command price premiums. Bavaria and North Rhine-Westphalia anchor distributed commercial procurement through Mittelstand aggregator-led consortia.
India
BIS certification mandates for module imports create inventory bottlenecks during tender award windows. PLI scheme incentives attract cell-to-module capacity to Gujarat and Tamil Nadu manufacturing hubs. Agrivoltaic dual-use installations in Maharashtra and Karnataka unlock land-constrained deployment without agricultural displacement.
PERC Solar Cell Market Competitive Landscape
Player mix skews toward vertically integrated polysilicon-to-module conglomerates with captive wafer capacity. The supplier base concentrates around tier-one manufacturers with MIIT certification and proven bankability for utility-scale tenders. Three archetypes dominate: backward-integrated polysilicon giants controlling ingot supply, Southeast Asian cell-to-module assemblers leveraging tariff-advantaged export positioning, and premium residential specialists with German-engineered quality protocols. Competitive moves center on n-type capacity conversion ahead of TOPCon substitution timelines and carbon-border adjustment readiness through renewable-powered smelter sourcing.
Within the backward-integrated tier, LONGi Green Energy Technology and Tongwei Co. Ltd occupy positions anchored by captive polysilicon supply. JinkoSolar exemplifies the Southeast Asian hub strategy through vertically integrated cell-to-module capacity in Vietnam and Malaysia. Hanwha Q Cells represents the premium residential archetype with quality protocols dominating German and US distributed markets. These three groupings illustrate how divergent integration depths and geographic footprints segment competitive positioning across procurement channels.
| Leading Market Players |
|---|
| JinkoSolar |
| Risen Energy |
| LONGi Green Energy Technology |
| Hanwha Q Cells |
| Tongwei Co. Ltd |
| JA Solar |
| Canadian Solar |
| REC Solar |
| Trina Solar |
| Others |
Pricing and Supply Chain Analysis
n-Type mono-casting displacing legacy Czochralski pullers simultaneously redraws equipment depreciation schedules and compresses p-type wafer premiums, forcing procurement managers to rebalance contract tenors between spot polysilicon exposure and fixed-price module offtake.
Pricing Analysis
Cost-plus contracts with London Metal Exchange-indexed polysilicon clauses dominate tier-one procurement, insulating buyers from metallurgical-grade silicon swings while locking in cell processing margins. Price differentiation hinges on MIIT certification tier and bifacial glass-glass construction, with certified monocrystalline lines commanding premiums over legacy polycrystalline capacity. Cost compression in standard p-type PERC is intensifying as TOPCon conversion absorbs R&D capital and stranding risk discounts legacy equipment. Utility-scale independent power producers exhibit highest price sensitivity, while premium residential segments in Germany prioritize warranty terms over pure cost minimization.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane elevate inbound logistics costs for European project developers sourcing from Yangtze River Delta manufacturing clusters. Supply concentrates in China, Vietnam, and Malaysia, with polysilicon feedstock drawing from Xinjiang and Inner Mongolia smelters. Single-source vulnerability pervades high-purity quartz crucible supply for Czochralski ingot growth. Distribution runs through cell-to-module assemblers with captive wafer capacity, bypassing merchant wafer markets for utility-scale tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology fragmentation between PERC, TOPCon, and heterojunction processes fragments procurement standards, creating niche openings for specialists with carbon-border readiness or agrivoltaic mounting expertise.
For Market Incumbents: Compound cost leadership through backward integration into polysilicon and selective emitter laser doping retrofits that extend legacy line viability against n-type substitution. Defend utility-scale share by anchoring Southeast Asian cell-to-module capacity to qualify for US Inflation Reduction Act domestic content bonuses. Prioritize renewable-powered smelter sourcing to preempt EU carbon-border adjustment mechanism penalties. For New Entrants and Emerging Players: Lead with agrivoltaic dual-use installations in Maharashtra and Karnataka, where land-constrained deployment bypasses agricultural displacement conflicts and BIS certification bottlenecks filter incumbent supply. Target India's MSME rooftop segment through aggregator-led procurement consortia that bypass traditional distributor markups. Emphasize lightweight glass-glass module construction for commercial building-integrated segments previously served by thin-film alternatives. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Southeast Asian cell-to-module assemblers lacking captive polysilicon, presenting rollup opportunities as tariff-advantaged export positioning erodes under evolving domestic content rules. Long-term viability hinges on n-type conversion timelines and carbon-intensity documentation systems. Watch MIIT efficiency threshold escalations as the inflection signal for p-type equipment stranding velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive supply from Xinjiang smelters insulates margin against LME-indexed feedstock volatility. |
| SE+ Laser Doping Retrofit | Picosecond laser deployment compresses capex per gigawatt and extends legacy Al-BSF line economics. |
| Carbon-Border Adjustment Readiness | Granular traceability systems qualify modules for EU green taxonomy alignment and CSRD disclosure compliance. |
| Agrivoltaic Mounting System Development | Dual-use installations in Karnataka unlock land-constrained procurement without agricultural displacement. |
| Southeast Asian Capacity Expansion | Vietnam and Malaysia cell-to-module hubs qualify for US IRA tax credits under evolving domestic content tests. |
Research Methodology
Operator-level perspectives from utility planning officers, independent power producer project developers, EPC contractors, and polysilicon procurement managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through MIIT GB standard filings, FERC interconnection queue data, EU Construction Products Regulation documentation, and customs trade records. Bottom-up cell and module production estimates triangulated against top-down tender award tracking across Chinese state-backed pipelines and Saudi gigawatt-scale auctions.
Sensitivity analysis tested polysilicon price trajectories, n-type conversion adoption curves, and carbon-border adjustment implementation timelines across the analysis window. The forecast framework modeled segmentation across monocrystalline versus bifacial product architectures, utility-scale versus residential application channels, and ground-mounted versus building-integrated installation types. CAGRs derived from capacity expansion announcements, equipment vendor order backlogs, and interconnection queue reform velocity. Key inputs included albedo-optimized desert site deployment rates and BIS certification timeline compression effects on import inventory cycles.
The analysis sits within stated boundaries; outcomes outside sustained polysilicon price volatility, accelerated n-type substitution, or delayed carbon-border enforcement would require recalibration. Forecasts reflect documented assumptions around MIIT efficiency threshold maintenance, FERC Order 2023 implementation pace, and EU CSRD disclosure rule adherence by module importers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
Flexible Solar Panel Market
Solar Power Systems
High Concentration Photovoltaics Market
Solar Power Systems
India Solar Photovoltaic (PV) Market
Solar Power Systems
Off-Grid Solar Power Market
Solar Power Systems
Mexico Rooftop Solar Market
Solar Power Systems
Trinidad and Tobago Solar Energy Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
India Solar Tracker Market
Solar Power Systems
France Solar Energy Market
Solar Power Systems
Ground Mount PV Utility Market
Solar Power Systems
Organic PV Solar Cells Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Photovoltaic Coating Market
Solar Power Systems
Middle-East Solar Power Market
Solar Power Systems
Photovoltaic Solar Kits Market