
 Solar Rack Market | 2026-2036
Solar Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Rack Market Insights
The EU Green Deal is realigning procurement standards across European solar installations, forcing rack suppliers to certify lower-carbon aluminum and steel sourcing. Nextracker leverages its vertically integrated domestic manufacturing to meet these traceability requirements. Array Technologies anchors its competitive position through high-volume production of single-axis trackers for utility-scale sites. Soltec differentiates with terrain-adaptive tracking systems designed for uneven ground conditions.
Solar racks are structural support systems engineered from aluminum extrusions, galvanized steel, or reinforced composites, typically rated for wind loads exceeding 150 km/h and designed to maintain module tilt angles within 0.5 degrees over 25-year service lives. Their primary function is to secure photovoltaic panels to rooftops, ground surfaces, or elevated structures while enabling thermal expansion and drainage. Fixed Racks still dominate volume in residential and small commercial rooftops where simplicity and low maintenance outweigh tracking gains. Ground Mount Racks command the fastest expansion as utility developers in arid regions prioritize land-use efficiency and automated cleaning compatibility. Aluminum retains margin concentration due to its corrosion resistance and lightweight properties in rooftop applications where structural load limits constrain design.
The EU Green Deal and REACH regulations are tightening embodied carbon thresholds for imported steel and aluminum, reshaping supplier qualification criteria across European project pipelines. India's BIS certification mandates structural load testing for all imported mounting hardware, creating compliance barriers for non-domestic manufacturers. China's GB standards for photovoltaic support structures specify salt-spray resistance and seismic load factors that influence local procurement decisions. Stakeholders must monitor how divergent national certification regimes fragment supply chains and where regional production investments can preempt trade friction costs.
Market Dynamics
The EU Green Deal's embodied carbon thresholds are forcing rack manufacturers to requalify their entire aluminum and steel supply chains, compressing margins for non-compliant imports while advantaging domestic European extruders.
Growth Catalysts
- Utility-scale deployment acceleration:Arid-zone developers in the US, India, and Australia are prioritizing ground-mount systems with automated cleaning compatibility, driving demand for high-clearance fixed-tilt and single-axis tracker configurations.
- REACH and EU Green Deal compliance:European project pipelines now mandate certified low-carbon aluminum sourcing, creating procurement preference for suppliers with vertically integrated European smelting partnerships.
- Domestic manufacturing incentives:India's PLI scheme for solar components is attracting mounting hardware investments to Gujarat and Tamil Nadu, reducing import dependency for utility-scale developers.
Market Restraints
- Aluminum price volatility:LME aluminum fluctuations directly compress rack manufacturer margins, particularly for fixed-price EPC contracts with 12-18 month delivery horizons.
- Chinese supply concentration:Over 60% of global aluminum extrusion capacity resides in Shandong and Henan provinces, creating geographic risk for non-Chinese project developers.
- Steel corrosion limitations:Galvanized steel racks face accelerated degradation in coastal and high-humidity environments, restricting their deployability in Southeast Asian and Latin American markets.
Strategic Opportunities
- Agrivoltaic integration:Elevated rack designs enabling dual-use agriculture are gaining traction in Japan and France, where land-use restrictions favor power-generation-plus-food-production models.
- Floating solar expansion:Specialized corrosion-resistant aluminum frames for reservoir and coastal installations represent underpenetrated demand in South Korea and Singapore.
- India BIS certification arbitrage:Domestic manufacturers with pre-certified structural testing capabilities can capture share from importers facing 6-9 month compliance delays.
Industry Challenges
- Structural engineering talent scarcity:Finite-element analysis expertise for wind-load optimization is concentrated among senior engineers at established tracker firms, constraining new entrant product development cycles.
- Multi-jurisdiction certification stacking:Rack suppliers serving international EPCs must maintain parallel testing protocols for EU CE marking, India BIS, and China GB standards, inflating quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Rack Market |
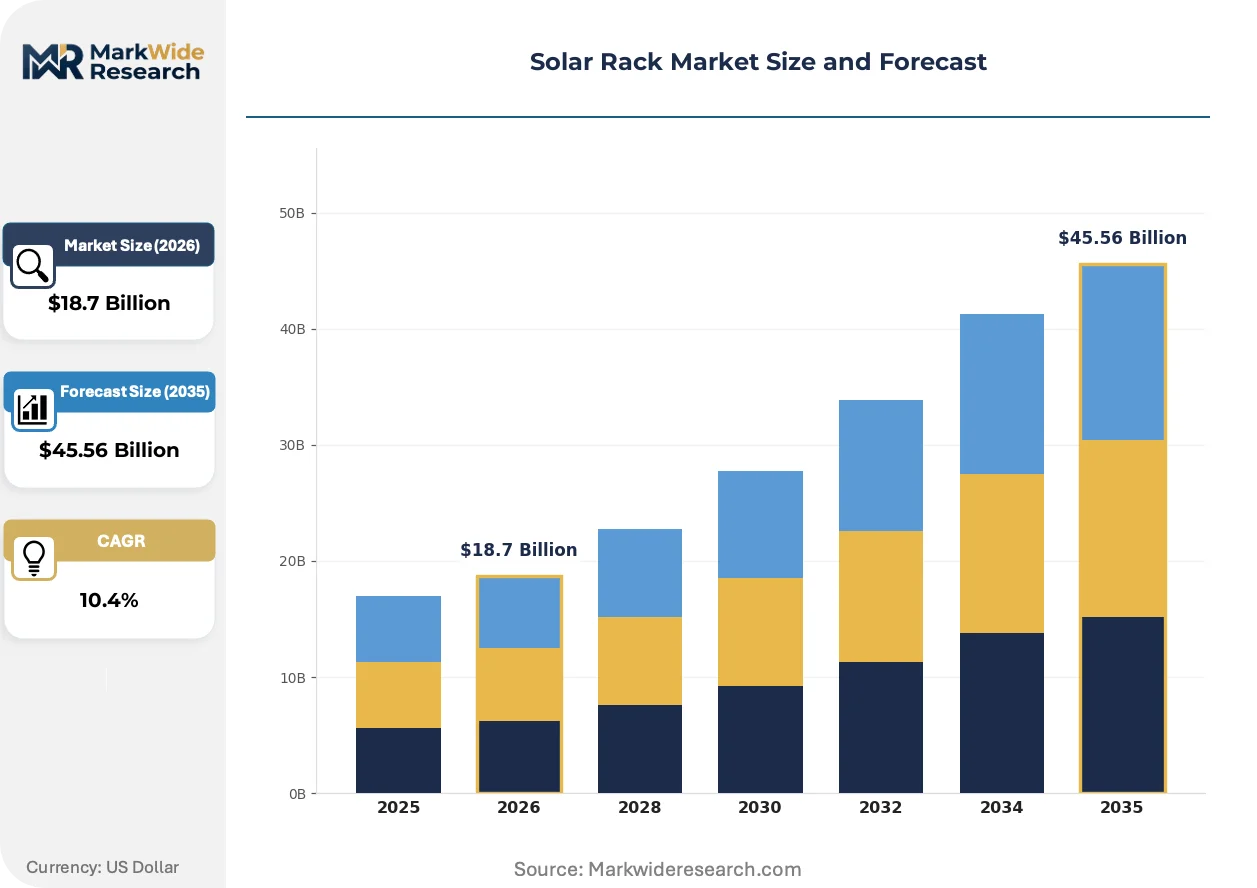
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $45.56 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Racks, Adjustable Racks, Ballasted Racks, Ground Mount Racks Material: Aluminum, Steel, Plastic, Composite Installation Type: On-Ground, Rooftop, Hybrid, Carport Application: Residential, Commercial, Industrial, Utility |
| Companies Covered | Nextracker, Array Technologies, Arctech Solar, Soltec, GameChange Solar, PV Hardware, Clenergy, Mounting Systems, K2 Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Rack Market Trends and Innovations
Tracker technology is expanding from horizontal single-axis into terrain-adaptive and bifacial-optimized configurations, while regulatory pressure on material provenance is reshaping supplier qualification workflows across major solar markets.
Carbon-fiber-reinforced polymer racks are expanding into rooftop applications where structural load limits constrain conventional aluminum systems. Commercial building owners in Germany and Japan are specifying these composites for retrofits with marginal roof capacity. The technology is expanding into premium residential segments where aesthetic integration and weight reduction justify 40-60% material cost premiums.
REACH substance restrictions and the EU Carbon Border Adjustment Mechanism are tightening documentation requirements for imported steel and aluminum. Rack manufacturers must now provide Environmental Product Declarations and supply-chain emissions audits to qualify for European utility tenders. Developers in Spain and Italy are responding by shortening supplier lists to pre-qualified domestic extruders with certified low-carbon production.
Engineering-procurement-construction firms are consolidating rack procurement under multi-year framework agreements with tier-one tracker suppliers. This concentration displaces spot-market purchasing for utility-scale projects in the US and Australia. The shift is most visible in Texas and Rajasthan, where 500MW+ project pipelines favor suppliers with guaranteed delivery slots and embedded installation crews.
Solar Rack Market Segmentation
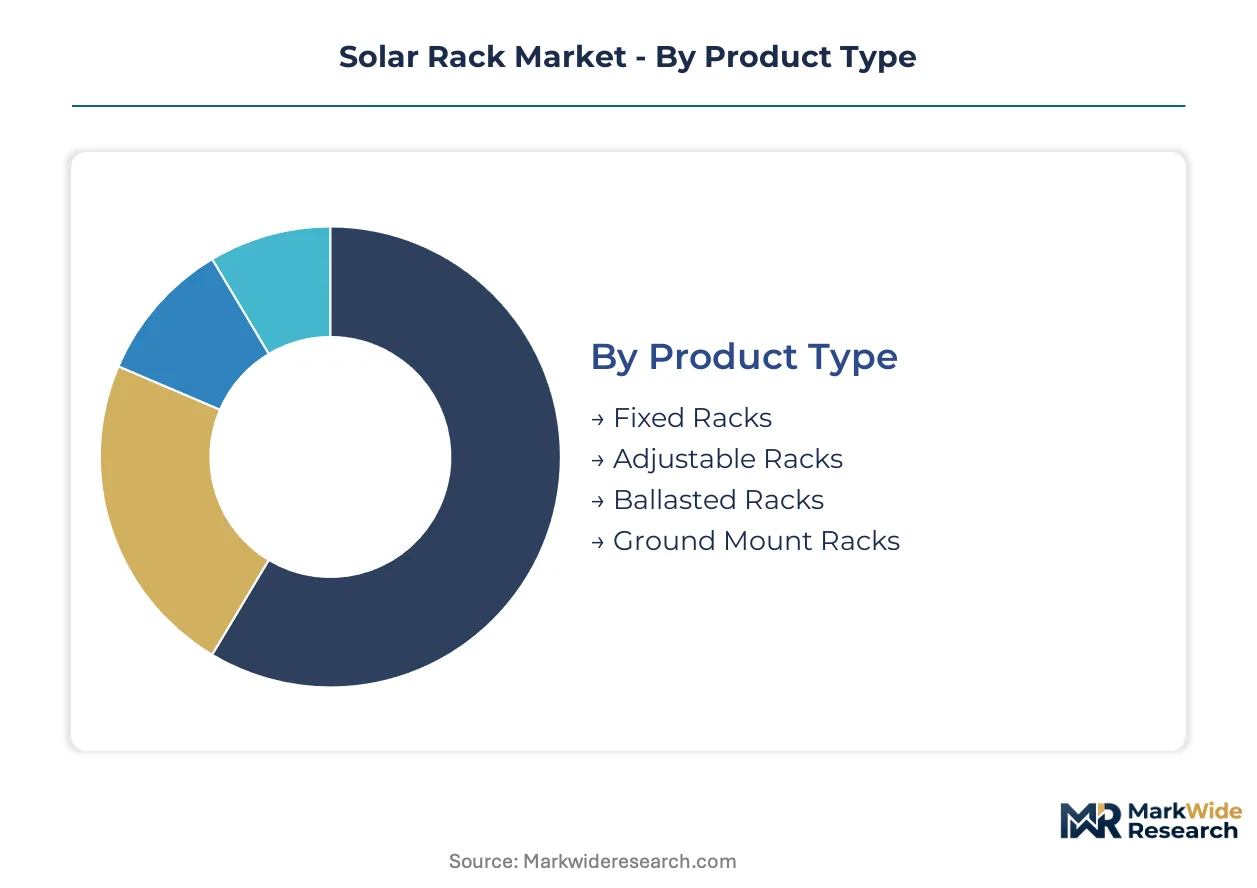
Solar rack segmentation reveals how structural load requirements, corrosion exposure, and installation logistics fragment procurement patterns across deployment scales. Buyers prioritize material certification, terrain adaptability, and labor efficiency differently depending on project size and regulatory environment.
Product Type:
Ground-mount developers prioritize automated cleaning compatibility and terrain flexibility, while rooftop installers emphasize weight minimization and rapid assembly.
- Fixed Racks:Stationary aluminum or steel frames maintain fixed tilt angles optimized for latitude-specific irradiance. Residential rooftops in Germany and Japan specify these for structural simplicity and minimal maintenance overhead. Volume sits with Fixed Racks; growth tilts toward Ground Mount Racks.
- Adjustable Racks:Seasonally tilt-adjustable systems enable manual angle optimization for snow shedding and summer yield maximization. Northern latitude commercial installations in Canada and Scandinavia adopt these where labor costs justify seasonal adjustment routines.
- Ballasted Racks:Weight-anchored systems eliminate roof penetration, preserving membrane warranties on flat commercial rooftops. US warehouse operators in California and Texas specify these for accelerated permitting and reduced structural engineering.
- Ground Mount Racks:Elevated structures with pile-driven or concrete foundations dominate utility-scale deployments across Rajasthan and Texas where land availability permits wide row spacing and automated maintenance access.
Fixed configurations dominate installation counts; adjustable and ground-mount variants capture margin expansion from performance optimization and scale economies.
Material:
Corrosion environment and structural load limits determine material selection more than upfront cost for specification-grade buyers.
- Aluminum:Extruded 6061-T6 or 6005A alloys deliver corrosion resistance and one-third the density of steel for rooftop constraints. Coastal installations in Florida and Mediterranean Spain mandate marine-grade anodized finishes for salt-spray durability. Procurement concentrates with aluminum for premium rooftop applications; steel retains cost-driven ground-mount share.
- Steel:Hot-dip galvanized structural sections provide compressive strength for high-wind zones and heavy snow loads. Central US utility developers specify steel for pile-driven tracker foundations where mass stabilizes dynamic wind response.
- Plastic:Glass-reinforced polymer mounting rails penetrate residential DIY segments where tool-free assembly and electrical isolation matter. German balcony solar kits specify these for plug-and-play regulatory compliance.
- Composite:Carbon-fiber reinforced systems enable ultra-lightweight deployment on structurally marginal roofs. Tokyo commercial retrofits adopt these where seismic load limits constrain conventional materials.
Aluminum commands specification premiums; composites climb fastest from baseline near-zero in specialized retrofit applications.
Installation Type:
Site constraints and land-use regulations push developers toward hybrid configurations that maximize generation density.
- On-Ground:Direct soil-mounted systems with driven piles or concrete ballast dominate utility-scale pipelines in arid regions. Rajasthan and Arizona developers favor these for grading flexibility and vegetation management.
- Rooftop:Attached or ballasted systems for pitched and flat commercial roofs constitute the volume base in mature solar markets. Japanese commercial building owners specify these under METI feed-in tariff deadlines.
- Hybrid:Combined rooftop and ground-mount portfolios serve industrial campuses with mixed building density. German manufacturing facilities deploy these to maximize self-consumption across distributed roof and parking assets.
- Carport:Elevated canopy structures dual-purpose parking coverage with generation. California school districts and French retail chains specify these for visible sustainability commitments and vehicle shading.
Ground and rooftop split volume; carport configurations expand most quickly from minimal installed base in premium commercial segments.
Application:
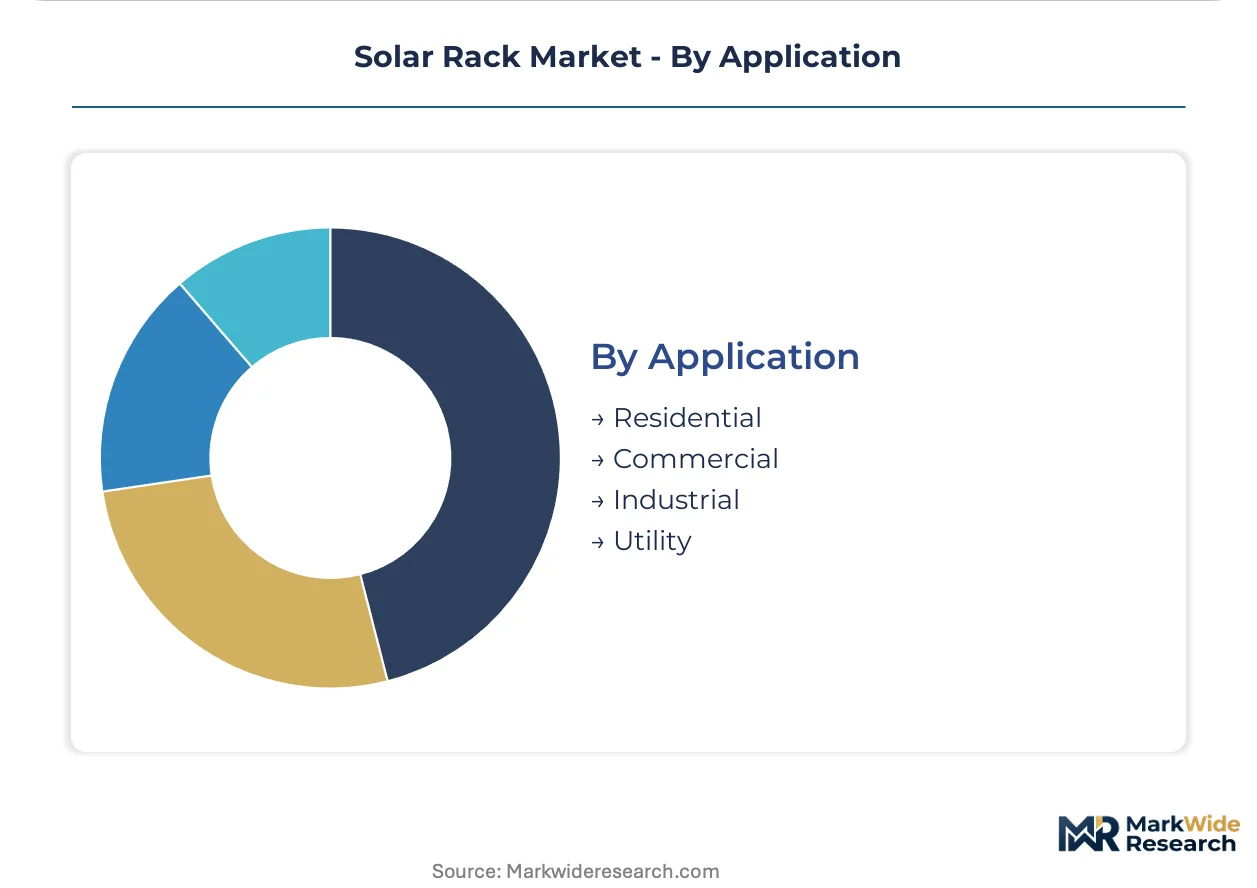
Scale determines procurement sophistication, with utility buyers consolidating under framework agreements and residential remaining fragmented.
- Residential:Distributed rooftop systems under 20kW prioritize rapid permitting and aesthetic integration. Australian homeowners and Dutch retrofit markets drive demand for low-profile rail systems.
- Commercial:20kW–5MW rooftop and carport installations balance yield optimization with structural engineering constraints. US retail chains and Indian manufacturing campuses specify these for behind-the-meter savings.
- Industrial:Large rooftop and adjacent ground-mount systems serve energy-intensive operations with high load correlation. Saudi petrochemical facilities and Brazilian mining operations deploy these for diesel displacement.
- Utility:Centralized solar farms exceeding 5MW dominate aluminum and steel consumption volumes. EPCs in Texas, Gujarat, and Queensland consolidate procurement under multi-year tracker supply agreements.
Utility-scale deployments concentrate material throughput; commercial applications gain share fastest from distributed generation policy support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates over half of global aluminum extrusion capacity for solar racks, while deployment demand concentrates in the United States, India, and European markets with divergent certification regimes.
United States
Utility-scale developers in Texas and Arizona are procuring high-clearance ground-mount systems compatible with automated cleaning equipment. FERC interconnection queue reforms are accelerating project timelines for 500MW+ solar farms. Domestic tracker assembly facilities in Colorado and Texas are expanding to reduce lead times for Southwest utility pipelines.
China
Shandong and Henan provinces host the majority of global aluminum extrusion capacity serving both domestic utility installations and export markets. GB standards for photovoltaic support structures mandate salt-spray resistance and seismic load factors that shape local procurement. Manufacturers in Jiangsu province are vertically integrating from billet casting through finished rack assembly to meet traceability requirements for European exports.
India
Gujarat and Rajasthan utility developers are sourcing mounting hardware under the PLI scheme for solar components. BIS certification mandates structural load testing for all imported mounting hardware, creating compliance barriers for non-domestic manufacturers. Tamil Nadu manufacturing clusters are attracting domestic rack investments to serve southern state solar parks.
Germany
Commercial building owners in Bavaria and North Rhine-Westphalia are specifying carbon-fiber-reinforced polymer racks for rooftop retrofits with marginal structural capacity. EU Green Deal embodied carbon thresholds are forcing requalification of aluminum and steel supply chains. Domestic extruders in the Rhineland are capturing procurement preference with certified low-carbon production.
Australia
Queensland and New South Wales utility developers are consolidating procurement under multi-year framework agreements with tier-one tracker suppliers. Arid-zone project economics favor ground-mount configurations with wide row spacing for vegetation management. EPCs in the National Electricity Market are prioritizing suppliers with guaranteed delivery slots and embedded installation crews.
Solar Rack Market Competitive Landscape
The competitive structure tilts toward vertically integrated tracker specialists with captive aluminum supply and certified European smelting partnerships. Tier-one suppliers with multi-gigawatt manufacturing footprints command framework agreement positions with major EPCs, while regional fabricators compete on domestic certification speed and local logistics. Two strategic archetypes dominate: integrated tracker manufacturers controlling upstream extrusion capacity, and specialized mounting hardware suppliers focused on rooftop and distributed generation segments. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing billet supply agreements and pre-certified testing capabilities to preempt trade friction costs.
Among the named suppliers, Nextracker and Array Technologies exemplify the scale-driven integrated archetype with domestic manufacturing footprints, while Soltec represents terrain-adaptive specialization. Nextracker leverages vertically integrated production to meet EU traceability requirements, Array Technologies anchors high-volume single-axis tracker supply for utility-scale deployments, and Soltec occupies a differentiated position with systems engineered for uneven ground conditions. These three companies sit within the premium tier where certification compliance and guaranteed delivery capacity determine competitive position.
| Leading Market Players |
|---|
| Nextracker |
| Array Technologies |
| Arctech Solar |
| Soltec |
| GameChange Solar |
| PV Hardware |
| Clenergy |
| Mounting Systems |
| K2 Systems |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between EU Green Deal-compliant and non-compliant rack suppliers manifests in divergent pricing power and sourcing architectures across European project pipelines. Premium-tier suppliers with certified low-carbon aluminum partnerships command procurement preference from EPCs facing REACH documentation mandates, while commodity-tier imports absorb margin compression from carbon border exposure.
Pricing Analysis
Cost-down pressure on fixed-tilt aluminum systems accelerates because LME volatility transmits directly into EPC contract margins with 12-18 month delivery horizons. Project-based long-term offtake agreements dominate utility-scale procurement, with price differentiation hinging on certification grade and guaranteed delivery capacity. Residential rooftop buyers exhibit highest price sensitivity, while utility developers prioritize traceability documentation over unit cost.
Supply Chain Analysis
Container freight rates from Shandong province to Rotterdam and Mumbai shape landed cost competitiveness for extruded aluminum components. Supply concentrates in China, India, and Germany for finished rack assembly, with raw material draws from Australian bauxite and Guinean alumina feedstock. Single-source vulnerability sits with Shandong extrusion capacity serving over half of global demand. Distribution runs through EPC framework agreements rather than spot-market purchasing for utility-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Solar Rack Market operates as a cost-of-compliance arena where EU Green Deal embodied carbon thresholds erect regulatory moats favoring pre-certified domestic extruders over import-dependent competitors.
For Market Incumbents: Deploy captive billet supply agreements to preempt aluminum price volatility transmission into fixed-price EPC contracts. Array Technologies and Nextracker should expand Rhineland extrusion partnerships to solidify CE marking qualification ahead of CBAM phase-in, while secondary players face displacement from consolidated procurement under multi-year framework agreements. For New Entrants and Emerging Players: The mid-market price-point gap between premium-tracker and economy-fixed configurations offers white-space opportunity in India's PLI-subsidized manufacturing clusters. Target BIS pre-certification capabilities in Tamil Nadu to capture share from importers facing 6-9 month compliance delays, with agrivoltaic elevated rack designs as the differentiated entry angle. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated tracker specialists given EU traceability requirements concentrating procurement preference. Long-term viability favors archetypes with captive aluminum supply and certified European smelting partnerships; monitor CBAM implementation pace as the inflection signal for import-dependent model obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Billet Supply | Captive aluminum sourcing insulates margins from LME volatility and qualifies for EU Green Deal traceability mandates. |
| European Smelting Partnership Certification | Low-carbon extrusion partnerships unlock procurement preference from EPCs facing REACH documentation requirements. |
| Multi-Year EPC Framework Agreements | Guaranteed delivery slots displace spot-market purchasing for 500MW+ utility pipelines in Texas and Rajasthan. |
| India BIS Pre-Certification Investment | Domestic structural testing capabilities capture share from importers facing compliance delays under PLI scheme. |
| Agrivoltaic Rack Design Development | Elevated dual-use configurations penetrate Japan and France where land-use restrictions favor power-plus-food models. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with EPC procurement directors, tracker manufacturer supply chain leads, and aluminum extrusion plant managers. Secondary sources included EIA project databases, IEA renewable energy reports, FERC interconnection queue filings, and EU ETS carbon price series. Bottom-up installation forecasts triangulated against top-down aluminum consumption models across product type, material, and application segments.
Granularity-level modeling deployed capacity-by-technology assumptions for fixed-tilt versus tracker configurations, with material intensity coefficients applied across rooftop, ground-mount, and floating installation types. CAGRs derived from regression against utility-scale deployment pipelines and distributed generation policy trajectories. Forecast inputs incorporated PLI scheme uptake curves in India, CBAM phase-in schedules, and BIS certification processing timelines.
Inputs from EPC framework agreement disclosures and customs extrusion export records were available through the study window; gaps in real-time LME hedge positioning data introduce uncertainty bands around margin compression estimates. Forecasts reflect documented assumptions regarding aluminum price trajectories and regulatory implementation pace; stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Mexico Rooftop Solar Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
United States Solar Energy Market
Solar Power Systems
Solar Panel Bracket Market
Solar Power Systems
Vietnam Solar Energy Market
Solar Power Systems
North America Solar Photovoltaic (PV) Market
Solar Power Systems
Photovoltaic Mounting System Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
Global Photovoltaic Glass Market
Solar Power Systems
United Arab Emirates Solar Energy Market
Solar Power Systems
Bifacial Solar Market
Solar Power Systems
Off-Grid Solar Lighting Market
Solar Power Systems
Thin Film Solar PV Market