
 Australia Rooftop Solar Market | 2026-2036
Australia Rooftop Solar Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Rooftop Solar Market Outlook
Residential uptake is decoupling from commercial deployment as Australian households pursue energy independence amid volatile retail tariffs. Tindo Solar anchors its position through Australian-made panel manufacturing in Adelaide. JinkoSolar competes aggressively on module cost while LONGi Green Energy leverages monocrystalline wafer efficiency leadership to capture premium residential segments.
Australia rooftop solar denotes photovoltaic systems installed on building rooftops, typically comprising silicon cell modules rated between 300-600 watts with DC-to-AC conversion through string or micro-inverters for grid injection or self-consumption. Monocrystalline modules command the product mix due to superior conversion efficiency in Australia's high-temperature operating conditions. Grid-tied technology dominates installations though hybrid configurations with battery storage represent the fastest-growing technology segment as households seek backup resilience. Agricultural applications remain underdeveloped relative to residential and commercial deployment.
The Clean Energy Regulator administers Small-scale Technology Certificates while Standards Australia governs AS/NZS 5033 installation requirements and the Australian Energy Market Commission sets network connection rules. These frameworks dictate product eligibility, installer accreditation, and export compensation structures that directly shape consumer economics and market access. Stakeholders must monitor impending reforms to distributed energy resource participation frameworks in the National Electricity Market that will redefine how rooftop assets interact with grid dispatch and settlement systems.
Market Dynamics
Residential energy independence is accelerating system sizing beyond historical self-consumption economics, compressing payback periods through state-level feed-in tariff structures and Small-scale Technology Certificate stacking that reward larger behind-the-meter capacity.
Growth Catalysts
- Small-scale Renewable Energy Scheme:The Clean Energy Regulator's certificate mechanism reduces upfront capital outlay for Victorian and Queensland households, compressing payback timelines below five years in high-irradiance zones.
- Retail tariff volatility:Essential Services Commission pricing decisions and network cost pass-throughs in New South Wales are forcing residential load defection toward behind-the-meter generation.
- Monocrystalline efficiency gains:Passivated emitter and rear cell architectures are lifting module output in Australia's high-temperature operating conditions, reducing rooftop footprint requirements for target capacity.
Market Restraints
- Polysilicon supply concentration:Xinjiang-based ingot production dominates wafer feedstock, exposing Australian distributors to input cost volatility and forced labor disclosure compliance under Modern Slavery Act requirements.
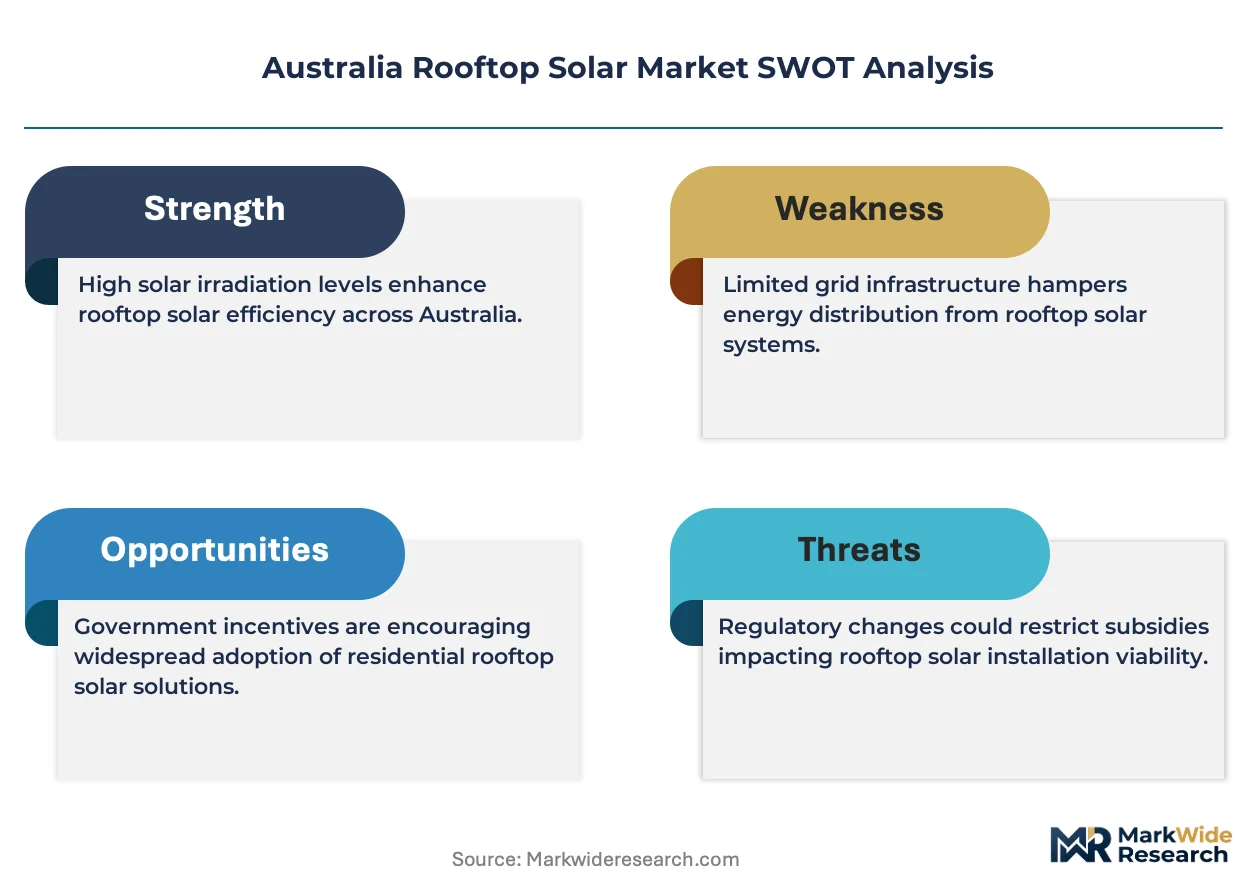
- Network export limits:Australian Energy Market Commission connection rules impose inverter throttling and export curtailment on congested low-voltage feeders, degrading revenue streams from surplus generation.
- Skilled installer scarcity:Clean Energy Council accreditation bottlenecks and electrical trades migration to commercial construction are elongating residential project lead times in suburban Melbourne growth corridors.
Strategic Opportunities
- Western Australia grid saturation:South West Interconnected System rooftop penetration lags eastern states, creating whitespace for behind-the-meter deployment ahead of anticipated retail tariff rebalancing.
- Virtual power plant aggregation:AEMO's distributed energy resource participation frameworks will enable household battery fleets to bid into frequency control ancillary services, unlocking new revenue stacking.
- Agricultural building integration:Dairy shed and irrigation pump solarization in Queensland's Darling Downs remains underdeveloped relative to residential deployment, offering volume scale through standardized rural designs.
Industry Challenges
- AS/NZS 5033 compliance complexity:Standards Australia's installation requirements for DC isolator placement and earthing configurations are creating certification delays for new module form factors entering the market.
- Post-installation service fragmentation:Warranty claim routing between module manufacturers, inverter suppliers, and installation contractors is generating consumer dispute escalation through state fair trading offices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Rooftop Solar Market |
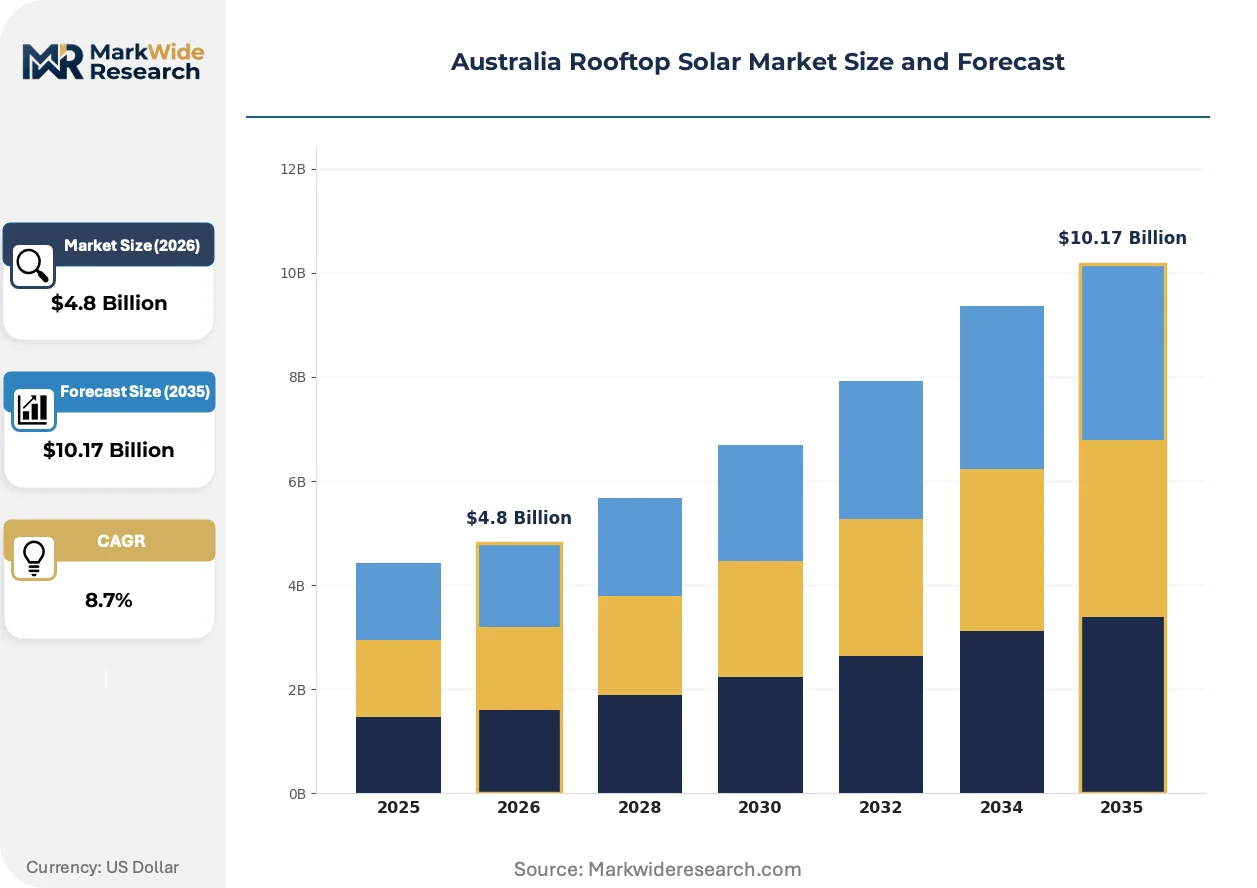
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Application: Residential, Commercial, Industrial, Agricultural Technology: Grid-Tied, Off-Grid, Hybrid, Smart Inverters Installation Type: Roof-Mounted, Ground-Mounted, Carport, Building-Integrated |
| Companies Covered | Maxeon Solar Technologies, Energy Matters, Trina Solar, Tindo Solar, GEM Energy, JinkoSolar, Canadian Solar, Infinite Energy, LONGi Green Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Rooftop Solar Market Strategic Shifts
Module-level power electronics and battery coupling are reconfiguring system architecture away from centralized string designs, while regulatory frameworks for distributed energy participation are rewriting how rooftop assets monetize grid services.
Module-level power electronics is decentralizing fault isolation and performance optimization across residential arrays. Suburban Sydney installers are specifying power optimizers and micro-inverters for shading-prone rooftops at accelerating rates. This topology is decentralizing maintenance liability from string-level to component-level, compressing installer warranty exposure while lifting generation certainty for household export revenue.
Standards Australia's pending revisions to AS/NZS 4777 grid connection standards are mandating inverter capabilities for voltage ride-through and frequency-watt response. Equipment manufacturers are pre-certifying hardware for these requirements ahead of enforcement timelines. Queensland's Ergon Energy network is most exposed, with rural feeders experiencing the highest distributed generation penetration and requiring active power management.
Households are bundling storage procurement with solar installation at rising rates, displacing standalone PV-only quotes. Retail channel consolidation is compressing independent installer margins as vertically integrated energy retailers capture bundled system sales. South Australia's Home Battery Scheme subsidy exhaustion is most visible, with post-incentive procurement now relying on pure bill-savings economics rather than upfront capital support.
Australia Rooftop Solar Market Segmentation
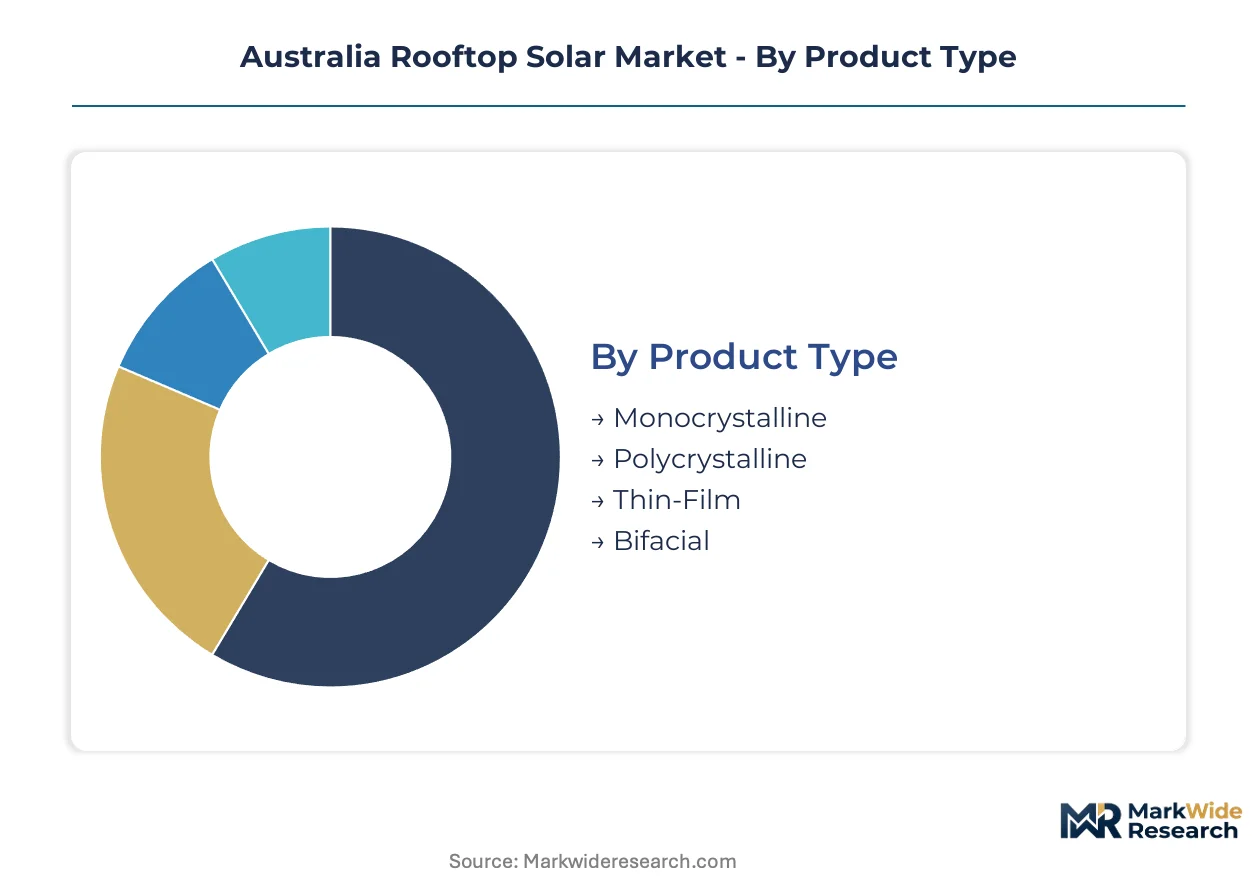
Segmentation in the Australia rooftop solar market reveals how technology choices, installation configurations, and end-use applications distribute value across the supply chain. Understanding these splits helps distributors align inventory with state-level incentive structures and irradiance-driven economics.
Product Type:
Module chemistry determines conversion efficiency in Australia's high-temperature operating conditions, with integration depth varying from standalone rooftop arrays to building-embedded photovoltaic skins.
- Monocrystalline:Passivated emitter and rear cell architectures deliver superior wattage density per square meter. Demand clusters in suburban Sydney and Melbourne corridors where roof area constraints meet high retail tariffs from Essential Services Commission pricing decisions.
- Polycrystalline:Lower conversion efficiency comes with reduced module cost, appealing to price-sensitive regional Queensland households outside Brisbane's metropolitan zone. Supply exposure to Xinjiang polysilicon feedstock complicates procurement under Modern Slavery Act disclosure requirements.
- Thin-Film:Cadmium telluride and amorphous silicon variants tolerate partial shading better than crystalline alternatives.
- Bifacial:Dual-sided light capture boosts yield on elevated commercial installations with reflective roofing substrates.
Volume placements concentrate in Monocrystalline; the faster expansion belongs to Bifacial.
Application:
End-use segmentation tracks how tariff volatility and energy independence motivations reshape deployment patterns across household, commercial, and productive agricultural settings.
- Residential:Behind-the-meter generation targets bill reduction and backup resilience through battery coupling. New South Wales and Queensland households lead procurement, driven by high irradiance and network cost pass-throughs from Australian Energy Market Commission rulings.
- Commercial:Flat-roof warehouses and retail premises exploit economies of scale in system sizing. Melbourne's industrial west and Sydney's outer southwest corridors show concentrated activity where daytime load profiles match solar generation curves.
- Industrial:Heavy manufacturing facilities integrate rooftop arrays with process heat and cooling loads.
- Agricultural:Dairy sheds and irrigation pumps in Queensland's Darling Downs remain underdeveloped relative to residential deployment, offering whitespace through standardized rural system designs.
Commercial procurement dominates current installed capacity; Agricultural applications are climbing the fastest as irrigation electrification accelerates.
Technology:
System architecture choices determine grid interaction modes, revenue stacking potential, and resilience against network export constraints.
- Grid-Tied:Direct injection into distribution networks dominates current installations. Victorian and Queensland feed-in tariff structures from state energy departments shape payback calculations for surplus export.
- Hybrid:Battery-coupled configurations enable self-consumption optimization and backup power during outages. South Australia's Home Battery Scheme demonstrated demand elasticity, with post-subsidy procurement now relying on pure bill-savings economics.
- Off-Grid:Standalone systems serve remote properties beyond the National Electricity Market footprint.
- Smart Inverters:Grid-supporting capabilities for voltage ride-through and frequency-watt response address Standards Australia's pending AS/NZS 4777 revisions.
Grid-Tied retains the largest installed base; Hybrid configurations are gaining share fastest as households prioritize energy independence.
Installation Type:
Mounting configuration segmentation reflects site constraints, land availability, and building-integrated design ambitions across Australia's varied built environment.
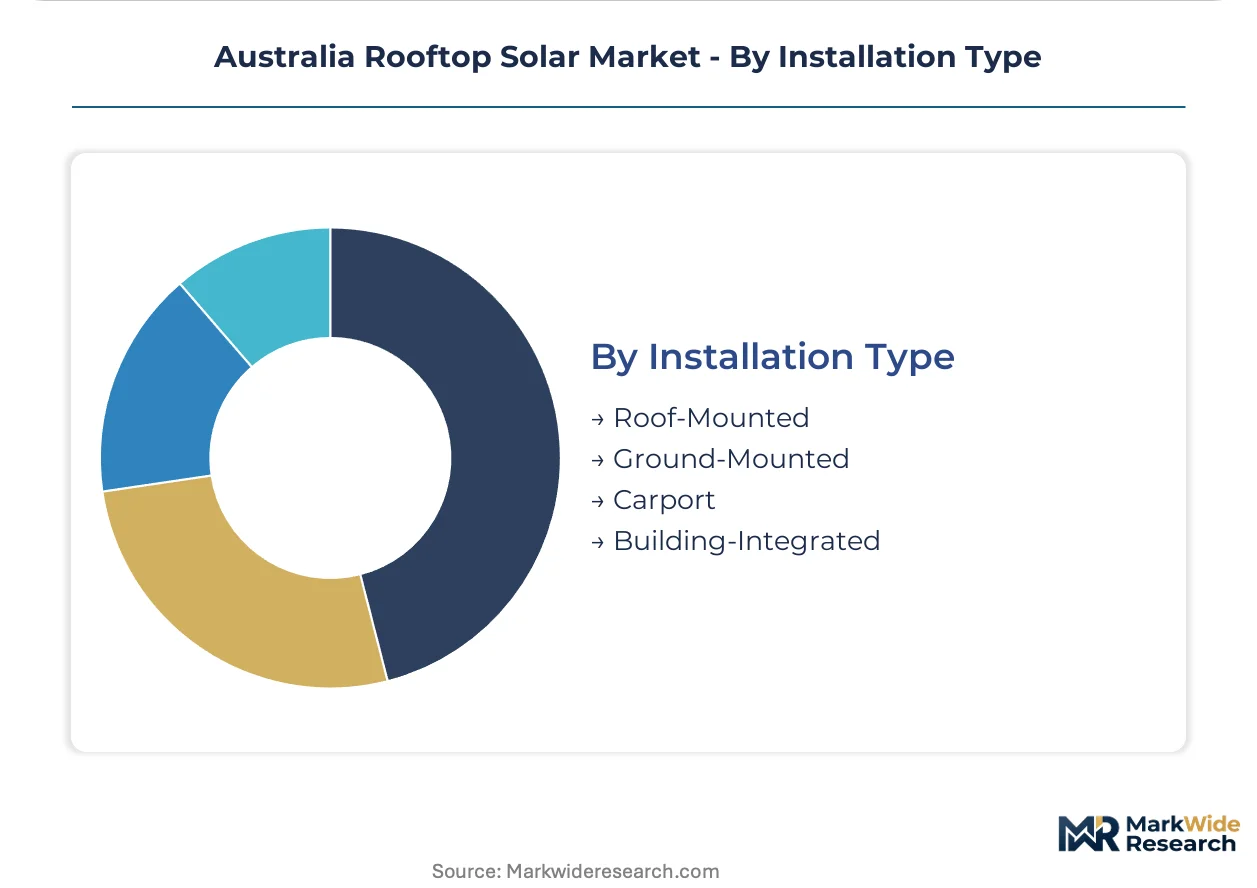
- Roof-Mounted:Tilted arrays on pitched residential roofs constitute the overwhelming majority of deployments. AS/NZS 5033 compliance requirements for DC isolator placement and earthing configurations govern installer accreditation through the Clean Energy Council.
- Building-Integrated:Photovoltaic skins and solar tiles replace conventional roofing materials, embedding generation into building envelopes. Premium residential segments in Sydney's eastern suburbs and Melbourne's inner north experiment with these configurations despite higher capital intensity.
- Ground-Mounted:Elevated arrays on rural properties exploit unshaded land availability.
- Carport:Dual-purpose structures combine vehicle shelter with generation capacity in commercial parking facilities.
Roof-Mounted systems capture the highest volume; Building-Integrated approaches show the steepest expansion trajectory among premium customer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Small-scale Renewable Energy Scheme's certificate trading zones concentrate installer activity and distribution capacity in state-level markets where irradiance and retail tariff differentials create viable payback economics.
New South Wales
Sydney's outer southwestern growth corridors and coastal regional centers drive residential procurement as Essential Services Commission network cost pass-throughs elevate retail electricity prices. The state's feed-in tariff framework through the Department of Climate Change, Energy, the Environment and Water shapes export revenue calculations. Newcastle and Wollongong industrial zones concentrate commercial rooftop deployment on warehouse and logistics facilities.
Victoria
Melbourne's suburban expansion corridors in the west and southeast exhibit the highest residential penetration rates nationally as households respond to volatile retail tariffs from Australian Energy Market Commission pricing decisions. The Victorian Energy Upgrades program layers additional certificate value atop federal Small-scale Technology Certificates. Geelong and Ballarat regional centers show accelerating agricultural solarization on dairy and intensive farming operations.
Queensland
Brisbane's metropolitan zone and the Sunshine Coast corridor lead procurement volume, supported by the Department of Energy's regional feed-in tariff structures and the highest solar irradiance levels of eastern seaboard capitals. The Darling Downs agricultural belt remains underdeveloped for irrigation pump and shed solarization relative to residential deployment. Ergon Energy's rural network experiences the most severe distributed generation penetration, driving active power management requirements.
South Australia
Adelaide's metropolitan market demonstrated strong battery coupling elasticity under the now-exhausted Home Battery Scheme, with post-subsidy procurement relying on pure bill-savings economics. Tindo Solar's local manufacturing presence anchors a modest domestic module assembly capability. The state's high retail tariffs and network reliability concerns accelerate hybrid system preferences over grid-tied-only configurations.
Western Australia
Perth's metropolitan zone and the South West Interconnected System lag eastern states in rooftop penetration, creating whitespace for deployment ahead of anticipated retail tariff rebalancing. The state's isolated grid structure limits export compensation mechanisms compared to National Electricity Market jurisdictions. Regional agricultural properties beyond the main grid drive off-grid standalone system demand for remote pumping and station power.
Australia Rooftop Solar Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with module supply consolidating around Asian-scale producers while installation and project development fragments across state-level accredited contractors. Three archetypes dominate: vertically integrated cell-to-module manufacturers, regional installation specialists with Clean Energy Council accreditation, and energy retailers bundling hardware with retail electricity contracts. Capacity expansion in passivated emitter and rear cell architectures and strategic partnerships for virtual power plant aggregation represent the dominant competitive moves.
Among module manufacturers, JinkoSolar and LONGi Green Energy occupy positions as scale-driven suppliers, while Tindo Solar exemplifies the domestic manufacturing archetype with Adelaide-based production. These anchors illustrate how Chinese-scale producers compete on module cost against local assembly's compliance and logistics advantages.
| Leading Market Players |
|---|
| Maxeon Solar Technologies |
| Energy Matters |
| Trina Solar |
| Tindo Solar |
| GEM Energy |
| JinkoSolar |
| Canadian Solar |
| Infinite Energy |
| LONGi Green Energy |
| Others |
Value Chain & Pricing Dynamics
Polysilicon spot price volatility cascades through module manufacturing into installer pricing tiers, with Xinjiang-origin feedstock commanding discounts against forced-labor-compliant alternatives under Australia's Modern Slavery Act disclosure requirements. Distributors pass through certificate stacking economics from the Small-scale Renewable Energy Scheme while absorbing network export limit risks that compress margins on congested Victorian and Queensland feeders.
Pricing Analysis
Short-lead-time premiums of 8-12% apply to monocrystalline modules held in Melbourne and Sydney distribution hubs against spot inventory discounts for polycrystalline alternatives with 8-10 week sea freight timelines. Three-tier pricing structure across premium, standard, and economy levels separates passivated emitter and rear cell certified modules from standard monocrystalline and legacy polycrystalline inventory. Cost compression in the economy tier is intensifying because Xinjiang polysilicon exposure triggers compliance scrutiny. Regional Queensland households exhibit highest price sensitivity; premium residential segments in Sydney's eastern suburbs show lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from major Australian distributors mandate qualification of both Chinese-scale cell producers and alternative Southeast Asian module assemblers to mitigate tariff and logistics exposure. Supply concentrates in China for polysilicon ingots and wafers, Vietnam for cell assembly, and Malaysia for module finishing. Raw material dependencies span metallurgical-grade silicon, silver paste for screen printing, and aluminum frames. Single-source vulnerability around Xinjiang polysilicon creates forced labor disclosure risk under Australian customs regulations. Distribution runs through state-level wholesale distributors with Clean Energy Council accreditation before reaching installation contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia rooftop solar market functions as a cost-of-compliance arena where Clean Energy Council installer accreditation and AS/NZS 5033 certification create substantial barrier-to-entry moats for compliant participants against uncertified price competitors.
For Market Incumbents: Deploy virtual power plant aggregation capabilities to capture frequency control ancillary services revenue as AEMO's distributed energy resource frameworks mature. Incumbents should deepen backward integration into battery storage supply to defend margin position against vertically integrated energy retailers bundling hardware with retail contracts. The threat of channel consolidation by Origin Energy and AGL compresses independent installer margins and demands counter-positioning through premium service differentiation. For New Entrants and Emerging Players: Agricultural property owners in Queensland's Darling Downs represent an underserved buyer archetype with standardized irrigation pump and dairy shed applications awaiting solarization. New entrants should prioritize Western Australia's South West Interconnected System where rooftop penetration lags eastern states and retail tariff rebalancing will improve payback economics. A go-to-market angle anchored in off-grid standalone system expertise for remote pastoral properties beyond the National Electricity Market footprint offers defensible positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor Clean Energy Council-accredited installation specialists with established virtual power plant aggregation partnerships in South Australia and Victoria. Long-term viability across the projection horizon hinges on regulatory capture through early compliance with pending AS/NZS 4777 inverter standards revisions. The signal to watch is Ergon Energy's active power management procurement intensity as a proxy for distributed generation saturation and revenue model transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Power Plant Aggregation | AEMO's frequency control markets unlock new revenue stacking for household battery fleets beyond export tariffs. |
| Backward Integration into Storage | In-house battery assembly hedges supply risk and captures margin compression from Chinese cell producers. |
| Clean Energy Council Accreditation Expansion | Installer certification bottlenecks in Melbourne corridors create scarcity value for accredited contractor networks. |
| Western Australia Market Entry | South West Interconnected System whitespace offers first-mover positioning ahead of retail tariff rebalancing. |
| Agricultural Solarization Standardization | Darling Downs irrigation pump applications provide volume scale through repeatable rural system designs. |
Study Parameters
Multi-period observation of Small-scale Technology Certificate trading volumes, state-level feed-in tariff uptake rates, and network export constraint filings anchored the trend analysis, supplemented by interviews with Clean Energy Council accredited installers, distribution procurement managers, utility distributed energy resource planners, and agricultural irrigation cooperative technical officers. Secondary validation drew from Clean Energy Regulator certificate registry data, Australian Energy Market Commission connection rule filings, Essential Services Commission retail tariff determinations, and Standards Australia draft standard consultation submissions. Bottom-up system deployment estimates triangulated against top-down module import customs records.
Input-output matrices mapped module supply flows from polysilicon producers through cell and module assembly to state-level distribution hubs, with segmentation across product type, application, technology, and installation configuration dimensions modeled across the analysis window. CAGRs derived from regression analysis of historical deployment trajectories against irradiance-adjusted payback period elasticities and retail tariff volatility indices. Industry-specific forecast inputs incorporated pending AS/NZS 4777 standard enforcement timelines and AEMO distributed energy resource market participation framework implementation schedules.
Revisions become necessary when network export limit tightening accelerates beyond current Australian Energy Market Commission roadmaps or when Modern Slavery Act enforcement disrupts Xinjiang polysilicon supply chains. Deviation in Victorian or Queensland state election outcomes affecting feed-in tariff continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
France Solar Energy Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
US Solar Tracker Market
Solar Power Systems
Iran Solar Energy Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Asia-Pacific Solar Photovoltaic (PV) Market
Solar Power Systems
United Arab Emirates Solar Energy Market
Solar Power Systems
Thin Film Photovoltaic Modules Market
Solar Power Systems
Flexible Solar Panel Market
Solar Power Systems
Solar Pontoon Market
Solar Power Systems
Global Solar Microinverter Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Building Integrated Photovoltaic (BIPV) Market
Solar Power Systems
Australia Solar Power Market