
 Italy Data Center Physical Security Market | 2026-2036
Italy Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Data Center Physical Security Market Insights
Certified cybersecurity-physical security integration specialists is rotating toward shortage across northern Italy, tightening deployment timelines for integrated command centers. Honeywell International Inc leverages its building automation heritage to anchor multi-site security management contracts. ASSA ABLOY sustains dominance in electromechanical access hardware through deep relationships with Italian integrators. Siemens AG competes on energy-efficient safety system architectures that reduce operational overhead for Milan-area operators.
Italy Data Center Physical Security encompasses perimeter barriers, biometric identity verification, video analytics, and environmental threat detection engineered to protect computing infrastructure from unauthorized physical access, natural hazards, and deliberate sabotage. Systems typically integrate ISO 27001-aligned access logging with real-time alarm telemetry to facility operations centers. Access Control solutions occupy the largest solution share as financial services and telecommunications operators mandate multi-factor entry protocols. Biometrics technology leads growth within the technology dimension, with fingerprint and facial recognition displacing card-based systems in Tier III facilities. Cloud-integrated installation models are gaining traction among mid-size colocation providers seeking centralized visibility without capital-intensive on-premises command centers.
Italy's implementation of the EU NIS2 Directive through national transposition measures compels critical data center operators to upgrade physical access audit trails and incident reporting capabilities. The CE marking framework under the EU Construction Products Regulation shapes barrier and fire suppression system compliance requirements for facility construction. Stakeholders must monitor how Italy's planned critical infrastructure designation expansion affects security expenditure obligations for edge computing sites outside established Lombardy and Rome clusters.
Market Dynamics
The EU NIS2 Directive is compressing deployment timelines for integrated physical-cybersecurity systems across Italian critical infrastructure, forcing operators to consolidate access control, video analytics, and environmental monitoring into unified command architectures before the transposition deadline.
Growth Catalysts
- EU NIS2 transposition:Italy's national implementation mandates upgraded physical access audit trails and incident reporting for critical data center operators, creating immediate compliance-driven procurement cycles.
- Hyperscale facility expansion:Colocation providers in Milan's Lombardy corridor are deploying multi-factor biometric entry protocols to attract financial services tenants with stringent security requirements.
- Cloud-integrated security models:Mid-size operators are adopting centralized visibility platforms that eliminate capital-intensive on-premises command centers while maintaining ISO 27001-aligned logging standards.
Market Restraints
- Specialized labor scarcity:Certified cybersecurity-physical security integration specialists are rotating toward shortage across northern Italy, extending deployment timelines for complex integrated command centers.
- CE marking compliance costs:The EU Construction Products Regulation creates barrier and fire suppression system certification friction that delays facility construction schedules.
- Copper and semiconductor input volatility:Electromechanical access hardware production faces margin pressure from fluctuating raw material costs and component lead time uncertainty.
Strategic Opportunities
- Edge computing security gaps:Critical infrastructure designation expansion planned by Italian authorities will extend security expenditure obligations to edge sites outside established Lombardy and Rome clusters.
- Biometric-video convergence:Facial recognition analytics fused with behavioral monitoring algorithms offer differentiated positioning for Tier III facility upgrades.
- Energy-efficient safety architectures:Siemens AG's low-power safety system designs point toward opportunity for vendors who can reduce operational overhead for Milan-area operators facing rising energy costs.
Industry Challenges
- Legacy system integration complexity:Brownfield data centers in Rome and Turin must bridge decades-old card-based access systems with modern biometric and cloud-integrated platforms without operational disruption.
- Certified technician pipeline gaps:The shortage of professionals qualified to deploy and maintain integrated command centers is compressing vendor capacity and extending project delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Data Center Physical Security Market |
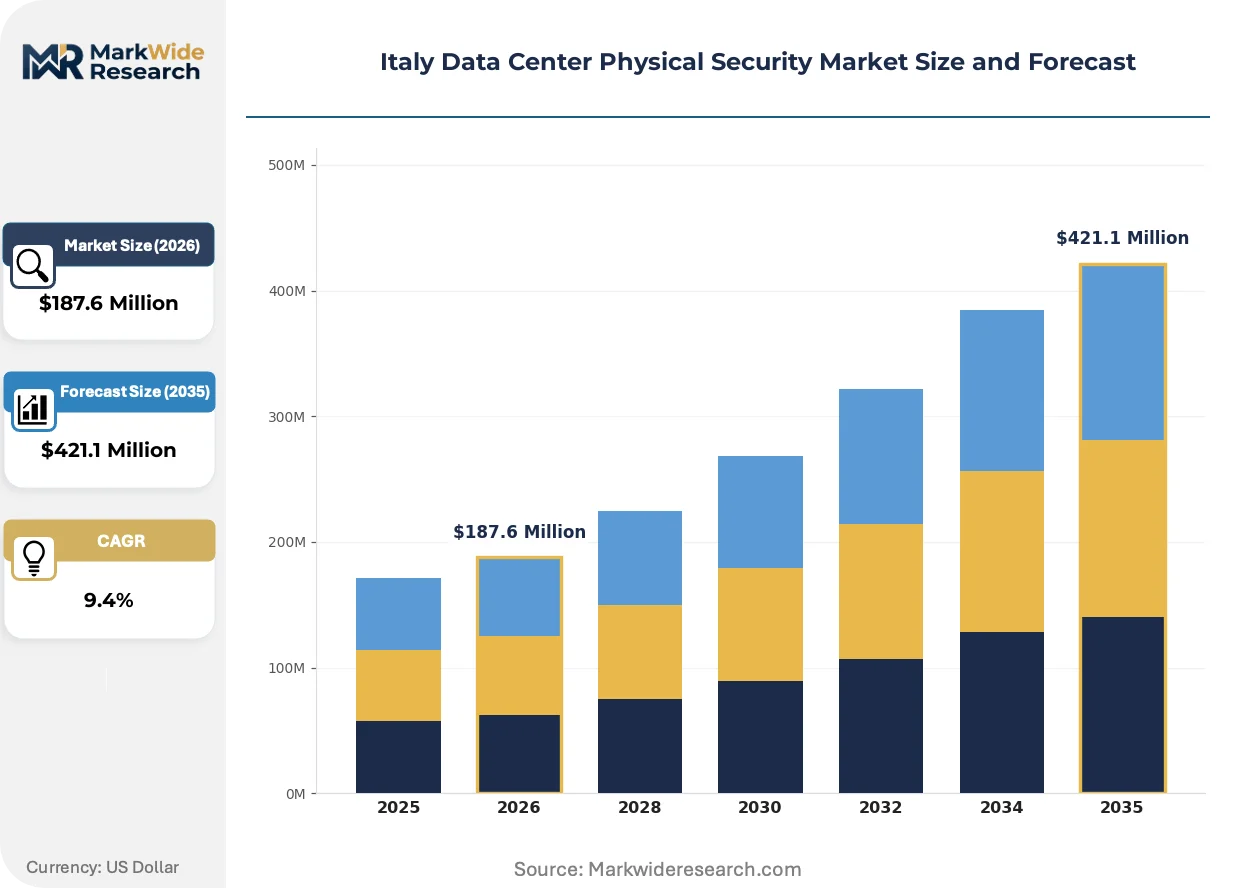
| Market Size in 2026 | $187.6 Million |
| Market Size in 2035 | $421.1 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Access Control, Surveillance Systems, Intrusion Detection, Fire Protection Technology: Biometrics, CCTV, Alarm Systems, Environmental Monitoring Installation: On-premises, Cloud-integrated, Hybrid, Remotely Monitored End User: Telecommunications, Financial Services, Healthcare, Government |
| Companies Covered | Honeywell International Inc, ABB Ltd, ASSA ABLOY, Cisco Systems Inc, Siemens AG, Schneider Electric, Hangzhou Hikvision Digital Technology Co Ltd, Bosch Sicherheitssysteme GmbH, Axis Communications AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Data Center Physical Security Market Trends and Innovations
Biometric identity verification is fragmenting the traditional access control market as fingerprint and facial recognition systems displace card-based credentials across Italian Tier III facilities. Cloud-integrated security management platforms are compressing the capital requirements for mid-size colocation providers. Energy-efficient safety architectures are reshaping competitive positioning among Milan-area operators.
Facial recognition analytics with liveness detection is fragmenting the incumbent card-and-reader ecosystem across Italian financial services data centers. Tier III operators in Milan are adopting these systems to satisfy tenant audit requirements for multi-factor entry protocols. The technology is fragmenting vendor market share by enabling specialized biometric providers to bypass traditional electromechanical access hardware suppliers.
The EU NIS2 Directive through Italian national transposition measures is mandating stricter physical access audit trails and standardized incident reporting formats for critical infrastructure operators. Facility managers must upgrade logging systems to capture granular entry-exit telemetry with real-time alarm integration. Colocation providers in Lombardy are responding by consolidating previously siloed security subsystems into unified command architectures.
Subscription-based security-as-a-service models are displacing capital-intensive on-premises command center investments among mid-size Italian colocation operators. These providers previously faced barrier-to-entry constraints from integrated physical-cybersecurity system costs. The shift is most visible in secondary Italian markets including Turin and Naples, where operators seek centralized visibility without dedicated security operations center staffing.
Italy Data Center Physical Security Market Segmentation
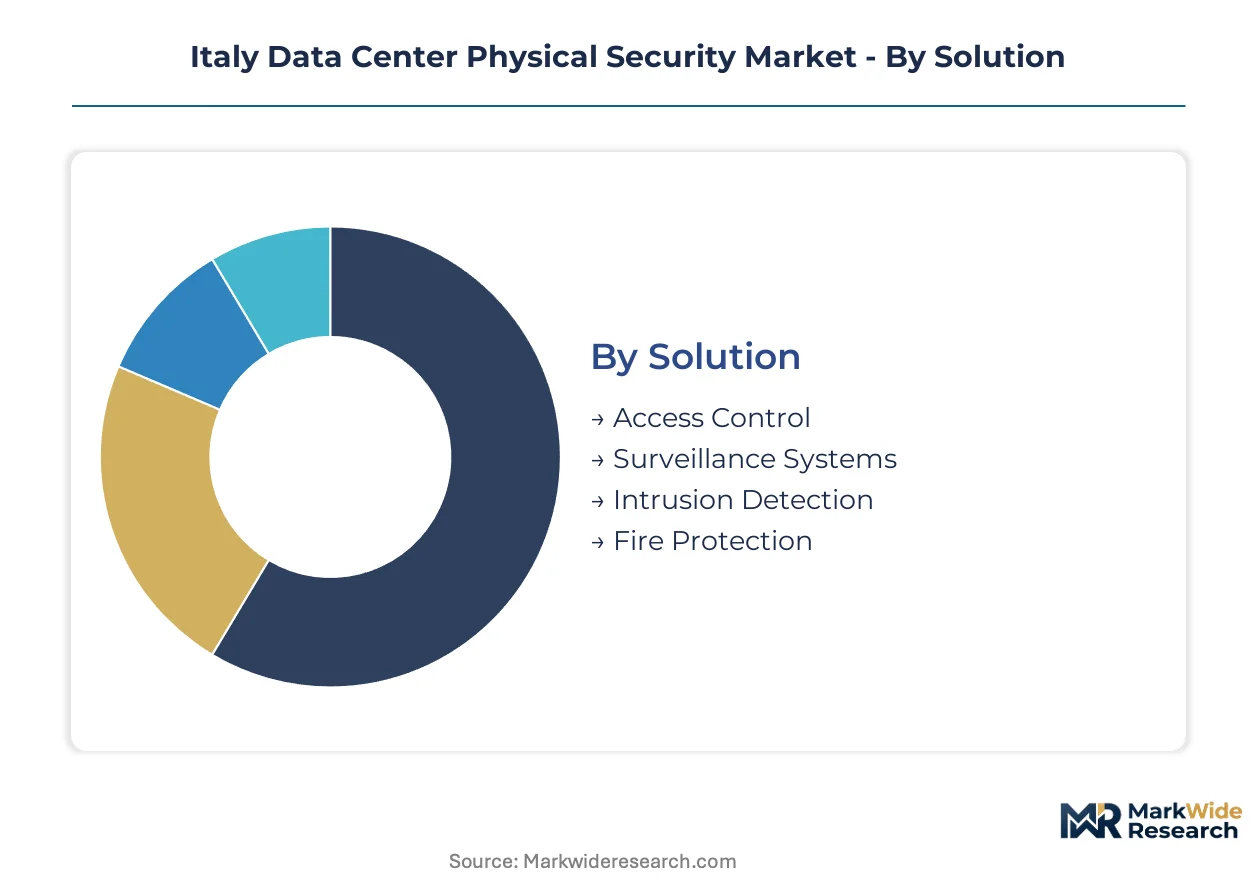
Segmentation in Italy's data center physical security market reveals how compliance mandates and facility tiers reshape procurement patterns. Channel strategies diverge sharply between hyperscale operators in Lombardy and mid-size colocation providers in secondary cities.
Solution:
Channel mix varies by solution complexity, with integrated command center deployments flowing through certified systems integrators while standalone components move via distributor networks.
- Access Control:Multi-factor biometric entry protocols dominate Tier III and Tier IV facility specifications across Milan's Lombardy corridor. Financial services tenants mandate these systems for audit compliance, compressing deployment timelines for colocation providers facing EU NIS2 deadlines.
- Surveillance Systems:Video analytics platforms with facial recognition capabilities are displacing legacy CCTV installations in hyperscale facilities. Demand concentrates among telecommunications operators upgrading perimeter monitoring to satisfy critical infrastructure designation requirements.
- Intrusion Detection:Perimeter barrier sensors and motion detection arrays protect facility boundaries.
- Fire Protection:Clean agent suppression systems align with CE marking requirements under EU Construction Products Regulation.
By volume, Access Control leads. By growth pace, Surveillance Systems with embedded analytics is expanding most quickly.
Technology:
Cost tier differentiation separates premium biometric deployments in Tier IV facilities from standard alarm configurations in edge computing sites.
- Biometrics:Fingerprint and facial recognition systems with liveness detection are fragmenting traditional card-based credential markets. Italian financial services data centers in Milan adopt these for multi-factor entry protocols that satisfy tenant audit requirements.
- CCTV:IP-based camera networks with edge processing capabilities reduce bandwidth overhead for real-time monitoring. Healthcare operators in Rome deploy these for patient data protection compliance.
- Alarm Systems:Integrated intrusion alerts feed directly to facility operations centers.
- Environmental Monitoring:Temperature and humidity sensors protect computing infrastructure from thermal failures.
By installed base, CCTV retains the largest footprint. By adoption velocity, Biometrics is gaining share fastest among new facility constructions.
Installation:
Customer type determines deployment model, with hyperscale operators favoring on-premises command centers while mid-size providers adopt subscription-based alternatives.
- On-premises:Dedicated security operations centers with localized data retention satisfy stringent audit requirements for government and defense facilities. These installations demand certified cybersecurity-physical security integration specialists currently in short supply across northern Italy.
- Cloud-integrated:Centralized visibility platforms eliminate capital-intensive infrastructure investments for mid-size colocation providers in Turin and Naples. The model compresses upfront expenditure while maintaining ISO 27001-aligned logging standards.
- Hybrid:Mixed architectures balance local processing with remote backup capabilities.
- Remotely Monitored:Third-party security operations center oversight reduces staffing requirements for edge computing sites.
By revenue contribution, On-premises installations dominate. By expansion trajectory, Cloud-integrated models show the steepest growth among providers outside established Lombardy clusters.
End User:
Application urgency varies by sector, with financial services and telecommunications facing the most compressed compliance timelines under EU NIS2 transposition.
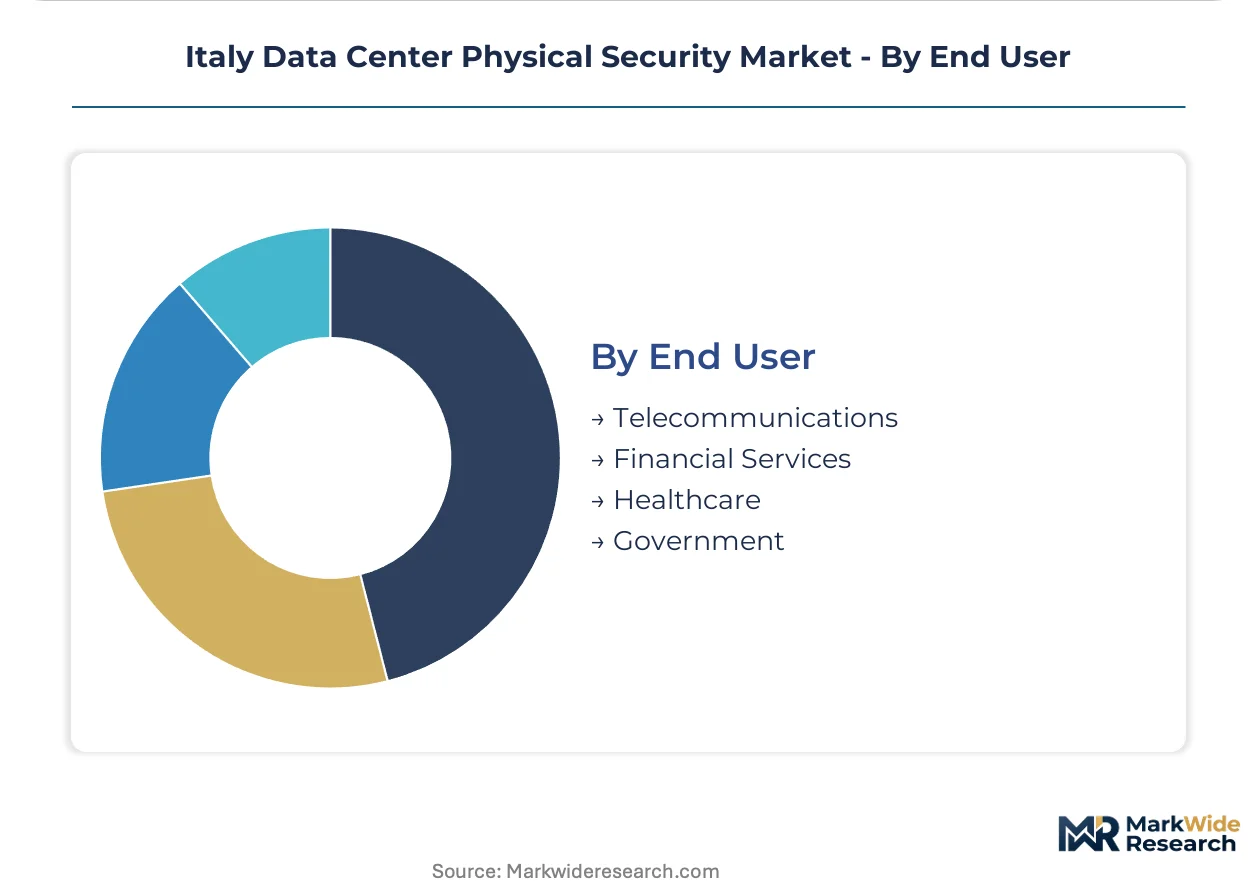
- Telecommunications:Critical infrastructure designation subjects operators to mandatory physical access audit trail upgrades. Facility managers must consolidate previously siloed security subsystems into unified command architectures before regulatory deadlines.
- Financial Services:Multi-factor biometric entry protocols are non-negotiable for data center tenancy agreements. Milan-based colocation providers deploy these systems to attract banking and insurance clients with stringent security requirements.
- Healthcare:Patient data protection mandates drive surveillance and access control investments in Rome and northern Italy.
- Government:National security classifications require specialized perimeter defense and intrusion detection configurations.
By procurement volume, Telecommunications leads. By regulatory pressure intensity, Financial Services shows the most accelerated upgrade cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian data center operators deploy physical security systems with heavier emphasis on biometric-video convergence than their European counterparts, while German and French facilities prioritize perimeter hardening and UK operators favor cloud-integrated monitoring architectures.
Germany
Hyperscale operators in Frankfurt's Rhine-Main corridor drive demand for multi-layered access control systems. The country's national critical infrastructure regulator enforces stringent physical protection standards under the IT Security Act. Bavarian data center clusters near Munich are upgrading electromechanical barriers to satisfy tenant audit requirements from financial services clients.
France
Île-de-France colocation providers are consolidating siloed security subsystems into unified command architectures. ANSM and CNIL guidelines shape biometric data handling protocols for facility access logs. Paris-area operators are deploying facial recognition analytics to satisfy multi-factor entry mandates from banking tenants.
United Kingdom
London hyperscale facilities are adopting subscription-based security-as-a-service models to reduce capital expenditure. The National Cyber Security Centre provides physical security guidance that influences procurement specifications. Slough's data center corridor is seeing accelerated cloud-integrated platform adoption among mid-size colocation providers.
Netherlands
Amsterdam's Schiphol-Rijk data center cluster demands energy-efficient safety system architectures to manage rising operational costs. The Dutch Authority for Digital Infrastructure enforces EU NIS2-aligned physical access audit requirements. Randstad-area operators are deploying integrated intrusion detection arrays to satisfy critical infrastructure designation standards.
Spain
Madrid colocation providers are expanding biometric entry protocol deployments to attract international financial services tenants. The country's national cybersecurity institute mandates standardized incident reporting formats for critical data center operators. Barcelona's emerging technology corridor is seeing cloud-integrated security model adoption among regional operators.
Italy Data Center Physical Security Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Italy's data center physical security market. Electromechanical access hardware suppliers with deep integrator relationships command premium positioning in Milan's Lombardy corridor, while video analytics specialists fragment the surveillance segment through biometric-video convergence offerings. Strategic moves center on certified technician workforce expansion and energy-efficient safety system development to address labor scarcity and rising operational cost pressures.
Within the integrated building automation tier, Honeywell International Inc and Siemens AG exemplify multinational vendors leveraging industrial heritage for multi-site security management contracts. ASSA ABLOY occupies a position representing electromechanical access hardware specialists with established Italian integrator networks. These three anchors illustrate how vendor archetypes map to distinct procurement channels across Tier III and Tier IV facility deployments.
| Leading Market Players |
|---|
| Honeywell International Inc |
| ABB Ltd |
| ASSA ABLOY |
| Cisco Systems Inc |
| Siemens AG |
| Schneider Electric |
| Hangzhou Hikvision Digital Technology Co Ltd |
| Bosch Sicherheitssysteme GmbH |
| Axis Communications AB |
| Others |
Pricing and Supply Chain Analysis
Biometric sensor substitution for electromechanical card readers is redrawing procurement economics across Italian data center security deployments, compressing hardware margins while elevating software licensing value pools for Milan-area integrators.
Pricing Analysis
Long-term service contracts dominate procurement for Tier III and Tier IV facilities, with colocation providers favoring multi-year security-as-a-service agreements over capital-intensive on-premises installations. Three-tier pricing structure across premium, standard, and economy levels separates biometric-video converged systems from standalone access hardware and basic alarm configurations. Cost compression in mid-tier cloud-integrated platforms is intensifying because semiconductor input volatility pressures electromechanical component suppliers. Mid-size colocation operators in Turin and Naples exhibit highest price sensitivity, while financial services tenants in Lombardy prioritize certification-grade systems regardless of premium positioning.
Supply Chain Analysis
Germany and the Netherlands anchor electromechanical access hardware production for Italian data center deployments, while Taiwan and South Korea feed semiconductor components for biometric systems and edge-processing cameras. Copper wiring, rare-earth magnets for door actuators, and CMOS image sensors constitute critical input dependencies. Single-source vulnerability concentrates in specialized biometric algorithm licensing from a narrow vendor set. Distribution runs through certified systems integrators for complex command center deployments, with distributor networks handling standalone component fulfillment to smaller operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against cloud-native security platforms that displace traditional on-premises command center architectures among mid-size Italian colocation providers.
For Market Incumbents: Shield installed base relationships by embedding energy-efficient safety system development into Milan-area service contracts, countering Siemens AG's low-power positioning. Deepen backward integration into biometric sensor calibration capabilities to reduce exposure to Taiwan semiconductor lead time volatility. Prioritize certification investment for EU NIS2-aligned audit trail systems ahead of transposition deadlines. For New Entrants and Emerging Players: Differentiate on facial recognition analytics with liveness detection for Rome and Turin brownfield retrofits, where legacy card system complexity deters incumbent vendors. Target edge computing sites in secondary Italian markets outside Lombardy, where critical infrastructure designation expansion will trigger compliance-driven procurement cycles. Pursue partnership routes with regional systems integrators lacking biometric-video convergence expertise. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialist acquisition over greenfield capacity build. Long-term viability hinges on cloud-integrated platform penetration rates across mid-tier providers. Acquisition target archetype: biometric-video convergence specialists with certified technician workforces in northern Italy. Watch cloud-native security platform adoption velocity among Naples and Turin operators as inflection indicator for traditional hardware displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric-Video Convergence Development | Facial recognition with behavioral analytics fragments traditional card-based access markets in Milan Tier III facilities. |
| Certified Technician Workforce Expansion | Training programs address scarcity of cybersecurity-physical security integration specialists across northern Italy. |
| Cloud-Integrated Platform Launch | Subscription models displace capital-intensive command centers for mid-size Turin and Naples operators. |
| Energy-Efficient Safety Architecture Investment | Low-power designs reduce operational overhead for Lombardy operators facing rising utility costs. |
| EU NIS2 Compliance Service Bundling | Integrated audit trail and incident reporting packages capture compliance-driven procurement from telecommunications operators. |
Research Methodology
Desk research of EU regulatory filings, CE marking databases, and Italian critical infrastructure designations preceded structured interviews with data center facility managers, security systems integrators, biometric technology vendors, and colocation procurement leads. Primary fieldwork captured deployment timelines, budget allocation patterns, and vendor selection criteria across Lombardy, Rome, and Turin clusters. Secondary validation drew from hyperscaler capex disclosures, SEC filings of listed security vendors, and customs data for electromechanical access hardware imports. Bottom-up facility-level sizing and top-down sectoral expenditure estimates were triangulated to constrain variance.
Variance decomposition across solution type, technology tier, installation model, and end-user sector shaped the analytical framework over the projection horizon. CAGRs were derived from facility expansion pipelines, regulatory deadline schedules, and substitution elasticity estimates for biometric versus card-based systems. Modeled inputs included EU NIS2 transposition timing, CE marking compliance cost trajectories, and cloud-integrated platform adoption curves among mid-size providers.
Material uncertainties — copper and semiconductor price volatility, certified technician pipeline constraints, and critical infrastructure designation scope expansion — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and tenant security specification evolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Containerized Data Center Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
Taiwan Data Center Rack Market
Data Center Infrastructure
Thailand Data Center Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
North America Hyperscale Data Center Market
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
APAC Green Data Center Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
North America Data Center Infrastructure Management Market
Data Center Infrastructure
Beijing Data Center Market
Data Center Infrastructure
North America Data Center Server Market
Data Center Infrastructure
Netherlands Data Center Physical Security Market
Data Center Infrastructure
Malaysia Data Center Storage Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Italy Data Center Power Market