
 Italy Data Center Power Market | 2026-2036
Italy Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Data Center Power Market Insights
Tier-III and Tier-IV reliability specifications is redrawing procurement priorities across Italian data center developments. Schneider Electric SE leverages its integrated power management portfolio to anchor major colocation projects in Northern Italy. ABB Ltd competes through advanced medium-voltage switchgear tailored to hyperscale campus designs. Riello UPS SpA dominates the uninterruptible power supply segment with manufacturing roots in the Veneto region.
Data center power encompasses the electrical infrastructure systems that convert, distribute, condition, and safeguard energy flowing to servers, storage, and networking equipment, typically operating at voltages from 400V AC down to 48V DC rack-level feeds with redundancy architectures spanning N+1 to 2N configurations. This infrastructure ensures continuous operation during grid disturbances and enables scalability from single-megawatt edge sites to hundred-megawatt hyperscale campuses. UPS systems command the largest installed base among power type segments, while backup generators capture premium margins tied to extended runtime requirements. Cloud services applications outpace enterprise data centers in capacity additions as hyperscale operators commit to multi-facility Italian deployments.
Italy's National Energy Strategy aligns with EU Green Deal efficiency mandates and F-Gas Regulation phase-down schedules, pushing operators toward liquid cooling and renewable-backed power architectures. BIS-equivalent electrical safety standards and CE marking requirements govern equipment certification, while ARERA grid codes shape interconnection timelines for large loads. Stakeholders must weigh stranded asset risk against the capital intensity of next-generation power topologies as efficiency thresholds tighten.
Market Dynamics
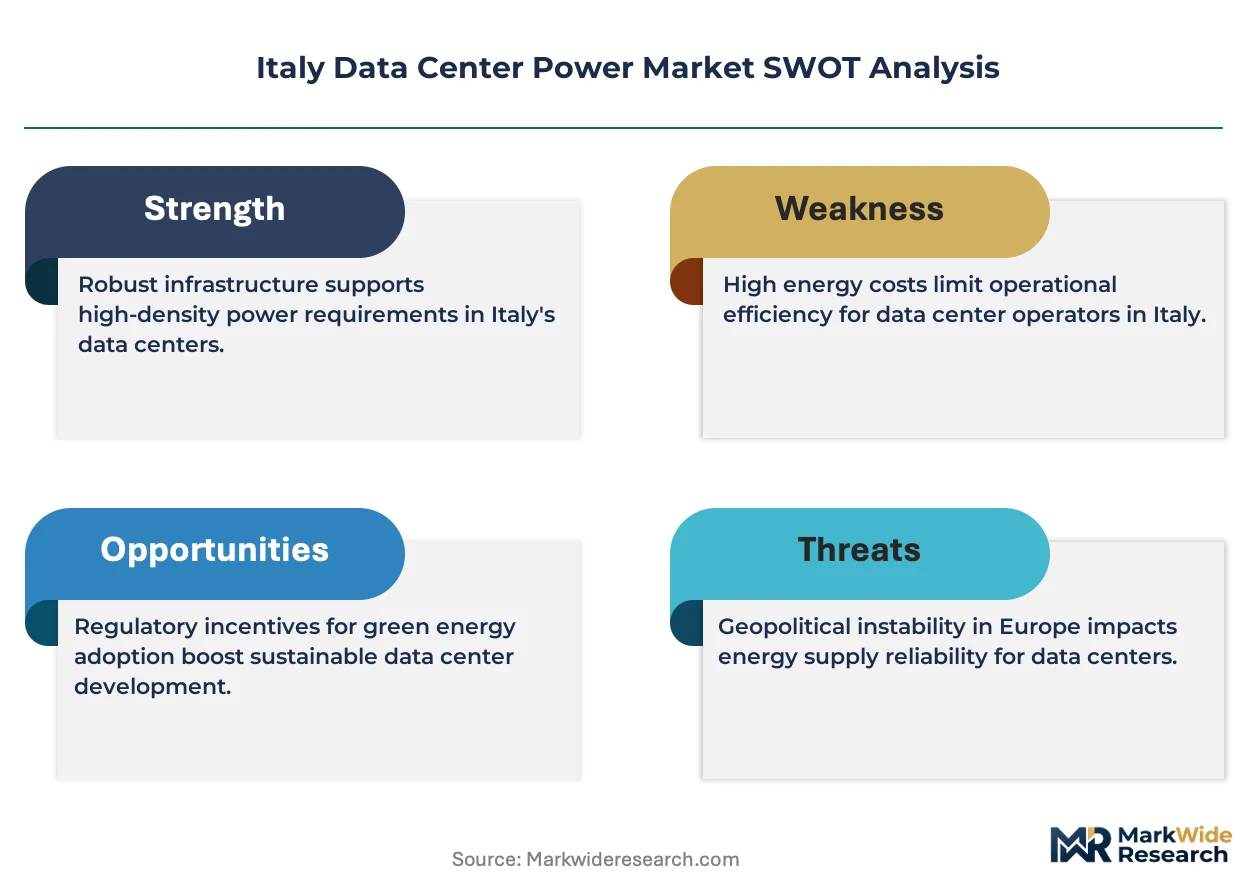
EU Green Deal efficiency mandates are compressing design cycles for Italian data center power infrastructure, forcing operators to pre-commit to liquid-cooled architectures and renewable-backed topologies before load factors justify the capital outlay.
Growth Catalysts
- Hyperscale Cloud Expansion:Amazon Web Services, Google Cloud, and Microsoft Azure are committing to multi-facility Italian deployments, concentrating demand for high-reliability power systems in the Milan corridor.
- F-Gas Regulation Phase-Down:The EU F-Gas Regulation is accelerating displacement of conventional refrigerants in cooling systems, creating pull-through demand for integrated power and thermal management solutions.
- National Energy Strategy Alignment:Italy's renewable energy targets are channeling grid investment toward Lombardy and Veneto, reducing interconnection timelines for data center loads.
Market Restraints
- Copper and Rare Earth Price Volatility:Medium-voltage switchgear and transformer cores face input cost pressure from commodity swings, compressing margins on fixed-price EPC contracts.
- Generator Set Supply Concentration:Backup power systems rely on a concentrated European supplier base, creating delivery risk for hyperscale projects with synchronized commissioning schedules.
- Grid Interconnection Queues:ARERA grid codes impose extended technical study periods for loads exceeding 50 MW, stretching project timelines in saturated transmission zones.
Strategic Opportunities
- Edge Computing in Southern Italy:Latency-sensitive applications are driving distributed facility deployment in Campania and Sicily, opening demand for modular UPS and containerized power skids.
- EU AI Act Compliance Infrastructure:The EU AI Act's energy disclosure requirements for high-risk AI systems are creating specification pull for sub-metered power distribution units with real-time monitoring.
- Hydrogen-Ready Generator Retrofit:Dual-fuel backup power architectures are emerging as a convergence play between existing diesel infrastructure and Italy's hydrogen valley development in Emilia-Romagna.
Industry Challenges
- Medium-Voltage Engineering Talent Scarcity:Specialized skills for 15-36 kV switchgear design and commissioning are concentrated among aging practitioner pools in Northern Italy.
- CE Marking Timeline Compression:Novel power electronics architectures face extended conformity assessment periods under BIS-equivalent electrical safety standards, delaying product launches.
- Legacy 400V AC Integration:Hyperscale 48V DC rack-level designs must interface with existing Italian building infrastructure, adding engineering complexity and fault coordination risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Data Center Power Market |
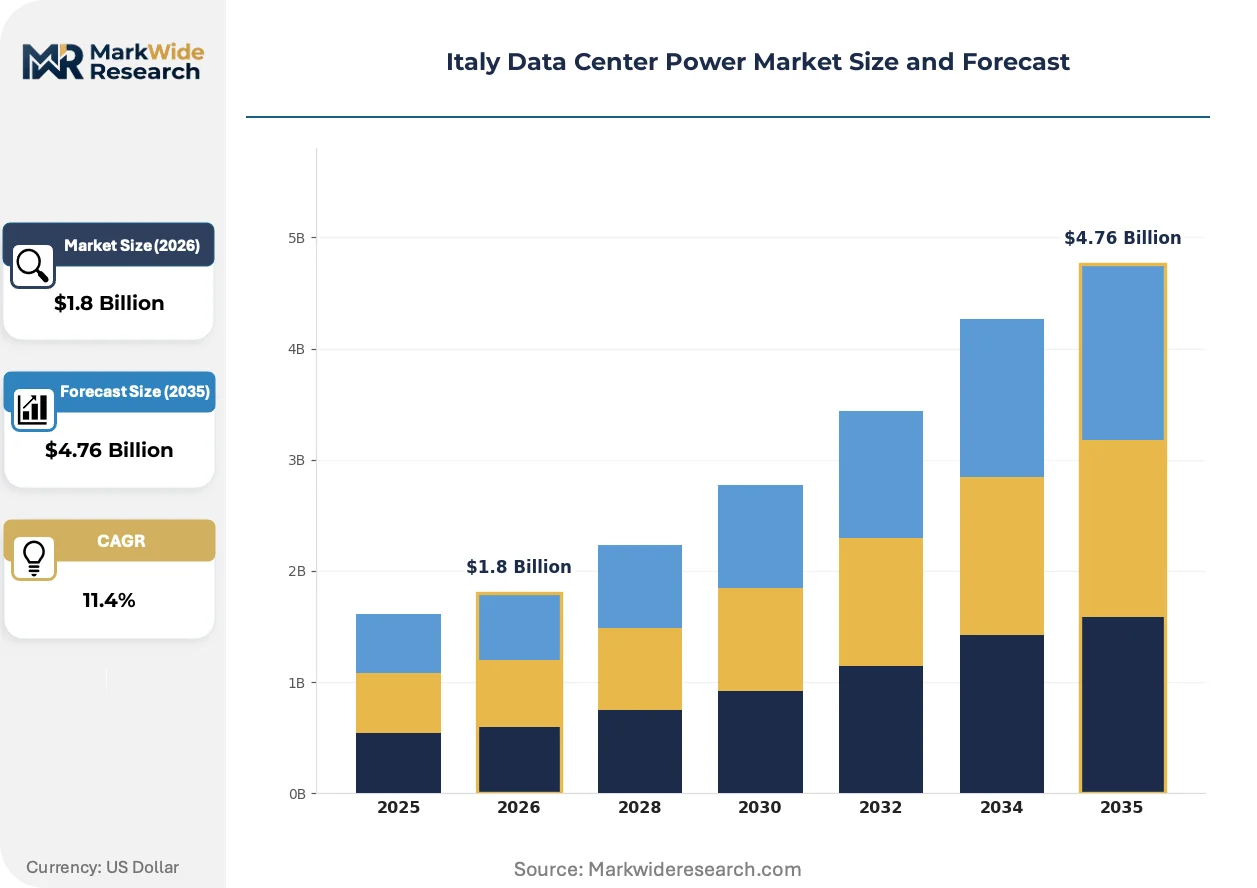
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Type: UPS, Backup Generators, Power Distribution Units, Power Supply Units Application: Cloud Services, Colocation Services, Managed Hosting, Enterprise Data Centers Customer Type: SMEs, Large Enterprises, Government Organizations, Telecommunication Providers Technology: AI Optimization, Energy Management, Renewable Integration, Virtualization |
| Companies Covered | ABB Ltd, Schneider Electric SE, Vertiv Group Corp., Eaton Corporation plc, Caterpillar Inc., Cummins Inc., Riello UPS SpA, Legrand Group, Siemens AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Data Center Power Market Trends and Innovations
Liquid cooling integration is redrawing power architecture specifications across Italian facilities, with thermal and electrical design converging at the rack level rather than operating as separate engineering workstreams.
Busway power distribution is decomposing traditional raised-floor PDU deployments in hyperscale Milan facilities. Colocation operators are specifying overhead busbar systems for 400A-1600A feeds to reduce copper runs and enable hot-swappable tap boxes. This topology is compressing mechanical-electrical coordination timelines and forcing EPC contractors to acquire busway fabrication capabilities in-house.
The EU Green Deal's stricter energy efficiency standards for digital infrastructure are mandating power usage effectiveness thresholds that legacy air-cooled designs cannot meet. Italian operators must now pre-certify facility designs against these benchmarks to secure planning permits. Hyperscale campus projects in the Lombardy region are responding with integrated solar-plus-storage microgrids that shift grid synchronization risk to the developer.
Power procurement is consolidating under hyperscale direct-negotiation models that bypass traditional colocation intermediaries. Enterprise buyers with sub-5 MW loads are losing pricing leverage as vendor sales organizations restructure around anchor tenants. This bifurcation is most visible in the Milan metropolitan area, where cloud operators command dedicated manufacturing slots from Italian switchgear suppliers.
Italy Data Center Power Market Segmentation
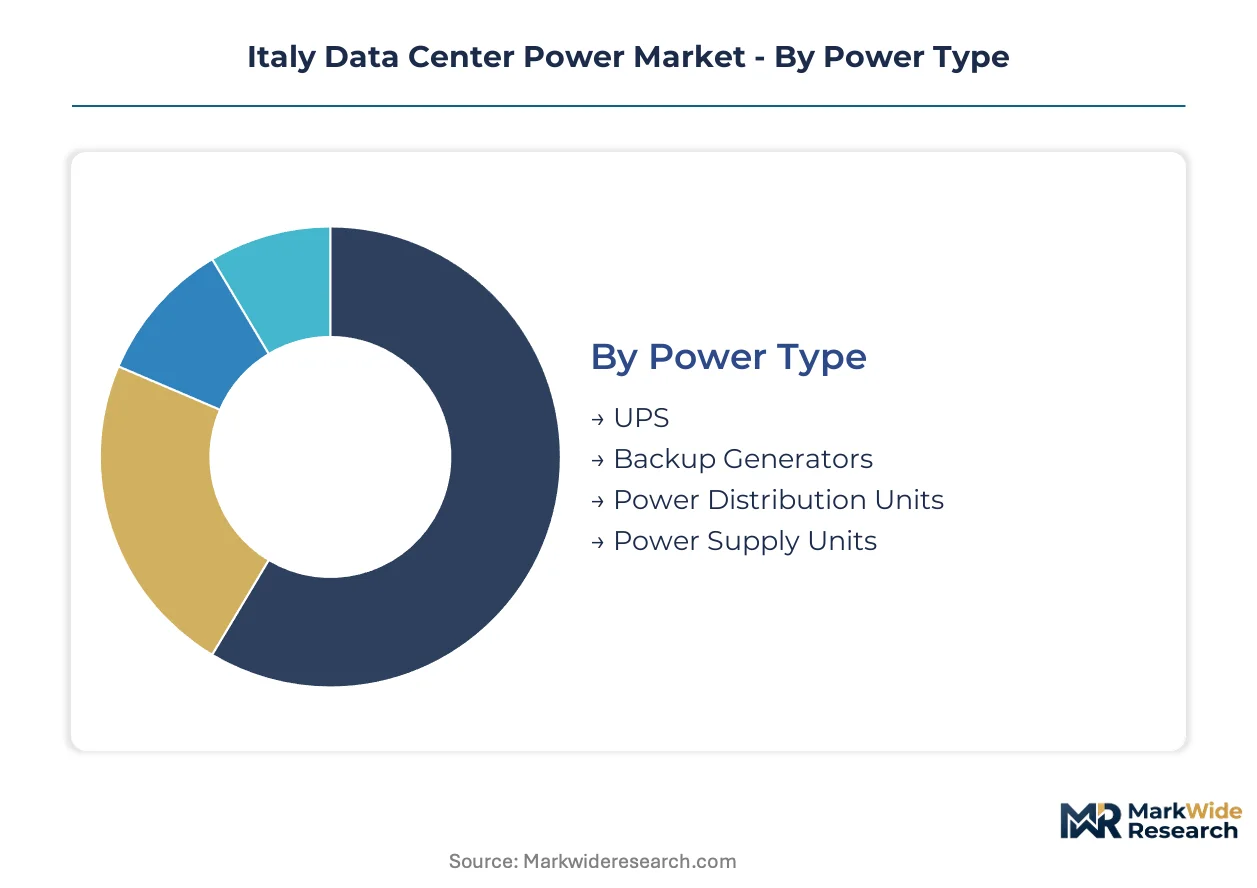
Power infrastructure procurement patterns diverge sharply across deployment scales and reliability tiers in Italy. Hyperscale operators negotiate directly with switchgear manufacturers while smaller deployments rely on standardized product lines. Understanding these segment boundaries clarifies where vendor consolidation and margin compression concentrate.
Power Type:
Substitution pressure from integrated rack-level architectures is compressing standalone product margins, particularly where liquid cooling convergence eliminates discrete power conditioning layers.
- UPS:Double-conversion online systems dominate Italian hyperscale specifications for harmonic isolation and zero-transfer switching. Milan corridor colocation operators specify 500-2000 kVA modular blocks with lithium-ion battery integration to meet EU Green Deal efficiency mandates.
- Backup Generators:Diesel-electric sets with 72-hour fuel storage anchor Tier-III and Tier-IV facility designs. Delivery queues from concentrated European engine suppliers stretch commissioning timelines for synchronized hyperscale campus rollouts.
- Power Distribution Units:Intelligent rack-level units with branch circuit monitoring enable sub-metered energy disclosure required by EU AI Act compliance.
- Power Supply Units:Titanium-efficiency 48V DC rectifiers interface with legacy 400V AC Italian building infrastructure, adding fault coordination complexity.
UPS systems anchor the volume base while backup generators gain share at the steepest rate as extended runtime requirements harden in utility interconnection queues.
Application:
Customer procurement scale determines pricing leverage, with direct hyperscale negotiations bypassing traditional channel structures that serve fragmented demand.
- Cloud Services:Amazon Web Services, Google Cloud, and Microsoft Azure commit to multi-facility Italian deployments with 100+ MW campus designs. These operators specify integrated solar-plus-storage microgrids to shift grid synchronization risk internally.
- Colocation Services:Northern Italian operators face stranded asset risk as efficiency thresholds tighten under EU Green Deal mandates. Busway power distribution is displacing raised-floor PDU topologies in Milan facilities to compress mechanical-electrical coordination.
- Managed Hosting:Mid-market providers in Lombardy and Veneto lack capital for liquid-cooled pre-commitment, narrowing their addressable contract base.
- Enterprise Data Centers:Sub-5 MW loads lose vendor attention as sales organizations restructure around anchor tenants, forcing reliance on standardized product tiers.
Cloud services command the capital deployment while colocation services face the steepest margin compression from efficiency mandate pre-commitment requirements.
Customer Type:
Procurement authority concentration varies dramatically, with state-backed buyers imposing domestic content requirements that distort vendor selection.
- SMEs:Price-taker position in consolidated supply chains forces acceptance of extended lead times and reduced configuration flexibility.
- Large Enterprises:Direct manufacturer relationships for medium-voltage switchgear bypass distribution channels in saturated transmission zones.
- Government Organizations:Public procurement codes favor CE-marked equipment from EU-established suppliers, reinforcing Schneider Electric and ABB positions.
- Telecommunication Providers:Edge computing deployments in Campania and Sicily drive modular UPS demand for latency-sensitive infrastructure.
Large enterprises anchor procurement volume while telecommunication providers expand most quickly into distributed southern Italian markets.
Technology:
Technology maturity curves determine implementation risk, with unproven architectures facing extended conformity assessment under BIS-equivalent electrical safety standards.
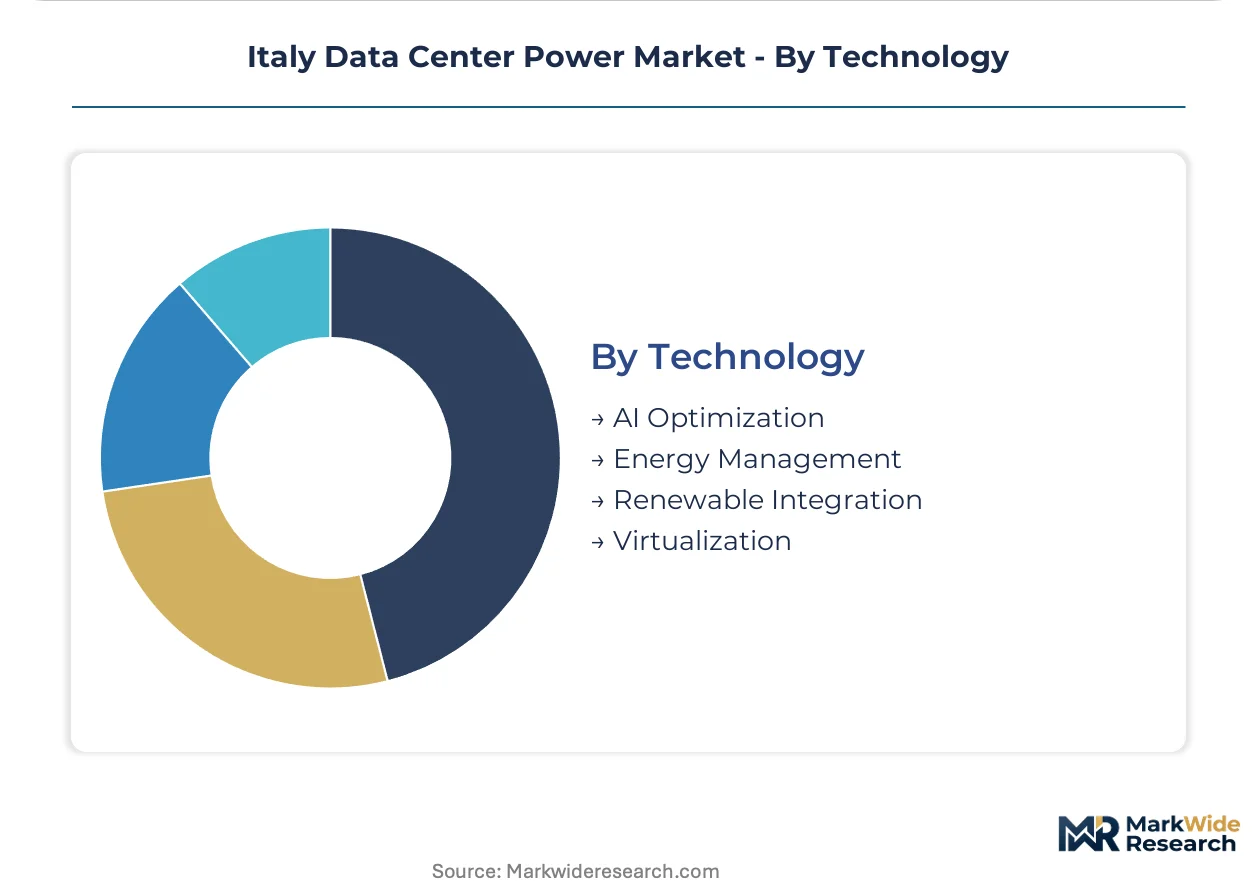
- AI Optimization:Predictive load forecasting algorithms reduce oversizing penalties in variable-density rack environments. Hyperscale operators in Milan pilot neural-network-based power capping to defer transformer upgrades.
- Energy Management:Real-time PUE monitoring with ARERA grid code integration enables demand response participation for large loads exceeding 50 MW.
- Renewable Integration:Solar-plus-storage microgrids pre-certify against EU Green Deal benchmarks to secure Lombardy planning permits.
- Virtualization:Software-defined power architectures face CE marking timeline compression as novel electronics trigger extended conformity assessment.
Energy management anchors deployment scale while AI optimization climbs the fastest as hyperscale operators seek transformer deferral economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German switchgear exports flow into Milan corridor hyperscale projects as EU Green Deal efficiency mandates reshape procurement patterns across Southern European data center developments.
Lombardy
Hyperscale cloud operators anchor demand concentration in the Milan metropolitan area where fiber connectivity and renewable energy access converge. ARERA grid codes govern interconnection timelines for loads exceeding 50 MW, compressing project schedules. Tier-III and Tier-IV facilities cluster along the Milan-Bergamo axis as colocation operators pre-commit to liquid-cooled architectures.
Veneto
UPS manufacturing heritage concentrates in the Veneto region where local production roots support rapid deployment timelines for modular power blocks. CE marking requirements under BIS-equivalent electrical safety standards govern equipment certification for export-qualified suppliers. Verona and Vicenza host specialized commissioning teams for medium-voltage switchgear integration.
Piedmont
Turin anchors engineering talent pools for 15-36 kV switchgear design as aging practitioner scarcity intensifies across Northern Italy. The National Energy Strategy channels renewable grid investment toward Piedmont's alpine hydroelectric resources. Hyperscale developers negotiate directly with switchgear manufacturers to bypass traditional distribution channels.
Emilia-Romagna
Hydrogen valley development in Emilia-Romagna creates convergence opportunities for dual-fuel backup power architectures. Bologna and Modena host EPC contractors acquiring busway fabrication capabilities to serve hyperscale campus timelines. F-Gas Regulation phase-down schedules accelerate displacement of conventional refrigerants in integrated thermal-electrical designs.
Lazio
Rome government procurement codes favor CE-marked equipment from EU-established suppliers, reinforcing positions of integrated power management portfolios. Public sector data center modernization drives specification pull for sub-metered power distribution units. Latency-sensitive edge applications remain underpenetrated compared to Northern Italian load concentrations.
Italy Data Center Power Market Competitive Landscape
Listed leaders compete with private specialists across integrated power management portfolios as procurement authority concentrates under hyperscale direct-negotiation models. The vendor base stratifies between full-stack platform providers and component specialists serving standardized product tiers. Two dominant archetypes emerge: integrated electrical infrastructure platforms anchoring major colocation projects, and regional manufacturing specialists dominating uninterruptible power supply segments. Competitive moves center on busway fabrication capability acquisition and lithium-ion battery integration partnerships.
Within the integrated platform tier, Schneider Electric SE and ABB Ltd exemplify divergent approaches to hyperscale campus design. Schneider leverages its portfolio breadth to anchor major colocation projects across Northern Italy. ABB competes through advanced medium-voltage switchgear tailored to synchronized commissioning schedules. Among regional specialists, Riello UPS SpA occupies a position reflecting deep manufacturing roots in the Veneto region.
| Leading Market Players |
|---|
| ABB Ltd |
| Schneider Electric SE |
| Vertiv Group Corp. |
| Eaton Corporation plc |
| Caterpillar Inc. |
| Cummins Inc. |
| Riello UPS SpA |
| Legrand Group |
| Siemens AG |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion battery substitution for valve-regulated lead-acid systems in Italian UPS deployments redraws procurement geography toward Asian cell manufacturers while compressing lifecycle pricing economics for European system integrators. This chemistry migration concentrates supply leverage with producers in China and South Korea, forcing Milan-based operators to accept longer order cycles in exchange for energy density gains that satisfy EU Green Deal efficiency mandates.
Pricing Analysis
Next-generation 48V DC rack-level architectures command substantial premiums over legacy 400V AC infrastructure, while transitional lithium-ion UPS systems occupy a narrowing mid-band between mature lead-acid and emerging solid-state alternatives. Three-tier pricing structure across premium titanium-efficiency rectifiers, standard double-conversion UPS blocks, and economy-grade standby systems reflects certification tier and volume scale differentiation. Pricing pressure stems from copper and rare earth commodity volatility feeding into medium-voltage switchgear contracts. SMEs face acute price sensitivity as hyperscale direct negotiations capture manufacturing priority slots from Italian suppliers.
Supply Chain Analysis
Strategic stockpiling of diesel generator engines and medium-voltage switchgear components dominates procurement behavior as hyperscale campus synchronization schedules create demand spikes that outstrip European foundry capacity. Supply concentrates in Germany for switchgear fabrication, China for lithium-ion cells, and Italy for final UPS assembly and busway integration. Raw material dependencies span copper conductors, rare earth magnetic materials, and semiconductor power modules. Single-source vulnerability concentrates in concentrated European engine suppliers for backup generators. Distribution runs through EPC contractors with captive electrical fabrication capabilities serving Northern Italian load clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against liquid-cooled integrated power architectures that eliminate discrete UPS layers entirely, eroding the addressable market for standalone power conditioning equipment.
For Market Incumbents: Secure lithium-ion battery integration partnerships with established cell suppliers to defend margin position against chemistry-agnostic competitors. Acquire busway fabrication capabilities in-house to capture EPC contractor value that hyperscale developers currently internalize. Channel control through direct service relationships with ARERA-interconnected loads exceeding 50 MW anchors pricing power.
For New Entrants and Emerging Players: Differentiate on hydrogen-ready generator retrofit capabilities that align with Emilia-Romagna hydrogen valley development timelines. Target edge computing deployments in Campania and Sicily where latency-sensitive applications drive modular UPS demand underserved by Northern Italian supply chains. Go-to-market through telecommunication provider procurement frameworks that bypass saturated Milan corridor competition.
For Investors and Strategic Acquirers: EU AI Act energy disclosure requirements reshape the acquisition landscape toward sub-metered power distribution specialists with real-time monitoring capabilities. Long-term viability centers on vendors capable of bridging 400V AC legacy infrastructure to 48V DC hyperscale standards without stranding existing customer investments. Acquisition targets combine CE marking expertise with liquid cooling integration capabilities. The signal to watch is ARERA queue position for loads exceeding 50 MW as interconnection priority determines revenue recognition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Busway Fabrication Capability Acquisition | EPC contractors internalize overhead power distribution to compress Milan hyperscale project timelines. |
| Lithium-Ion Battery Integration Partnership | UPS manufacturers secure cell supply chains against chemistry substitution risk from solid-state alternatives. |
| Hydrogen-Ready Generator Retrofit Program | Backup power suppliers align with Emilia-Romagna hydrogen valley development for dual-fuel positioning. |
| AI-Optimized Load Forecasting Platform | Hyperscale operators defer transformer upgrades through neural-network-based power capping in variable-density racks. |
| Solar-Plus-Storage Microgrid Development | Developers shift ARERA grid synchronization risk internally to secure Lombardy planning permits under EU Green Deal benchmarks. |
Research Methodology
Desk research of ARERA regulatory filings, EU Green Deal implementation guidelines, and hyperscaler capex disclosures preceded structured interviews with data center facility directors, EPC contractor project managers, medium-voltage switchgear procurement leads, and ARERA interconnection planners. Secondary validation drew from CE marking databases, F-Gas Regulation compliance registries, and Lombardy regional planning authority records. Bottom-up facility-level capacity aggregation triangulated against top-down vendor shipment analysis to reconcile market sizing.
Variance decomposition across power type, application tier, and regional load concentration segments isolates growth contribution by technology maturity curve position over the projection horizon. CAGRs derive from installed base replacement cycles, efficiency mandate compliance deadlines, and hyperscale commitment timelines. Industry-specific forecast inputs incorporate ARERA queue depth for loads exceeding 50 MW and lithium-ion battery cost trajectory assumptions.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale commitment to Italian deployment, stable ARERA interconnection timelines, or copper price volatility within historical bands would require recalibration. Forecasts reflect documented assumptions regarding EU Green Deal enforcement consistency and F-Gas Regulation phase-down adherence. Revision becomes warranted when medium-voltage engineering talent scarcity crosses thresholds that delay commissioning schedules beyond contractual penalty clauses.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
Sweden Data Center Construction Market
Data Center Infrastructure
Europe Hyperscale Data Center Market
Data Center Infrastructure
India Data Center Power Market
Data Center Infrastructure
APAC Green Data Center Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
Poland Data Center Construction Market
Data Center Infrastructure
Public Cloud System Infrastructure Service Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Netherlands Data Center Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Saudi Arabia Data Center Power Market
Data Center Infrastructure
France Data Center Power Market