
 Thailand Data Center Market | 2026-2036
Thailand Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Data Center Market Insights
Thailand's Board of Investment incentive framework is rebalancing capital allocation toward energy-efficient facility construction. ST Telemedia Global Data Centres leverages its Singapore heritage to anchor premium colocation capacity in Greater Bangkok. True Internet Data Center competes through integrated telecom-data center bundling. Gulf Energy Development Public Company Limited extends its power generation expertise into captive renewable supply for server farms.
A data center constitutes a dedicated facility housing servers, storage systems, and networking equipment with controlled temperature (18-27°C), humidity (40-60% RH), and redundant power feeds to ensure continuous digital service availability. These installations process, store, and distribute data for enterprise IT, cloud platforms, and content delivery networks. Colocation and cloud services command the dominant revenue share as enterprises shed owned infrastructure. Edge computing deployments within virtualization architectures represent the fastest-expanding technology layer, driven by latency-sensitive applications in manufacturing and autonomous systems. Hyperconverged infrastructure consolidates storage, compute, and networking into single appliances, compressing deployment timelines for mid-market buyers in the retail and healthcare verticals.
The National Broadcasting and Telecommunications Commission governs spectrum and facility licensing, while the Board of Investment structures tax holidays that directly shape foreign direct investment location decisions. The Ministry of Energy enforces efficiency standards that filter equipment procurement toward liquid cooling and low-PUE designs. Stakeholders must weigh land scarcity in Bangkok against fiber latency advantages as they evaluate greenfield versus brownfield expansion paths.
Market Dynamics
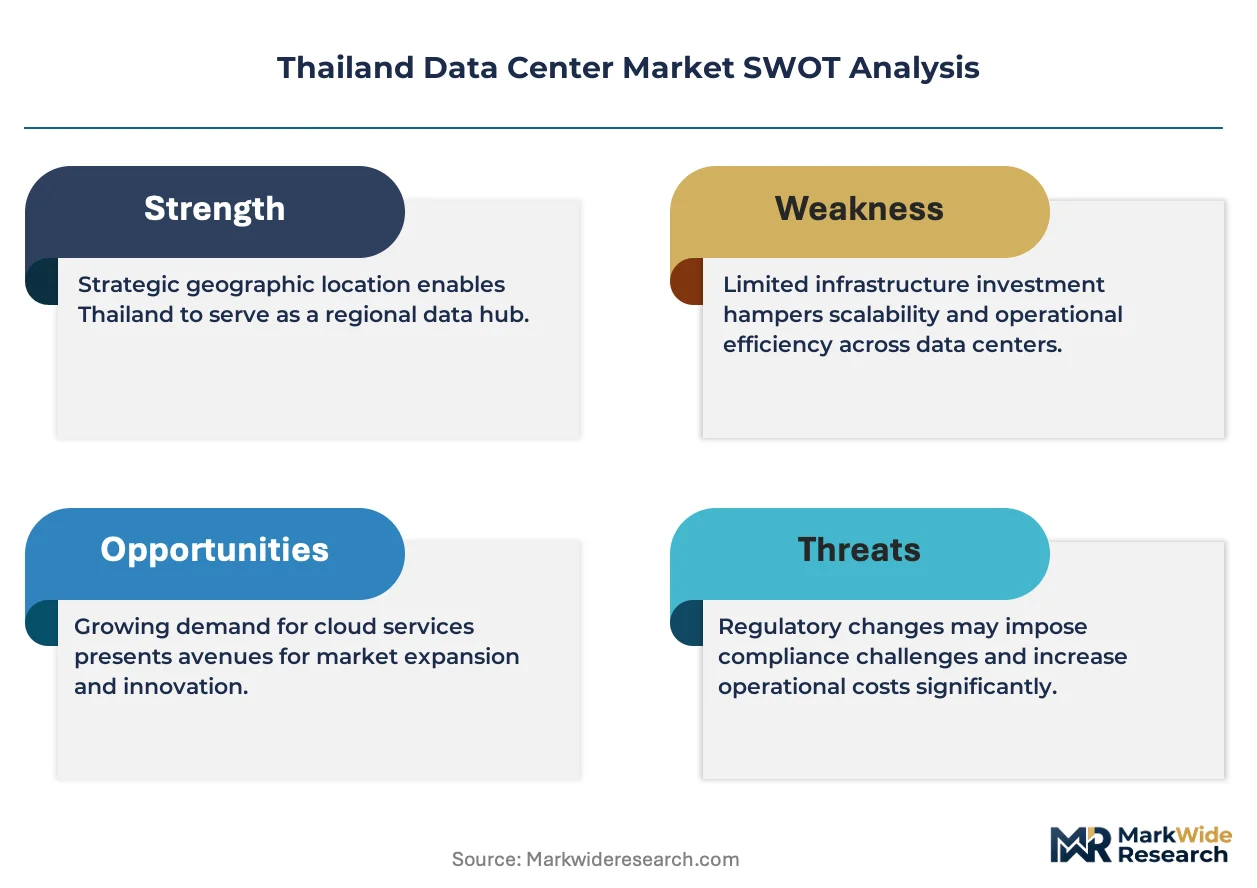
Thailand's data center market is undergoing a structural transformation driven by the convergence of sovereign cloud mandates and renewable energy procurement requirements, forcing operators to redesign facility architectures around liquid cooling and captive solar generation.
Growth Catalysts
- Board of Investment Incentives:Thailand's BOI offers eight-year tax holidays for digital infrastructure investments, redirecting capital toward Bangkok and the Eastern Economic Corridor.
- Hyperscale Cloud Expansion:Global cloud providers are establishing availability zones to serve ASEAN enterprises, creating demand for certified Tier III+ facilities.
- 5G Network Rollout:The National Broadcasting and Telecommunications Commission's spectrum allocation is driving edge computing deployments for latency-sensitive industrial automation.
Market Restraints
- Land Scarcity in Bangkok:Prime fiber-connected sites command premium valuations, compressing project returns for greenfield developments.
- Grid Interconnection Queues:Provincial utility capacity constraints delay power-up timelines by 18-24 months in high-demand zones.
- Cooling Equipment Import Dependence:Precision air handling units and chillers rely on Southeast Asian manufacturing hubs, exposing procurement to regional supply volatility.
Strategic Opportunities
- Eastern Economic Corridor Expansion:Chonburi and Rayong provinces offer land banks with submarine cable landing station proximity for submarine cable diversity.
- AI Workload Specialization:GPU-dense configurations for generative AI training represent an underserved premium segment requiring high-density power and direct liquid cooling.
- Cross-Border Data Flow Frameworks:ASEAN Digital Masterplan 2025 harmonization creates arbitrage potential for Thailand-based facilities serving regional financial institutions.
Industry Challenges
- Certified Operations Talent Gap:Uptime Institute-accredited facility managers remain concentrated in Singapore and Hong Kong, forcing Thai operators to import expertise or accept longer commissioning cycles.
- Legacy System Integration:Enterprise colocation clients require seamless hybrid cloud orchestration with on-premise VMware and mainframe estates, complicating migration roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Data Center Market |
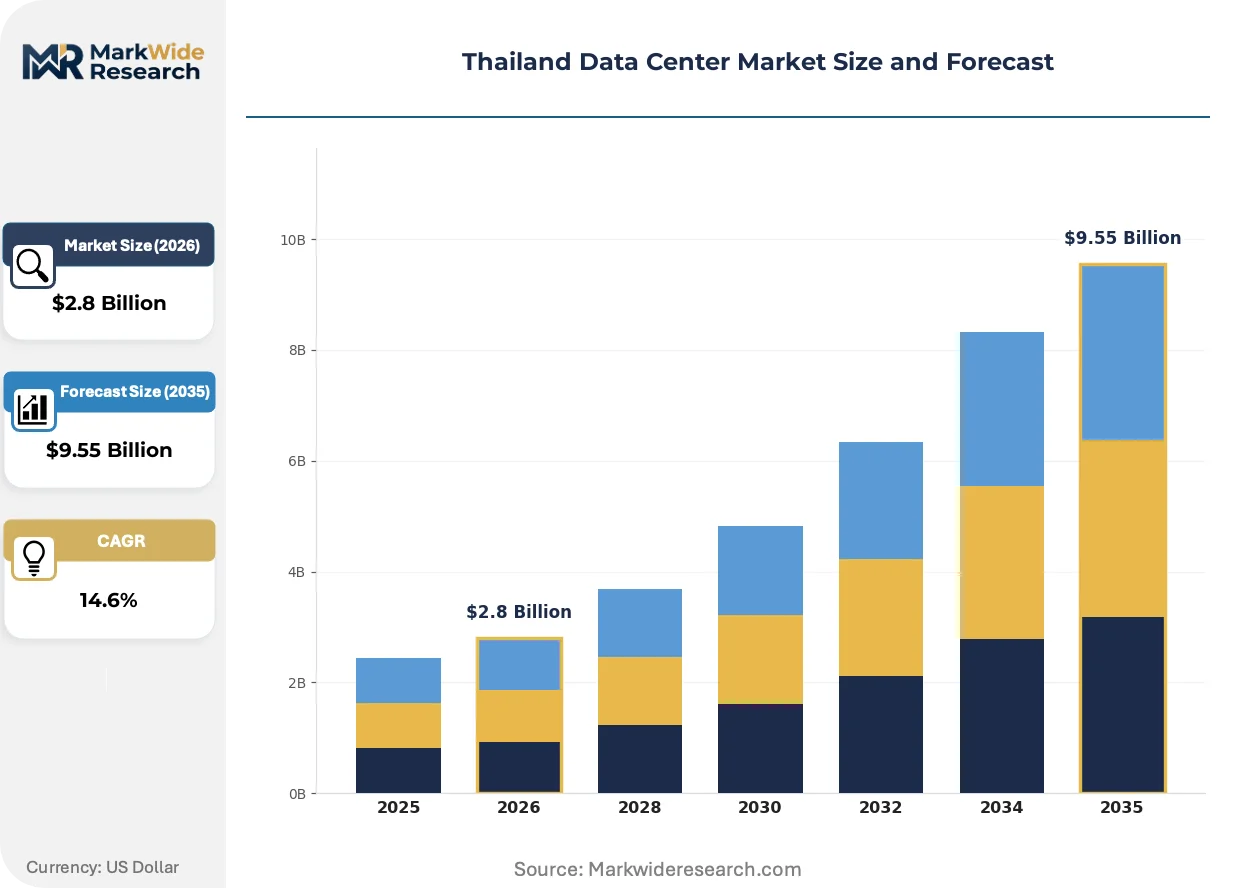
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Cloud Services, Managed Hosting, Disaster Recovery Technology: Virtualization, Edge Computing, Hyperconverged Infrastructure, Modular Designs End User: Telecommunication, BFSI, Retail, Healthcare Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Data Storage |
| Companies Covered | ST Telemedia Global Data Centres, United Information Highway, True Internet Data Center, SUPERNAP Thailand, CS Loxinfo Public Company Limited, AIS Data Center, NTT Global Data Centers, Gulf Energy Development Public Company Limited, NT Data Center, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Data Center Market Trends and Innovations
Liquid cooling architectures and modular construction methods are compressing deployment timelines while Thailand's energy regulators tighten efficiency standards. These shifts are redefining competitive differentiation beyond location and connectivity.
Direct-to-chip liquid cooling is modularizing data center thermal management by replacing perimeter CRAC units with cold plates and coolant distribution units. Hyperscale operators and AI training clusters are adopting this approach to support densities exceeding 50 kW per rack. The technology is modularizing facility design by decoupling power and cooling infrastructure from shell construction, enabling phased capacity expansion.
Thailand's Ministry of Energy is enforcing Power Usage Effectiveness thresholds through building code amendments that mandate sub-1.4 PUE for new facilities. This regulatory pressure is accelerating equipment replacement cycles and favoring operators with in-house engineering capabilities. Colocation providers are responding by pre-certifying designs with the Thailand Green Building Institute to secure enterprise tenants with net-zero commitments.
Enterprise buyers are consolidating vendor relationships through multi-year reserved capacity contracts that bundle interconnection, cross-connects, and managed services. This behavior shift is displacing month-to-month colocation arrangements and compressing sales cycles for providers with integrated platform offerings. Financial services and e-commerce verticals in Bangkok are driving this transition as they seek operational expenditure predictability.
Thailand Data Center Market Segmentation
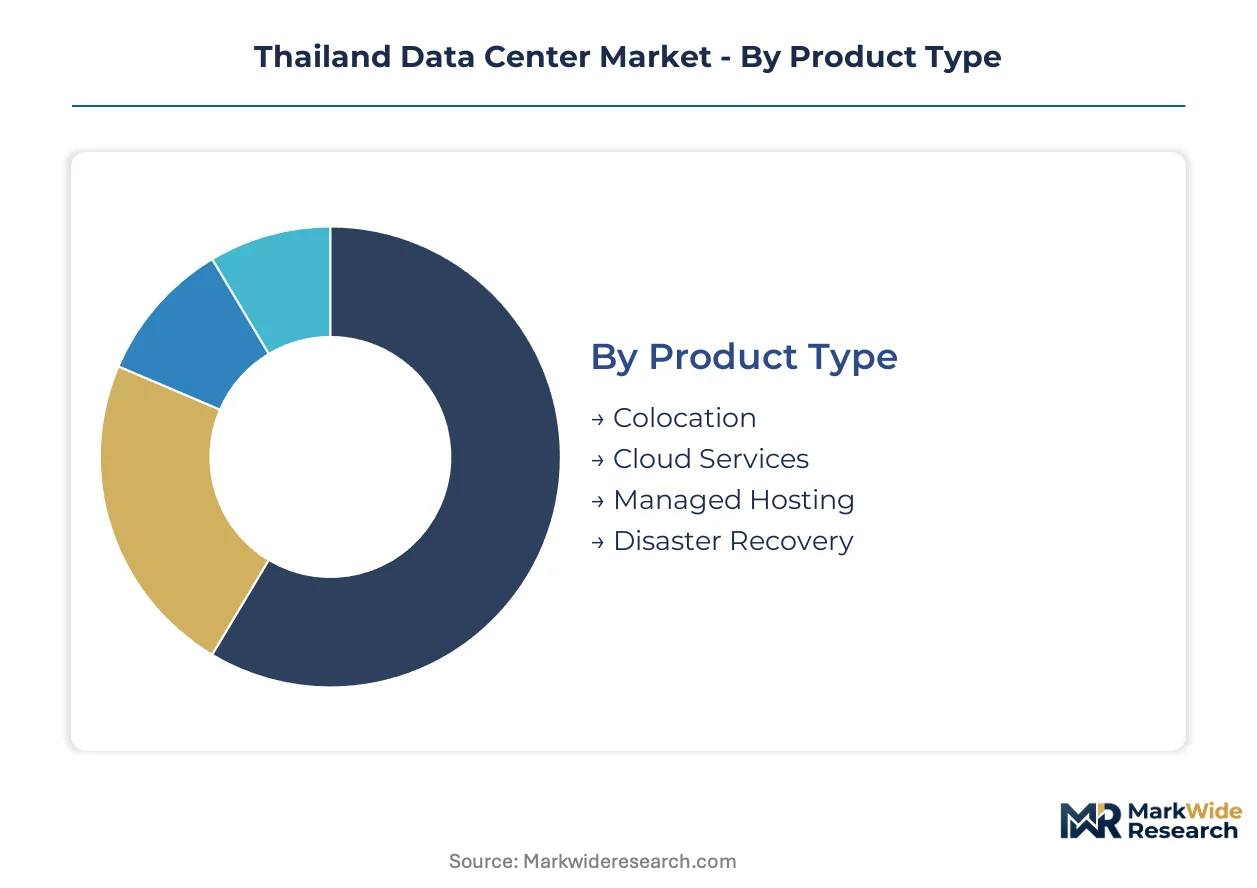
Segmentation in Thailand's data center market reveals how procurement priorities diverge across buyer archetypes. Facility operators and enterprise tenants allocate capital differently based on workload criticality, compliance obligations, and latency requirements.
Product Type:
Cost tier differentiation separates enterprises maintaining owned infrastructure from those pursuing full operational outsourcing.
- Colocation:Physical space, power, and cooling leased within multi-tenant facilities. Bangkok-based financial institutions and regional cloud providers anchor demand for certified Tier III+ white space in the Eastern Economic Corridor.
- Cloud Services:On-demand compute, storage, and networking resources delivered via hyperscale platforms. BFSI institutions in Thailand are expanding sovereign cloud deployments to satisfy data localization mandates while retaining elastic scaling.
- Managed Hosting:Dedicated server environments with vendor-managed maintenance and security patching. Mid-market retailers prefer this model to preserve application control without building in-house operations teams.
- Disaster Recovery:Secondary site replication and failover orchestration for business continuity. Healthcare providers in Greater Bangkok deploy these services to meet Ministry of Public Health uptime requirements for electronic medical records.
Volume sits with Colocation; growth tilts toward Cloud Services.
Technology:
Application workload density determines which infrastructure architectures Thai operators prioritize in facility design.
- Virtualization:Software abstraction layers enabling multiple operating systems on shared hardware. Enterprise IT departments in Thailand's manufacturing sector leverage VMware and Hyper-V to consolidate legacy server sprawl.
- Edge Computing:Distributed processing nodes positioned proximal to data sources. The National Broadcasting and Telecommunications Commission's 5G spectrum allocation is accelerating factory-floor deployments for real-time industrial automation in Rayong and Chonburi provinces.
- Hyperconverged Infrastructure:Integrated compute-storage-networking appliances with unified management planes. Hospital networks in Bangkok adopt these systems to compress deployment timelines for picture archiving and communication systems.
- Modular Designs:Prefabricated data center components enabling phased capacity expansion. Operators facing land scarcity in Bangkok favor this approach to match supply ramp with actual tenant commitments.
Deployment scale favors Virtualization; infrastructure investment is climbing fastest for Edge Computing.
End User:
Customer type shapes facility requirements through divergent compliance, latency, and redundancy specifications.
- Telecommunication:Mobile network operators and fixed-line providers requiring interconnection density and carrier-neutral meet-me rooms. True Corporation and AIS anchor wholesale demand in Thailand for 5G core network hosting.
- BFSI:Banks, insurers, and securities firms with stringent regulatory uptime and audit requirements. The Bank of Thailand's cybersecurity guidelines mandate localized data storage, driving private cloud and colocation contracts.
- Retail:Omnichannel merchants with seasonal traffic volatility and payment processing compliance. E-commerce platforms in Bangkok reserve burst capacity for campaign periods while maintaining baseline loads in shared facilities.
- Healthcare:Hospitals and medical device networks requiring HIPAA-equivalent data protection and low-latency imaging access. Ministry of Public Health digitization initiatives are expanding picture archiving and electronic health record hosting demand.
Contract value concentrates with BFSI; facility expansion is accelerating most quickly for Telecommunication.
Service Type:
Margin structure varies with abstraction layer depth and customer technical sophistication.
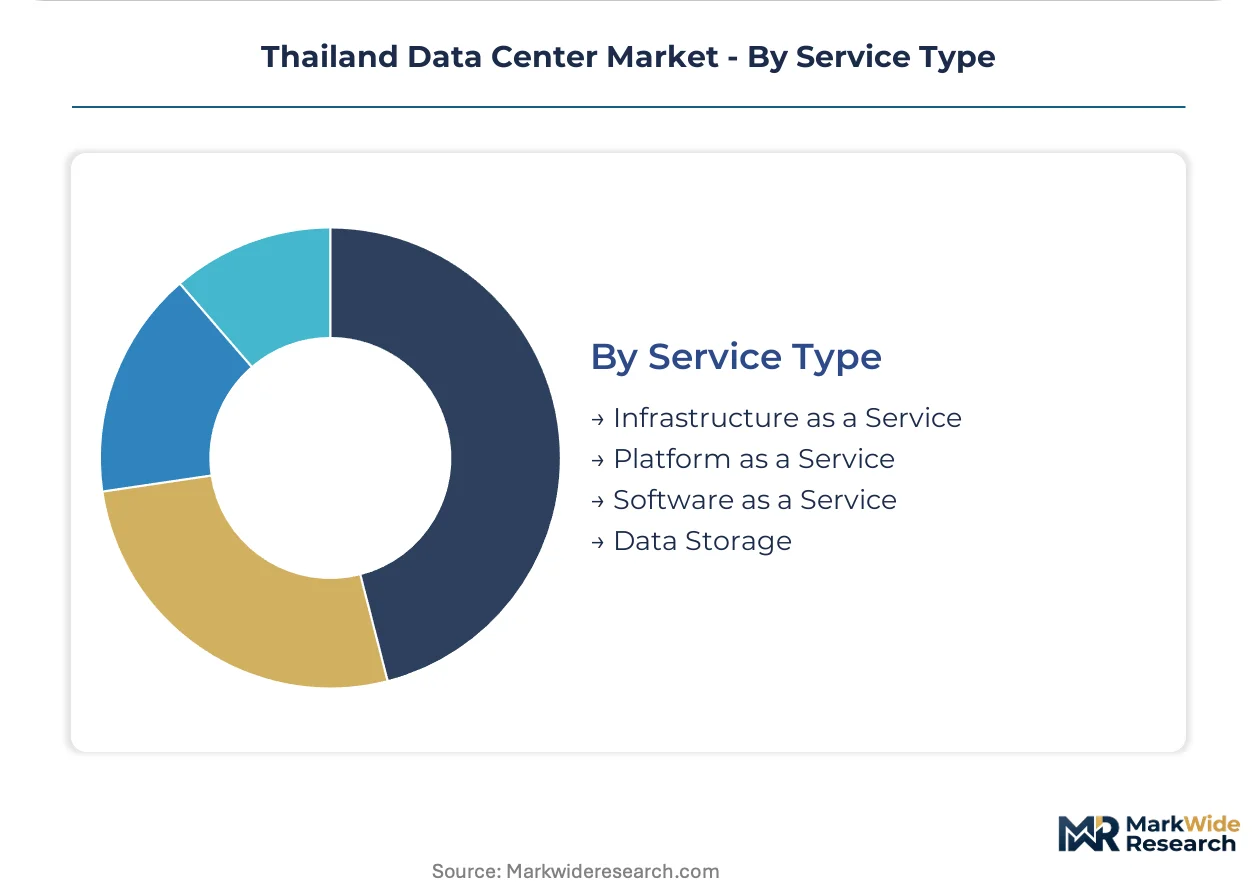
- Infrastructure as a Service:Raw compute, storage, and network resources provisioned through APIs. Thai software startups favor this model to avoid capital expenditure while maintaining infrastructure-as-code deployment practices.
- Platform as a Service:Managed runtime environments with integrated databases, messaging, and development tools. Enterprise development teams in Bangkok's Eastern Economic Corridor adopt these services to accelerate application modernization.
- Software as a Service:Fully managed applications delivered through web interfaces. Small and medium enterprises across Thailand prefer this consumption model for ERP, CRM, and collaboration workloads.
- Data Storage:Object, block, and file storage services with tiered durability and retrieval performance. Media and entertainment companies in Thailand utilize these services for content archive and distribution origin storage.
Revenue scale favors Infrastructure as a Service; customer acquisition is expanding most quickly for Platform as a Service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand consumes data center capacity faster than it produces specialized facility engineering talent, creating reliance on Singapore and Hong Kong for Uptime Institute-certified operations expertise. Domestic construction activity concentrates where Board of Investment incentives intersect with submarine cable landing points.
Bangkok Metropolitan Region
Enterprise financial services and hyperscale cloud availability zones drive absorption in the capital district. The National Broadcasting and Telecommunications Commission licenses facilities under spectrum coordination rules that favor established telecom corridors. Latency-sensitive trading systems and 5G core networks cluster in Ratchada-Ladprao and Bang Na sub-markets.
Eastern Economic Corridor
Chonburi and Rayong provinces attract greenfield development through BOI tax holidays and land availability absent in Bangkok. The Ministry of Energy enforces sub-1.4 PUE standards on new construction, favoring operators with captive renewable generation plans. Industrial automation workloads from manufacturing tenants are accelerating edge computing deployments.
Chiang Mai and Northern Thailand
Cooler ambient temperatures reduce mechanical cooling loads for disaster recovery and archival storage workloads. Provincial utility interconnection queues stretch 18-24 months, delaying power-up timelines. University and government data migration projects are expanding beyond Bangkok-centric infrastructure.
Phuket and Southern Coastal Provinces
Submarine cable diversity objectives position the region for international connectivity redundancy. Tourism sector digitalization is expanding hospitality and payment processing data residency requirements. Limited fiber backhaul capacity constrains large-scale deployment relative to eastern alternatives.
Thailand Data Center Market Competitive Landscape
The competitive structure tilts toward integrated energy-to-digital infrastructure conglomerates with captive power generation assets. Three distinct archetypes occupy the market: Singapore-heritage premium colocation specialists, domestic telecom-data center bundlers, and power utility-backed facility developers. Capacity expansion and strategic land banking in the Eastern Economic Corridor represent the dominant competitive moves as operators secure fiber-connected sites ahead of hyperscale demand.
Among Singapore-based operators, ST Telemedia Global Data Centres anchors the premium-tier segment through Tier III+ certification heritage. True Internet Data Center exemplifies domestic telecom integration with bundled connectivity offerings. Gulf Energy Development Public Company Limited represents the power-to-data center vertical, leveraging generation expertise into captive renewable supply arrangements for server farms.
| Leading Market Players |
|---|
| ST Telemedia Global Data Centres |
| United Information Highway |
| True Internet Data Center |
| SUPERNAP Thailand |
| CS Loxinfo Public Company Limited |
| AIS Data Center |
| NTT Global Data Centers |
| Gulf Energy Development Public Company Limited |
| NT Data Center |
| Others |
Pricing and Supply Chain Analysis
Captive renewable generation integration by Thai power utilities anchors both supply security and pricing power for data center operators facing Ministry of Energy efficiency mandates. This backward control over electricity input costs insulates Tier III+ facilities from grid tariff volatility while compressing competitor margins.
Pricing Analysis
Cost-down pressure on colocation tiers accelerates because hyperscale cloud providers negotiate multi-year reserved capacity blocks with bundled interconnection discounts. Three-tier pricing structure across certified Tier III+, Tier III, and Tier II facilities separates Bangkok financial institutions from manufacturing tenants on cost sensitivity. Price differentiation rests on Uptime Institute certification grade and captive solar supply arrangements. Retail and mid-market healthcare buyers exhibit highest price sensitivity; sovereign cloud deployments for BFSI institutions show lowest elasticity.
Supply Chain Analysis
Precision cooling equipment manufacturing workforce availability concentrates in Singapore, Malaysia, and Taiwan, creating procurement bottlenecks for Thai operators scaling liquid-cooled deployments. Direct-to-chip cold plates and coolant distribution units draw from Southeast Asian component hubs with single-source vulnerability for specialized pump assemblies. Supply chain risk centers on regional logistics chokepoints through the Strait of Malacca. Distribution runs through direct OEM relationships and regional systems integrators rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's data center market is consolidating around power-to-digital infrastructure conglomerates, with Board of Investment tax holidays and land scarcity in Bangkok forcing sub-scale operators toward exit or acquisition.
For Market Incumbents: Lock in fiber-connected land banks in Chonburi and Rayong provinces ahead of hyperscale demand waves. Secure captive renewable generation certificates to meet Ministry of Energy sub-1.4 PUE mandates. Defensive consolidation against Singapore-heritage premium colocation specialists requires accelerated Tier III+ certification investment.
For New Entrants and Emerging Players: AI training clusters requiring GPU-dense configurations represent an underserved buyer archetype with premium pricing tolerance. Target generative AI workloads in the Eastern Economic Corridor with direct liquid cooling capabilities. Go-to-market leverage rests on modular construction compressing 18-24 month deployment timelines.
For Investors and Strategic Acquirers: Exit pathways concentrate in power utility-backed facility developers with captive generation assets. Long-term viability favors operators with integrated energy-to-digital infrastructure spanning the analysis window. Acquisition target archetype: mid-scale colocation providers with BOI-approved land positions but lacking renewable supply arrangements. Watch hyperscale cloud availability zone announcements as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Renewable Generation Buildout | Gulf Energy Development leverages power expertise to supply solar-backed server farms meeting Ministry of Energy mandates. |
| Modular Facility Construction | Prefabricated components enable phased expansion matching tenant commitments amid Bangkok land scarcity constraints. |
| Direct Liquid Cooling Deployment | Cold plate architectures support AI training densities exceeding 50 kW per rack for hyperscale workloads. |
| Submarine Cable Landing Proximity | Eastern Economic Corridor sites near Rayong and Chonburi landing stations reduce latency for ASEAN financial institutions. |
| Uptime Institute Tier III+ Certification | Pre-certified designs attract BFSI tenants with Bank of Thailand cybersecurity localization requirements. |
Research Methodology
SEC filings from hyperscale cloud providers, Thailand Board of Investment incentive disclosures, and National Broadcasting and Telecommunications Commission spectrum allocation records formed the secondary backbone. Primary interviews with data center facility managers, power utility planning officers, and enterprise IT procurement leads at Bangkok-based financial institutions combined with this documentary base. Bottom-up capacity installation tracking and top-down energy consumption modeling enabled triangulation across projection scenarios.
Historical trendline analysis of facility power density evolution and PUE improvement trajectories informed the analytical framework across the modeling period. Segmentation dimensions modeled include service type tier, certification grade, end-user vertical, and captive renewable supply status. CAGRs derived from capacity absorption rates and construction pipeline visibility. Forecast inputs incorporated Ministry of Energy building code amendment timelines and submarine cable landing station expansion schedules.
Revisions become necessary when Board of Investment incentive structures shift, provincial utility interconnection queues extend beyond current 18-24 month baselines, or hyperscale cloud provider availability zone strategies pivot. Forecasts reflect documented assumptions on power density trajectories and renewable procurement timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Cloud Network Infrastructure Market
Data Center Infrastructure
Delhi-NCR Data Center Market
Data Center Infrastructure
Austria Data Center Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
Advanced Data Center Infrastructure Market
Data Center Infrastructure
Israel Data Center Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Singapore Data Center Power Market
Data Center Infrastructure
New Zealand Data Center Power Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Thailand Data Center Power Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Data Center in Middle East Market
Data Center Infrastructure
North America Data Center Power Market