
 North America Hyperscale Data Center Market | 2026-2036
North America Hyperscale Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hyperscale Data Center Market Analytics
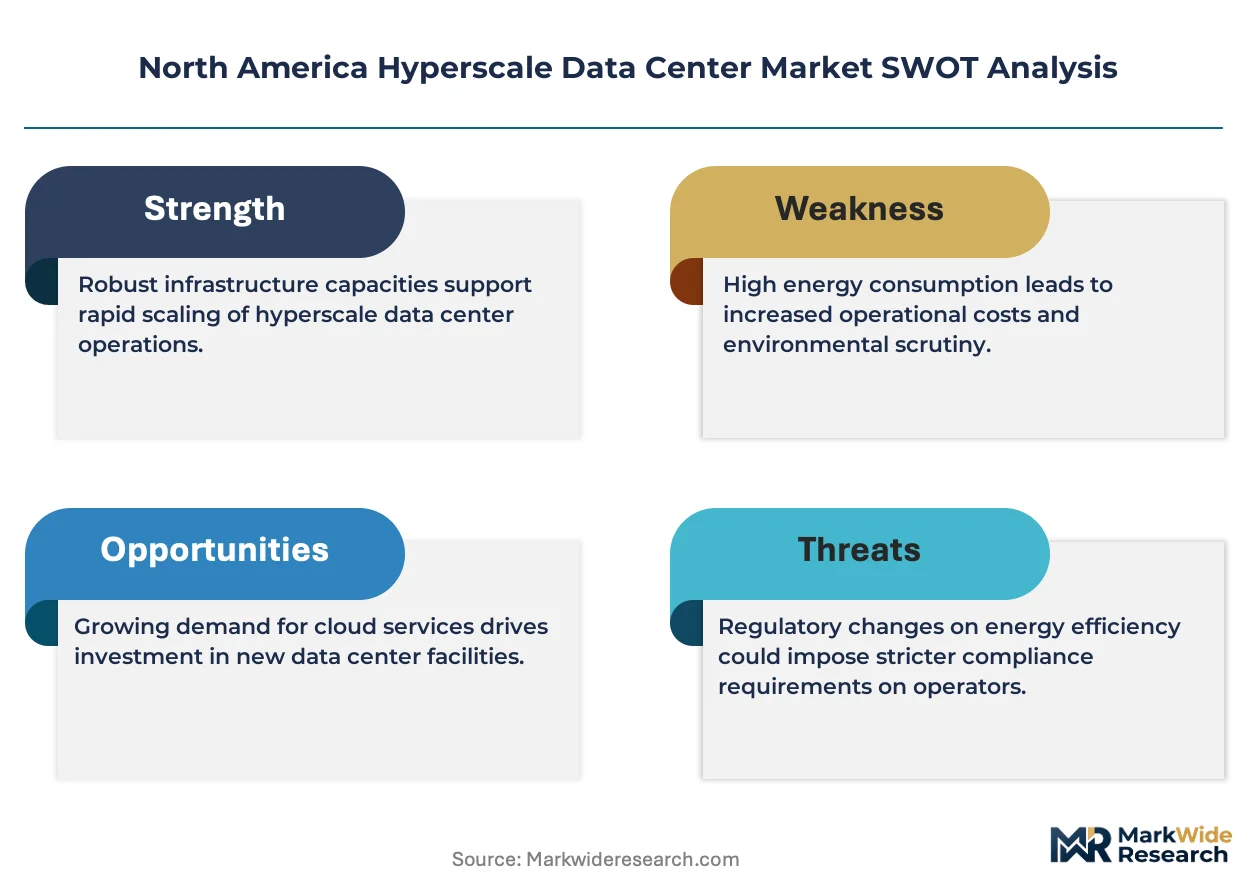
Liquid cooling infrastructure is broadening total addressable economics for high-density deployments. Microsoft leverages its vertical integration into custom silicon and cooling hardware to control rack-level thermal design. Google Cloud anchors its competitive stance through renewable energy matching and advanced evaporative cooling systems across its U.S. footprint. Amazon Web Services dominates wholesale leasing structures, negotiating long-term power purchase agreements that lock in below-market electricity rates.
North America hyperscale data centers constitute purpose-built facilities exceeding 15 megawatts of critical IT capacity, engineered to support cloud, AI, and distributed computing workloads through modular power and cooling architectures. These installations employ redundant electrical distribution, direct liquid cooling manifolds, and software-defined infrastructure orchestration to sustain availability above 99.999 percent. Cloud Service Providers represent the dominant demand segment, capturing the majority of new capacity absorption as training clusters scale beyond 100,000 GPUs per deployment. Colocation Services maintain mature margin pools in primary markets where land and power constraints limit greenfield competition, while Edge deployments register the fastest structural expansion as latency-sensitive applications proliferate.
EPA Energy Star certification and ASHRAE thermal guidelines shape equipment procurement standards, compelling operators to document power usage effectiveness below industry baselines for utility incentive eligibility. State regulators in Texas, Arizona, and Illinois administer divergent water-use and emissions disclosure rules that fragment compliance burdens across the footprint. FERC interconnection queue reform and NERC reliability standards will determine how quickly new generation reaches data center load centers, making grid access timelines the critical variable for capacity planning decisions.
Market Dynamics
Generative AI training clusters exceeding 100,000 GPUs per deployment are compressing facility commissioning timelines from 24 months to 14 months, forcing simultaneous construction of power substations and liquid cooling manifolds.
Growth Catalysts
- FERC interconnection queue reform:Accelerated grid access timelines in Texas and Arizona enable faster energization of multi-hundred-megawatt facilities.
- State renewable portfolio standards:Virginia, Illinois, and California mandates compel operators to match load with carbon-free generation through long-term power purchase agreements.
- Liquid cooling manifolds:Direct-to-chip thermal management supports rack densities above 100 kilowatts, unlocking AI training economics previously constrained by air-cooled limits.
Market Restraints
- Transformer and switchgear lead times:Critical electrical equipment from Asian suppliers now extends 18-24 months, delaying substation completion.
- Water scarcity in Arizona:Evaporative cooling dependence faces municipal withdrawal limits and escalating use fees.
- Copper and aluminum price volatility:Busbar and cable costs fluctuate with commodity markets, compressing EPC contractor margins.
Strategic Opportunities
- Mexico border states:Chihuahua and Nuevo León offer cross-border fiber routes and competitive industrial electricity rates below Texas averages.
- Waste heat recovery:District heating partnerships with municipal utilities convert rejected thermal energy into revenue streams.
- EPA Energy Star certification:Utility incentive eligibility for documented power usage effectiveness below 1.2 accelerates payback on efficiency investments.
Industry Challenges
- High-voltage electrical commissioning:Specialized technicians for 345-kV substation energization command premium wages and limited availability.
- ASHRAE thermal guideline compliance:Documentation requirements for inlet temperature ranges add 6-8 weeks to equipment procurement cycles.
- Legacy facility retrofit complexity:Raised floor infrastructure in older buildings cannot accommodate liquid cooling distribution without structural reinforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hyperscale Data Center Market |
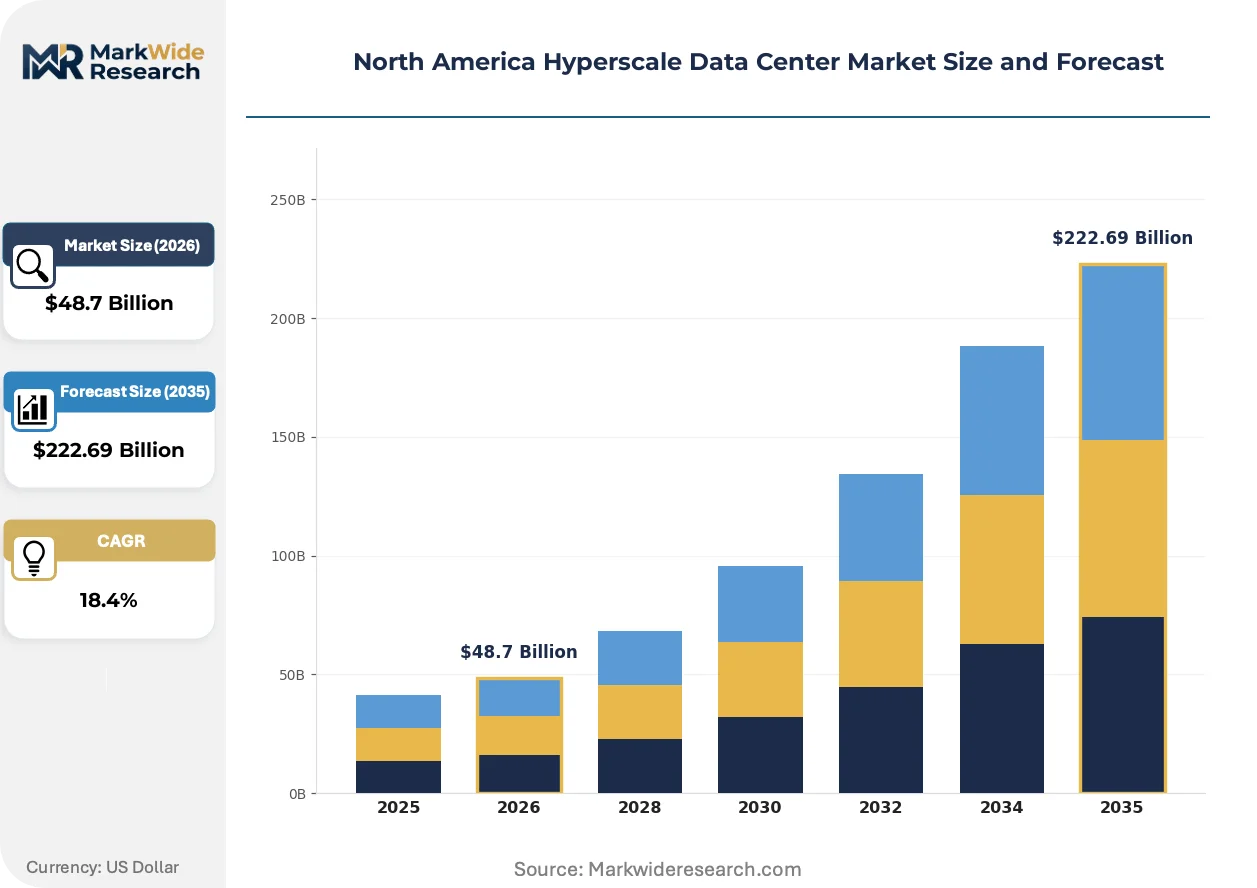
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $222.69 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation Services, Managed Services, Infrastructure as a Service, Platform as a Service Deployment: On-Premises, Cloud-Based, Hybrid, Edge End User: Internet Service Providers, Cloud Service Providers, Enterprises, Telecommunication Companies Technology: Cooling Systems, Power Distribution Units, Rack Servers, Virtualization Solutions |
| Companies Covered | Microsoft, Meta Platforms, Equinix, American Tower, Oracle, Digital Realty, Google Cloud, CyrusOne, Amazon Web Services, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hyperscale Data Center Market Evolving Landscape
Artificial intelligence workloads are rewriting infrastructure specifications, compressing design cycles while elevating thermal and electrical density requirements beyond legacy facility capabilities.
Direct liquid cooling is automating thermal management at rack densities previously requiring dedicated mechanical rooms. Cloud service providers deploy manifold systems feeding cold plates across thousands of GPUs simultaneously. This architecture is automating the elimination of perimeter computer room air handlers, reclaiming 15-20 percent of white space for compute.
EPA carbon emissions reporting mandates now require facility-level disclosure of Scope 1 and Scope 2 sources above 25,000 metric tons annually. Operators must install continuous emissions monitoring systems and submit verified data through the central data exchange. Wholesale colocation providers in Northern Virginia and Dallas-Fort Worth face the steepest compliance burdens given their concentration of covered facilities.
Power purchase agreement structures are displacing traditional utility tariff reliance among hyperscale tenants. Buyers now contract directly with renewable developers for 10-15 year terms, bypassing incumbent utilities. This pattern concentrates in PJM and ERCOT territories where retail choice regulations permit direct wholesale market access.
North America Hyperscale Data Center Market Segmentation
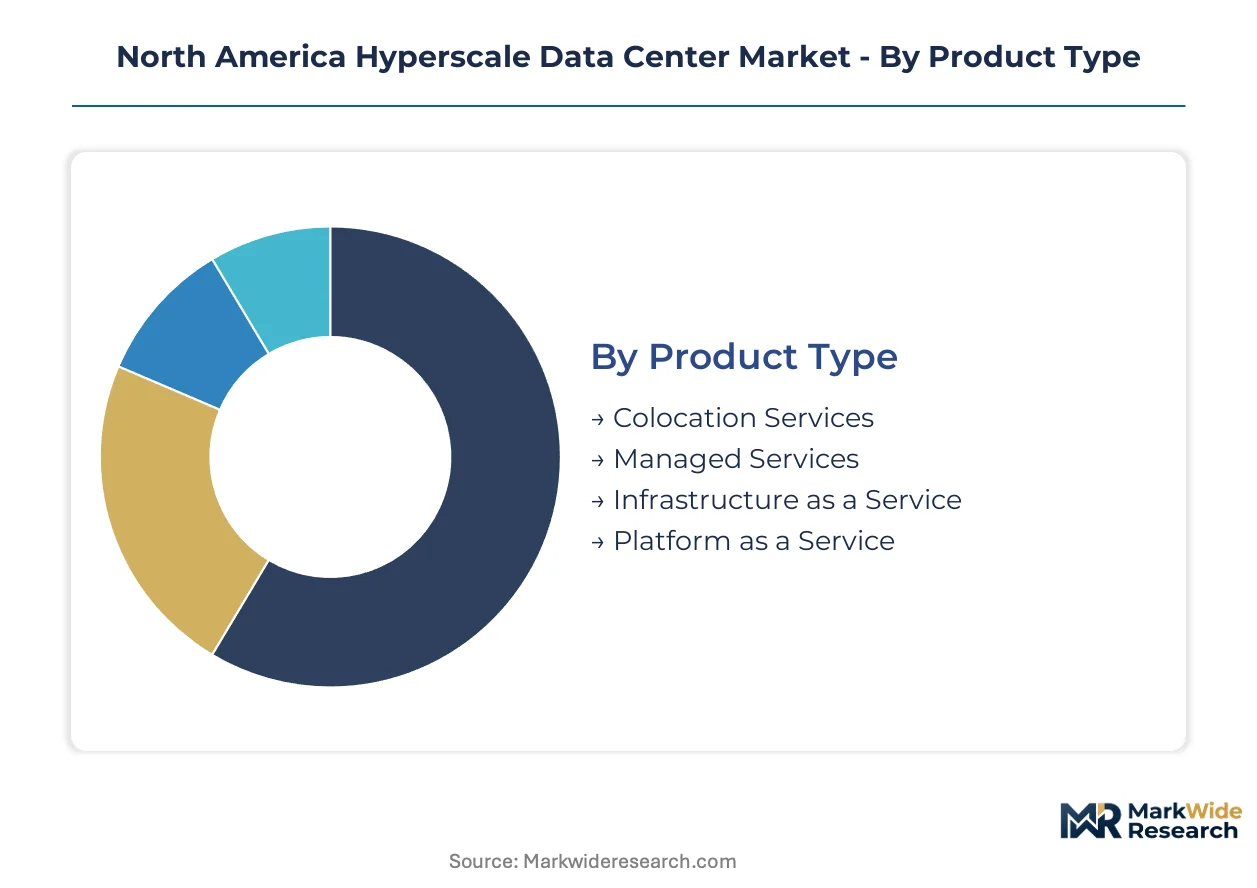
Hyperscale data center segmentation reveals how infrastructure economics fragment across service models, deployment architectures, and thermal technologies. Each dimension carries distinct margin structures and capital intensity profiles that shape operator strategy.
Product Type:
Standalone service offerings dominate revenue capture, while embedded platform capabilities accelerate customer lock-in through deeper integration.
- Colocation Services:Wholesale leasing of powered shell space with cross-connect infrastructure enables cloud providers to deploy proprietary server fleets. Demand concentrates in Northern Virginia and Dallas-Fort Worth where fiber density and tax abatements cluster investment, though land scarcity in primary markets is compressing availability timelines.
- Managed Services:Remote hands, smart hands, and infrastructure monitoring packages extend facility revenue per rack beyond pure space and power. Enterprises in regulated sectors—healthcare and financial services—drive adoption as internal IT teams lack specialized data center operations expertise.
- Infrastructure as a Service:Compute and storage resources provisioned through API-driven orchestration layers.
- Platform as a Service:Application development environments with managed middleware and database services.
Volume placements concentrate in Colocation Services; the faster expansion belongs to Platform as a Service.
Deployment:
Deployment architectures distribute latency risk and capital burden differently across customer types and workload sensitivities.
- Cloud-Based:Multi-tenant facilities operated by hyperscale providers with pooled resource allocation across thousands of customers. Cloud Service Providers absorb the fastest capacity additions as training clusters scale beyond 100,000 GPUs per deployment, forcing simultaneous substation and liquid cooling construction.
- Edge:Micro-facilities positioned within 10 milliseconds of population centers for latency-sensitive applications. Autonomous vehicle data ingestion, industrial IoT control systems, and content delivery networks are driving greenfield development in secondary metros including Columbus, Ohio and Reno, Nevada.
- On-Premises:Captive facilities owned and operated by single enterprises for compliance or performance isolation.
- Hybrid:Orchestrated workload placement across owned and leased infrastructure with unified management planes.
Cloud-Based deployments anchor current capacity absorption; Edge infrastructure is climbing the fastest as 5G networks densify.
End User:
Customer concentration varies sharply by deployment scale, with wholesale buyers driving facility-level economics and enterprise accounts filling marginal capacity.
- Cloud Service Providers:Amazon Web Services, Microsoft Azure, and Google Cloud Platform negotiate long-term power purchase agreements that lock in below-market electricity rates. These tenants command custom build-to-suit specifications including direct liquid cooling manifolds and 99.999 percent availability architectures.
- Enterprises:Fortune 500 corporations with legacy mainframe workloads and compliance-sensitive data residency requirements. Financial services firms in New York and Chicago maintain captive footprints for trading infrastructure, though many are migrating non-critical workloads to colocation.
- Internet Service Providers:Network operators requiring neutral interconnection points for traffic exchange.
- Telecommunication Companies:Carriers integrating edge compute with 5G core network functions.
Cloud Service Providers dominate megawatt-scale commitments; Enterprise demand is gaining share fastest as hybrid strategies mature.
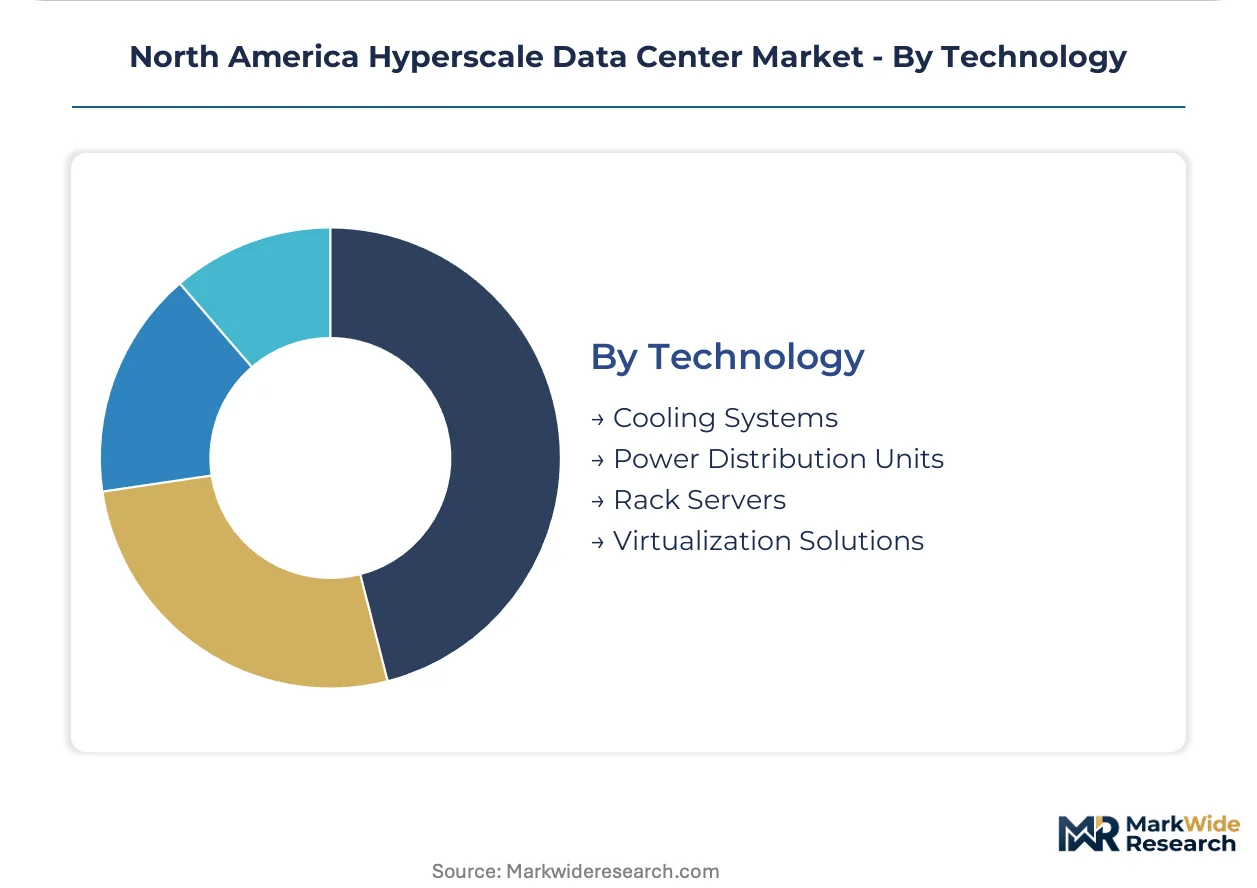
Technology:
Technology layers stratify by thermal density ceiling and integration complexity, with cooling systems commanding disproportionate capital allocation.
- Cooling Systems:Direct liquid cooling manifolds, rear-door heat exchangers, and evaporative cooling towers now represent 25-35 percent of facility capital expenditure. ASHRAE thermal guideline compliance and EPA Energy Star certification requirements are extending equipment procurement cycles by 6-8 weeks.
- Power Distribution Units:Medium-voltage switchgear, UPS systems, and rack-level PDUs with real-time metering. Transformer and switchgear lead times from Asian suppliers now extend 18-24 months, making electrical infrastructure the critical path for facility commissioning.
- Rack Servers:High-density compute enclosures with integrated network and storage fabric.
- Virtualization Solutions:Software-defined compute, storage, and networking orchestration platforms.
Cooling Systems attract the steepest capital intensity; Virtualization Solutions are expanding most quickly as software-defined infrastructure displaces hardware-centric architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale capacity concentrates in three national markets where power availability, fiber density, and policy incentives align. Each jurisdiction presents distinct regulatory frameworks and infrastructure constraints that shape facility economics.
United States
Virginia's Data Center Alley in Loudoun County hosts the densest concentration of critical IT load on the continent. FERC interconnection queue reforms in PJM and ERCOT territories are compressing grid access timelines for multi-hundred-megawatt facilities. Northern Virginia operators navigate state renewable portfolio standards mandating carbon-free generation matching through long-term power purchase agreements.
Canada
Quebec and Ontario provinces attract compute-intensive workloads through below-market hydroelectric rates and temperate climates reducing cooling energy. The country's national energy regulator and provincial utilities administer streamlined interconnection processes for facilities exceeding 50 megawatts. Greater Toronto and Montreal metro areas concentrate investment where cross-border fiber routes meet municipal property tax abatements.
Mexico
Northern border states Chihuahua and Nuevo León leverage competitive industrial electricity rates and proximity to Texas fiber corridors. The Secretariat of Energy oversees wholesale market reforms enabling direct renewable procurement by large consumers. Querétaro and Mexico City metros emerge as secondary nodes for latency-sensitive financial services workloads.
North America Hyperscale Data Center Market Competitive Landscape
Capacity expansion dominates the current landscape as cloud service providers race to commission facilities before transformer lead times extend further. The competitive structure concentrates around vertically integrated hyperscale operators and wholesale colocation specialists serving as landlord-developers. Three archetypes define the field: captive cloud infrastructure divisions, independent data center REITs, and carrier-neutral interconnection platforms. M&A activity and renewable energy procurement partnerships represent the primary competitive vectors reshaping positioning.
Among integrated cloud infrastructure operators, Microsoft and Amazon Web Services anchor the scale-driven tier through captive facility development and direct utility negotiations. Equinix occupies a position exemplifying the carrier-neutral interconnection archetype, while Digital Realty represents wholesale colocation specialists building powered shell capacity for tenant customization. These three entities illustrate how vertical scope, geographic footprint, and customer segment focus stratify competitive advantage across the North American footprint.
| Leading Market Players |
|---|
| Microsoft |
| Meta Platforms |
| Equinix |
| American Tower |
| Oracle |
| Digital Realty |
| Google Cloud |
| CyrusOne |
| Amazon Web Services |
| Others |
Value Network & Pricing Analysis
Copper and aluminum price indices on the London Metal Exchange cascade through electrical infrastructure procurement, stratifying facility construction costs across premium-certified, standard-compliant, and economy-tier deployments. Cloud service providers with captive power purchase agreements capture below-market electricity rates unavailable to wholesale colocation tenants, while transformer and switchgear lead times from Asian suppliers compress EPC contractor margins and extend commissioning timelines.
Pricing Analysis
Volume commitments versus margin capture splits the competitive landscape. Wholesale colocation operators negotiate long-term leases with cloud service providers at compressed rates, sacrificing margin for occupancy certainty. Price differentiation hinges on EPA Energy Star certification status and ASHRAE thermal guideline compliance tier. Pricing pressure intensifies in secondary markets where land scarcity and power constraints limit greenfield competition. Enterprise tenants in regulated sectors exhibit highest price sensitivity; hyperscale cloud providers with direct utility negotiations demonstrate lowest sensitivity.
Supply Chain Analysis
Reverse logistics flows for decommissioned server hardware and liquid cooling components remain underdeveloped, constraining circular economy participation. Supply concentration centers on Taiwan and South Korea for advanced semiconductors, China for rare earth magnets and power electronics, and domestic U.S. fabrication for medium-voltage switchgear. Raw material dependencies span copper busbar, aluminum extrusion, and specialized coolant fluids. Single-source vulnerability in transformer manufacturing from Asian suppliers poses structural risk. Distribution runs through direct OEM relationships for hyperscale self-builds and tier-one EPC contractors for wholesale colocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America hyperscale data center market operates as a vertical-integration race where control over power procurement and cooling hardware determines cost position. Players are pursuing upstream integration into renewable generation assets and captive silicon design to escape commodity infrastructure pricing.
For Market Incumbents: Deploy long-term power purchase agreement pipelines to lock in below-market electricity rates before interconnection queue reforms saturate prime renewable sites. Consolidate liquid cooling hardware supply through backward integration or exclusive manufacturing partnerships. Threat substitution from edge computing architectures and modular facility designs demands defensive positioning in latency-sensitive secondary metros. For New Entrants and Emerging Players: Mid-market enterprises with hybrid workload requirements represent the most underserved buyer archetype for specialized colocation with compliance-grade security certifications. Mexico border states offer penetrable geography with competitive industrial electricity rates and cross-border fiber density. Target district heating partnerships with municipal utilities as a differentiated sustainability narrative for ESG-mandated enterprise procurement. For Investors and Strategic Acquirers: The window for entry favors wholesale colocation platforms with secured land positions in PJM and ERCOT territories. Long-term viability rests on grid interconnection timelines and renewable energy matching capabilities. Acquisition target archetype: regional operators with permitted but unbuilt capacity in power-constrained primary markets. Signal to monitor: FERC interconnection queue reform implementation pace as inflection indicator for energization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Power Purchase Agreement | Locks in below-market electricity rates through direct renewable developer contracts in PJM and ERCOT territories. |
| Liquid Cooling Infrastructure Deployment | Enables rack densities above 100 kilowatts for AI training clusters previously constrained by air-cooled thermal limits. |
| Cross-border Geographic Expansion | Captures competitive industrial electricity rates in Chihuahua and Nuevo León with Texas fiber corridor proximity. |
| Waste Heat Recovery Partnership | Converts rejected thermal energy into revenue streams through municipal utility district heating agreements. |
| EPA Energy Star Certification Program | Unlocks utility incentive eligibility for documented power usage effectiveness below 1.2 baseline. |
Research Methodology
SEC filings from hyperscale cloud providers, FERC interconnection queue databases, and EIA electricity market data formed the secondary backbone for this analysis. Primary interviews with data center development executives, utility planning officers, EPC contractors, and renewable energy developers validated capacity expansion timelines and procurement patterns. Bottom-up facility-level capacity tracking and top-down cloud capex aggregation enabled cross-verification of market size estimates.
Historical trendline analysis of hyperscale facility commissioning timelines and power density evolution informed projection frameworks across the analysis window. Segmentation modeling incorporated service model, deployment architecture, end-user concentration, and thermal technology layers. CAGRs derived from fitted growth curves applied to facility pipeline data and cloud provider infrastructure disclosure patterns. Forecast inputs included transformer lead time trajectories, state renewable portfolio standard compliance deadlines, and liquid cooling adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FERC interconnection reform implementation, copper price volatility, and generative AI workload demand persistence. Forecasts reflect documented assumptions on grid access timelines and equipment procurement cycles. Practitioners should monitor transformer manufacturing capacity expansion and state-level water withdrawal regulation tightening for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Middle East Data Center Rack Market
Data Center Infrastructure
Indonesia Data Center Construction Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
Asia-Pacific Data Center Power Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
Global Mega Data Center Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
South Africa Data Center Construction Market
Data Center Infrastructure
France Data Center Power Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
New Zealand Data Center Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Thailand Data Center Physical Security Market
Data Center Infrastructure
Sweden Data Center Construction Market