
 Malaysia Data Center Storage Market | 2026-2036
Malaysia Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Data Center Storage Market Insights
Malaysia is rewriting Southeast Asia's data center storage map with aggressive capacity additions across Johor and Selangor. Dell Technologies leverages its integrated server-storage portfolio to anchor enterprise refresh cycles in Kuala Lumpur's financial district. Huawei Technologies competes through localized manufacturing and direct government engagement on sovereign cloud projects. Kingston Technology dominates the memory component layer, supplying both OEM channels and direct-to-datacenter modules for hyperscale builds.
Data center storage encompasses the systems, media, and software architectures designed to capture, retain, and retrieve digital information at enterprise scale, typically measured in petabyte-class throughput and sub-millisecond latency thresholds for mission-critical workloads. Solid state drives now lead performance tiers for financial trading and real-time analytics, while hard disk drives sustain bulk archival economics in government and telecom backup environments. Software-defined storage is displacing traditional SAN architectures fastest among cloud service providers, and object storage protocols are capturing unstructured data growth from healthcare imaging and video surveillance pipelines.
Malaysia's Personal Data Protection Act enforcement through the Personal Data Protection Commissioner shapes cross-border data handling requirements, while BIS-equivalent SIRIM certification and CyberSecurity Malaysia's audit frameworks govern product eligibility for government tenders. The Malaysian Communications and Multimedia Commission directs spectrum and facility licensing that indirectly constrains storage scaling timelines. Stakeholders must weigh sovereign data residency mandates against the capital efficiency of regional cloud consolidation when committing to multi-year infrastructure contracts.
Market Dynamics
Malaysia's data center storage market is being restructured by sovereign cloud mandates that require domestic data residency for financial and government workloads. These compliance requirements are compressing procurement cycles and favoring localized supply chains over regional cloud consolidation.
Growth Catalysts
- Cloud-First Policy Directives:Malaysia's national cloud-first mandates require government agencies to prioritize domestic cloud infrastructure, accelerating storage procurement for sovereign data environments.
- Financial Sector Digitalization:Banks and insurers in Kuala Lumpur and Penang are deploying petabyte-scale storage for real-time analytics and regulatory reporting.
- Hyperscale Facility Construction:Bridge Data Centres and YTL Data Center Holdings are expanding capacity across the Klang Valley corridor, creating concentrated demand for enterprise storage systems.
Market Restraints
- NAND Flash Price Volatility:Solid-state storage costs fluctuate with global memory chip supply cycles, compressing margin predictability for local system integrators.
- Certification Timeline Friction:CyberSecurity Malaysia's audit frameworks and SIRIM certification requirements extend product qualification periods by 6-12 months for foreign vendors.
- Regional Cloud Consolidation Pull:Singapore and Indonesia offer competing hyperscale capacity with established compliance frameworks, diverting some cross-border workload demand.
Strategic Opportunities
- Johor Corridor Expansion:Southern Malaysia's proximity to Singapore creates opportunities for disaster recovery and latency-sensitive storage deployments serving ASEAN financial networks.
- Healthcare Imaging Archive Growth:Public hospital digitization programs are generating unstructured data volumes that favor object storage architectures over traditional SAN systems.
- Green Data Center Incentives:Malaysia Investment Development Authority tax holidays for energy-efficient facilities are steering procurement toward flash-optimized, high-density storage designs.
Industry Challenges
- Specialized Engineering Talent Scarcity:Shortages of storage architects certified in software-defined and hyperconverged platforms delay enterprise deployment timelines.
- Legacy SAN Integration Complexity:Financial institutions maintaining mainframe-connected storage face friction migrating to cloud-native architectures without disrupting core banking operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Data Center Storage Market |
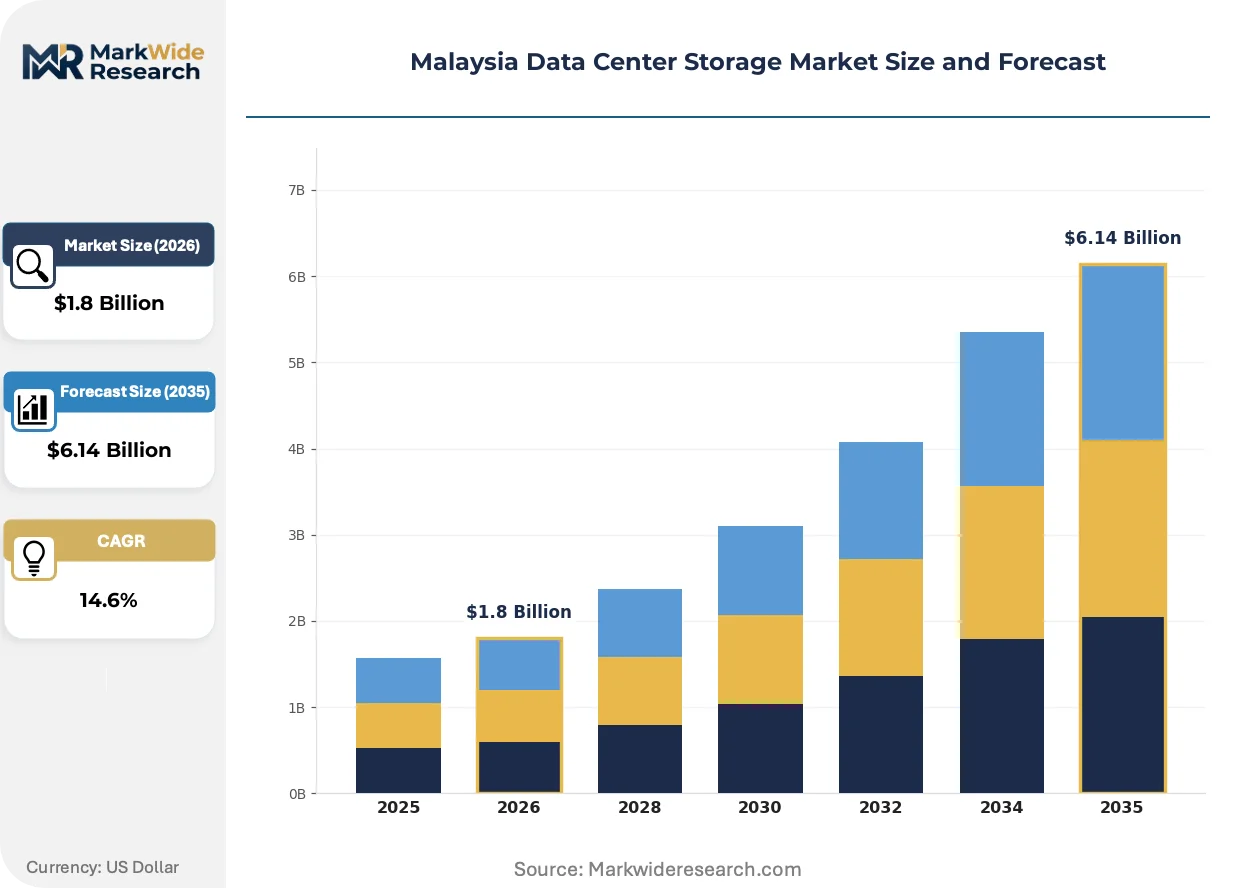
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Disk Drives, Solid State Drives, Tape Storage, Hybrid Storage Technology: Cloud Storage, Virtualized Storage, Object Storage, Software-Defined Storage End User: Telecom Providers, Government Agencies, Financial Institutions, Healthcare Organizations Deployment Model: On-Premises, Colocation, Managed Services, Hybrid Infrastructure |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp, Huawei Technologies, Kingston Technology, Bridge Data Centres, Keppel Data Centres, NTT, YTL Data Center Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Data Center Storage Market Trends and Innovations
Software-defined storage architectures are compressing the traditional hardware-software boundary in Malaysian data centers. These shifts are redistributing value capture from appliance vendors to platform-agnostic software suppliers.
NVMe-over-Fabrics is digitizing storage network performance by replacing SCSI-based protocols with direct memory-access connectivity. Financial trading firms in Kuala Lumpur are adopting these fabrics to achieve sub-100-microsecond latency for algorithmic transaction processing. This protocol shift is compressing the performance gap between local flash and networked storage, enabling rack-scale disaggregation of compute and storage resources.
Malaysia's Personal Data Protection Act enforcement through the Personal Data Protection Commissioner is tightening cross-border data transfer restrictions. Organizations must now demonstrate explicit consent mechanisms and data localization for sensitive personal information. Healthcare providers and digital banks are responding by deploying on-premise object storage with encryption-at-rest rather than regional cloud archives.
Consumption-based financing models are displacing traditional capital expenditure cycles for storage infrastructure. Managed service providers in Selangor are offering capacity-as-a-service contracts with committed utilization tiers. This shift is most visible among mid-market enterprises in Penang's manufacturing corridor, where CFOs prefer operational expenditure treatment for infrastructure scaling.
Malaysia Data Center Storage Market Segmentation
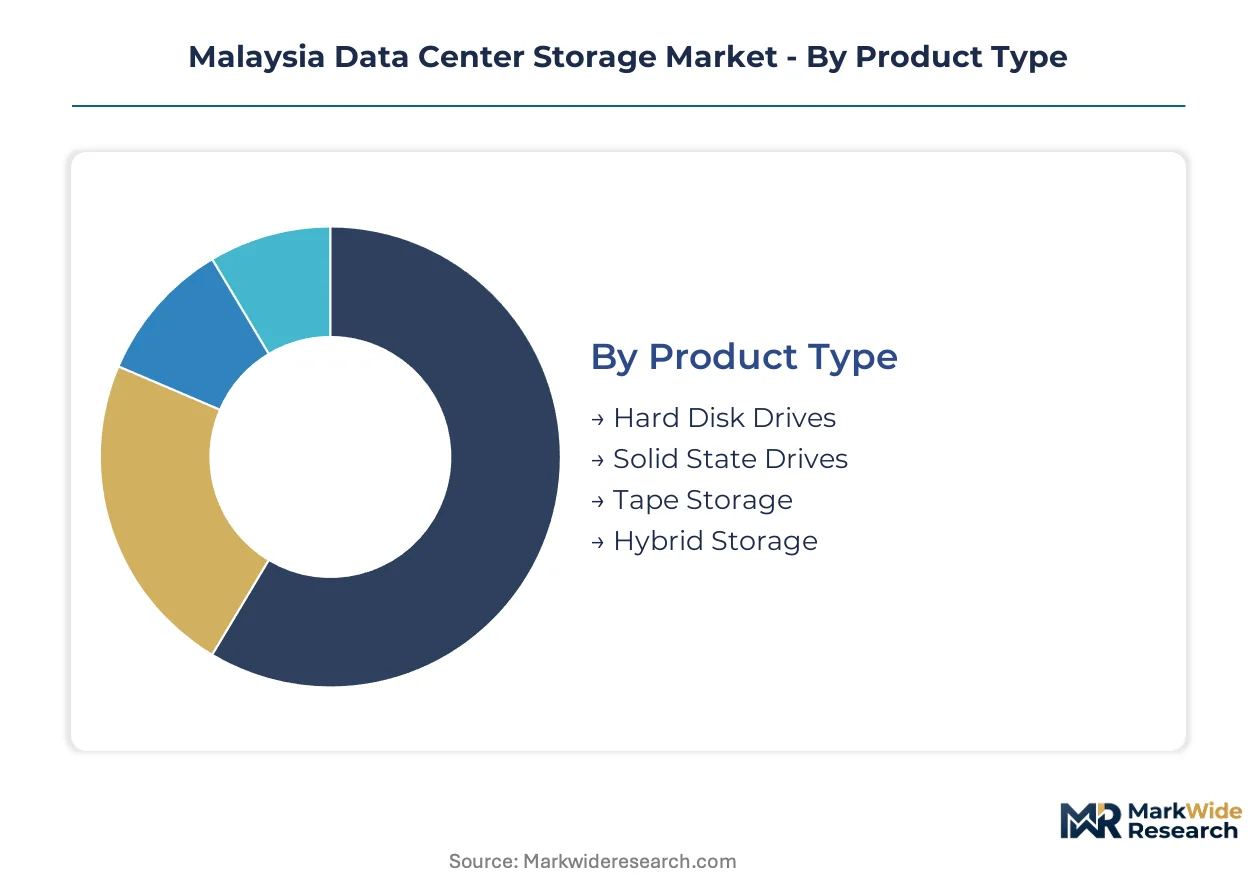
Malaysia's data center storage market fragments across four critical dimensions that shape procurement patterns and vendor positioning. Understanding these segment boundaries reveals where capital concentrates fastest and which technology transitions compress replacement cycles most aggressively.
Product Type:
Cycle times vary dramatically across storage media, with flash-based systems refreshing every 3-4 years while tape archives persist for 7-10 year horizons.
- Solid State Drives:NAND flash architectures deliver sub-millisecond latency for transactional workloads. Kuala Lumpur financial institutions prioritize NVMe-based arrays for algorithmic trading platforms, though NAND price volatility constrains procurement budgeting.
- Hard Disk Drives:Magnetic platter technology sustains bulk economics for sequential read operations. Government backup environments and telecom log retention in Penang favor high-capacity helium-filled drives for petabyte-scale cold storage.
- Tape Storage:Linear tape-open formats provide air-gapped archival for CyberSecurity Malaysia compliance mandates. Long media lifespans suit judicial record retention and healthcare imaging vaults.
- Hybrid Storage:Tiered architectures combine flash front-ends with disk back-ends. Mid-market enterprises in Selangor adopt these for balanced performance-cost profiles.
Hard Disk Drives anchors the volume base while Solid State Drives gains share at the steepest rate.
Technology:
Application intensity separates these architectures, with real-time analytics demanding fundamentally different data planes than compliance archiving.
- Software-Defined Storage:Decoupled control planes running on commodity hardware displace traditional SAN appliances. Cloud service providers in the Klang Valley corridor deploy Ceph and VMware vSAN for tenant-isolated capacity pools.
- Object Storage:Flat namespace architectures with RESTful APIs capture unstructured data growth. Healthcare providers digitizing radiology departments in Johor favor S3-compatible systems for DICOM image repositories.
- Cloud Storage:Hyperscale provider APIs abstract underlying infrastructure complexity. Financial institutions with sovereign data residency requirements balance on-premise object stores with certified domestic cloud tiers.
- Virtualized Storage:Hypervisor-integrated data services streamline VM provisioning. Managed service providers in Penang's manufacturing corridor leverage these for multi-tenant hosted environments.
Virtualized Storage dominates current installed capacity while Software-Defined Storage climbs the fastest.
End User:
Customer type determines procurement sophistication, with regulated industries demanding certified supply chains that informal sectors bypass.
- Financial Institutions:Banks and insurers face Bank Negara Malaysia guidelines on operational resilience and data localization. Real-time risk analytics and regulatory reporting drive petabyte-scale flash deployments.
- Government Agencies:Cloud-first policy directives mandate domestic infrastructure preference. National digitization programs generate sustained demand for encrypted, SIRIM-certified storage systems.
- Telecom Providers:Network operators manage subscriber data and lawful intercept archives. 5G rollout timelines in the Klang Valley accelerate edge storage scaling for low-latency services.
- Healthcare Organizations:Public hospital digitization and private diagnostic chains generate imaging workloads. Personal Data Protection Act compliance shapes on-premise deployment preferences over regional cloud consolidation.
Government Agencies anchor procurement volume while Healthcare Organizations expand most quickly.
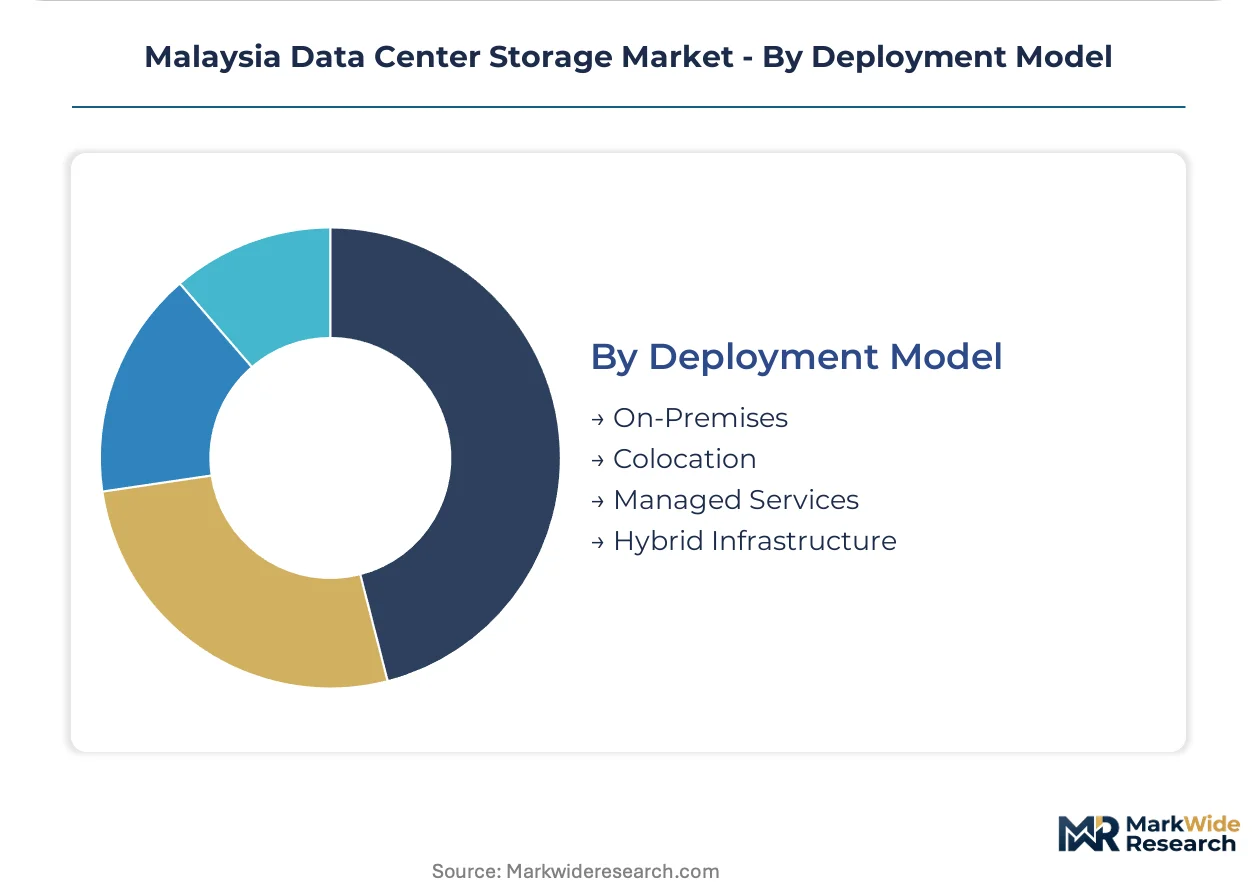
Deployment Model:
Margin structures diverge sharply here, with asset-light service models capturing value from capital-constrained mid-market buyers.
- Colocation:Third-party facility leasing with tenant-managed equipment. Bridge Data Centres and YTL Data Center Holdings expand Klang Valley capacity for enterprises seeking certified physical infrastructure without facility ownership.
- Hybrid Infrastructure:Orchestrated workloads spanning on-premise and off-premise resources. Financial institutions balance sovereign data requirements against burst capacity needs.
- On-Premises:Customer-owned and operated equipment in dedicated facilities. Large government datacenters and central bank operations maintain this model for maximum control.
- Managed Services:Capacity-as-a-service contracts with committed utilization tiers. Penang manufacturing CFOs favor operational expenditure treatment for infrastructure scaling.
On-Premises retains the largest installed base while Managed Services demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's data center storage consumption diverges from regional peers through sovereign cloud mandates that prioritize domestic data residency over cross-border cloud consolidation, creating procurement patterns distinct from Singapore's regional hub model or Indonesia's distributed archipelago approach.
Singapore
Financial institutions and multinational headquarters drive demand for ultra-low latency storage fabrics. The Monetary Authority of Singapore's Technology Risk Management Guidelines enforce stringent operational resilience standards. Marina Bay and Changi Business Park clusters concentrate hyperscale capacity serving ASEAN trading networks.
Indonesia
Digital banking expansion and e-commerce platforms generate petabyte-scale unstructured data growth. Bank Indonesia's payment system regulations mandate domestic transaction data localization. Jakarta-Bandung corridor and Surabaya emerging as primary data center clusters with government-backed digital infrastructure programs.
Thailand
Smart city initiatives and healthcare digitization accelerate object storage deployment for video surveillance and medical imaging archives. The National Cyber Security Agency's critical infrastructure protection framework governs data handling for government systems. Bangkok's Ratchada-Ladprao district and Eastern Economic Corridor attract facility investments.
Vietnam
Foreign direct investment in manufacturing and gaming sectors creates hybrid cloud storage demand balancing performance and cost. The Ministry of Information and Communications' cybersecurity law restricts cross-border personal data transfers. Ho Chi Minh City and Hanoi dominate facility concentration with emerging Da Nang secondary hub.
Philippines
Business process outsourcing and remittance platforms require high-availability storage for transactional workloads. The National Privacy Commission's data protection guidelines influence procurement decisions for personal data handling. Metro Manila's Makati and Taguig central business districts anchor existing capacity with provincial expansion underway.
Malaysia Data Center Storage Market Competitive Landscape
Capability concentration sits with integrated technology providers possessing sovereign cloud certifications; scale advantage sits with hyperscale facility operators expanding raw capacity across the Klang Valley corridor. The market structure reflects a bifurcated tiering where enterprise storage vendors compete on compliance integration while data center developers compete on power and connectivity access. Two strategic archetypes dominate: full-stack infrastructure providers bundling hardware, software, and services; and pure-play facility operators leasing certified space to tenant-managed equipment. Competitive moves center on CyberSecurity Malaysia certification acquisition and Johor corridor land banking for Singapore-proximate disaster recovery capacity.
Within the full-stack infrastructure tier, Dell Technologies and Hewlett Packard Enterprise occupy positions as enterprise refresh cycle anchors in Kuala Lumpur's financial district, exemplifying vendors with integrated server-storage portfolios. Huawei Technologies represents the localized manufacturing archetype through direct government engagement on sovereign cloud projects. Kingston Technology sits within the component supply tier, supplying memory modules across both OEM channels and direct hyperscale builds. These three companies illustrate the market's tripartite segmentation between systems vendors, component suppliers, and facility operators.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| Huawei Technologies |
| Kingston Technology |
| Bridge Data Centres |
| Keppel Data Centres |
| NTT |
| YTL Data Center Holdings |
| Others |
Pricing and Supply Chain Analysis
Hyperscale facility overcapacity in the Klang Valley corridor compresses storage system pricing power while concentrating procurement leverage among Bridge Data Centres and YTL Data Center Holdings. This utilization dynamic forces component suppliers to absorb NAND flash volatility through long-term contract structures rather than spot-market exposure.
Pricing Analysis
Long-term offtake agreements dominate enterprise storage procurement, with Kuala Lumpur financial institutions locking three-to-four-year flash array commitments to hedge against memory chip cyclicality. Pricing stratifies across CyberSecurity Malaysia-certified tiers, SIRIM-validated configurations, and uncertified commercial offerings, with sovereign cloud mandates widening the premium gap. Cost compression in mid-market hybrid tiers intensifies because Kingston Technology and Huawei Technologies compete aggressively on localized manufacturing claims. Government agencies show least price sensitivity due to compliance-driven sole-source eligibility, while Penang manufacturing CFOs demand consumption-based financing to shift capex to opex treatment.
Supply Chain Analysis
Upstream NAND wafer fabrication feeds from South Korea, Taiwan, and Japan, with memory module assembly concentrating in Penang and Shenzhen facilities. Controller silicon, PCB substrates, and power management components draw from U.S., Chinese, and Malaysian supplier networks. Single-source vulnerability sits with advanced NAND process nodes where Samsung and SK Hynix dominate 176-layer and below production. Distribution runs through Dell Technologies and Hewlett Packard Enterprise direct sales forces for enterprise accounts, while Kingston Technology serves hyperscale builds through direct datacenter fulfillment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's data center storage market represents a high-growth disruption as sovereign cloud mandates and NVMe-over-Fabrics protocol shifts simultaneously restructure procurement patterns and performance requirements.
For Market Incumbents: Insulate flash array margins by deepening backward integration into controller firmware development and securing CyberSecurity Malaysia pre-certification for next-generation platforms. Capacity addition in Johor corridor land banks creates defensive positioning against Singapore-proximate disaster recovery demand leakage. Threat substitution from software-defined storage disaggregating hardware-software value capture demands accelerated Ceph and VMware vSAN partnership investments. For New Entrants and Emerging Players: Pursue healthcare imaging archive white space in Johor public hospital digitization programs where object storage expertise gaps persist among incumbent SAN vendors. Consumption-based financing penetration among Penang manufacturing mid-market enterprises offers the most penetrable entry vector. Go-to-market execution should anchor on managed service provider channel partnerships rather than direct enterprise sales force builds. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service providers offering capacity-as-a-service with committed utilization tiers, suggesting durable cash flow quality in this archetype. Long-term viability across the analysis window favors facility operators with Johor corridor land positions and SIRIM certification track records. Signal to monitor: Bridge Data Centres and YTL Data Center Holdings hyperscale construction timelines as leading indicators of storage system procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CyberSecurity Malaysia Certification Acquisition | SIRIM validation unlocks government tender eligibility and sovereign cloud project participation. |
| NVMe-over-Fabrics Platform Launch | Sub-100-microsecond latency positioning captures Kuala Lumpur algorithmic trading storage refresh cycles. |
| Johor Corridor Land Banking | Singapore-proximate disaster recovery capacity addresses ASEAN financial network latency requirements. |
| Consumption-Based Financing Model | Operational expenditure treatment aligns with Penang manufacturing CFO infrastructure scaling preferences. |
| Object Storage Healthcare Partnership | DICOM-compatible S3 architectures capture public hospital digitization program unstructured data growth. |
Research Methodology
Desk research of hyperscaler capex disclosures, CyberSecurity Malaysia certification registries, and Malaysian Communications and Multimedia Commission facility licensing records preceded structured interviews with datacenter infrastructure planners, storage procurement officers at Kuala Lumpur financial institutions, and system integrators serving government digitization programs. Primary fieldwork with Bridge Data Centres and YTL Data Center Holdings development teams validated capacity expansion timelines. Secondary sources included Dell Technologies and Hewlett Packard Enterprise SEC filings, Kingston Technology product qualification databases, and regional cloud provider infrastructure announcements. Bottom-up storage system shipment estimates triangulated against top-down facility power allocation projections.
Assumption sets held sovereign cloud policy continuity and NAND flash supply cyclicality within historical bands while varying hyperscale facility construction completion rates and healthcare digitization program funding levels. Segmentation modeling spanned product type, technology architecture, end-user vertical, and deployment model dimensions across the projection horizon. CAGRs derived from unit economics analysis of flash versus disk storage refresh cycles, weighted by Klang Valley corridor capacity concentration. Industry-specific inputs included Bank Negara Malaysia operational resilience guideline implementation timelines and Personal Data Protection Commissioner enforcement patterns.
Sensitivities concentrate around NAND flash price volatility amplitude, CyberSecurity Malaysia audit timeline extensions, and regional cloud consolidation pull from Singapore and Indonesia. Forecasts embed assumptions regarding sovereign data residency mandate durability and green data center incentive program continuity. Cross-checking against Malaysian Investment Development Authority tax holiday utilization rates and SIRIM certification issuance volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
UAE Data Center Server Market
Data Center Infrastructure
Chile Data Center Server Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
China Data Center Physical Security Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
North America Containerized Data Center Market
Data Center Infrastructure
Middle East Data Center Power Market
Data Center Infrastructure
Data Center Equipment Market
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
Asia-Pacific Virtual Desktop Infrastructure Market
Data Center Infrastructure
United States Data Center Server Market
Data Center Infrastructure
New Zealand Data Center Physical Security Market
Data Center Infrastructure
Smart Data Center Market
Data Center Infrastructure
Spain Data Center Power Market