
 Brazil Container Glass Market | 2026-2036
Brazil Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Container Glass Market Insights
Recycled cullet processing revenue is tilting toward premium-grade furnace-ready material as Brazilian bottlers face energy cost pressures. Owens-Illinois do Brasil Indústria e Comércio Ltda leverages its Guarulhos furnace complex to anchor supply for domestic beer exporters. Verallia Brasil S.A. competes through specialized wine bottle formats for Rio Grande do Sul's expanding vineyard sector. SGD Brasil Vidros Ltda dominates pharmaceutical amber glass through ANVISA-certified mold capabilities.
Brazil container glass comprises silica-soda-lime formulations melted at 1,500°C and formed via blow-and-blow or press-and-blow processes, creating chemically inert vessels for liquid and semi-solid storage. Bottles sustain the largest volume position, though flacons command superior margins in pharmaceutical and cosmetics applications. The 1-5 liter capacity band leads beverage industry procurement, while custom design types capture value from premium spirits branding requirements. Eco-friendly design variants are gaining traction as AB InBev and Ambev advance returnable bottle commitments.
ANVISA governs pharmaceutical glass biocompatibility standards, while INMETRO administers mandatory conformity assessments for food-contact materials under Mercosur regulations. The national solid waste policy (Política Nacional de Resíduos Sólidos) mandates post-consumer glass recovery targets that reshape raw material sourcing economics. Stakeholders must monitor proposed updates to Brazil's carbon pricing framework, which would alter natural gas furnace economics relative to electric melting pilot investments.
Market Dynamics
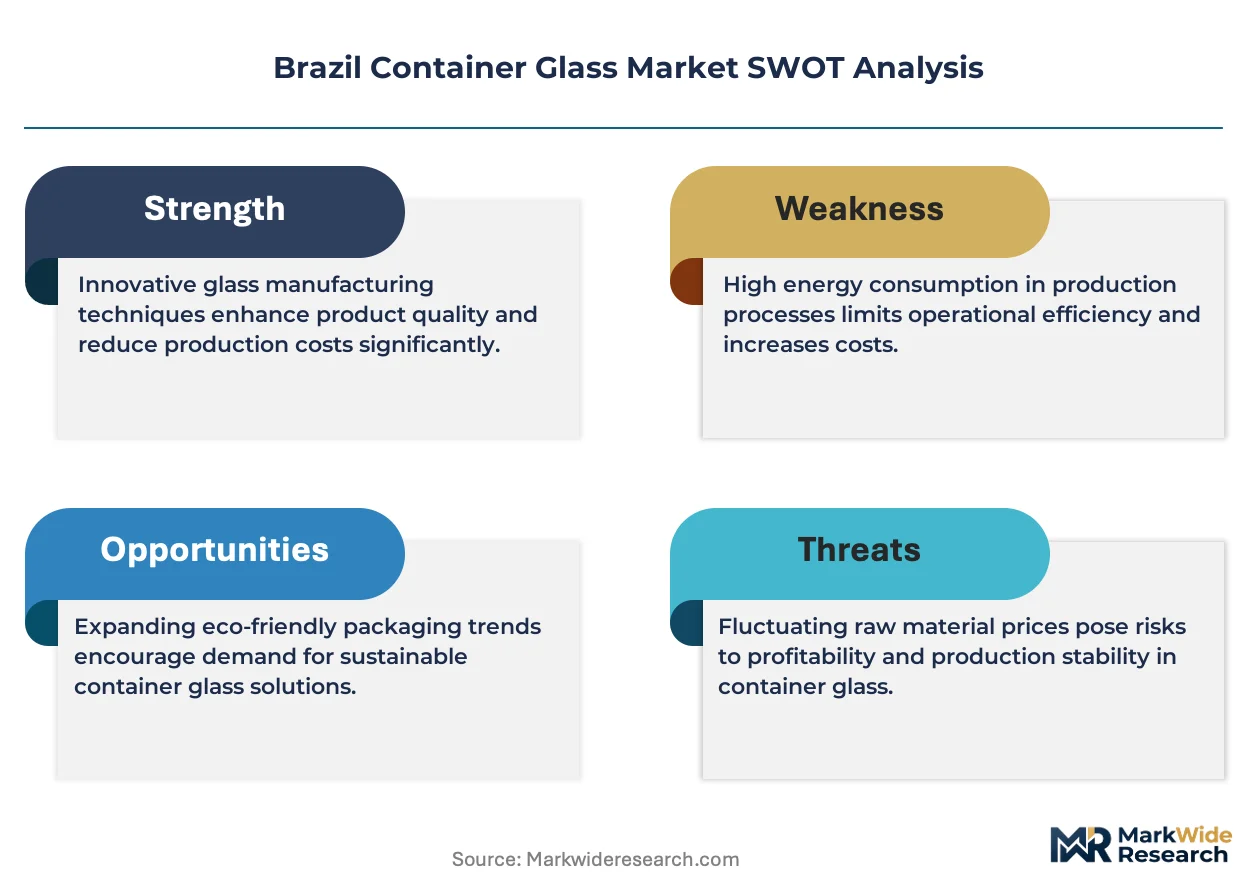
Energy-intensive furnace operations face mounting pressure from Brazil's evolving carbon pricing discussions, forcing producers to recalibrate natural gas dependence against electric melting pilot investments while navigating ANVISA's tightened pharmaceutical traceability mandates.
Growth Catalysts
- Returnable bottle commitments:AB InBev and Ambev have advanced closed-loop packaging programs that expand cullet recovery infrastructure and anchor demand for durable container formats.
- ANVISA pharmaceutical standards:Updated biocompatibility and traceability rules for amber glass packaging are displacing lower-grade alternatives in prescription drug distribution.
- São Paulo industrial corridor concentration:Food and beverage manufacturing clusters in this state dominate procurement volumes, creating localized economies of scale for furnace operators.
Market Restraints
- Natural gas price volatility:Furnace energy costs constitute the largest production expense, and feedstock price swings compress margin predictability for batch operations.
- High-purity silica sand supply concentration:Domestic extraction permits face environmental licensing delays, forcing reliance on limited qualified suppliers.
- Aluminum can substitution:Beverage packagers in mass-market beer segments are adopting metal alternatives for weight and logistics efficiency.
Strategic Opportunities
- Rio Grande do Sul vineyard expansion:Brazil's southern wine region is developing export-grade production that requires specialized bottle formats with premium decoration capabilities.
- Política Nacional de Resíduos Sólidos mandates:Post-consumer glass recovery targets are creating structured feedstock markets for furnace-ready cullet processing.
- Electric melting technology convergence:Hybrid furnace designs combining oxy-fuel and electric boosting are enabling carbon intensity reduction without full infrastructure replacement.
Industry Challenges
- ANVISA certification timeline compression:Pharmaceutical mold qualification periods are extending due to enhanced documentation requirements, delaying new product launches.
- Specialized furnace engineering talent scarcity:Brazil's technical education pipeline produces insufficient thermal process engineers for advanced glass melting operations.
- Legacy batch house integration complexity:Automated weighing and mixing system upgrades require extended downtime that conflicts with continuous production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Container Glass Market |
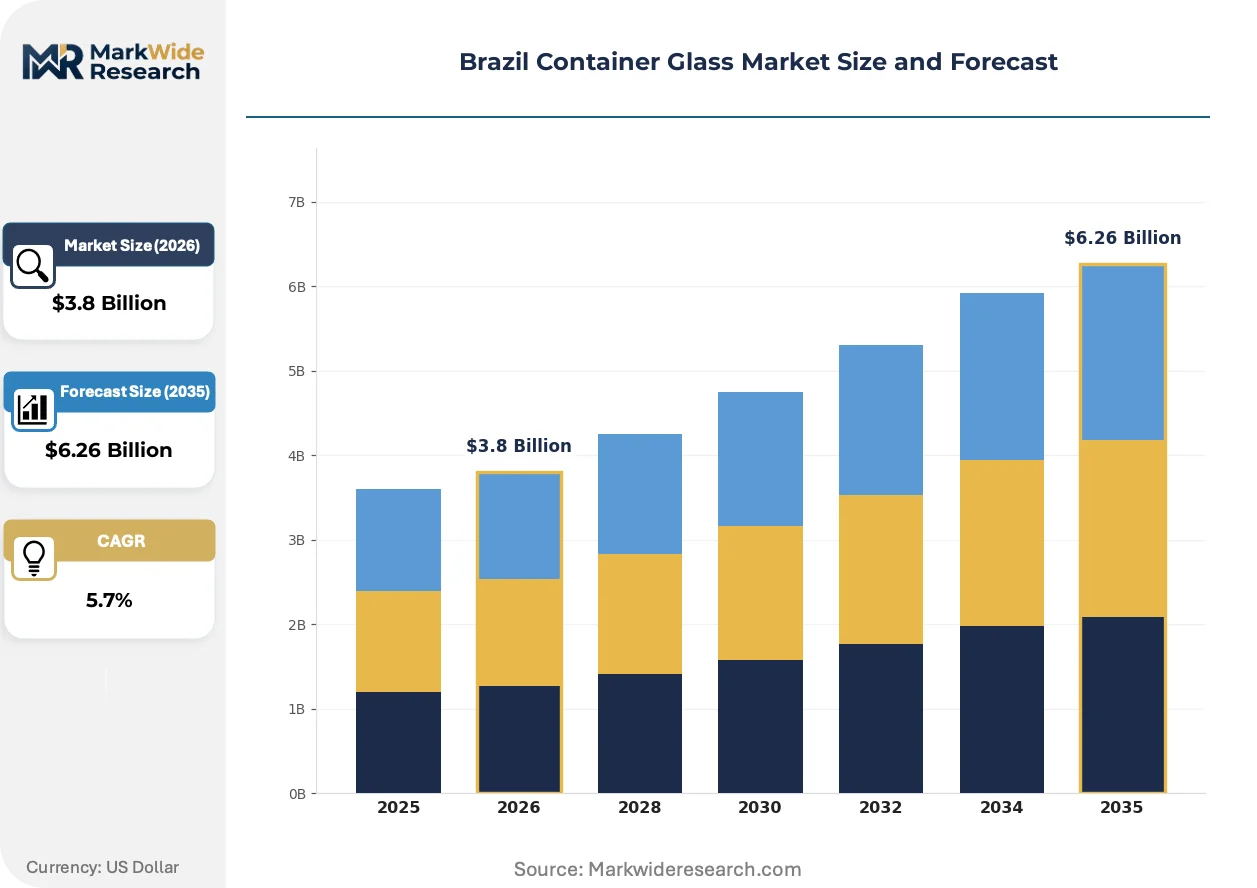
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Flacons End User: Food Industry, Beverage Industry, Pharmaceuticals, Cosmetics Capacity: Under 1 Liter, 1-5 Liters, 5-10 Liters, Above 10 Liters Design Type: Standard, Custom, Eco-friendly, Decorative |
| Companies Covered | SGD Brasil Vidros Ltda, Ardagh Group, Vidrala S.A., Gerresheimer AG, Wheaton Group, Owens-Illinois do Brasil Indústria e Comércio Ltda, Vitro do Brasil Ltda, Ambev, Verallia Brasil S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Container Glass Market Trends and Innovations
Digital process control systems are virtualizing quality assurance workflows across Brazilian container glass manufacturing, compressing inspection cycles while enabling real-time furnace optimization that was previously impractical at this production scale.
Digital twin technology for furnace thermal modeling is virtualizing traditional trial-and-error batch optimization. Owens-Illinois do Brasil and Verallia Brasil are deploying sensor arrays that feed predictive algorithms, reducing energy consumption per ton while maintaining viscosity targets. This virtualization is compressing the competitive advantage of legacy operators who rely on empirical operator expertise.
ANVISA's updated pharmaceutical packaging guidance is mandating enhanced mold traceability and surface chemistry documentation for amber glass containers. Manufacturers must now maintain batch records linking specific mold cavities to individual vial lots, increasing compliance overhead but creating differentiation for certified suppliers. SGD Brasil Vidros has responded by investing in laser-etched mold identification systems that satisfy audit requirements.
Craft brewery procurement patterns are fragmenting toward smaller order quantities with accelerated design cycles. Rio Grande do Sul and Minas Gerais microbreweries are bypassing traditional distributor channels to contract directly with mold shops for proprietary bottle shapes, compressing the traditional 12-week tooling timeline to six weeks through digital file transfer protocols. This behavior is most visible in the premium lager and barrel-aged stout segments where packaging differentiation commands shelf price premiums.
Brazil Container Glass Market Segmentation
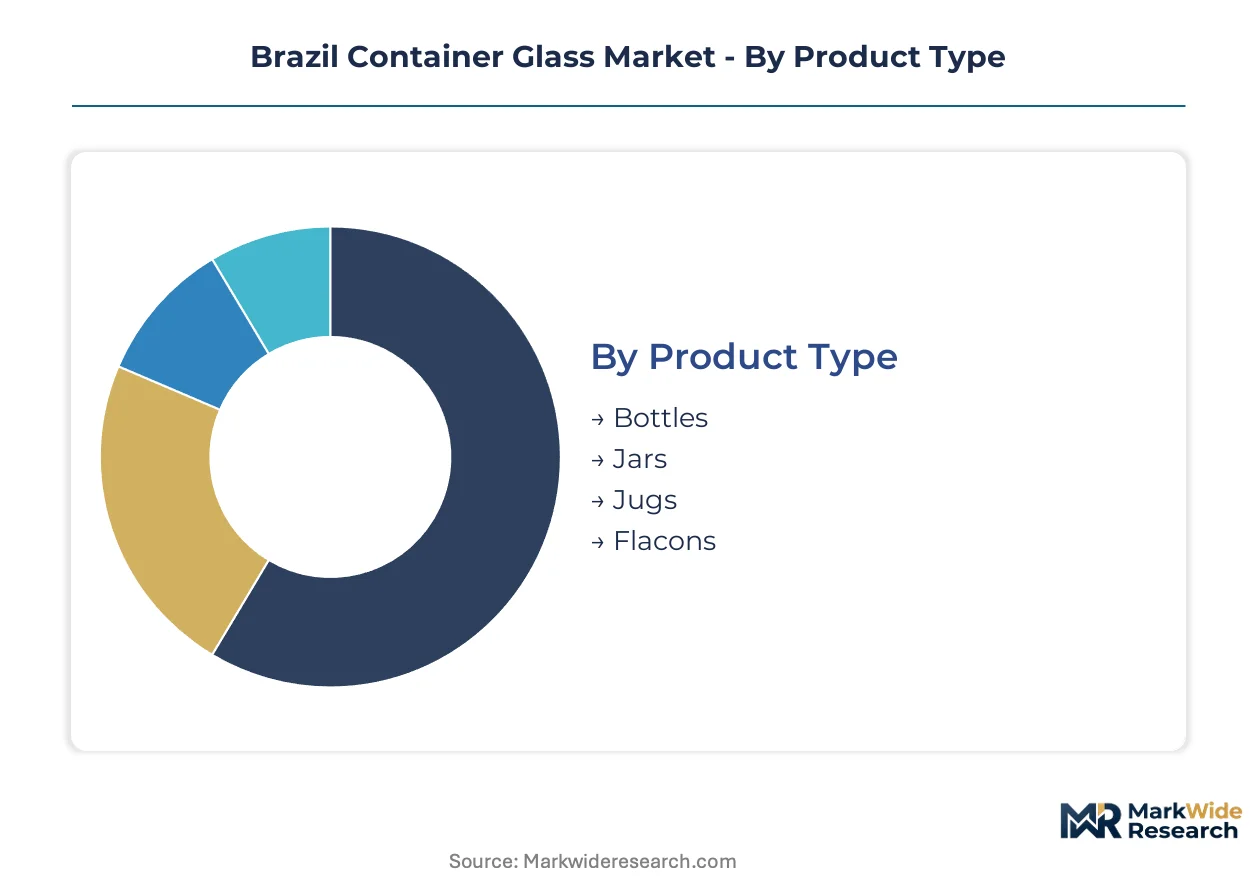
Segmentation in Brazil's container glass market reveals how furnace operators align production configurations with divergent service requirements across beverage, pharmaceutical, and cosmetics buyers. Each segment demands distinct mold capabilities, quality certification levels, and technical support intensity that reshape commercial relationships.
Product Type:
After-sales service intensity varies sharply across product types, with pharmaceutical flacons requiring mold cavity traceability and batch documentation that beverage bottles rarely demand.
- Bottles:Silica-soda-lime vessels formed via blow-and-blow or press-and-blow processes dominate procurement volumes across São Paulo's beverage manufacturing corridor. AB InBev and Ambev anchor demand for returnable formats that sustain cullet recovery infrastructure investments.
- Jars:Wide-mouth containers with threaded finishes serve food preservation applications where thermal shock resistance and hermetic sealing performance determine supplier selection. Domestic condiment and preserve manufacturers in Minas Gerais concentrate procurement.
- Jugs:Large-format vessels with reinforced handles target bulk liquid distribution for food service and institutional buyers. Lower decoration requirements compress margin profiles relative to premium beverage formats.
- Flacons:Amber and clear glass vials for pharmaceutical and cosmetics applications command superior margins through ANVISA-certified mold capabilities and surface chemistry documentation.
By volume, bottles lead. By growth pace, flacons are expanding most quickly.
End User:
Application-specific compliance burdens segment the market, with pharmaceutical and food-contact materials facing mandatory INMETRO conformity assessments that cosmetics buyers avoid.
- Food Industry:Preserves, sauces, and condiments drive demand for thermal shock-resistant containers with vacuum-sealing compatibility. São Paulo state processors dominate procurement volumes.
- Beverage Industry:Beer, spirits, wine, and soft drink bottlers generate the largest revenue concentration, with craft breweries in Rio Grande do Sul and Minas Gerais fragmenting order patterns toward custom formats.
- Pharmaceuticals:ANVISA biocompatibility standards mandate amber glass for photosensitive compounds, with mold traceability requirements extending qualification timelines and compliance overhead.
- Cosmetics:Premium fragrance and skincare brands demand decorative finishing capabilities and precise dimensional tolerances for pump and dispenser compatibility.
Food and beverage industries anchor current volume. Pharmaceuticals demonstrate the steepest margin expansion trajectory.
Capacity:
Volume scale determines furnace campaign economics, with mid-range capacities achieving optimal batch efficiency while extreme formats require specialized handling equipment.
- Under 1 Liter:Single-serve beverage and pharmaceutical vials concentrate production in high-speed IS machine lines. Cosmetics flacons and premium spirits miniatures dominate value capture.
- 1-5 Liters:The standard beverage industry procurement band sustains continuous furnace operations through predictable demand from major brewers and soft drink bottlers.
- 5-10 Liters:Institutional and food service containers require reinforced structural designs and specialized palletization that extend logistics coordination.
- Above 10 Liters:Bulk chemical and industrial applications face limited domestic competition, with import dependence constraining availability.
The 1-5 liter band commands volume leadership. Under 1 liter formats gain share fastest through pharmaceutical and premium cosmetics demand.
Design Type:
Customization depth separates pricing tiers, with proprietary mold investments creating switching costs that standard formats cannot replicate.
- Standard:Catalog molds with minimal decoration serve cost-sensitive beverage and food segments where rapid turnaround and low minimum order quantities determine supplier relationships.
- Custom:Proprietary bottle shapes for craft spirits and wine exports require dedicated mold fabrication and compressed design cycles through digital file transfer protocols.
- Eco-friendly:Lightweighted designs and returnable formats advance AB InBev and Ambev closed-loop commitments while satisfying Política Nacional de Resíduos Sólidos recovery targets.
- Decorative:Premium finishing techniques including applied ceramic labeling and screen printing capture value from luxury spirits and cosmetics branding requirements.
Standard designs dominate shipment volume. Custom and eco-friendly variants together show the strongest momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Furnace operators concentrate capacity along Brazil's southeastern industrial corridor, where natural gas pipeline access and beverage manufacturing clusters create procurement density advantages unavailable elsewhere in the country.
São Paulo
AB InBev and Ambev bottling complexes anchor demand for returnable formats across the state's manufacturing belt. ANVISA pharmaceutical packaging standards drive amber glass qualification investments in Guarulhos. The industrial corridor linking São Paulo city to Campinas sustains continuous furnace campaigns through predictable procurement volumes.
Minas Gerais
Craft breweries in Belo Horizonte and surrounding municipalities fragment order patterns toward custom bottle designs with accelerated tooling cycles. Política Nacional de Resíduos Sólidos recovery targets reshape cullet collection infrastructure in the state's dairy and condiment processing zones. Juiz de Fora hosts specialized mold fabrication shops serving regional beverage startups.
Rio Grande do Sul
Vineyard expansion in the Serra Gaúcha wine region generates demand for specialized export-grade bottle formats. INMETRO conformity assessments for food-contact materials apply to expanding preserve and sauce manufacturing in Caxias do Sul. Porto Alegre distribution hubs coordinate logistics for premium spirits exporters targeting Mercosur markets.
Rio de Janeiro
Cosmetics and fragrance packaging demand concentrates in the state's northern petrochemical corridor. Pharmaceutical distribution networks serving the metropolitan region require ANVISA-certified amber glass inventory buffers. Duque de Caxias industrial parks host secondary decoration facilities for premium brand finishing.
Bahia
Cashew and tropical fruit processing drives jar demand for export-oriented food manufacturers. Cullet recovery infrastructure remains underdeveloped relative to southeastern states, creating feedstock supply gaps for potential furnace investments. Salvador port access offers logistics advantages for northeast Brazil distribution.
Brazil Container Glass Market Competitive Landscape
Multinational furnace operators and domestic specialists split the market between scale-driven beverage supply and certified pharmaceutical formats. Three archetypes dominate: integrated beverage packaging suppliers with captive cullet networks, pharmaceutical-grade specialists with ANVISA certification depth, and diversified European multinationals with technology transfer capabilities. Competitive moves center on furnace energy efficiency upgrades and mold fabrication partnerships with regional design shops.
Among Brazil-based limited companies, Owens-Illinois do Brasil Indústria e Comércio Ltda and SGD Brasil Vidros Ltda exemplify the integrated beverage and pharmaceutical archetypes respectively. Verallia Brasil S.A. occupies a position bridging premium wine formats with export logistics coordination. These three represent the dominant competitive anchors within a market where European parentage confers technology access and domestic registration enables regulatory responsiveness.
| Leading Market Players |
|---|
| SGD Brasil Vidros Ltda |
| Ardagh Group |
| Vidrala S.A. |
| Gerresheimer AG |
| Wheaton Group |
| Owens-Illinois do Brasil Indústria e Comércio Ltda |
| Vitro do Brasil Ltda |
| Ambev |
| Verallia Brasil S.A. |
| Others |
Pricing and Supply Chain Analysis
Natural gas price volatility determines both furnace operating cost spreads and the geographic concentration of batch-ready cullet networks across Brazil's southeastern industrial corridor. ANVISA pharmaceutical certification tiers and beverage returnable format durability requirements split pricing power between certified mold specialists and scale-driven beer bottler suppliers.
Pricing Analysis
ANVISA dictates the pricing tier structure across pharmaceutical amber glass, separating ANVISA-certified mold capabilities from uncertified commodity alternatives. Three-tier pricing stratifies across premium certified pharmaceutical formats, standard returnable beverage bottles, and economy single-use food jars. Cost compression in standard beverage tiers intensifies because aluminum can substitution pressures from AB InBev and Ambev procurement shifts. Pharmaceutical buyers demonstrate lowest price sensitivity due to regulatory compliance switching costs, while mass-market food processors anchor the most price-elastic demand segment.
Supply Chain Analysis
Furnace operators Owens-Illinois do Brasil, Verallia Brasil, and SGD Brasil Vidros anchor melting capacity within São Paulo state's natural gas pipeline corridor. High-purity silica sand draws from Minas Gerais extraction permits facing environmental licensing delays, while soda ash feeds from domestic chemical producers and import channels. Single-source vulnerability concentrates in qualified pharmaceutical mold fabrication where ANVISA documentation requirements extend qualification timelines. Distribution runs through São Paulo industrial corridor consolidation for beverage procurement, with Rio Grande do Sul vineyard logistics requiring specialized export-grade handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's container glass market sits at an electric melting technology inflection where carbon pricing discussions and ANVISA traceability mandates are simultaneously reshaping furnace economics and compliance overhead.
For Market Incumbents: Harden ANVISA-certified mold traceability systems against pharmaceutical qualification timeline extensions that threaten new product launch windows. Deepen backward integration into premium-grade cullet processing to capture Política Nacional de Resíduos Sólidos recovery infrastructure investments and defend margin position against natural gas cost volatility through electric melting pilot deployments. For New Entrants and Emerging Players: Pursue Rio Grande do Sul vineyard export-grade bottle formats where specialized decoration capabilities command premium positioning absent from mass-market beverage supply. Target Minas Gerais craft brewery direct contracting channels that fragment order patterns toward six-week digital tooling cycles, bypassing traditional distributor relationships through proprietary mold shop partnerships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors ANVISA-certified pharmaceutical specialists with captive electric melting technology pilots. Long-term viability centers on regulatory compliance moats widening against commodity beverage competitors. Monitor ANVISA carbon pricing framework proposals as the signal to watch for furnace economics inflection toward electric batch operations.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Melting Technology Pilot | ANVISA carbon pricing framework proposals would revalue natural gas furnace assets against hybrid electric alternatives. |
| ANVISA Mold Certification Investment | Laser-etched cavity traceability systems satisfy enhanced pharmaceutical documentation requirements and extend competitive moats. |
| Returnable Bottle Infrastructure Expansion | AB InBev and Ambev closed-loop commitments anchor cullet recovery economics for furnace-ready feedstock supply. |
| Rio Grande do Sul Vineyard Format Specialization | Export-grade wine bottle decoration capabilities capture premium positioning in Brazil's expanding southern vineyard sector. |
| Digital Twin Furnace Optimization | Sensor-fed predictive algorithms reduce energy consumption per ton while maintaining viscosity targets for competitive batch economics. |
Research Methodology
Operator-level perspectives from furnace managers, pharmaceutical packaging procurement leads, beverage bottler supply chain directors, and ANVISA regulatory affairs specialists anchored the qualitative base. Secondary validation drew from ANVISA regulatory filings, INMETRO conformity assessment databases, Política Nacional de Resíduos Sólidos implementation reports, and Brazilian chemical industry trade data. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed volume and value outputs across product type, end user industry, capacity band, and design customization depth dimensions. CAGRs derived from segment-level demand elasticity modeling and furnace capacity utilization trajectories. Industry-specific forecast inputs incorporated natural gas price scenario curves and ANVISA pharmaceutical packaging standard revision timelines.
Sensitivities concentrate around ANVISA carbon pricing framework adoption pace and silica sand environmental permit approval velocity. Forecasts reflect assumptions regarding electric melting technology cost convergence and craft brewery order fragmentation persistence. Quarterly review of ANVISA regulatory filing volumes and furnace energy cost indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Congo Container Glass Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
United Arab Emirates Glass Packaging Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
Nigeria Container Glass Market
Glass Packaging
Amber Glass Packaging Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Bangladesh Container Glass Market
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
Pharmaceutical Glass Packaging Market
Glass Packaging
Germany Glass Packaging Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
Poland Container Glass Market