
 France Container Glass Market | 2026-2036
France Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
France Container Glass Market Foresight
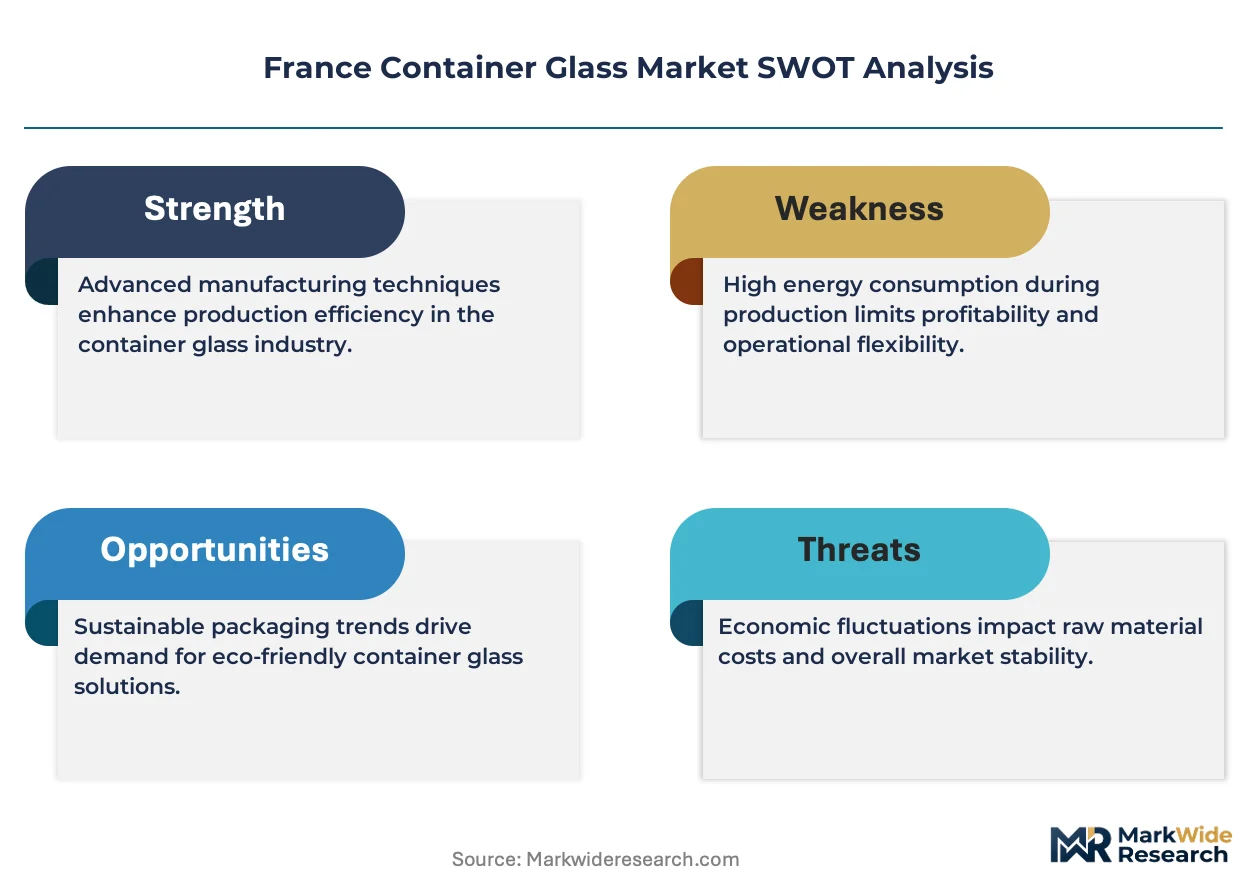
Buyer concentration among French beverage multinationals is shifting as craft breweries and regional wine cooperatives fragment procurement across smaller batch orders. Verallia Packaging dominates domestic supply through its extensive furnace network across Normandy and Lorraine. Saverglass differentiates through premium decoration capabilities serving Bordeaux and Burgundy estates. Ardagh Glass Packaging – Europe competes on lightweighting technology for export-bound champagne bottles.
Container glass comprises silica sand, soda ash, and limestone melted at approximately 1,500°C to form chemically inert, infinitely recyclable packaging for liquid and solid goods. The bottles segment anchors volume as wine and spirits producers mandate heavier wall thickness for premium positioning. Pharmaceutical vials sustain higher margin pools due to borosilicate durability requirements and GMP compliance costs. Cosmetic jars occupy a growing niche as French perfumers revive artisanal presentation formats.
France's national environmental agency enforces extended producer responsibility schemes mandating minimum recycled glass content, while ANSM inspects pharmaceutical packaging for extractables and leachables compliance. REACH chemical registration shapes raw material sourcing across European supply chains. Stakeholders must monitor furnace decarbonization timelines and EU carbon border adjustment mechanisms affecting imported cullet competitiveness.
Market Dynamics
France's extended producer responsibility framework is tightening recycled-content thresholds, forcing furnace operators to reconfigure cullet sourcing and melting protocols. This regulatory pressure intersects with Champagne-Ardenne cluster concentration and premium wine producers' lightweighting mandates to reshape competitive positioning.
Growth Catalysts
- EPR Recycled-Content Mandates:France's national environmental agency enforces escalating minimum cullet ratios, compelling furnace upgrades that lock in domestic supply contracts and reduce imported glass dependency.
- Champagne Export Demand:Appellation d'Origine Contrôlée bottling requirements sustain specialized heavy-wall production for prestige cuvée segments, insulating regional glassmakers from commodity pricing cycles.
- Lightweighting Chemistry Advances:Thin-wall bottle formulations using modified soda-lime compositions cut transport emissions while preserving pressure resistance for sparkling wine applications.
Market Restraints
- Natural Gas Cost Volatility:Furnace operations depend on natural gas feedstock for 1,500°C melting, exposing margins to European energy market fluctuations and carbon border adjustment exposure.
- Cullet Quality Inconsistency:Post-consumer glass collection yields variable contamination rates, complicating batch chemistry stability and increasing defect rates in pharmaceutical-grade output.
- Aluminum Can Substitution:Craft brewers and ready-to-drink spirits producers are migrating toward aluminum formats for single-serve portability, eroding mid-volume beer bottle demand.
Strategic Opportunities
- Pharmaceutical Borosilicate Expansion:ANSM inspection protocols for extractables and leachables compliance create barrier-to-entry dynamics that sustain premium pricing for GMP-certified vial production.
- Cosmetic Artisanal Revival:French perfumers are reviving hand-finished presentation formats, opening niche volume for decorative jar capabilities in Normandy and Burgundy supply zones.
- Electrification-Ready Furnace Retrofits:EU Green Deal funding streams support hybrid-electric melting trials, positioning early adopters for carbon-adjusted export competitiveness into Northern European markets.
Industry Challenges
- Batch Chemistry Expertise Shortage:Specialized furnace engineering and color-matching competencies are concentrating among retiring workforce cohorts, constraining operational flexibility for seasonal wine bottling surges.
- REACH Compliance Documentation:Raw material sourcing across European supply chains requires expanded chemical registration dossiers, extending qualification timelines for new supplier onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Container Glass Market |
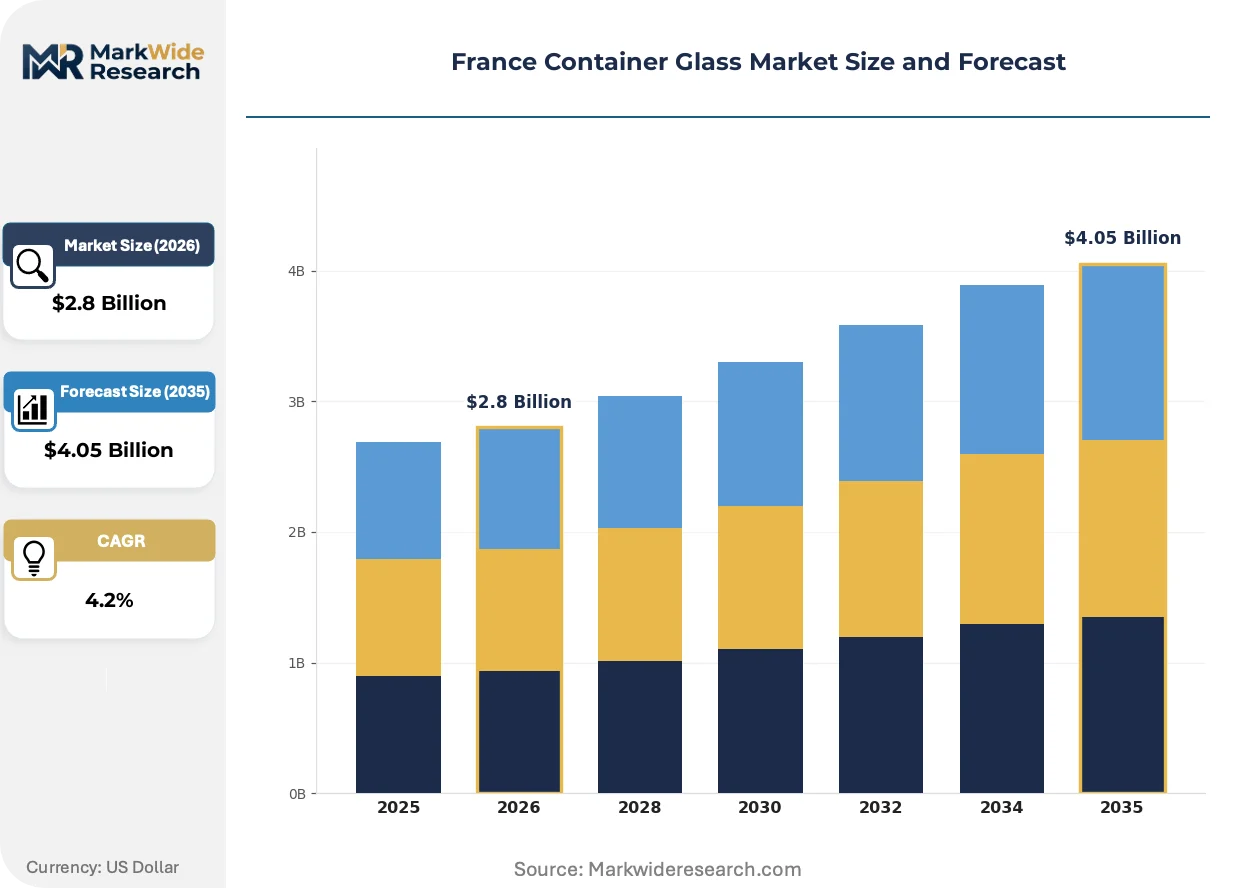
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.05 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Vials, Ampoules, Tubes Application: Beverages, Pharmaceuticals, Cosmetics, Food Packaging, Chemicals End User: Breweries, Pharmaceutical Manufacturers, Cosmetic Companies, Food Processing Plants, Chemical Suppliers Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers, Exporters |
| Companies Covered | Ardagh Glass Packaging – Europe, Gerresheimer AG, Verallia Packaging, Verescence SAS, SGD Pharma, O-I Glass, Inc., Stoelzle Glass Group, Saint-Gobain S.A., Saverglass, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Container Glass Market Shifts & Advancements
Digital furnace control systems and closed-loop cullet processing are converging to reshape production economics. These shifts intersect with regulatory carbon accounting and buyer sustainability auditing to redefine competitive differentiation.
Electrified hybrid melting technology is consolidating around oxy-fuel and plasma-augmented furnace designs that reduce Scope 1 emissions intensity. Champagne houses and Bordeaux négociants are specifying these bottles for export markets with carbon-labeled retail requirements. The technology is consolidating supply relationships toward furnace operators with capital reserves for multi-year retrofit cycles.
France's national environmental agency is extending producer responsibility schemes to cover packaging reuse targets beyond recycling rates. Industrial consequence includes mandatory deposit-return infrastructure investments and reverse logistics partnerships with retail chains. Wine cooperatives in Languedoc-Roussillon are most affected, responding through pooled procurement consortia to share compliance infrastructure costs.
Fragmented procurement patterns among craft breweries and regional wine cooperatives are compressing order batch sizes and shortening lead-time expectations. Traditional volume-based distributor relationships are yielding to direct furnace contracts for seasonal campaigns. This behavioral shift is most visible in the Loire Valley, where mid-size estates bypass wholesale channels for just-in-time bottling schedules aligned with harvest timing.
France Container Glass Market Segmentation
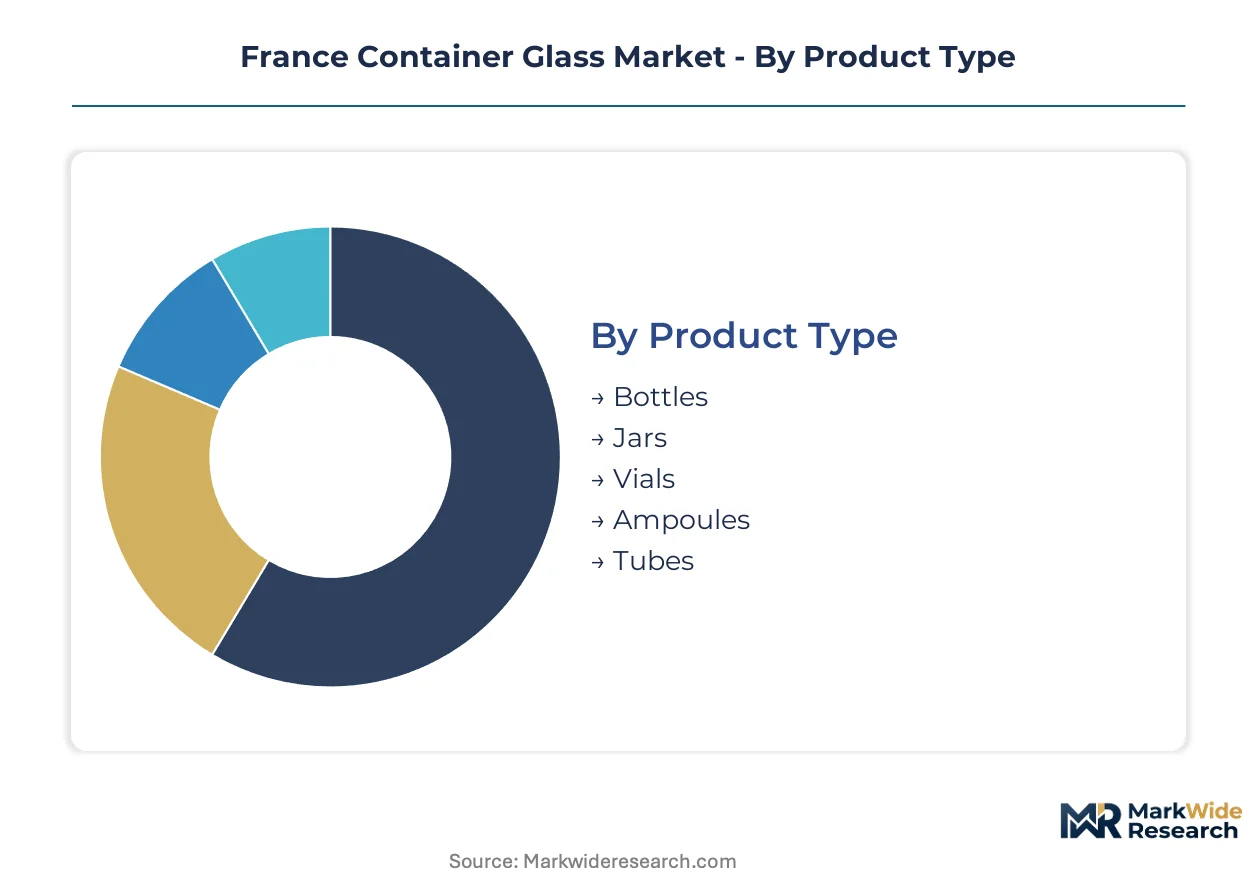
Segmentation in the France container glass market reveals how distinct buyer requirements reshape furnace scheduling, batch chemistry priorities, and distribution economics across the value chain. Each dimension exposes different margin pools and capital intensity profiles that suppliers must navigate.
Product Type:
Buyers differentiate primarily by wall thickness specifications and thermal durability requirements that dictate melting protocols and annealing cycles.
- Bottles:Standard soda-lime formulations with variable wall thickness serve wine and spirits producers demanding pressure resistance for sparkling applications. Champagne-Ardenne cluster furnaces dedicate capacity to heavy-wall prestige cuvée specifications that command premium positioning in export markets.
- Vials:Borosilicate compositions withstand thermal shock and chemical interaction required for injectable pharmaceuticals. ANSM extractables and leachables compliance mandates lock in GMP-certified production lines at higher margin tiers than commodity glass.
- Jars:Wide-mouth configurations accommodate solid and semi-solid cosmetics, with French perfumers specifying hand-finished presentation surfaces.
- Ampoules:Single-dose break-seal designs for parenteral drugs require precise neck concentricity and contamination-controlled forming environments.
- Tubes:Cylindrical formats for ointments and diagnostic reagents leverage continuous drawing processes distinct from blow-molding operations.
Bottles anchor volume throughput across Norman and Lorraine furnace networks; vials deliver the steepest margin expansion trajectory.
Application:
End-use sectors impose divergent regulatory burdens and quality certification thresholds that stratify supplier capabilities.
- Beverages:Wine and spirits producers dominate procurement with seasonal bottling surges concentrated around harvest windows. Lightweighting mandates from export-bound champagne houses are compressing traditional wall thickness specifications while preserving pressure ratings.
- Pharmaceuticals:Injectable and oral dosage forms require Type I borosilicate or Type III treated soda-lime compliance. ANSM inspection protocols and REACH raw material documentation create qualification barriers that sustain incumbent supplier relationships.
- Cosmetics:Artisanal perfumers in Grasse and Paris are reviving decorative jar formats with applied color labels and metallic closures.
- Food Packaging:Preserves and condiment containers prioritize hermetic seal integrity over aesthetic differentiation.
- Chemicals:Laboratory and industrial reagent bottles emphasize chemical inertness and UN-certified transport durability.
Beverages consume the largest furnace hours; pharmaceuticals expand most quickly on per-tonne value metrics.
End User:
Procurement scale and technical specification authority vary sharply across buyer categories, reshaping contract structures and inventory positioning.
- Breweries:Craft operators fragment orders into smaller batch sizes with compressed lead times, bypassing traditional distributor relationships for direct furnace contracts in the Loire Valley.
- Pharmaceutical Manufacturers:Multinational drug companies consolidate volume through multi-year supply agreements with embedded quality audit rights and regulatory change notification clauses.
- Cosmetic Companies:Niche perfumers and mass-market houses split between artisanal decoration requirements and high-speed filling line compatibility specifications.
- Food Processing Plants:Seasonal harvest processors prioritize just-in-time delivery windows aligned with agricultural production cycles.
- Chemical Suppliers:Industrial distributors stock standardized formats with less stringent color consistency requirements than beverage or pharmaceutical segments.
Breweries and pharmaceutical manufacturers represent opposing poles of procurement fragmentation versus consolidation.
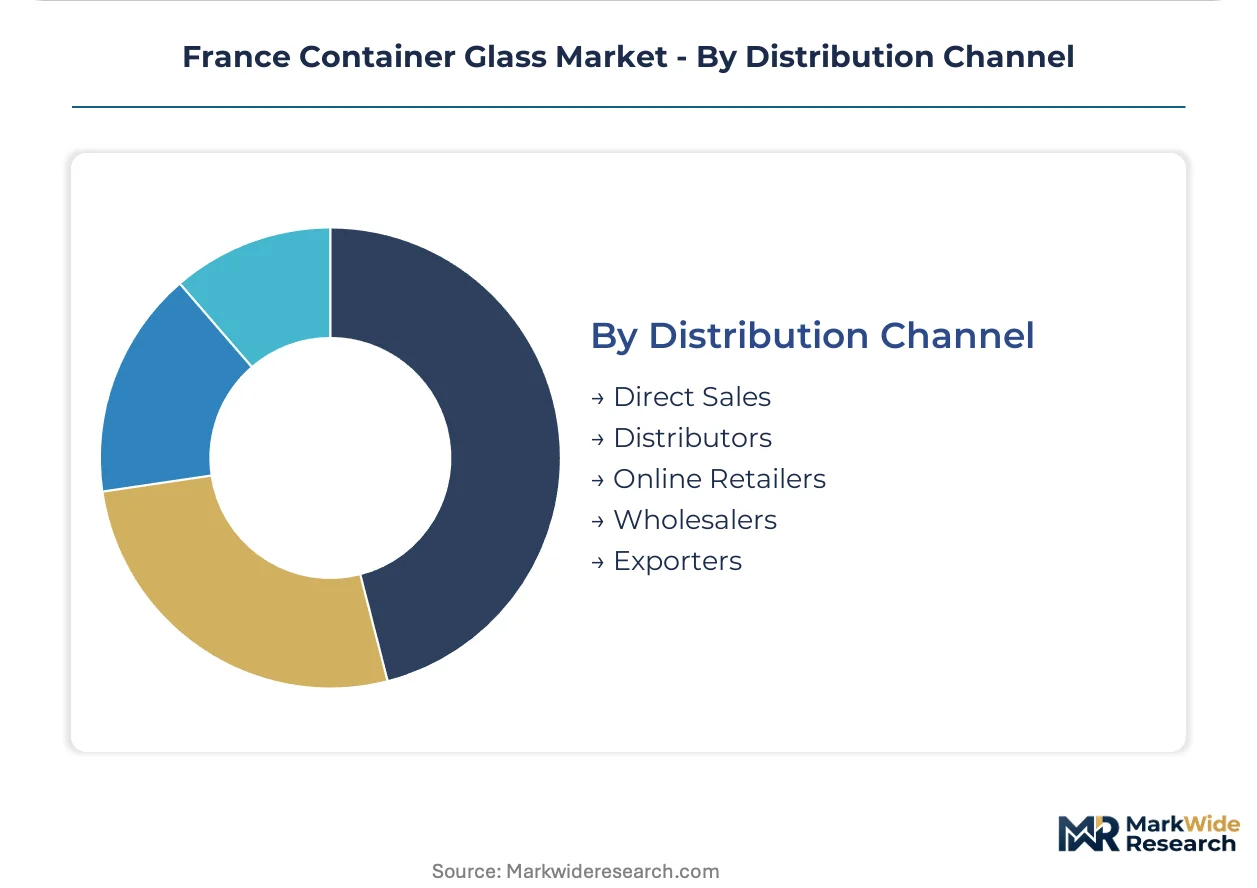
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and geographic proximity to furnace locations.
- Direct Sales:Large beverage multinationals and pharmaceutical companies negotiate furnace-direct contracts with embedded technical service and batch traceability documentation. Verallia Packaging and Saverglass maintain dedicated account teams for Bordeaux négociants and champagne houses.
- Distributors:Regional intermediaries aggregate smaller winery and craft brewery orders, managing seasonal inventory buffers and mixed-SKU pallet consolidation.
- Online Retailers:Emerging channels for specialty cosmetic jars and small-laboratory vials serve fragmented buyers with low minimum order quantities.
- Wholesalers:Traditional beverage supply houses retain relevance for mid-volume beer and still wine producers outside major appellation zones.
- Exporters:Specialized logistics providers manage customs documentation and carbon-border compliance for champagne and cognac shipments to Northern European markets.
Direct sales capture the highest-value contracts; distributor relationships are compressing as mid-size estates migrate to furnace-direct procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's container glass industry concentrates specialized furnace engineering talent across the Champagne-Ardenne corridor and Normandy-Lorraine furnace networks, anchoring European premium packaging supply.
Champagne-Ardenne
Prestige cuvée bottling for Appellation d'Origine Contrôlée champagne sustains heavy-wall production capacity unavailable elsewhere. ANSM inspection protocols for pharmaceutical-grade output intersect with wine industry seasonal demand. Reims-based glassmakers coordinate furnace scheduling between sparkling wine surges and borosilicate vial campaigns.
Normandy
Lightweighting chemistry advances for export-bound bottles drive modified soda-lime formulation trials. France's national environmental agency enforces escalating recycled-content thresholds through extended producer responsibility schemes. Verallia Packaging operates extensive furnace infrastructure across the region, locking in direct contracts with beverage multinationals.
Lorraine
Pharmaceutical borosilicate expansion capitalizes on GMP-certified production lines serving ANSM-regulated injectable markets. EU Green Deal funding streams support hybrid-electric melting retrofit trials. Nancy-Metz corridor facilities position for carbon-adjusted export competitiveness into Northern European markets.
Bordeaux-Aquitaine
Regional wine cooperatives fragment procurement into smaller batch orders with compressed lead times. Saverglass maintains premium decoration capabilities serving Bordeaux and Burgundy estates. Distributor relationships compress as mid-size estates migrate to furnace-direct procurement aligned with harvest timing.
Loire Valley
Craft breweries bypass traditional wholesale channels for direct furnace contracts with seasonal campaign scheduling. REACH chemical registration requirements extend raw material qualification timelines. Tours-Angers glassmaking facilities adapt to just-in-time bottling demands from mid-volume still wine producers.
France Container Glass Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across furnace scale tiers. The market structure consolidates around three operational archetypes: integrated packaging conglomerates with multi-furnace networks, premium decoration specialists serving luxury beverage estates, and pharmaceutical-grade certified producers. Dominant competitive moves include furnace electrification retrofits securing EU Green Deal funding and direct procurement relationship cultivation with fragmented craft brewery segments.
Among France-based packaging specialists, Verallia Packaging and Saverglass exemplify divergent strategic positioning within the same national market. Verallia occupies the integrated conglomerate tier with extensive Normandy-Lorraine furnace infrastructure. Saverglass represents the premium decoration specialist archetype anchored in Bordeaux supply zones. Ardagh Glass Packaging – Europe, with its Ireland-originated corporate structure, sits within the lightweighting technology tier competing for export-bound champagne bottle contracts. Gerresheimer AG and SGD Pharma represent pharmaceutical-certified specialists serving ANSM-regulated borosilicate demand.
| Leading Market Players |
|---|
| Ardagh Glass Packaging – Europe |
| Gerresheimer AG |
| Verallia Packaging |
| Verescence SAS |
| SGD Pharma |
| O-I Glass, Inc. |
| Stoelzle Glass Group |
| Saint-Gobain S.A. |
| Saverglass |
| Others |
Supply & Pricing Matrix
Lightweighting mandates from Champagne export houses are forcing furnace operators to reconfigure batch chemistry and annealing protocols, compressing margins on standard soda-lime formulations while creating premium capture opportunities for thin-wall specialists. This specification shift concentrates pricing power among operators with electrification-ready infrastructure and GMP-certified borosilicate lines.
Pricing Analysis
Capacity additions in Lorraine and Normandy are reshaping price floors for commodity bottles while preserving premium tiers for pharmaceutical-grade output. Contract structures stratify across premium decoration capabilities, ANSM certification levels, and volume scale commitments. Cost compression in mid-tier beverage glass is intensifying because natural gas feedstock volatility transfers directly into spot pricing. Craft breweries exhibit highest price sensitivity; champagne négociants prioritize specification compliance over unit economics.
Supply Chain Analysis
Specialized furnace engineering and color-matching competencies are concentrating among retiring cohorts in the Champagne-Ardenne corridor, constraining operational flexibility for seasonal surges. Silica sand sourcing draws from Belgian and German deposits; soda ash supply rests on Solvay's European production network. Single-source vulnerability sits with natural gas procurement through Gazprom-legacy contracts. Distribution runs through direct furnace contracts for large beverage multinationals and regional distributor aggregators for fragmented winery procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through electrification-driven cost reduction and pharmaceutical-grade tier migration. Premium capture concentrates among operators with hybrid furnace technology and ANSM-certified borosilicate capacity.
For Market Incumbents: Deepen backward integration into cullet processing infrastructure to lock in EPR compliance thresholds and reduce imported glass dependency. Prioritize furnace-direct relationship cultivation with Loire Valley craft breweries bypassing wholesale channels. Aluminum can substitution in ready-to-drink segments threatens mid-volume beer bottle demand; counter through lightweighting chemistry R&D partnerships with champagne houses. For New Entrants and Emerging Players: The premium-to-economy price gap in cosmetic jar decoration offers white-space entry through hand-finished presentation capabilities serving Grasse perfumers. Target pharmaceutical borosilicate expansion where ANSM compliance barriers sustain incumbent pricing umbrellas. Lead with just-in-time delivery contracts for mid-size Bordeaux estates seeking harvest-aligned bottling schedules. For Investors and Strategic Acquirers: Asymmetric upside sits with pharmaceutical-certified specialists possessing GMP production lines and extractables testing infrastructure. Long-term viability hinges on electrification retrofit completion and EU carbon border adjustment positioning. Watch furnace decarbonization timeline announcements as inflection indicator for export competitiveness into Northern European markets.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification-Ready Furnace Retrofit | EU Green Deal funding locks in carbon-adjusted export competitiveness for Lorraine operators. |
| Backward Integration into Cullet Processing | Closed-loop sourcing secures EPR compliance thresholds and insulates batch chemistry stability. |
| Pharmaceutical Borosilicate Capacity Expansion | ANSM inspection protocols sustain premium pricing tiers above commodity soda-lime margins. |
| Direct Procurement Relationship Cultivation | Furnace-direct contracts with Loire Valley craft breweries compress distributor intermediation. |
| Premium Decoration Capability Investment | Hand-finished jar formats capture artisanal perfumer revival in Grasse and Paris supply zones. |
Research Methodology
Coverage spans Champagne-Ardenne, Normandy, Lorraine, Bordeaux-Aquitaine, and Loire Valley, with primary inputs from each furnace cluster. The research combines interviews with plant managers, procurement leads at beverage multinationals, regulatory affairs specialists at ANSM, and distribution channel partners with secondary validation through ADEME environmental filings, EU ETS carbon market data, and French customs trade records. Bottom-up furnace capacity modeling triangulates against top-down beverage production volume estimates.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. Segmentation dimensions include product type, application sector, end-user procurement scale, and distribution channel structure. CAGRs derive from furnace utilization rate projections, EPR threshold escalation schedules, and export demand elasticity for champagne and cognac shipments. Industry-specific inputs incorporate natural gas price scenario modeling and lightweighting technology adoption curves.
Caveats apply where furnace electrification subsidy allocations or natural gas supply disruptions could materially shift the outlook. Forecasts reflect assumptions about EPR compliance timeline adherence and REACH raw material documentation stability. Material deviation in carbon border adjustment implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
United States Glass Packaging Market
Glass Packaging
Cosmetic and Perfume Glass Bottle Market
Glass Packaging
Tunisia Container Glass Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Austria Container Glass Market
Glass Packaging
Portugal Container Glass Market
Glass Packaging
Glass Bottle Molds Market
Glass Packaging
Glass Veil Market
Glass Packaging
Benelux Container Glass Market
Glass Packaging
North America Pharmaceutical Glass Packaging Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
Latin America Glass Packaging Market
Glass Packaging
Cosmetic and Perfume Glass Packaging Market
Glass Packaging
Glass Packaging Market
Glass Packaging
Guatemala Container Glass Market
Glass Packaging
Glass Liquor Bottles Market