
 Italy Bottled Water Market | 2026-2036
Italy Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Bottled Water Market Foresight
rPET is shifting from niche alternative to primary packaging substrate across mid-tier and premium lines, compressing virgin plastic economics. Ferrarelle S.p.A leverages volcanic-origin positioning to anchor its carbonated portfolio in Southern distribution networks. Nestlé S.P.A competes through controlled spring access across multiple Italian aquifers. Fonti di Vinadio differentiates via alpine altitude claims and regional Piedmont identity.
Italy bottled water comprises naturally sourced or treated water packaged for retail and foodservice consumption, typically held to mineral content thresholds and microbiological standards under national and EU frameworks. The product serves hydration, culinary pairing, and wellness positioning across channels from vending to fine dining. Still Water occupies the largest volume pool through everyday household replenishment cycles. Sparkling Water captures higher per-liter margins in restaurant and hotel settings. Functional Water segments show structural momentum as electrolyte and vitamin-infused variants penetrate fitness-oriented urban consumers.
Italy's Ministry of Health enforces mineral water classification and source protection protocols under Legislative Decree 105, while EU REACH and national CONAI packaging consortia shape material compliance obligations. These frameworks elevate operational costs for smaller bottlers but reinforce barrier-to-entry advantages for established spring-rights holders. Stakeholders must monitor pending revisions to extended producer responsibility thresholds and their implications for regional refill infrastructure investment.
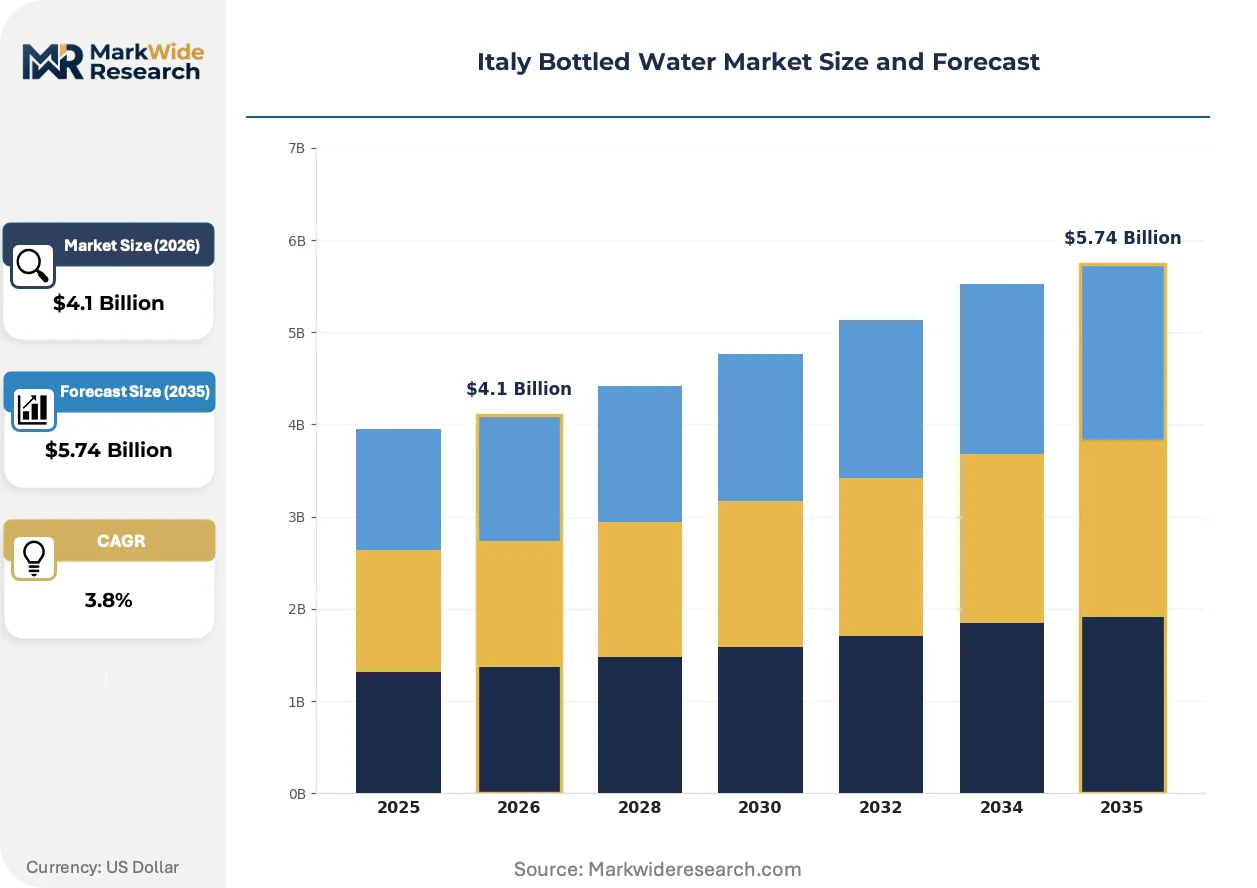
Market Dynamics
rPET conversion is compressing virgin plastic economics across Italy's mid-tier and premium bottling lines, forcing capital reallocation toward closed-loop recycling infrastructure and source-protected spring networks.
Growth Catalysts
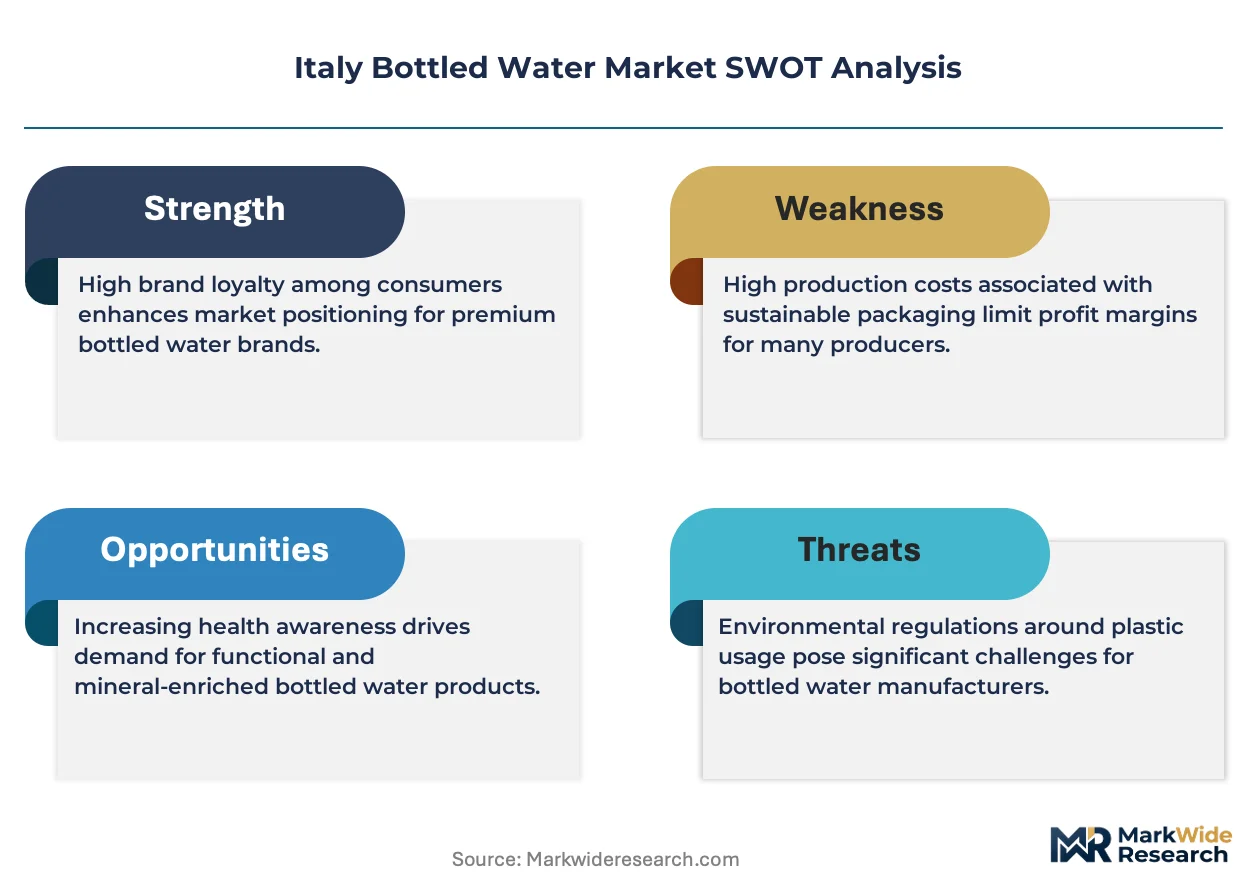
- Legislative Decree 105:Italy's mineral water classification and source protection protocols under this framework elevate compliance costs for new entrants while reinforcing incumbent spring-rights holders.
- Hospitality channel expansion:Premium mineral water placement in restaurants and hotels drives per-liter margin expansion through carbonated and sparkling variants.
- CONAI packaging consortium incentives:Extended producer responsibility thresholds under this national framework accelerate recycled PET adoption across bottling operations.
Market Restraints
- Alpine spring concentration:Northern Italy's established sourcing clusters create geographic supply vulnerability and transport cost asymmetries for Southern distribution.
- Virgin PET price volatility:Feedstock cost fluctuations for petroleum-derived resins compress margins for bottlers without backward integration into recycling streams.
- EU REACH compliance burden:Chemical substance registration and restriction protocols elevate operational complexity for smaller regional bottlers lacking dedicated regulatory functions.
Strategic Opportunities
- Southern Italy underpenetration:Volcanic-origin positioning and regional brand development in Campania and Sicily offer white-space expansion beyond Alpine-dominated supply networks.
- National Recovery and Resilience Plan funding:EU-backed financing instruments support recycled PET infrastructure investments and regional refill station deployment.
- Functional water convergence:Electrolyte and vitamin infusion technologies intersect with fitness-oriented urban consumption patterns in Milan and Rome metropolitan corridors.
Industry Challenges
- Spring-rights legal complexity:Multi-decade concession agreements and aquifer access litigation create protracted timeline uncertainty for capacity expansion.
- Microbiological certification bottlenecks:Italy's Ministry of Health approval protocols for new source activation impose extended validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Bottled Water Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $5.74 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sparkling Water, Still Water, Functional Water, Flavored Water Packaging Type: Glass Bottles, Plastic Bottles, Tetra Packs, Cans Distribution Channel: Supermarkets, Convenience Stores, Online Retail, HoReCa End User: Individuals, Restaurants, Hotels, Events |
| Companies Covered | Fonti di Vinadio, Acqua Lete, Nestlé S.P.A, Refresco Group B.V, Lauretana, Acqua Minerale San Benedetto, CoGeDi, Maniva, Ferrarelle S.p.A, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Bottled Water Market Shifts & Advancements
Packaging material substitution and regulatory compliance automation are restructuring competitive economics across Italy's bottled water value chain.
Recycled PET flake-to-bottle processing is consolidating as the dominant substrate technology across mid-tier and premium lines. Major bottling groups are converting virgin plastic lines to closed-loop rPET systems within compressed timelines. This substrate shift is consolidating cost advantages for operators with captive recycling infrastructure while squeezing margins for converters dependent on spot resin markets.
EU extended producer responsibility revisions are tightening material traceability requirements for plastic packaging. Italy's CONAI consortium is implementing granular reporting thresholds for post-consumer recycled content verification. Premium and functional water segments face disproportionate compliance investment given smaller batch volumes and higher SKU complexity.
Foodservice procurement is fragmenting toward direct-source relationships with single-origin spring bottlers. Regional restaurant groups in Piedmont and Lombardy are displacing multinational contracts with terroir-linked supply agreements. This channel disintermediation is most visible in Michelin-tier dining where provenance documentation commands menu placement premiums.
Italy Bottled Water Market Segmentation
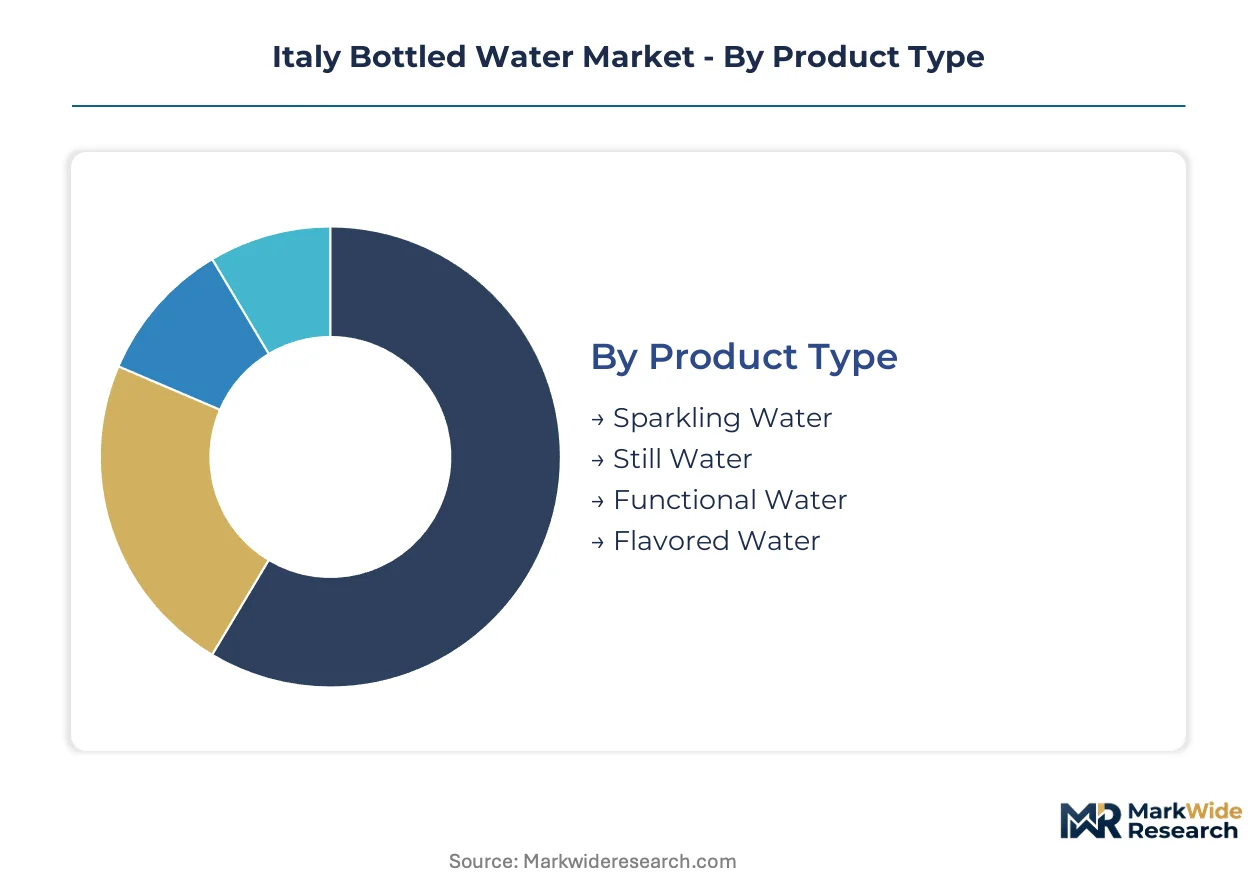
Segmentation in Italy's bottled water market reveals how regulatory frameworks, channel economics, and consumption occasions fragment demand across distinct value pools. Understanding these divisions exposes where premium positioning commands margin and where volume scale defends share.
Product Type:
Customization intensity varies sharply across this category, from standardized hydration commodities to engineered wellness formulations with proprietary mineral profiles.
- Still Water:Un carbonated natural or treated water with minimal dissolved solids serves household replenishment cycles across Northern Italian metropolitan corridors. Lombardy and Veneto households drive volume through multi-liter PET formats for daily consumption.
- Sparkling Water:Naturally carbonated or CO2-injected variants capture elevated per-liter margins in restaurant and hotel settings. Piedmont's volcanic aquifers supply distinctive mineral compositions that anchor terroir-based menu placement premiums.
- Functional Water:Electrolyte and vitamin-infused variants target fitness-oriented urban consumers in Milan and Rome.
- Flavored Water:Fruit-extract or essence-added products compete with soft drinks for younger demographic trial.
Most installed capacity flows through Still Water. Expansion is steepest in Functional Water.
Packaging Type:
Cost tier separation defines competitive positioning here, from premium glass formats commanding hospitality placement to economy plastic dominating household stock-up trips.
- Plastic Bottles:rPET and virgin PET containers deliver cost efficiency at scale for retail channels. Legislative Decree 105 compliance costs and CONAI extended producer responsibility thresholds accelerate conversion to recycled content across mid-tier bottling lines.
- Glass Bottles:Returnable and single-use formats secure premium placement in Michelin-tier dining and luxury hotel minibars. Tuscany and Emilia-Romagna restaurant groups specify regional spring sourcing with glass-only packaging for provenance documentation.
- Tetra Packs:Aseptic cartons target institutional and vending channel cost optimization.
- Cans:Aluminum formats penetrate convenience and on-the-go consumption occasions.
Plastic Bottles carry the heaviest volume throughput. Glass Bottles are climbing the fastest on value-per-liter metrics.
Distribution Channel:
Customer type and purchase occasion split this category between stock-up planning and immediate need fulfillment.
- Supermarkets:Hypermarket and supermarket chains dominate household replenishment with multi-pack promotions and private-label penetration. Northern Italy's dense retail infrastructure concentrates volume through Coop and Conad cooperative networks.
- HoReCa:Hotels, restaurants, and cafés drive carbonated and premium still water placement with direct-source contracting displacing multinational distribution. Piedmont and Lombardy regional groups favor single-origin spring relationships for menu differentiation.
- Convenience Stores:Impulse and immediate consumption purchases in urban and transit locations.
- Online Retail:Subscription and bulk delivery models penetrate affluent household segments.
Supermarkets process the majority of unit volume. HoReCa delivers the steepest margin expansion trajectory.
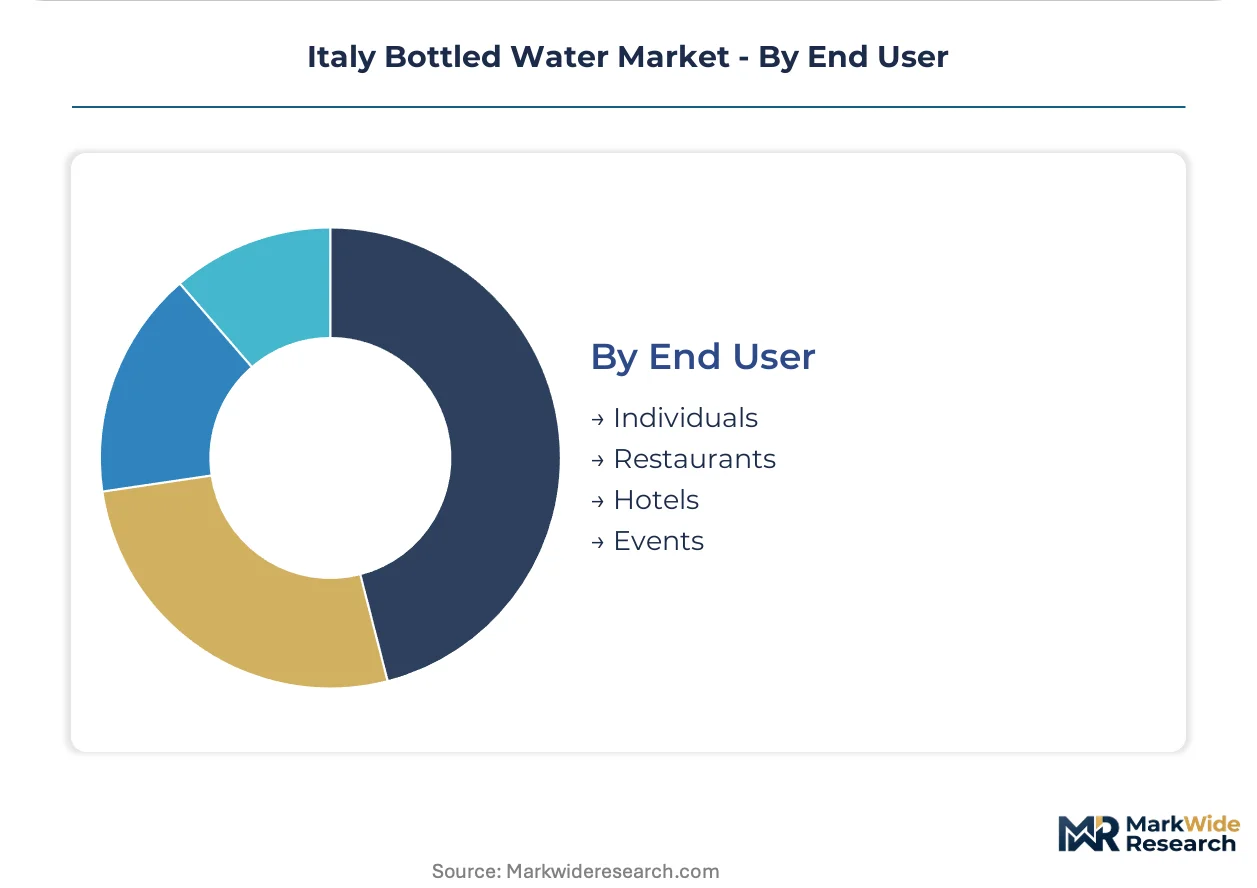
End User:
Application context separates standardized hydration from ceremonial consumption with distinct service and packaging requirements.
- Individuals:Personal consumption spans home hydration, fitness, and workplace replenishment with format flexibility from single-serve to family-size. Milan and Rome metropolitan fitness culture accelerates functional water adoption.
- Restaurants:Fine dining and casual establishments specify mineral content profiles for culinary pairing and table service presentation. Campania and Sicily volcanic-origin positioning challenges Alpine dominance in Southern expansion.
- Hotels:Minibar and banquet provisioning demands consistent quality tiering across property portfolios.
- Events:Temporary catering and festival servicing requires scalable logistics and branded customization.
Individual consumption absorbs the largest volume base. Restaurant placement offers the fastest value-per-liter growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Alpine spring sourcing clusters of Northern Italy concentrate bottling capacity and established supply networks. Southern regions present underpenetrated expansion corridors where volcanic-origin positioning challenges incumbent geographic dominance. Legislative frameworks and hospitality channel density fragment demand patterns across sub-national markets.
Lombardy
Milan metropolitan fitness culture and dense retail infrastructure drive functional water adoption and multi-liter household formats. Legislative Decree 105 enforcement by Italy's Ministry of Health maintains strict source protection protocols that favor established spring-rights holders. The Po Valley bottling corridor anchors volume production for national distribution networks.
Piedmont
Volcanic aquifers supply distinctive mineral compositions that command terroir-based menu placement premiums in Michelin-tier dining. CONAI packaging consortium incentives accelerate recycled PET conversion across mid-tier bottling operations. Turin and surrounding Alpine foothills concentrate premium sparkling water production for hospitality channel contracts.
Campania
Volcanic-origin water positioning leverages Vesuvian mineral profiles to differentiate Southern supply from Alpine-dominated competitors. National Recovery and Resilience Plan funding supports regional refill infrastructure and recycled PET adoption. Naples and surrounding provinces develop distribution networks that challenge Northern sourcing clusters in Southern markets.
Sicily
Tourism-dependent hospitality channels create seasonal demand spikes for premium mineral water in coastal resort markets. Extended producer responsibility thresholds under EU frameworks elevate compliance investment requirements for regional bottlers. Palermo and Catania metropolitan areas concentrate foodservice procurement relationships with direct-source spring contracts.
Veneto
Cooperative retail networks through Coop and Conad systems dominate household replenishment cycles with private-label penetration. EU REACH chemical substance protocols impose operational complexity on smaller regional bottlers lacking dedicated regulatory functions. The Veneto plain bottling belt serves as a logistics hub for Adriatic coastal distribution.
Italy Bottled Water Market Competitive Landscape
Global majors compete with regional champions across spring-rights access and hospitality channel relationships. The market structure tieres between multinational beverage conglomerates with controlled aquifer portfolios and family-owned bottlers leveraging single-origin provenance claims. Three archetypes dominate: Alpine-sourced premium specialists, volcanic-origin Southern challengers, and private-label contract manufacturers serving retail cooperatives. Competitive moves concentrate on direct-source restaurant contracts displacing distributor intermediaries, and backward integration into captive recycling infrastructure.
Within the premium sparkling tier, Ferrarelle S.p.A exemplifies volcanic-origin positioning that anchors carbonated portfolios in Southern distribution networks. Fonti di Vinadio and Lauretana represent Alpine-altitude specialists leveraging regional Piedmont identity for terroir-based menu placement. Among multinational operators, Nestlé S.P.A occupies a position defined by controlled spring access across multiple Italian aquifers. These three anchors illustrate how geographic origin claims and spring-rights portfolios structure competitive differentiation.
| Leading Market Players |
|---|
| Fonti di Vinadio |
| Acqua Lete |
| Nestlé S.P.A |
| Refresco Group B.V |
| Lauretana |
| Acqua Minerale San Benedetto |
| CoGeDi |
| Maniva |
| Ferrarelle S.p.A |
| Others |
Supply & Pricing Matrix
HoReCa procurement managers in Northern Italy concentrate purchasing power through direct-source contracting, locking in three-tier pricing structures that separate Michelin-tier glass formats from mid-tier rPET and economy virgin plastic lines.
Pricing Analysis
Input-cost pass-through from virgin PET resin volatility compresses margins for bottlers without captive recycling streams. Three-tier pricing structure across premium, standard, and economy levels differentiates by packaging substrate and mineral certification grade under Legislative Decree 105. Pricing pressure stems from CONAI extended producer responsibility thresholds accelerating rPET conversion investments. Economy-tier private-label buyers show highest price sensitivity, while hospitality procurement prioritizes provenance documentation over per-liter cost.
Supply Chain Analysis
Dual-sourcing requirements for Alpine spring water mandate qualification of multiple aquifer concessions to mitigate single-source vulnerability. Supply concentrates in Italy's Northern regions—Piedmont, Lombardy, Veneto—drawing from established Alpine clusters while Campania and Sicily develop volcanic-origin alternatives. Raw material dependencies center on rPET flake, virgin PET resin, and glass cullet supply. Distribution runs through cooperative retail networks in the North and fragmented foodservice procurement relationships across metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's bottled water market functions as a stable compounder where hospitality channel premiumization and regulatory-driven packaging conversion sustain predictable value expansion.
For Market Incumbents: Cement spring-rights portfolios through concession renewals in Piedmont and Lombardy aquifers before pending Legislative Decree 105 revisions tighten access protocols. Accelerate backward integration into captive rPET recycling infrastructure to offset virgin resin volatility and satisfy CONAI verification thresholds. Defend against volcanic-origin challengers by locking multi-year HoReCa contracts with provenance documentation requirements.
For New Entrants and Emerging Players: The mid-tier price-point gap between Alpine premium glass and economy private-label PET offers white-space positioning for regional terroir brands with rPET packaging. Target Campania and Sicily foodservice networks where volcanic mineral profiles challenge Northern sourcing dominance. Pursue direct-source restaurant relationships bypassing distributor markups as the primary go-to-market angle.
For Investors and Strategic Acquirers: Beverage conglomerates with multi-aquifer portfolios are the most active acquirers in this space, consolidating fragmented spring-rights holdings. Long-term viability rests on regulatory moats around source access and recycling infrastructure scale. Target acquisition archetypes are family-owned Alpine bottlers with unexploited hospitality channel relationships. Watch for inflection where extended producer responsibility thresholds trigger forced rPET conversion among laggard mid-tier operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Spring-Rights Portfolio Consolidation | Multi-decade aquifer concessions under Legislative Decree 105 lock out competitive entrants. |
| Captive rPET Infrastructure Buildout | Closed-loop recycling systems satisfy CONAI thresholds while insulating against virgin resin volatility. |
| Direct-Source HoReCa Contracting | Provenance-linked supply agreements displace distributor intermediaries in Michelin-tier dining. |
| Volcanic-Origin Brand Development | Vesuvian and Etna mineral profiles differentiate Southern challengers from Alpine incumbents. |
| Functional Water Line Extension | Electrolyte and vitamin infusion targets Milan and Rome fitness-oriented urban consumption. |
Research Methodology
Direct dialogue with bottling operations executives, spring-rights legal specialists, HoReCa procurement managers, and CONAI compliance officers grounded qualitative findings in operational reality. Secondary validation drew from Italy's Ministry of Health mineral water registries, EU REACH substance databases, CONAI packaging consortium reports, and cooperative retail network disclosures. Bottom-up volume modeling triangulated against top-down category spend estimates.
Bottom-up analysis built product-type and packaging-format trajectories across the projection horizon, while top-down approaches validated against national beverage consumption patterns and hospitality sector expenditure trends. Segmentation dimensions included product type, packaging substrate, distribution channel, and regional sourcing cluster. CAGRs derived from fitted growth curves applied to spring-capacity expansion timelines and rPET conversion adoption rates.
Caveats apply where Legislative Decree 105 revision timing, EU extended producer responsibility threshold adjustments, or Alpine aquifer yield variability could materially shift the outlook. Forecasts embed assumptions around hospitality channel recovery velocity and rPET flake supply elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Africa Dairy Based Beverages Market
Beverages
India Sports Drinks Market
Beverages
Ready to Drink Premixes Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Hot Cocoa Mix Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
Low Fat Drinks Market
Beverages
Global Electrolyte Drinks Market
Beverages
Alternative Waters (Plant Based Waters) Market
Beverages
Hydrogen Water Dispenser Market
Beverages
Asia-Pacific Energy Bar Market
Beverages
Packaged Cactus Water Market
Beverages
Europe Bottled Water Market
Beverages
Oat Based Beverages Market
Beverages
United States Smoothie Market
Beverages
Caffeine-Based Drinks Market