
 Automotive Silencer Market | 2026-2036
Automotive Silencer Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Silencer Market Intelligence
The performance gap between premium titanium silencers and standard aluminized steel units is broadening. Tenneco Inc. leverages its global manufacturing footprint to serve both OEM and aftermarket channels with a wide product portfolio. Faurecia specializes in advanced exhaust systems, integrating smart materials and active noise cancellation technologies for high-end passenger cars. Friedrich Boysen GmbH & Co. KG competes on engineering excellence for German and other European premium vehicle assemblers.
An automotive silencer is an acoustic device engineered to reduce the audible noise produced by a vehicle's internal combustion engine exhaust. It typically consists of a series of chambers and baffles, or perforated tubes wrapped in sound-absorbing materials like fiberglass, to dissipate sound energy. Stainless steel variants dominate the passenger car segment for their cost and durability, while commercial trucks require more robust aluminized steel designs. The aftermarket shows a preference for straight-through and chambered designs for performance enhancement.
Vehicle noise regulations enforced by bodies like the EPA in the United States and through EU type-approval standards directly mandate silencer performance levels. In China, GB standards for vehicle noise and emissions are becoming increasingly strict, influencing design specifications for both domestic and imported vehicles. The key decision for manufacturers is whether to invest in active noise control technologies or focus on optimizing passive material-based solutions.
Market Dynamics
The primary structural force shaping the automotive silencer market is the global convergence of stringent environmental regulations. Mandates like the EU's Euro 7 standards and China's evolving GB standards create a non-negotiable demand for more advanced acoustic and emission control technologies.
Growth Catalysts
- Regulatory Mandates:Increasingly strict vehicle noise regulations, including EU type-approval standards and EPA rules in the United States, directly compel original equipment manufacturers to invest in higher-performance silencer technologies to achieve compliance.
- Commercial Fleet Modernization:Demand from the commercial trucks segment is rising as logistics companies upgrade their fleets, requiring robust aluminized steel silencers that offer durability and meet modern noise and emissions requirements.
- Aftermarket Customization:A growing enthusiast culture in the automotive aftermarket creates consistent demand for performance-oriented silencers, including straight-through and chambered designs, that offer enhanced sound and power output.
Market Restraints
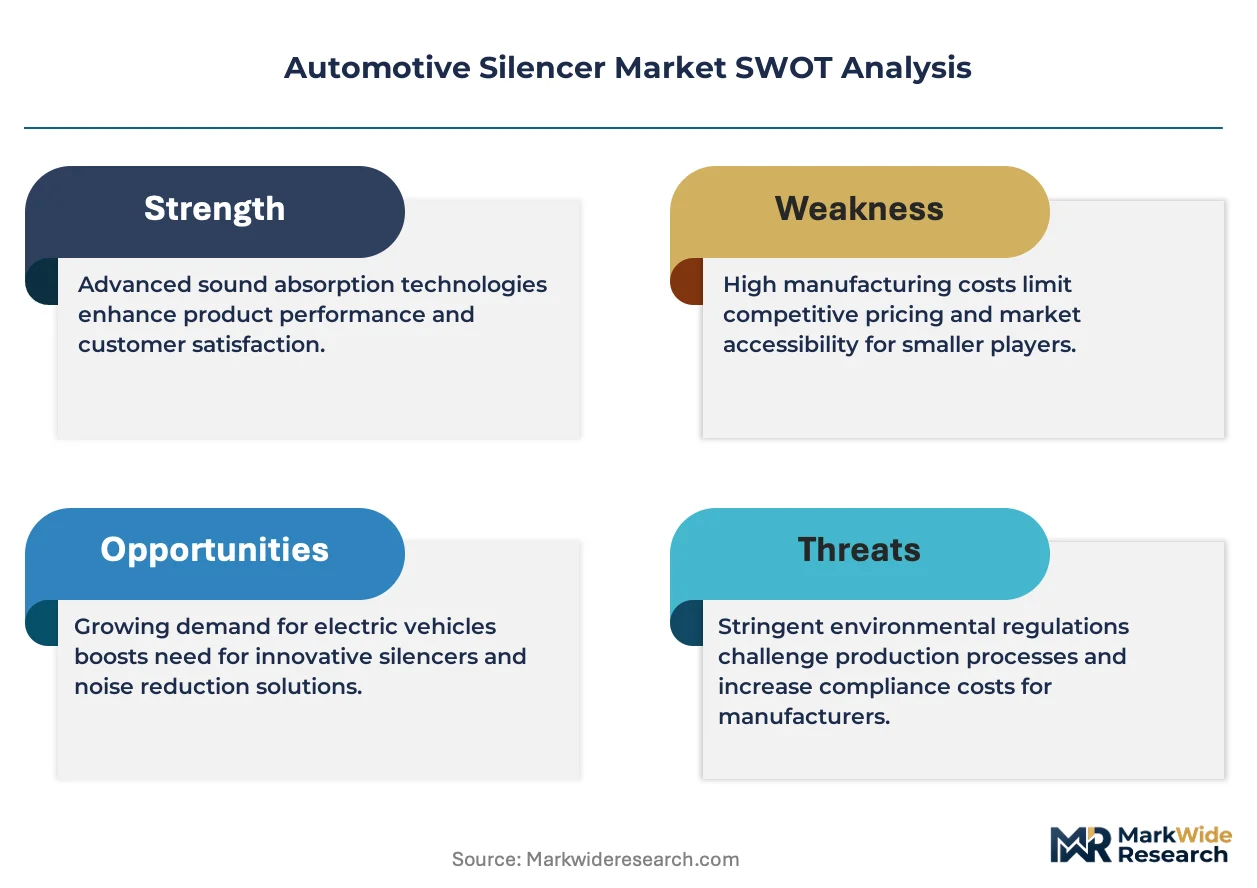
- Raw Material Price Volatility:Fluctuations in the cost of key inputs such as stainless steel, aluminized steel, and fiberglass insulation directly impact manufacturing profitability and can lead to pricing pressure across the supply chain.
- EV Transition Threat:The accelerating market shift toward battery electric vehicles (BEVs) represents a fundamental long-term restraint, as these vehicles do not have internal combustion engines and therefore do not require exhaust silencers.
- Design Trade-Offs:A persistent engineering constraint is the trade-off between maximizing noise reduction and minimizing exhaust back-pressure, which can negatively impact engine performance and fuel efficiency if not carefully balanced.
Strategic Opportunities
- Active Noise Control Systems:The development of integrated active noise cancellation technologies for exhaust systems opens a new, high-margin market segment for premium vehicles, offering electronically tunable sound profiles and superior noise suppression.
- Emerging Market Aftermarket:The expanding vehicle parc in developing economies, particularly in China and India, presents a significant opportunity for aftermarket silencer sales, catering to both replacement and performance upgrade demand.
- Advanced Material Integration:There is a clear opportunity in commercializing silencers made from lightweight alternatives like titanium alloys or advanced composites, targeting high-performance and luxury vehicle segments where weight reduction is critical.
Industry Challenges
- Global Compliance Complexity:Manufacturers face the operational challenge of designing and validating products that can meet a diverse and often conflicting set of regional noise and emissions standards, such as those from the KBA in Germany and the EPA in the US.
- System Integration:Integrating complex silencer units with other exhaust after-treatment components like catalytic converters and filters within the tightly packaged underbody of modern vehicles poses a significant engineering challenge.
- Manufacturing Process Upgrades:Shifting production to accommodate advanced designs like active systems or new materials such as titanium requires substantial capital investment in new tooling, automation, and specialized workforce skills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Silencer Market |
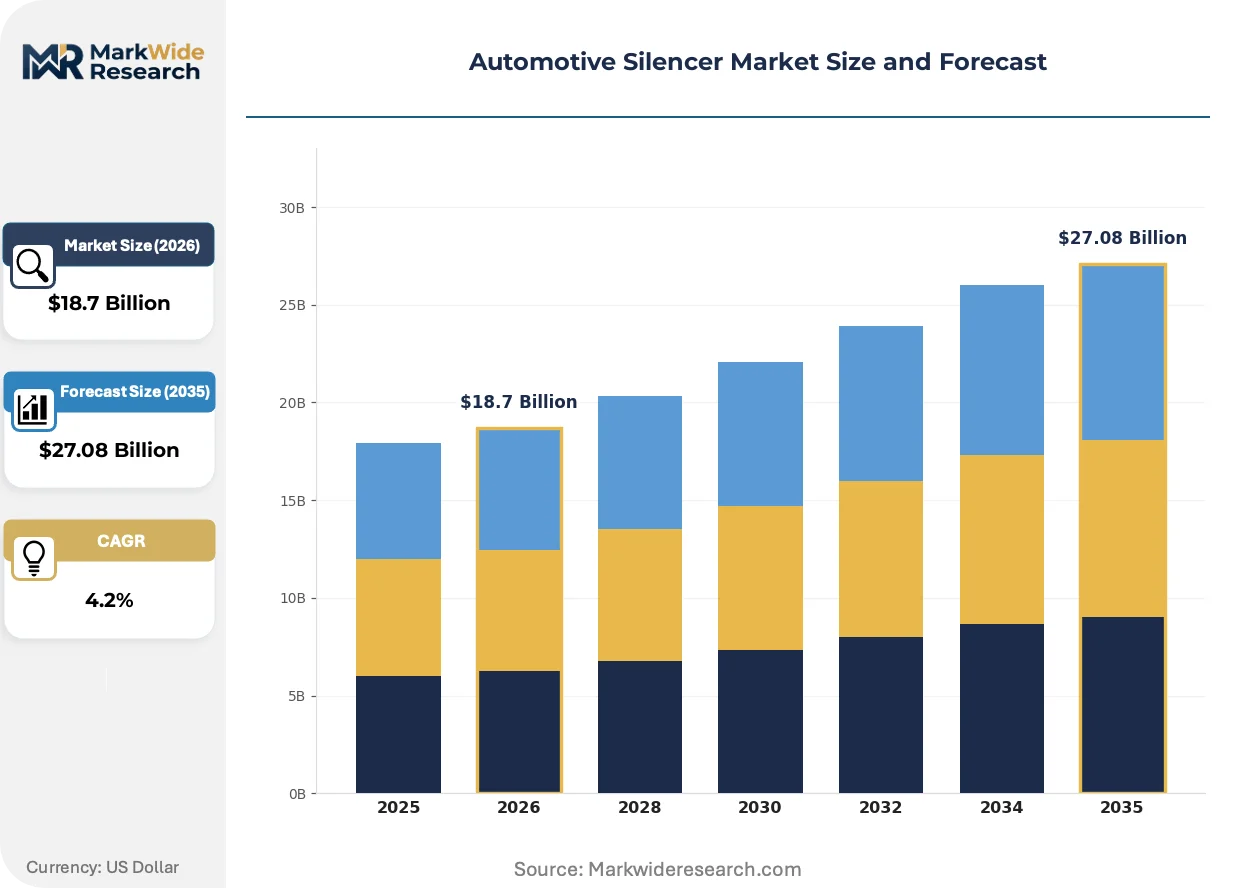
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axle-Back, Chambered, Turbo-Back, Straight-Through Material: Stainless Steel, Aluminized Steel, Titanium, Carbon Fiber Vehicle Type: Passenger Cars, Commercial Trucks, Two-Wheelers, Off-Road Vehicles End User: Aftermarket Retailers, Fleet Operators, Vehicle Assemblers, Performance Tuners |
| Companies Covered | Continental AG, Bosal International N.V., Tenneco Inc., Sejong Industrial Co. Ltd., Sango Co. Ltd., Faurecia, Futaba Industrial Co. Ltd., Friedrich Boysen GmbH & Co. KG, Eberspächer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Silencer Market Strategic Shifts & Innovations
The market's evolution is defined by a technological pivot from passive acoustic dampening toward intelligent, electronically controlled exhaust systems. This transition is a direct response to simultaneous pressures for stricter noise control and greater driver-centric performance customization.
Active noise cancellation (ANC) technology for exhausts uses microphones and speakers to generate sound waves that neutralize specific engine frequencies. Premium passenger car and performance SUV segments are adopting these systems to deliver unparalleled cabin quietness and offer customizable, software-defined exhaust notes. This evolution from static components to mechatronic systems is rewriting the fundamental value of the silencer within the vehicle architecture.
Forthcoming regulations, exemplified by the European Union's Euro 7 standards, are broadening the scope of noise control beyond just the exhaust pipe. These rules necessitate a holistic vehicle-level approach to noise, vibration, and harshness (NVH), elevating the importance of the silencer's contribution. Automakers selling into the EU are most affected, forcing investment in advanced passive designs or active systems to meet the new, more stringent pass-by noise limits.
A clear behavioral change is visible in the aftermarket, where consumers increasingly favor modular exhaust systems over traditional, single-unit silencer replacements. This trend disrupts the standard repair channel, creating an opening for suppliers offering kits with interchangeable resonators, mufflers, and tips for personalization. This demand for tunability is most pronounced within the North American and European performance vehicle enthusiast communities.
Automotive Silencer Market Segmentation
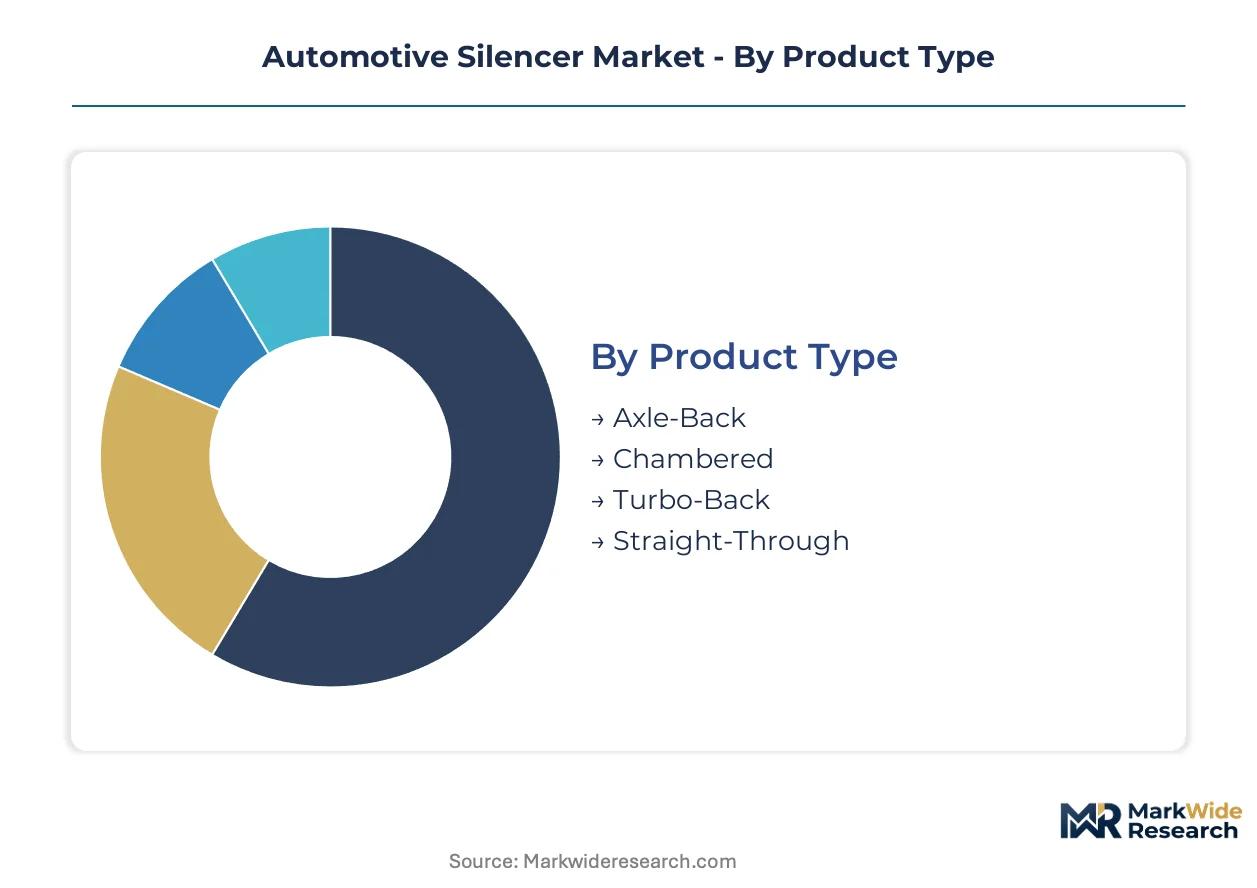
Understanding the varied segments within the automotive silencer market is crucial for identifying distinct demand drivers and technological requirements. This granular analysis illuminates the diverse needs across vehicle types, material preferences, and end-user applications, guiding strategic investments and product development efforts.
Product Type:
The product type segmentation highlights the spectrum from highly standardized replacement units to specialized performance-enhancing designs, catering to a wide range of vehicle owner priorities.
- Straight-Through:These silencers feature a direct path for exhaust gases, optimizing flow for maximum performance and a distinct, aggressive sound profile, particularly favored by performance vehicle enthusiasts in North America.
- Chambered:Utilizing internal chambers and baffles to reflect and cancel sound waves, chambered designs offer a balance of noise reduction and moderate exhaust flow, making them a popular choice for aftermarket upgrades seeking improved sound without excessive noise.
- Axle-Back:This type replaces only the components from the vehicle's rear axle to the exhaust tip, primarily altering sound and aesthetics without major performance changes.
- Turbo-Back:Designed for turbocharged vehicles, these systems replace the entire exhaust from the turbocharger back, providing significant gains in horsepower and torque by reducing back-pressure.
Most installed capacity flows through Chambered designs. Expansion is steepest in Straight-Through units.
Material:
Material choices for automotive silencers reflect a clear cost-performance hierarchy, influencing both durability and acoustic properties across different vehicle categories.
- Stainless Steel:Valued for its excellent corrosion resistance and durability, stainless steel is the dominant material for passenger car silencers, offering a good balance of cost and longevity. Demand for these units is strong in the European passenger car market.
- Aluminized Steel:This material provides a cost-effective solution with good heat resistance, making it suitable for high-volume commercial trucks where robustness and economic efficiency are paramount. Fleet modernization programs in China drive demand for these robust units.
- Titanium:Offering superior strength-to-weight ratio and corrosion resistance, titanium is reserved for high-performance and luxury vehicles where weight reduction is a critical design objective.
- Carbon Fiber:Primarily used in high-end aftermarket applications, carbon fiber provides extreme lightweighting and aesthetic appeal, often integrated into exhaust tips and outer casings.
The largest volume of units is produced using Stainless Steel. Innovation is concentrated in Titanium.
Vehicle Type:
Vehicle type segmentation delineates distinct engineering requirements, from high-volume passenger cars to heavy-duty commercial applications, each with specific regulatory and operational demands.
- Passenger Cars:This segment represents the largest volume, requiring silencers that balance noise reduction, fuel efficiency, and compact design, with a strong focus on meeting EU Euro 7 and US EPA noise standards.
- Commercial Trucks:These vehicles demand highly robust and durable silencers, typically made from aluminized steel, capable of withstanding continuous heavy-duty operation and meeting stringent noise and emission regulations for long-haul logistics.
- Two-Wheelers:Silencers for motorcycles and scooters focus on compact design and specific acoustic tuning, often with an emphasis on performance and aesthetic integration.
- Off-Road Vehicles:Silencers for off-road vehicles must endure harsh environmental conditions and extreme vibrations, prioritizing durability and robust construction over lightweighting.
Demand is primarily driven by Passenger Cars. The segment with the most specialized requirements is Off-Road Vehicles.
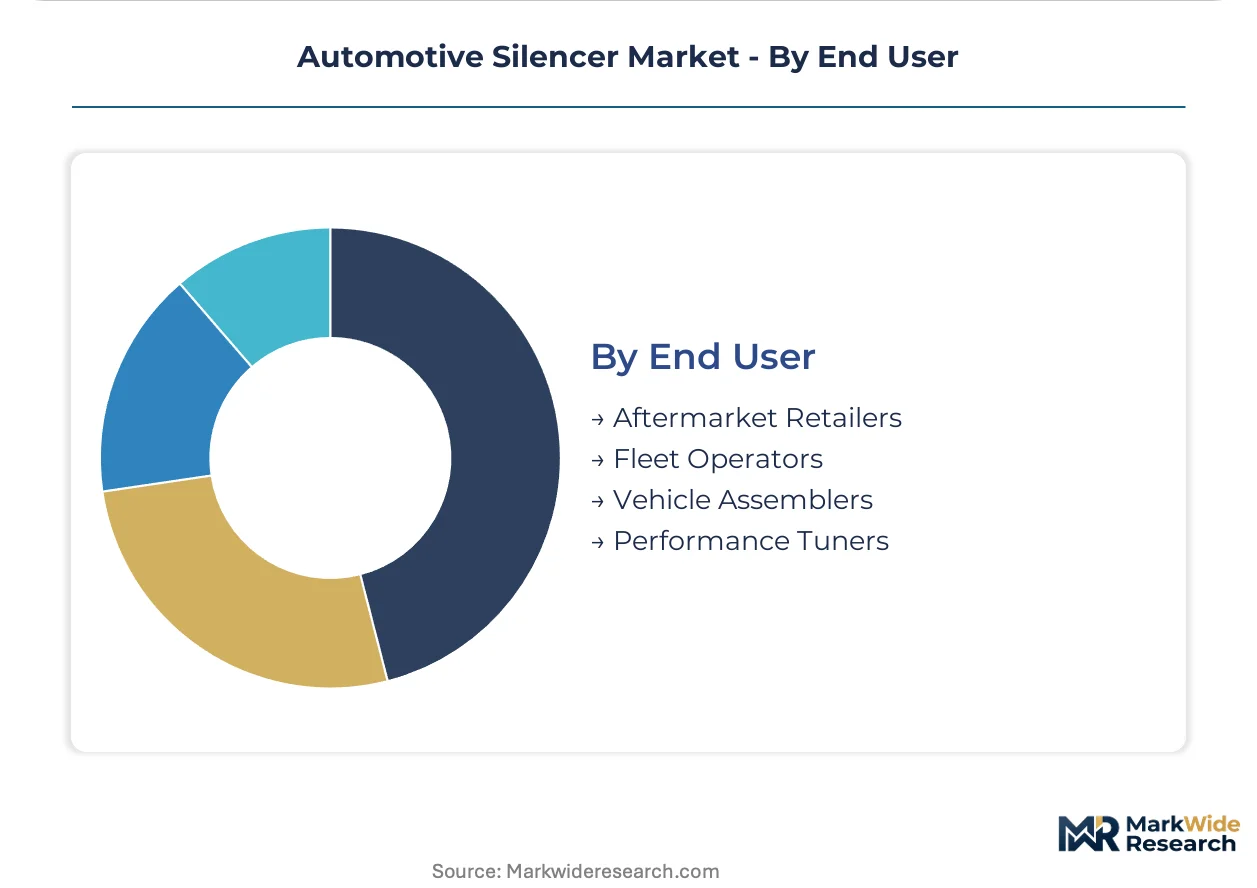
End User:
End-user categories reflect varied procurement patterns and purchasing motivations, from large-scale OEM supply to individual consumer upgrades, each shaping distribution channels and product specifications.
- Vehicle Assemblers:These are original equipment manufacturers (OEMs) that integrate silencers directly into new vehicle production lines, demanding high volumes, stringent quality control, and precise technical specifications.
- Aftermarket Retailers:This segment caters to replacement parts and performance upgrades for existing vehicles, offering a wide array of products to consumers and independent repair shops.
- Fleet Operators:Commercial fleet operators procure silencers for their truck and bus fleets, prioritizing durability, compliance with emissions standards, and cost-effectiveness for maintenance and replacement.
- Performance Tuners:These specialized businesses and enthusiasts seek high-performance silencers for vehicle modification, focusing on sound enhancement, power gains, and unique aesthetic designs.
The most significant revenue streams originate from Vehicle Assemblers. Emerging demand patterns are evident among Performance Tuners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled automotive engineering talent concentrations across key global manufacturing hubs are driving localized innovation in silencer design and production. These centers of excellence develop advanced acoustic solutions tailored to diverse market demands. Regulatory pressures and fleet modernization initiatives further shape regional market dynamics.
China
China's vast domestic vehicle parc and ongoing commercial fleet modernization programs create substantial demand for robust silencer solutions. The country's evolving GB standards for vehicle noise and emissions directly influence design specifications. Automotive manufacturing clusters in the Yangtze River Delta region concentrate silencer production to serve this immense market.
Germany
German vehicle assemblers in the premium segment prioritize engineering excellence in exhaust system components. The EU's Euro 7 standards and KBA type-approval processes compel investment in advanced acoustic technologies. Stuttgart-Baden-Württemberg, a hub for automotive innovation, drives development of sophisticated silencer designs for European vehicles.
United States
United States demand for automotive silencers stems from robust commercial truck sales and a thriving aftermarket customization culture. EPA noise standards mandate performance levels for new vehicles. Detroit's automotive manufacturing belt and independent aftermarket specialists drive innovation in straight-through and chambered silencer units.
Japan
Japanese passenger car manufacturers require highly efficient and compact silencer designs to meet stringent domestic market demands. METI regulations and JIS standards guide integration of advanced materials and acoustic technologies. Automotive production centers around Toyota City are developing lightweight silencers for enhanced fuel efficiency and reduced emissions.
India
India's expanding vehicle parc, particularly in the two-wheeler and passenger car segments, fuels demand for cost-effective and durable silencers. Bharat Stage emission norms increasingly influence exhaust system design and noise reduction. Automotive manufacturing hubs in Chennai and Pune are rapidly expanding production capabilities for both OEM and aftermarket silencer units.
Automotive Silencer Market Key Industry Players
Top-tier vendors anchor the global automotive silencer market, while a diverse array of specialized manufacturers and regional players contribute to a tiered competitive landscape. The market exhibits moderate consolidation at the OEM supply level, with significant fragmentation in the aftermarket segment. Large integrated suppliers, specialist performance component providers, and regional aftermarket distributors represent key strategic archetypes. Strategic partnerships with OEMs and geographic expansion into emerging markets are dominant competitive moves.
Specialists in advanced exhaust systems include Faurecia, which represents a key player integrating smart materials and active noise cancellation technologies. Tenneco Inc. exemplifies a global manufacturing footprint, serving both OEM and aftermarket channels with a wide product portfolio across various vehicle types. Friedrich Boysen GmbH & Co. KG occupies a strong position for engineering excellence, particularly for German and other European premium vehicle assemblers. These companies anchor different segments of the market, from high-end passenger cars to broad OEM and aftermarket supply, reflecting varied strategic focuses within the industry.
| Leading Market Players |
|---|
| Continental AG |
| Bosal International N.V. |
| Tenneco Inc. |
| Sejong Industrial Co. Ltd. |
| Sango Co. Ltd. |
| Faurecia |
| Futaba Industrial Co. Ltd. |
| Friedrich Boysen GmbH & Co. KG |
| Eberspächer Group |
| Others |
Cost & Logistics Intelligence
Skilled automotive engineering talent concentrations in Germany and Japan influence premium silencer pricing. Labor-cost differentials across global manufacturing hubs, particularly China, create distinct pricing-tier spreads for various product types.
Pricing Analysis
Bundled OEM agreements often dictate contract-based long-term offtake pricing for silencers. Price differentiation stratifies across premium, standard, and economy tiers, driven by material quality (titanium versus aluminized steel) and stringent regulatory compliance (EU Euro 7 standards). Pricing softness reflects the accelerating market shift toward battery electric vehicles, eroding long-term demand. Commercial fleet operators exhibit high price sensitivity, while performance tuners prioritize unique aesthetic designs and sound enhancement.
Supply Chain Analysis
Dual-sourcing requirements from major vehicle assemblers characterize the automotive silencer supply chain. Production concentrates in China, serving its vast domestic market, while Germany and Japan also contribute specialized components. The supply chain draws from key inputs such as stainless steel, aluminized steel, and fiberglass insulation. Raw material price volatility presents a structural risk. Distribution runs through direct OEM supply channels and a fragmented network of aftermarket retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive silencer market presents a compelling margin-expansion story, driven by the increasing adoption of premium active noise control systems in high-end passenger vehicles. This shift allows for higher average selling prices and improved profitability per unit.
For Market Incumbents:Deepen investment in active noise control (ANC) technologies to secure premium vehicle segment contracts. Expand advanced material production capabilities for titanium silencers to counter the long-term EV transition threat. Leverage global manufacturing footprint to optimize cost structures for high-volume aluminized steel units. Pursue strategic partnerships with software providers for integrated exhaust sound management.
For New Entrants and Emerging Players:Launch via direct-to-consumer online channels, targeting the burgeoning aftermarket customization segment. Focus on modular exhaust systems offering interchangeable components for personalization, particularly in North America and Europe. Develop advanced composite material solutions for niche high-performance applications where lightweighting is critical. Exploit underpenetration in performance-oriented two-wheeler segments with unique acoustic profiles.
For Investors and Strategic Acquirers:Tier 1 automotive suppliers are the most active acquirers in this space, seeking to bolster their advanced acoustics portfolios. The market demonstrates long-term viability through its evolution into intelligent, electronically controlled exhaust systems across the next decade. Target specialist firms with proprietary active noise cancellation intellectual property or unique titanium manufacturing capabilities. The signal to watch is expanding OEM mandates for active noise control as standard vehicle equipment.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Active Noise Control (ANC) R&D | Secures future high-margin contracts for premium passenger cars. |
| Expand Titanium Production Capacity | Addresses demand for lightweight solutions in luxury and performance vehicle segments. |
| Develop Modular Aftermarket Kits | Captures growth from performance vehicle enthusiast communities in North America. |
| Strengthen OEM Partnerships for Euro 7 Compliance | Ensures market access and high-volume sales in the European passenger car market. |
| Optimize Aluminized Steel Supply Chain in China | Supports commercial truck fleet modernization programs and domestic vehicle parc growth. |
Research Approach
Direct dialogue with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and commercial fleet operators informed the primary research. This qualitative grounding was validated against extensive secondary data from vehicle production databases, IHS Markit registration data, and national environmental agency reports. Bottom-up market sizing and top-down validation ensured robust data triangulation.
A bottom-up analytical framework, complemented by top-down validation, projected market evolution across the analysis window. Segmentation dimensions modeled included product type, material, vehicle type, end user, and regional regulatory compliance. Compound annual growth rates were derived from historical growth trends and projected technological shifts. Key forecast inputs included global vehicle production forecasts and anticipated regulatory mandate timelines.
Several conditions sit outside the modeled scope, including unforeseen macroeconomic shocks and geopolitical events. Forecasts reflect assumptions regarding technological adoption rates and regulatory enforcement. Deviation in global economic downturns or radical shifts in raw material supply would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Composite Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Automotive Part Cleaners and Degreasers Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
Automotive Transaxle Market
Automotive Components
Automotive Stainless Steel Tubes Market
Automotive Components
Canada Automotive Glass Fiber Composites Market
Automotive Components
North America Automotive Bearing Market
Automotive Components
Europe Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Automotive Glass Fiber Composites Market
Automotive Components
Europe Automotive AHSS Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Asia-Pacific Automotive Composites Market